
 Vinyl Acetate Monomer (VAM) Market | 2026-2036
Vinyl Acetate Monomer (VAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Monomer (VAM) Market Analysis
Aftermarket service revenue for VAM purification and logistics is narrowing as integrated producers internalize these functions. Celanese Corporation leverages its acetyls chain integration to control feedstock costs across North American and European production hubs. Wacker Chemie AG anchors its competitive position through specialized polymer-grade output serving European adhesives manufacturers. Mitsubishi Chemical Corporation competes via deep operational experience in acetylene-based VAM synthesis, sustaining supply reliability for Asian coating formulators.
Vinyl acetate monomer is an organic compound with the formula CH3COOCH=CH2, typically produced through ethylene oxidation or acetylene addition processes with a purity threshold exceeding 99.5% for polymer-grade specifications; it serves as the foundational building block for polyvinyl acetate, ethylene-vinyl acetate copolymers, and polyvinyl alcohol resins used across construction, packaging, and textile bonding applications. Polymer-grade VAM occupies the dominant value share due to its indispensability in high-performance adhesive and coating formulations, while emulsion-grade output is experiencing accelerated demand from water-based paint manufacturers seeking low-VOC compliance pathways. Food-grade VAM maintains a narrow but protected margin pool tied to regulated packaging laminate applications where residual monomer thresholds are stringently controlled.
EPA oversight of ethylene oxide emissions and REACH registration requirements for acetic acid derivatives are elevating capital intensity for new VAM capacity, compelling producers to invest in closed-loop recovery systems and catalyst efficiency upgrades. China's MIIT enforces GB standards on industrial chemical purity that directly shape export eligibility for regional manufacturers supplying Asian coating and adhesive markets. Stakeholders must monitor how carbon border adjustment mechanisms and evolving biobased feedstock certifications will reshape feedstock sourcing decisions and regional production economics.
Market Dynamics
Polymer-grade specification tightening and EPA ethylene oxide emission caps are compressing viable production capacity into integrated acetyls chains with closed-loop recovery infrastructure.
Growth Catalysts
- Packaging adhesive demand:E-commerce fulfillment expansion drives hot-melt and pressure-sensitive adhesive consumption requiring high-purity ethylene-vinyl acetate copolymers.
- REACH low-VOC mandates:European coating formulators accelerate water-based emulsion transitions, elevating emulsion-grade VAM offtake for architectural paint systems.
- Acetylene-based synthesis:Asian producers with carbide feedstock access sustain cost-competitive supply for textile bonding and polyvinyl alcohol resin markets.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to ethylene oxidation route economics, squeezing margin predictability for non-integrated operators.
- Supply concentration in China:Domestic capacity expansions by Sinopec Group and regional chemical conglomerates create export surge risk into European and North American markets.
- Acetic acid derivative registration:REACH authorization timelines for acetic acid pathway intermediates extend new entrant qualification periods beyond 18 months.
Strategic Opportunities
- Biobased feedstock certification:EU Green Deal carbon border adjustment mechanisms reward bio-ethylene sourced VAM with preferential market access terms.
- Food-grade laminate specification:Residual monomer threshold compliance below 5 ppm opens protected margin pools in regulated dairy and meat packaging applications.
- Specialty polymer-grade premiumization:Ultra-high purity specifications for optical-grade polyvinyl alcohol enable pricing separation from commodity adhesive grades.
Industry Challenges
- Catalyst efficiency expertise:Palladium-gold catalyst formulation and regeneration know-how concentrates among legacy acetyls operators, constraining new facility ramp rates.
- Emission control capex intensity:Closed-loop ethylene oxide recovery systems and thermal oxidizer installations absorb 15-20% of greenfield project capital allocation.
- Cross-border standard harmonization:Divergent GB purity standards, ASTM specifications, and EN norms complicate multi-territory product registration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Monomer (VAM) Market |
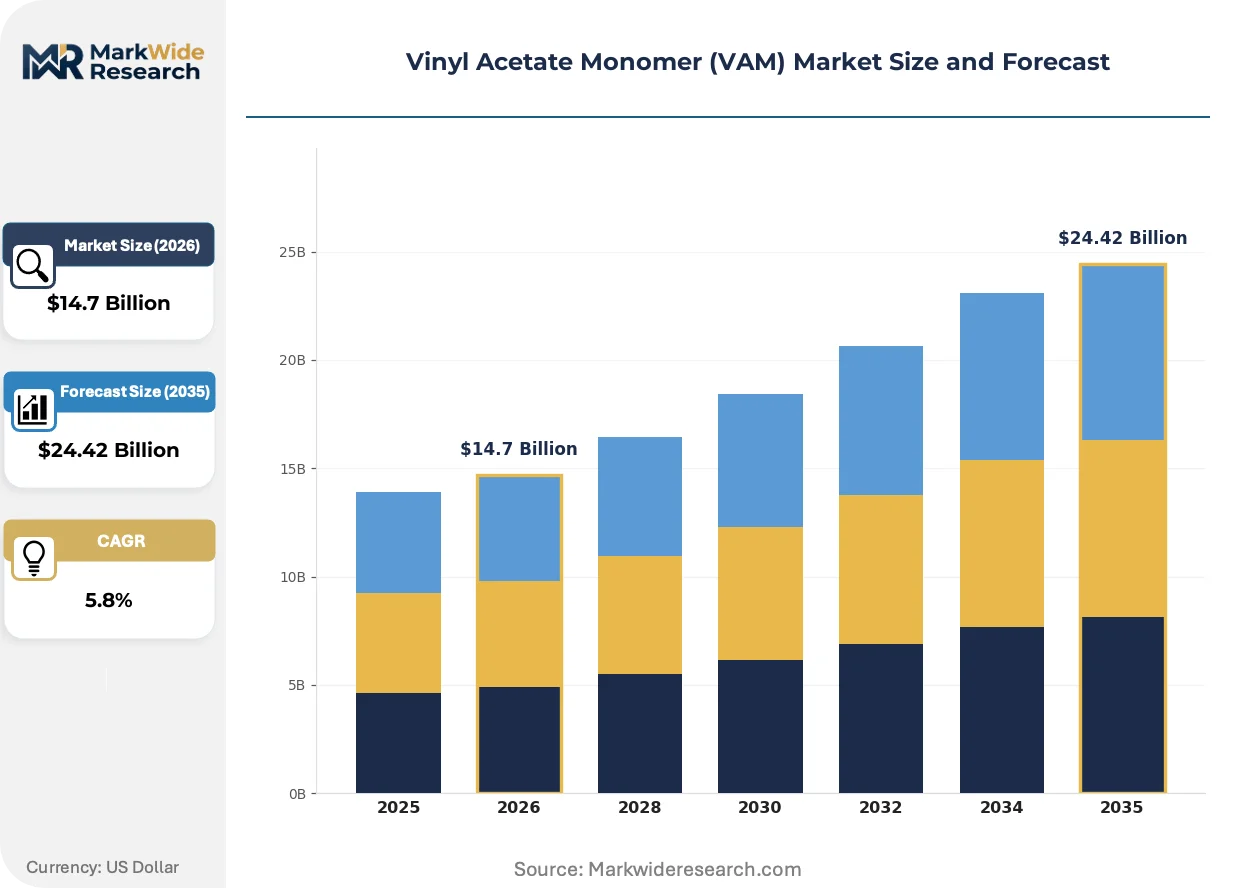
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Polymer Grade, Food Grade, Industrial Grade End Use Industry: Paints & Coatings, Adhesives, Textiles, Packaging Application: Flooring, Wall Coverings, Sealants, Inks Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Mitsubishi Chemical Corporation, Wacker Chemie AG, Celanese Corporation, Kuraray Co., Ltd., Sinopec Group, LyondellBasell Industries, Arkema, Exxon Mobil Corporation, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Monomer (VAM) Market Emerging Trajectories
Process intensification and emission control technology are compressing the viable producer set toward integrated chemical parks with captive utility and feedstock infrastructure.
Fixed-bed ethylene oxidation catalyst technology is collapsing the cost gap between ethylene-based and acetylene-based VAM production routes. European adhesives manufacturers now source from both pathways based on spot ethylene pricing rather than historical route loyalty. This technology convergence is eroding the traditional geographic specialization between carbide-rich Asian supply and ethylene-dominant Western capacity.
EPA ethylene oxide emission standards under the Clean Air Act are compelling existing facilities to install secondary catalytic oxidation and carbon adsorption recovery trains. Capital deployment for compliance now precedes any expansion authorization, freezing marginal capacity additions outside integrated chemical complexes. Texas and Louisiana Gulf Coast producers with existing acetyls integration capture regulatory timing advantages over standalone operators.
Specification-driven procurement now dominates coating formulator buying behavior, with residual monomer certification and batch traceability displacing volume-based contracting. Large European paint manufacturers audit supplier quality systems before awarding annual supply agreements. This shift concentrates offtake among producers with documented ISO 9001 and Responsible Care certification histories.
Vinyl Acetate Monomer (VAM) Market Segmentation
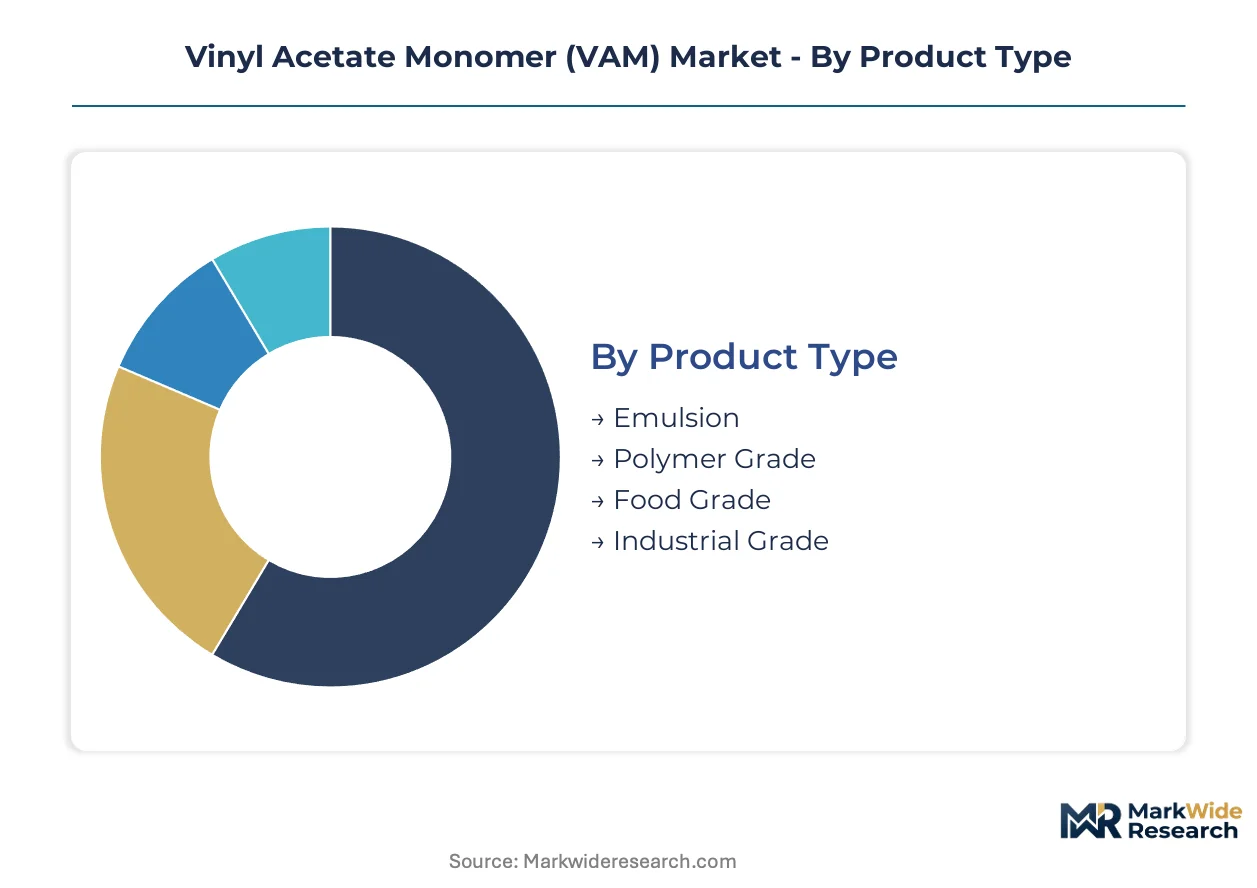
VAM segmentation reflects divergent purity requirements and regulatory exposure across adhesive, coating, and packaging applications. Specification thresholds determine pricing power and customer switching costs in this acetyls derivative market.
Product Type:
Mature polymer specifications coexist with emerging food-grade certification demands as regulatory scrutiny intensifies.
- Polymer Grade:Purity specifications exceeding 99.5% enable high-performance ethylene-vinyl acetate copolymer production for hot-melt adhesives. Demand concentrates in China where Sinopec Group and domestic construction chemical formulators are expanding EVA capacity for solar encapsulant films.
- Emulsion:Water-dispersible formulations serve architectural coating manufacturers seeking REACH low-VOC compliance pathways. European paint formulators accelerate procurement of emulsion-grade VAM as EPA ethylene oxide emission caps tighten supply from Texas and Louisiana Gulf Coast producers.
- Food Grade:Residual monomer thresholds below 5 ppm serve regulated dairy and meat packaging laminate applications.
- Industrial Grade:Standard purity specifications support general-purpose polyvinyl acetate adhesive manufacturing.
Polymer grade retains volume leadership; food grade holds the steepest expansion curve.
End Use Industry:
Application cost tiers separate specification-intensive coating formulators from volume-driven textile processors.
- Adhesives:Pressure-sensitive and hot-melt formulations consume the highest-purity polymer-grade output for bonding applications in automotive interior assembly and electronics manufacturing. Procurement concentrates among European and North American packaging converters responding to e-commerce fulfillment expansion.
- Paints & Coatings:Water-based emulsion systems drive architectural paint demand as REACH mandates displace solvent-borne alternatives. Formulator buying behavior now prioritizes residual monomer certification and batch traceability over volume-based contracting.
- Packaging:Flexible laminate structures for food contact applications require food-grade VAM with documented ISO 9001 compliance histories.
- Textiles:Polyvinyl alcohol resin production for warp sizing and textile bonding sustains acetylene-based VAM demand across Asian carbide-fed supply chains.
Adhesives command premium pricing tiers; packaging is gaining share fastest.
Application:
Volume concentration in flooring and wall coverings contrasts with emerging specification complexity in sealant formulations.
- Flooring:Vinyl acetate-ethylene copolymer emulsions bind luxury vinyl tile and resilient sheet flooring substrates. Demand clusters in North American residential renovation markets and Chinese commercial construction.
- Sealants:High-performance caulking and construction sealant formulations require controlled molecular weight distribution. European building product manufacturers source from integrated acetyls chains with closed-loop recovery infrastructure to satisfy ECHA registration requirements.
- Wall Coverings:Pre-pasted wallpaper adhesives utilize polyvinyl acetate homopolymer emulsions.
- Inks:Flexographic and gravure printing ink binders employ specialized VAM copolymers for substrate adhesion.
Flooring retains volume leadership; sealants hold the steepest expansion curve.
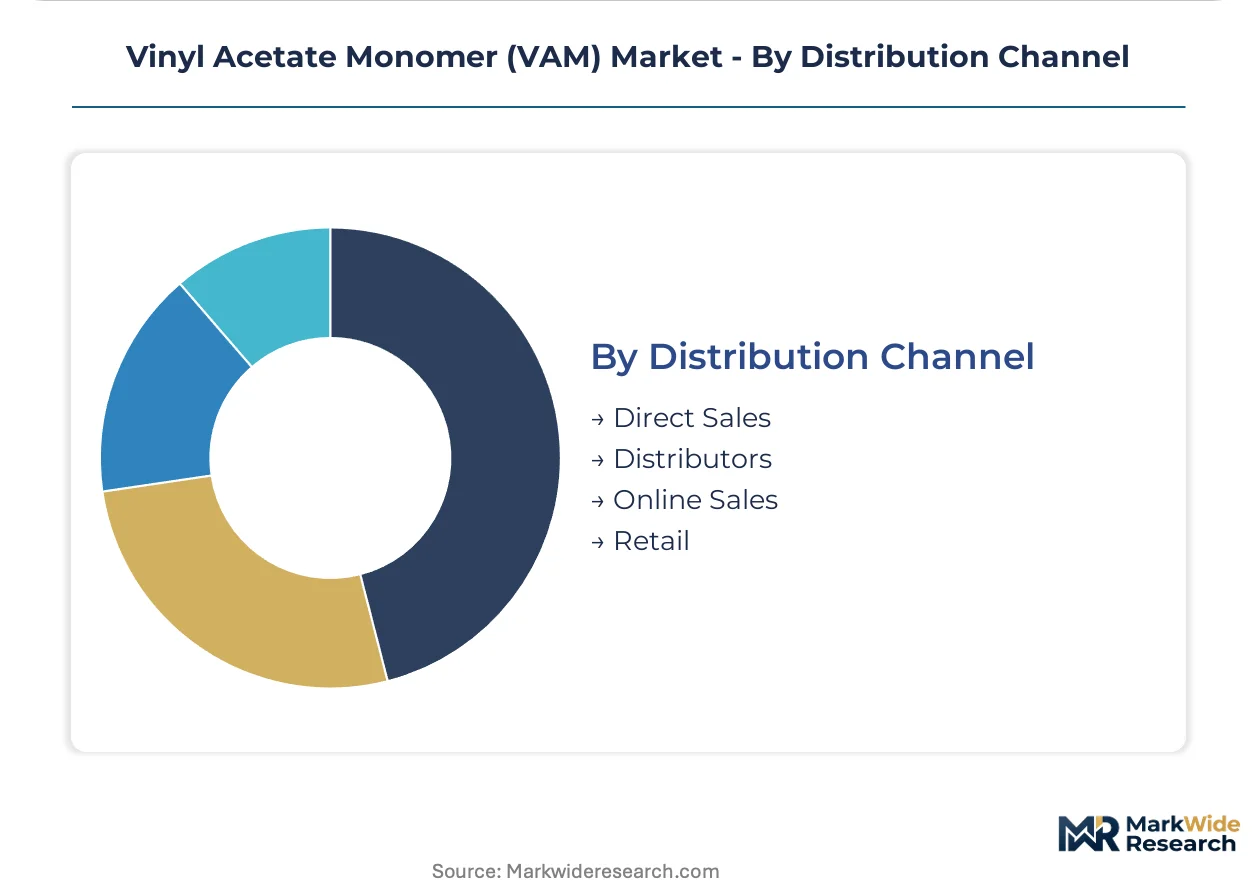
Distribution Channel:
Customer type separates bulk procurement by integrated formulators from fragmented retail and online purchasing patterns.
- Direct Sales:Annual supply agreements dominate polymer-grade procurement as large coating and adhesive manufacturers audit supplier quality systems before awarding contracts. Celanese Corporation and Wacker Chemie AG leverage direct relationships to secure specification-driven offtake.
- Distributors:Regional chemical distributors serve mid-sized formulators lacking tank-car receiving infrastructure. Inventory positioning in Rotterdam, Houston, and Singapore hubs enables just-in-time delivery for European, North American, and Asian coating plants.
- Online Sales:Digital procurement platforms facilitate spot purchasing for small-batch emulsion-grade requirements.
- Retail:Packaged quantities reach DIY adhesive and paint consumers through construction supply stores.
Direct sales retains volume leadership; online sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb volume with minimal price elasticity while European coating formulators demand certified low-emission grades at substantial premiums. This demand-elasticity contrast shapes regional procurement patterns and investment allocation across production hubs.
China
Sinopec Group and domestic construction chemical formulators are expanding ethylene-vinyl acetate copolymer capacity for solar encapsulant films and packaging adhesives. MIIT enforces GB standards on industrial chemical purity that directly shape export eligibility for regional manufacturers supplying Asian coating markets. Yangtze River Delta chemical parks host integrated acetyls chains with captive feedstock infrastructure serving textile bonding and polyvinyl alcohol resin production.
United States
Texas and Louisiana Gulf Coast producers with existing acetyls integration capture regulatory timing advantages over standalone operators. EPA ethylene oxide emission standards under the Clean Air Act compel secondary catalytic oxidation and carbon adsorption recovery train installations. Houston chemical corridor facilities serve North American packaging converters responding to e-commerce fulfillment expansion with hot-melt adhesive formulations.
Germany
European adhesives manufacturers source from both ethylene-based and acetylene-based pathways based on spot ethylene pricing rather than historical route loyalty. ECHA registration requirements for acetic acid pathway intermediates extend new entrant qualification periods beyond eighteen months. Ludwigshafen and Leverkusen chemical clusters anchor integrated production serving REACH-compliant coating formulators with documented ISO 9001 certification histories.
Japan
Mitsubishi Chemical Corporation sustains supply reliability for Asian coating formulators through deep operational experience in acetylene-based VAM synthesis. METI industrial chemical standards coordinate with international purity specifications to maintain export competitiveness. Chubu and Kansai industrial corridors concentrate carbide-fed production capacity serving textile bonding and polyvinyl alcohol resin markets.
Saudi Arabia
Petrochemical complexes leverage ethane feedstock access to sustain cost-competitive ethylene oxidation route economics. The country's national environmental regulator imposes emission control frameworks aligned with Gulf Cooperation Council chemical industry standards. Eastern Province industrial cities host integrated production facilities targeting export markets in India and Southeast Asia with polymer-grade specifications.
Vinyl Acetate Monomer (VAM) Market Vendor Landscape
Integrated acetyls chains and specialized polymer-grade producers split the market along specification intensity and feedstock control vectors. The producer set compresses toward chemical parks with captive utility infrastructure as emission control capex requirements freeze marginal capacity additions. Two strategic archetypes dominate: backward-integrated petrochemical conglomerates with ethylene oxidation assets, and carbide-based specialists serving acetylene-route demand pockets. Competitive moves concentrate on catalyst efficiency licensing and closed-loop recovery system partnerships rather than greenfield expansion.
Within the integrated acetyls tier, Celanese Corporation anchors North American and European production positioning through acetyls chain control. Wacker Chemie AG exemplifies the specialized polymer-grade archetype serving European adhesives manufacturers with specification-driven output. Mitsubishi Chemical Corporation represents acetylene-based synthesis expertise sustaining Asian supply reliability. These three occupy positions that reflect the market's bifurcation between feedstock-integrated scale and specification-premium specialization.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Wacker Chemie AG |
| Celanese Corporation |
| Kuraray Co., Ltd. |
| Sinopec Group |
| LyondellBasell Industries |
| Arkema |
| Exxon Mobil Corporation |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
China's ethylene-vinyl acetate capacity overhang compresses global spot pricing while tightening polymer-grade specifications in Europe and North America sustain premium tiers. Suppliers with integrated acetyls chains leverage captive feedstock to defend margins against carbide-route Asian exports.
Pricing Analysis
Aftermarket catalyst regeneration contracts and technical service agreements generate recurring revenue that exceeds initial product margins for legacy producers. Three-tier pricing structure across polymer-grade, emulsion-grade, and food-grade certification levels separates specification-intensive buyers from volume-driven processors. Cost compression in commodity polymer-grade tiers intensifies as Sinopec Group and domestic Chinese conglomerates expand export-oriented capacity. Small-batch coating formulators exhibit highest price sensitivity, while food-grade laminate manufacturers accept substantial premiums for residual monomer documentation below 5 ppm thresholds.
Supply Chain Analysis
Extended payment terms from integrated European coating manufacturers strain working capital for regional distributors serving mid-sized formulators. Feedstock sourcing concentrates in China, Saudi Arabia, and the United States Gulf Coast, with ethane-based Saudi supply and naphtha-cracker Asian output competing for Asian derivative demand. VAM production draws from acetic acid and ethylene or acetylene feedstocks, with palladium-gold catalyst systems constituting critical imported components. Single-source vulnerability concentrates in catalyst formulation expertise held by legacy acetyls operators. Distribution runs through Rotterdam, Houston, and Singapore chemical hubs for just-in-time delivery to coating and adhesive plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern VAM procurement as large coating formulators demand batch-traceable, certified supply integrated into their quality management systems. This interoperability shift rewards producers with documented ISO 9001 and Responsible Care histories while marginalizing spot-market suppliers.
For Market Incumbents: Build closed-loop ethylene oxide recovery infrastructure as a regulatory compliance moat. Celanese Corporation and Wacker Chemie AG should expand catalyst regeneration service contracts to capture lifetime value from installed capacity. Defend against carbide-route Asian export surge by securing long-term ethylene supply agreements with Gulf Coast crackers. Priority lever: backward integration into acetic acid production to isolate margin from feedstock volatility.
For New Entrants and Emerging Players: Southeast Asian coating markets exhibit geographic underpenetration by certified low-VOC emulsion-grade suppliers. Target Vietnam and Indonesia architectural paint formulators seeking REACH-equivalent compliance pathways for export-oriented production. White-space opportunity exists in food-grade laminate certification for regional dairy packaging growth. Go-to-market angle: partnership with European distributors holding existing Responsible Care audit relationships to bypass eighteen-month qualification timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catalyst technology licensors and closed-loop recovery system providers serving existing capacity rather than greenfield developers. Long-term viability favors integrated acetyls chains with captive utility infrastructure and documented regulatory compliance histories. Acquisition target archetype: regional emulsion-grade specialists with ISO 9001 certification and established relationships with mid-tier coating formulators. Signal to watch: EPA enforcement actions against Texas and Louisiana facilities that accelerate compliance capex deployment and compress marginal capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Celanese Corporation leverages acetyls chain control to isolate VAM margins from feedstock volatility. |
| Catalyst Efficiency Licensing | Technology transfer agreements generate recurring revenue while constraining new entrant ramp rates. |
| Closed-Loop Recovery Installation | EPA ethylene oxide compliance capex freezes marginal capacity additions outside integrated complexes. |
| Food-Grade Certification Investment | Residual monomer thresholds below 5 ppm open protected margin pools in regulated packaging applications. |
| Regional Distribution Hub Expansion | Inventory positioning in Rotterdam and Singapore enables just-in-time delivery for coating formulators. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at integrated acetyls facilities, procurement leads at European coating manufacturers, distribution channel partners in Rotterdam and Singapore, and technical R&D directors specializing in emulsion polymerization. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, EPA enforcement databases, and ECHA registration timelines. Bottom-up capacity and utilization estimates were triangulated against top-down demand segmentation across adhesive, coating, and packaging applications.
Calibration against historical capacity expansion patterns and feedstock cost regimes anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry concentration, regional production hub economics, and certification compliance status. CAGRs were derived from slope-intercept analysis of volume trajectories against macroeconomic drivers. Industry-specific forecast inputs incorporated ethylene-naphtha spread projections and REACH authorization timeline assumptions for acetic acid pathway intermediates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed conglomerates or accelerated EPA enforcement timelines would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market