
 Global Polyalkylene Glycol (PAG) and Esters Market | 2026-2036
Global Polyalkylene Glycol (PAG) and Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyalkylene Glycol (PAG) and Esters Market Analytics
Multi-source procurement for alkylene oxide feedstock is recalibrating how lubricant compounders manage cost volatility across the PAG value chain. Dow leverages captive ethylene oxide capacity in Freeport, Texas, to anchor its polyethylene glycol supply to North American coatings producers. BASF SE competes through backward integration into propylene oxide at its Ludwigshafen Verbund site, sustaining margin control across polypropylene glycol grades. Idemitsu Kosan specializes in high-viscosity PAG base stocks for Japanese automotive OEMs, occupying a defensible niche in compressor lubricants.
Polyalkylene glycols and esters comprise synthetic polyether polymers and carboxylic acid derivatives engineered for thermal oxidative stability across wide viscosity ranges, typically manufactured through base-catalyzed alkoxylation of alcohol initiators followed by esterification with fatty acids for lubricant and surfactant applications. Polypropylene glycol leads product type demand due to its dominance in polyurethane foam and brake fluid formulations, while esters represent the fastest-growing category as aviation turbine oil specifications tighten. In application segmentation, coatings absorbs the largest volume share from architectural and industrial protective formulations, whereas pharmaceuticals commands premium pricing through FDA-validated excipient grades for ophthalmic and parenteral delivery systems.
REACH registration requirements in Europe and EPA lubricant toxicity screening in the United States are elevating compliance costs for non-biodegradable PAG chemistries, while China's MEE enforcement of wastewater discharge limits is accelerating ester adoption in metalworking fluids. The EU F-Gas Regulation phase-down is simultaneously redirecting compressor lubricant demand toward PAG formulations compatible with lower-GWP refrigerants. Stakeholders must monitor how divergent biodegradability standards across the EPA, ECHA, and China's GB frameworks reshape product development roadmaps and regional manufacturing footprints.
Market Dynamics
Automotive OEM thermal stability specifications are compressing formulation cycles and forcing lubricant compounders to requalify base stock portfolios, while REACH registration deadlines and China's dual carbon goals simultaneously redirect R&D capital toward bio-based ester chemistries.
Growth Catalysts
- EU F-Gas Regulation phase-down:Compressor lubricant demand is migrating toward PAG formulations compatible with lower-GWP refrigerants, expanding addressable volume in HVAC and industrial refrigeration systems.
- Aviation turbine oil specification tightening:Ester base stocks are capturing incremental share in aerospace lubricant formulations as thermal oxidative stability requirements intensify for next-generation turbine engines.
- United States Gulf Coast propylene oxide integration:Captive alkylene oxide supply at Freeport and Corpus Christi is anchoring derivative PAG output for North American coatings and brake fluid compounders.
Market Restraints
- Alkylene oxide feedstock volatility:Ethylene oxide and propylene oxide prices fluctuate with crude oil derivatives and refinery operating rates, compressing blender margins unpredictably.
- REACH registration cost escalation:ECHA compliance requirements for non-biodegradable PAG chemistries impose six-figure dossier preparation costs that disadvantage smaller European compounders.
- Mineral oil substitution economics:Group II and Group III base oils from integrated refiners in Asia-Pacific offer price-performance ratios that constrain synthetic penetration in cost-sensitive industrial segments.
Strategic Opportunities
- India metalworking fluid upgrade cycle:BIS enforcement of stricter wastewater discharge standards is accelerating ester adoption in machining and grinding operations across Maharashtra and Gujarat manufacturing clusters.
- Ophthalmic excipient certification:FDA-validated PAG grades for parenteral and ocular drug delivery command 3-4x pricing multiples versus industrial formulations with limited qualified suppliers.
- Carbon accounting integration:EU CSRD disclosure requirements are creating procurement preference for bio-based esters with verified lifecycle carbon footprints in automotive and aerospace supply chains.
Industry Challenges
- Alkoxylation catalyst expertise scarcity:Base-catalyzed polymerization process optimization requires specialized chemical engineering talent concentrated at legacy German and Japanese producers.
- Multi-jurisdiction biodegradability testing:Divergent OECD, EPA, and GB standard protocols force redundant screening expenditures for products sold across North America, Europe, and China.
- Legacy formulation requalification timelines:Automotive OEM approval cycles for new base stocks extend 18-36 months, freezing supplier switches even when performance advantages are demonstrated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyalkylene Glycol (PAG) and Esters Market |
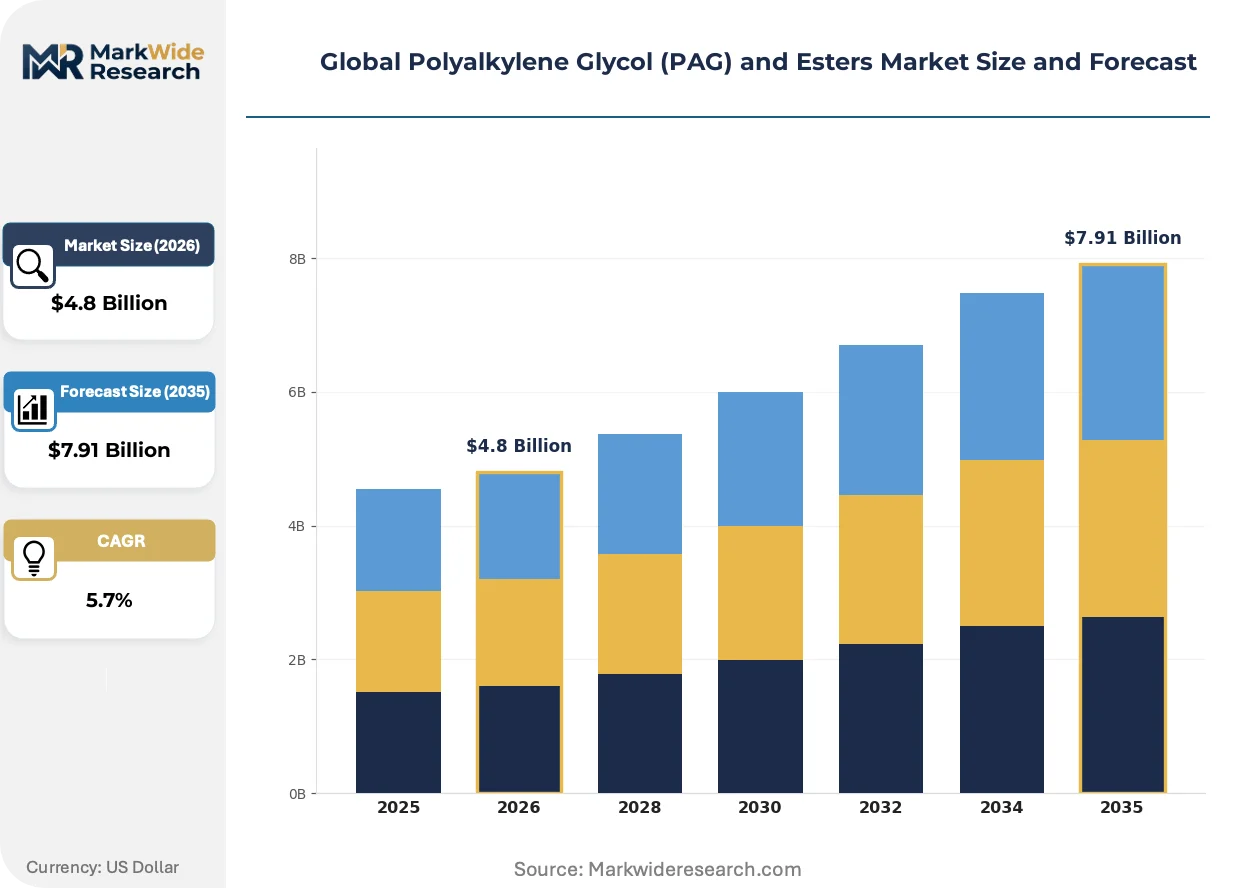
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Glycol, Polypropylene Glycol, Esters, Blends Application: Coatings, Adhesives, Cosmetics, Pharmaceuticals End User: Aerospace, Automotive, Personal Care, Food & Beverage Form: Liquid, Solid, Semi-Solid, Gel |
| Companies Covered | Dow, BASF SE, Idemitsu Kosan Co., Ltd., Clariant, Shell plc, INEOS, Huntsman Corporation, SABIC, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyalkylene Glycol (PAG) and Esters Market Evolving Landscape
Digital formulation platforms and closed-loop carbon accounting are compressing product development timelines while regulatory phase-downs across multiple geographies are forcing refrigerant-lubricant compatibility redesigns.
Water-soluble PAG lubricants for metalworking applications are decentralizing supply relationships between compounders and Tier-1 automotive suppliers. Japanese and German machining fluid formulators are adopting these chemistries at accelerated rates to meet MEE and REACH wastewater targets. This technology is decentralizing procurement authority from centralized chemical distributors toward direct mill relationships with specialized PAG producers.
China's dual carbon goals and GB standard updates are mandating biodegradable base stocks in industrial lubricants by 2027, with MEE enforcement accelerating in Yangtze River Delta manufacturing zones. Domestic ester producers in Jiangsu and Zhejiang are expanding capacity to capture substitution demand from mineral oil and conventional PAG formulations. Metalworking and hydraulic fluid segments are responding with accelerated reformulation programs to preempt compliance deadlines.
Automotive lubricant buyers are consolidating approved supplier lists from 8-12 base stock vendors toward 3-4 strategic partnerships with full technical service capabilities. This concentration is displacing spot-market purchasing and forcing mid-size compounders to invest in application engineering resources or exit OEM qualification pipelines. The shift is most visible in Germany and the United States, where Volkswagen Group and Detroit Three procurement organizations have implemented tiered supplier categorization frameworks.
Global Polyalkylene Glycol (PAG) and Esters Market Segmentation
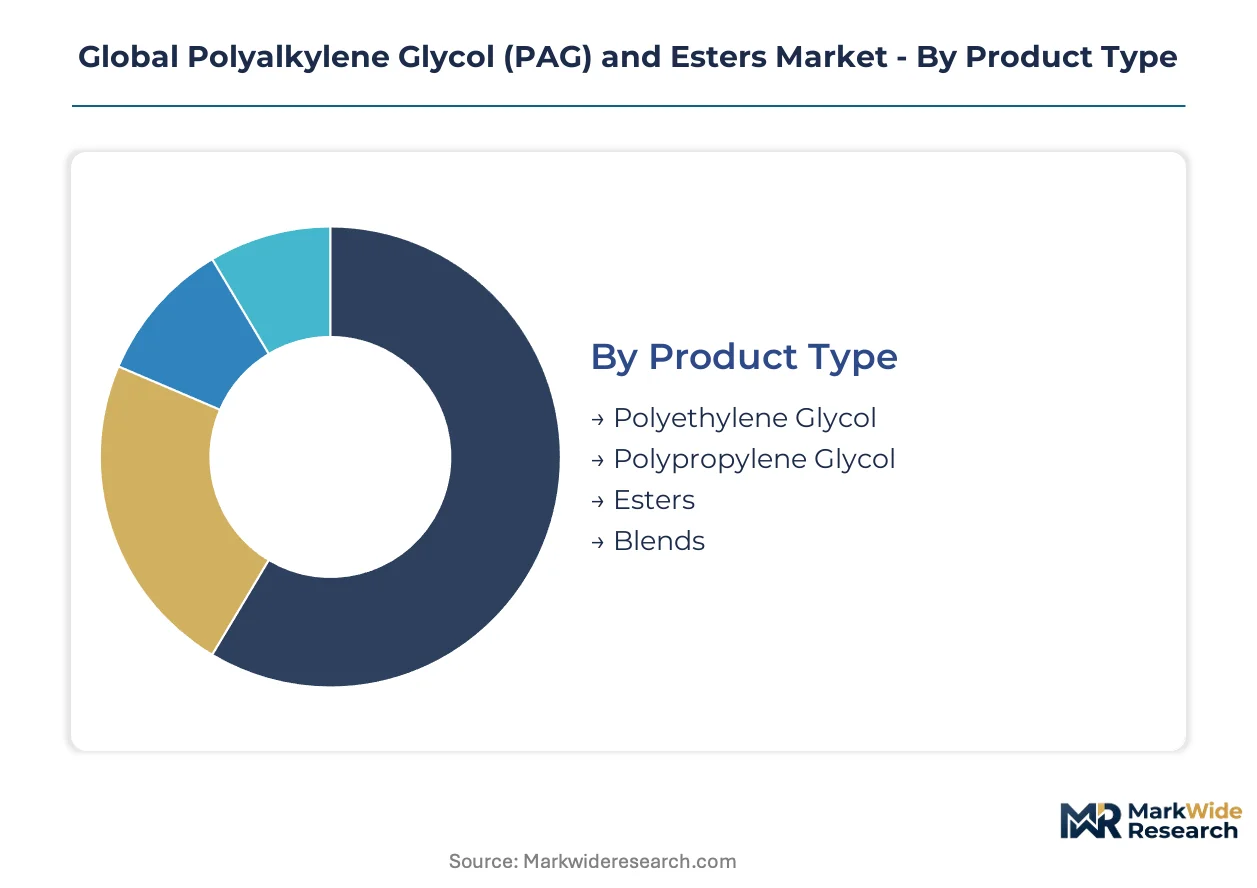
Product formulators select PAG and ester grades based on thermal stability thresholds and regulatory compliance requirements rather than commodity pricing. Segmentation logic in this market follows performance specifications that cascade from automotive OEM thermal standards through REACH and MEE wastewater mandates.
Product Type:
Integration depth varies sharply across this category, with polypropylene glycol functioning as a standalone base stock in brake fluids while ester blends embed as performance additives within complex lubricant formulations.
- Polypropylene Glycol:Manufactured through base-catalyzed propoxylation of alcohol initiators, this polymer dominates polyurethane foam and brake fluid applications. Demand concentrates in the United States Gulf Coast petrochemical corridor, where integrated propylene oxide supply at Freeport and Corpus Christi anchors derivative output for North American automotive compounders.
- Esters:Carboxylic acid derivatives engineered through fatty acid esterification deliver superior thermal oxidative stability for aviation turbine oils. German and Japanese automotive OEMs are expanding uptake as thermal stability specifications tighten, while REACH compliance redirects capital toward bio-based ester chemistries in European formulations.
- Polyethylene Glycol:Ethylene oxide-derived polyethers serve pharmaceutical excipient and surfactant applications with FDA-validated grades commanding premium positioning.
- Blends:Hybrid formulations combine PAG and ester chemistries to optimize cost-performance ratios in industrial metalworking fluids.
Polypropylene glycol leads volumes today; esters are gaining share fastest.
Application:
Cost tier differentiation separates commodity coatings volumes from pharmaceutical-grade premiums requiring multi-jurisdiction validation.
- Coatings:Architectural and industrial protective formulations absorb the largest volume share of PAG derivatives. Water-soluble PAG lubricants are decentralizing procurement relationships between compounders and Tier-1 automotive suppliers across German and Japanese machining fluid markets.
- Pharmaceuticals:FDA-validated excipient grades for ophthalmic and parenteral delivery systems command pricing multiples versus industrial formulations. Qualified supplier scarcity limits market entry despite attractive margins.
- Adhesives:Polyether backbone structures provide controlled viscosity and cure characteristics in construction and packaging bonding applications.
- Cosmetics:Humectant and emulsifying functions in personal care formulations require cosmetic-grade purity certifications.
Coatings dominates current volumes; pharmaceuticals shows the steepest expansion trajectory.
End User:
Customer type segmentation reveals how automotive OEM consolidation of approved supplier lists is compressing qualification pipelines for base stock vendors.
- Automotive:Brake fluid, compressor lubricant, and metalworking fluid specifications drive the largest commercial demand. Volkswagen Group and Detroit Three procurement organizations have implemented tiered supplier categorization frameworks that consolidate vendor relationships from 8-12 toward 3-4 strategic partnerships.
- Aerospace:Aviation turbine oil specifications are tightening thermal oxidative stability requirements for next-generation engines, expanding ester base stock adoption. EASA and FAA certification timelines extend 18-36 months, freezing supplier switches even when performance advantages are demonstrated.
- Personal Care:Cosmetic-grade PAG derivatives serve formulation needs for major consumer products manufacturers with strict purity requirements.
- Food & Beverage:Food-grade lubricant and processing aid applications require compliance with FDA and EFSA safety standards.
Automotive leads volumes today; aerospace is expanding most quickly.
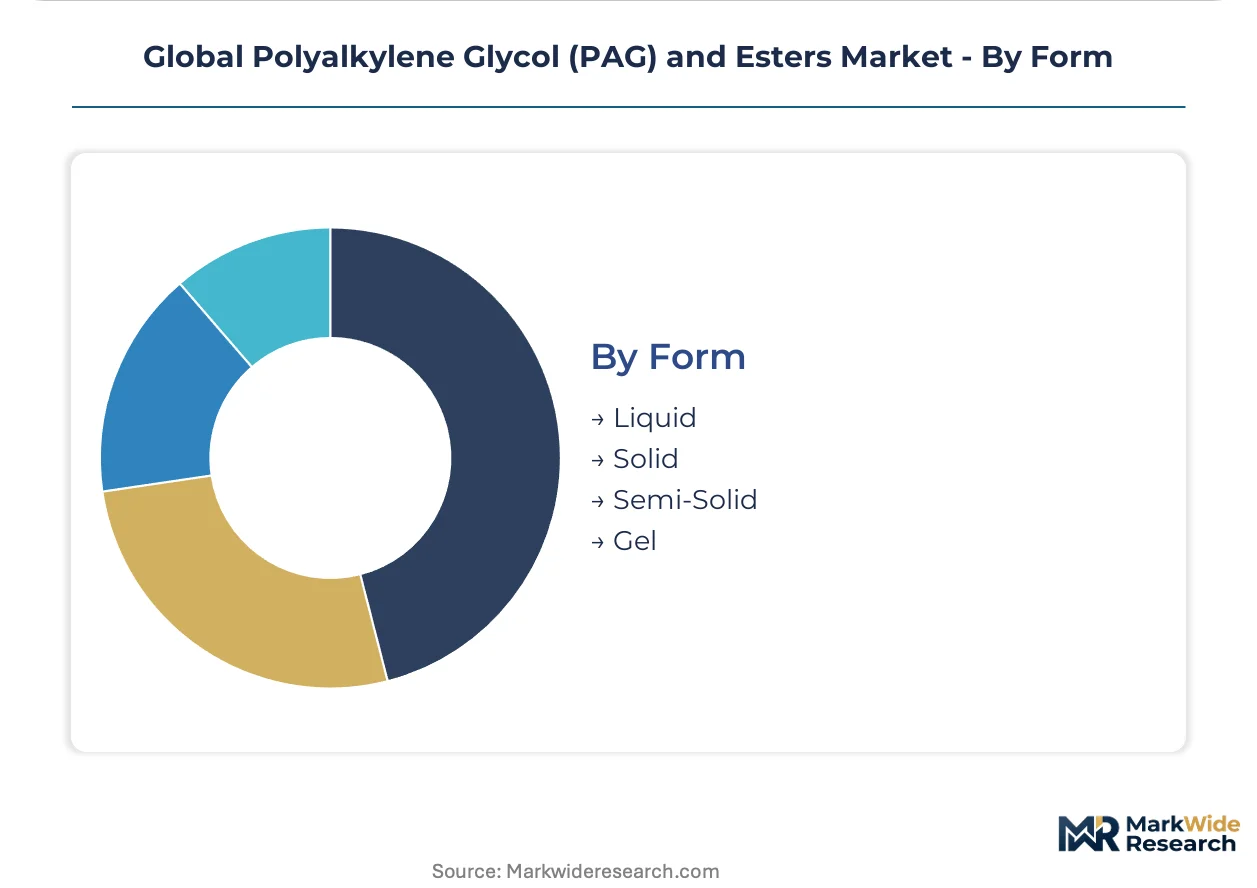
Form:
Supply concentration for high-viscosity grades sits with specialized Japanese producers, while commodity liquids flow through integrated petrochemical channels.
- Liquid:Dominant physical state for lubricant, brake fluid, and coating applications enabling pumpable handling and metered dosing. United States Gulf Coast propylene oxide integration supports liquid PAG output for North American coatings compounders.
- Solid:Polyethylene glycol flakes and powders serve pharmaceutical tablet binding and cosmetic formulation applications requiring controlled dissolution rates.
- Semi-Solid:Intermediate viscosity grades occupy niche positions in specialized adhesive and sealant formulations.
- Gel:Structured formulations for topical pharmaceutical and personal care delivery systems requiring rheological control.
Liquid leads volumes today; solid forms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor anchors global PAG derivative output through integrated propylene oxide supply chains serving North American coatings and brake fluid compounders.
United States
Automotive OEM thermal stability specifications from Detroit Three procurement organizations compress formulation cycles and force lubricant requalification. EPA lubricant toxicity screening elevates compliance costs for non-biodegradable PAG chemistries. Freeport and Corpus Christi propylene oxide integration sustains captive derivative output for regional coatings producers.
Germany
Volkswagen Group tiered supplier categorization consolidates approved vendor lists from 8-12 toward 3-4 strategic partnerships with full technical service capabilities. REACH registration requirements impose six-figure dossier preparation costs that disadvantage smaller compounders. Ludwigshafen Verbund site backward integration into propylene oxide sustains margin control across polypropylene glycol grades.
China
Dual carbon goals and MEE enforcement of wastewater discharge limits accelerate ester adoption in metalworking fluids across Yangtze River Delta manufacturing zones. GB standard updates mandate biodegradable base stocks in industrial lubricants by 2027. Domestic ester producers in Jiangsu and Zhejiang expand capacity to capture substitution demand from mineral oil formulations.
Japan
Automotive OEMs expand PAG uptake as thermal stability specifications tighten for compressor lubricants and metalworking fluids. METI industrial standards shape formulation requirements for domestic machining fluid markets. Idemitsu Kosan specializes in high-viscosity PAG base stocks, occupying a defensible niche serving Japanese automotive OEMs directly.
India
BIS enforcement of stricter wastewater discharge standards accelerates ester adoption in machining and grinding operations across Maharashtra and Gujarat manufacturing clusters. Metalworking fluid upgrade cycles create procurement windows for synthetic base stock suppliers. Domestic formulators reformulate hydraulic and cutting fluid portfolios to preempt compliance deadlines in western industrial corridors.
Global Polyalkylene Glycol (PAG) and Esters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based ester specializations and regional qualification partnerships. The vendor base stratifies between integrated petrochemical majors with captive alkylene oxide supply and specialized compounders with application engineering depth. Three archetypes dominate: Gulf Coast-integrated volume leaders, German-Japanese high-viscosity specialists, and Chinese domestic ester scale players. Competitive moves concentrate on backward integration into propylene oxide and strategic partnerships with automotive OEM technical centers.
Among integrated petrochemical majors, Dow exemplifies the captive-supply archetype through its Freeport ethylene oxide capacity. BASF SE anchors the European integrated producer tier with Ludwigshafen Verbund site operations. Idemitsu Kosan occupies the high-viscosity specialist position serving Japanese automotive OEM qualification pipelines.
| Leading Market Players |
|---|
| Dow |
| BASF SE |
| Idemitsu Kosan Co., Ltd. |
| Clariant |
| Shell plc |
| INEOS |
| Huntsman Corporation |
| SABIC |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Captive propylene oxide integration at United States Gulf Coast petrochemical complexes anchors both supply security and pricing power for derivative PAG producers serving North American coatings and brake fluid compounders. Dow's Freeport ethylene oxide capacity and BASF SE's Ludwigshafen Verbund operations demonstrate how backward integration into alkylene oxide feedstock insulates margin control against commodity volatility while positioning integrated majors to dictate contract terms.
Pricing Analysis
Alkylene oxide feedstock pass-through mechanics dominate pricing structures across PAG and ester grades, with ethylene oxide and propylene oxide cost movements flowing directly into base stock quotations on quarterly adjustment schedules. Three-tier pricing structure across pharmaceutical-grade, automotive-specification, and industrial-commodity levels separates FDA-validated excipient batches from standard lubricant formulations. Cost compression in industrial-grade polypropylene glycol is intensifying because Group II and Group III mineral oil substitutes from Asian refiners constrain synthetic penetration in price-sensitive metalworking segments. Automotive OEM buyers exhibit the lowest price sensitivity due to 18-36 month requalification timelines that freeze supplier switches, while independent coating compounders negotiate aggressively on spot volumes.
Supply Chain Analysis
Intermodal freight costs from United States Gulf Coast propylene oxide hubs to Midwest automotive manufacturing clusters add meaningful landed cost differentials versus coastal derivative production. Supply concentrates in the United States, Germany, and China, with captive alkylene oxide output at Freeport, Ludwigshafen, and Ningbo anchoring regional PAG derivative flows. Raw material dependencies center on refinery-sourced ethylene and propylene feedstocks, specialized alcohol initiators, and fatty acid esterification agents for aviation-grade esters. Single-source vulnerability runs through concentrated propylene oxide supply at Texas and Louisiana petrochemical corridors, where hurricane disruptions have historically idled derivative output. Distribution runs through integrated chemical distributors serving Tier-1 automotive suppliers directly, with water-soluble PAG metalworking fluids increasingly bypassing intermediaries for mill-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation refrigerant phase-downs and China's MEE wastewater mandates are restructuring procurement specifications across automotive and industrial lubricant value chains.
For Market Incumbents: Anchor margin control through captive alkylene oxide capacity expansion at existing Gulf Coast and Ludwigshafen sites, insulating against feedstock volatility that compresses non-integrated blender margins. Deepen application engineering partnerships with Volkswagen Group and Detroit Three technical centers to secure positions within consolidated 3-4 vendor shortlists, as automotive OEM supplier tiering threatens to displace mid-size compounders lacking full-service capabilities. Prioritize bio-based ester R&D investment to capture REACH-driven substitution demand before Chinese domestic producers achieve European qualification.
For New Entrants and Emerging Players: Direct-to-mill digital procurement platforms offer a route to bypass entrenched chemical distributor relationships in German and Japanese metalworking fluid markets, where water-soluble PAG adoption is decentralizing purchasing authority. White-space concentration sits with ophthalmic excipient certification for parenteral and ocular drug delivery, where FDA-validated supplier scarcity sustains 3-4x pricing multiples versus industrial grades with limited qualified competition. Target India's Maharashtra and Gujarat manufacturing clusters for ester-based metalworking fluid introduction, as BIS wastewater enforcement accelerates reformulation cycles among domestic hydraulic fluid compounders.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs impose six-figure dossier burdens that disadvantage smaller European compounders lacking integrated propylene oxide supply. Long-term viability favors integrated petrochemical majors with captive feedstock and specialized Japanese producers holding automotive OEM qualification pipelines. Acquisition target archetypes include high-viscosity PAG specialists with Idemitsu Kosan-type OEM relationships and Chinese domestic ester producers positioned for European REACH compliance investment. Monitor ECHA bio-based chemistry registration timelines as inflection indicators for capital reallocation toward sustainable ester platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply at Freeport and Ludwigshafen insulates margin control against commodity volatility. |
| Bio-Based Ester Capacity Expansion | REACH compliance deadlines redirect R&D capital toward sustainable chemistries with verified lifecycle footprints. |
| Ophthalmic Excipient Certification | FDA validation for parenteral delivery commands premium positioning with limited qualified supplier competition. |
| Direct Mill Supply Relationships | Water-soluble PAG metalworking fluids bypass distributors for Tier-1 automotive supplier procurement integration. |
| Automotive OEM Technical Partnerships | Volkswagen Group and Detroit Three tiered supplier frameworks consolidate vendor positions to 3-4 strategic relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant formulators, automotive OEM procurement leads, chemical plant managers, and distribution channel partners with secondary validation from SEC 10-K filings, ACC and Cefic industry reports, customs trade data, and REACH registration databases. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against petrochemical derivative output statistics anchored forecast reliability.
Segment-weighting approaches distributed value and volume projections across polypropylene glycol, polyethylene glycol, ester, and blend product types, further disaggregated by coatings, pharmaceutical, automotive, and aerospace end-use applications. CAGRs were derived from alkylene oxide feedstock demand elasticity models and OEM specification adoption curves, with inputs including EU F-Gas Regulation implementation schedules, China's MEE enforcement intensity across Yangtze River Delta zones, and aviation turbine oil thermal stability specification evolution from EASA and FAA.
The model assumes a particular technology adoption path; alternative pathways for bio-based ester chemistry scale-up or accelerated mineral oil substitution in cost-sensitive industrial segments would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency, automotive OEM supplier consolidation timelines, and propylene oxide supply reliability at Gulf Coast petrochemical corridors. A model refresh is warranted upon material change in REACH bio-based registration requirements or MEE wastewater discharge standard implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market