
 Europe Polyolefin Market | 2026-2036
Europe Polyolefin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyolefin Market Insights
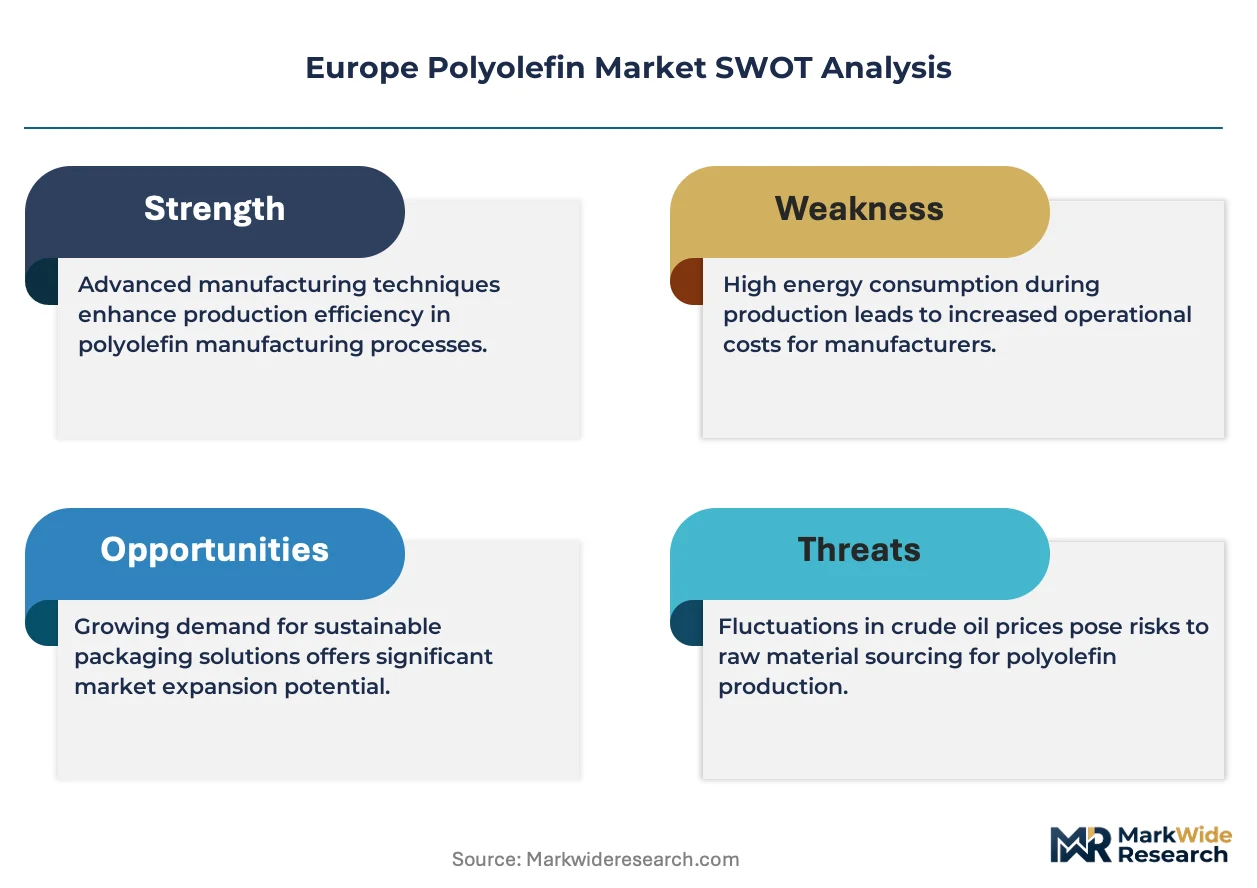
Commodity-grade resin trading margins is narrowing as European producers shift toward specialty copolymers and technical service bundles. INEOS Group AG leverages its North Sea cracker integration to sustain feedstock cost advantages across polyethylene grades. Borealis AG anchors its position through Borstar technology specialization in differentiated polypropylene. LyondellBasell Industries Holdings B.V competes via its Spheripol and Spherizone licensing platforms across European licensee networks.
Polyolefins comprise thermoplastic polymers synthesized primarily from ethylene and propylene monomers through catalytic polymerization, yielding crystalline materials with densities ranging from 0.85 to 0.97 g/cm³ and melt flow indices spanning 0.1 to 1000 g/10 min. These polymers serve as foundational inputs for injection-molded automotive components, blown-film packaging, and extruded construction membranes. Polypropylene commands the dominant product position due to its stiffness-to-weight ratio and heat resistance in automotive underhood applications. Packaging absorbs the largest application share, though construction-grade High-Density Polyethylene pipe resins are gaining specification momentum in utility infrastructure. Gas Phase technology leads installed European capacity, while Solution Process units are being retrofitted for metallocene elastomer output.
REACH registration requirements and the EU F-Gas Regulation constrain feedstock sourcing and process emissions compliance for polymer producers. ECHA substance evaluations are accelerating substitution timelines for certain catalyst systems and additive packages. The EU Green Deal's carbon border adjustment mechanism will reshape import competitiveness for Middle Eastern and North American resin suppliers. Stakeholders must monitor catalyst technology migration paths and assess backward integration into bio-based feedstock cracking before regulatory thresholds harden.
Market Dynamics
EU Green Deal carbon border adjustments are compressing import competitiveness for Middle Eastern resin suppliers while accelerating catalytic process upgrades across Ruhr-based integrated complexes.
Growth Catalysts
- Flexible packaging specification:German and French converters are expanding polypropylene uptake for food-grade films, tightening regional supply-demand balances.
- REACH registration timelines:ECHA substance evaluations are accelerating substitution demand for compliant catalyst systems and additive packages.
- Automotive underhood demand:Polypropylene's stiffness-to-weight ratio is displacing metal in thermal management components across German OEM supply chains.
Market Restraints
- Naphtha feedstock volatility:European crackers remain exposed to arbitrage-sensitive naphtha pricing against US ethane-advantaged competitors.
- Gas Phase capacity concentration:Installed European capacity clusters in Netherlands and Belgium create geographic supply risk during turnaround seasons.
- Mechanical recycling contamination:Post-consumer feedstock quality variability constrains food-contact compliance under EFSA safety standards.
Strategic Opportunities
- Metallocene elastomer retrofit:Solution Process units are converting to specialty output, capturing premium margins in automotive sealing applications.
- Construction-grade pipe resins:Utility infrastructure specifications for High-Density Polyethylene are expanding across French water distribution networks.
- Bio-based feedstock cracking:The EU Green Deal's emissions benchmarks incentivize backward integration into renewable naphtha alternatives.
Industry Challenges
- Metallocene catalyst sourcing:Specialized organometallic expertise concentrates with limited European licensors, constraining technology migration timelines.
- Spheripol license complexity:Polypropylene process IP fragmentation across multiple technology holders complicates capacity expansion planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyolefin Market |
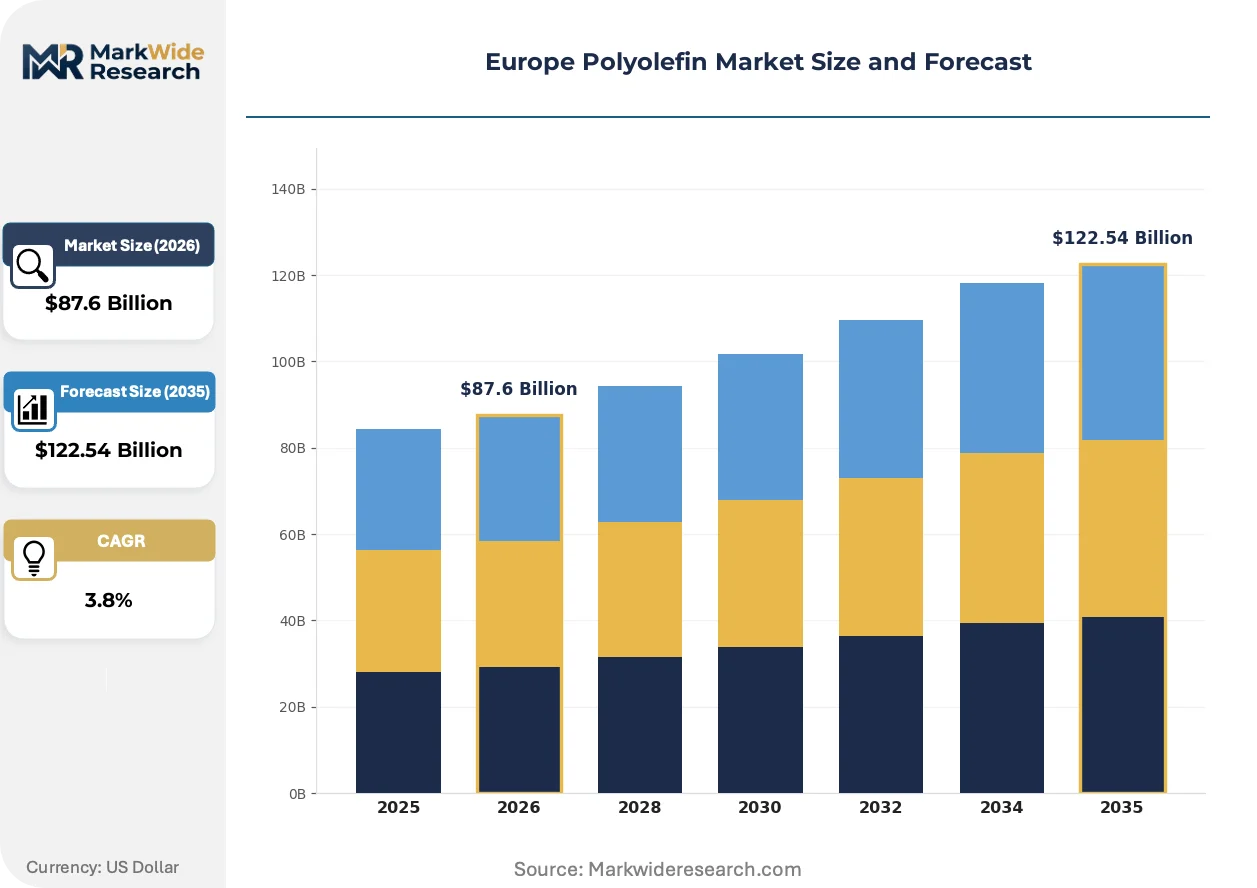
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, High-Density Polyethylene, Low-Density Polyethylene, Polyethylene Terephthalate Application: Packaging, Automotive, Consumer Goods, Construction Technology: Gas Phase, Slurry Process, Solution Process, Catalytic Process End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | INEOS Group AG, LyondellBasell Industries Holdings B.V, Borealis AG, BASF SE, Exxon Mobil Corporation, TotalEnergies SE, SABIC, Arkema S.A, Eni SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyolefin Market Trends and Innovations
Digital twin deployment across polymerization trains is compressing process optimization cycles while regulatory compliance automation is reshaping quality assurance protocols.
Advanced process control systems using real-time spectroscopic monitoring are virtualizing traditional lab-based quality verification. Packaging converters in Germany's North Rhine-Westphalia cluster are adopting these platforms fastest. This virtualization is compressing batch release timelines from hours to minutes while reducing off-spec material generation.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-grade foam blowing agent transitions toward hydrocarbon alternatives. Polypropylene block copolymer producers face reformulation complexity for insulated packaging applications. Spanish appliance manufacturers are accelerating qualification timelines to maintain CE marking compliance ahead of 2027 step-down thresholds.
Specification-driven procurement is consolidating buyer power among German automotive tier-one suppliers. Direct mill relationships are displacing distributor intermediaries for engineered resin grades. This concentration is most visible in Bavaria's automotive supply basin where BMW and Audi nesting strategies demand captive technical service capabilities.
Europe Polyolefin Market Segmentation
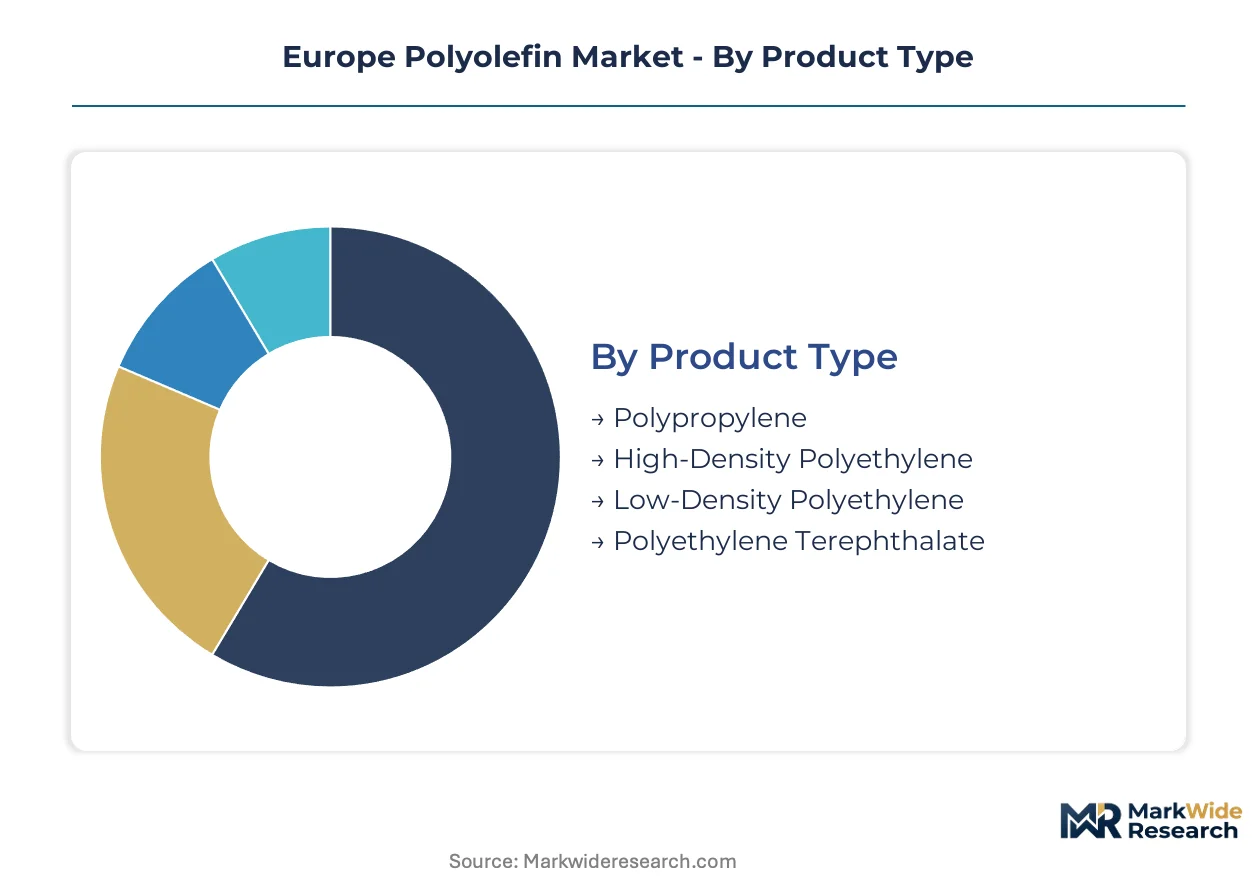
Polyolefin procurement patterns diverge sharply across product grades and end-use specifications. European converters select resin tiers based on regulatory compliance thresholds and automotive OEM qualification requirements rather than commodity pricing alone.
Product Type:
Cost tier differentiation separates commodity volume grades from specialty copolymers commanding technical service premiums.
- Polypropylene:Semi-crystalline thermoplastic with density near 0.90 g/cm³ and melt flow indices tailored to injection molding or film extrusion. German automotive underhood applications absorb expanding volumes as metal displacement accelerates across BMW and Audi supply chains facing lightweighting mandates.
- High-Density Polyethylene:Linear polymer chains yield density above 0.94 g/cm³ with superior tensile strength for pressure-rated applications. French water utility specifications for HDPE pipe resins are tightening across Saur and Veolia infrastructure renewal programs under EU Green Deal leakage reduction targets.
- Low-Density Polyethylene:Branched-chain architecture delivers flexibility for blown film and extrusion coating.
- Polyethylene Terephthalate:Aromatic polyester variant serves bottle and fiber applications outside core polyolefin chemistry.
Polypropylene commands the established base. The steepest expansion runs through High-Density Polyethylene.
Application:
Application mix reflects end-use margin profiles and regulatory exposure across EU member states.
- Packaging:Flexible film converters in Germany's Ruhr cluster and France's Hauts-de-France region specify food-grade polypropylene for extended shelf-life applications. EFSA compliance requirements for post-consumer recycled content are forcing reformulation investments ahead of PPWR implementation timelines.
- Automotive:Interior trim and thermal management components demand heat-resistant copolymers with long-term aging stability. Bavarian OEM nesting strategies concentrate procurement power among tier-one suppliers requiring captive technical service capabilities from resin vendors.
- Consumer Goods:Durable household articles and appliance housings specify medium-impact grades.
- Construction:Geomembranes and pipe systems utilize HDPE pressure ratings for civil engineering.
Packaging retains volume leadership. Automotive represents the fastest-climbing specification tier.
Technology:
Technology selection determines catalyst flexibility and product slate breadth for integrated producers.
- Gas Phase:Fluidized bed reactors operate without solvent recovery, lowering capital intensity for commodity polyethylene. Netherlands and Belgian capacity clusters anchor European supply, creating geographic concentration risk during planned turnaround seasons.
- Slurry Process:Loop reactors with diluent medium enable high-crystallinity polypropylene grades for stiffness-critical applications.
- Solution Process:Homogeneous catalysis in solvent medium supports metallocene elastomer retrofit investments.
- Catalytic Process:Ziegler-Natta and metallocene systems define molecular weight distribution control.
Gas Phase dominates installed European capacity. Solution Process retrofits are gaining share fastest among specialty producers.
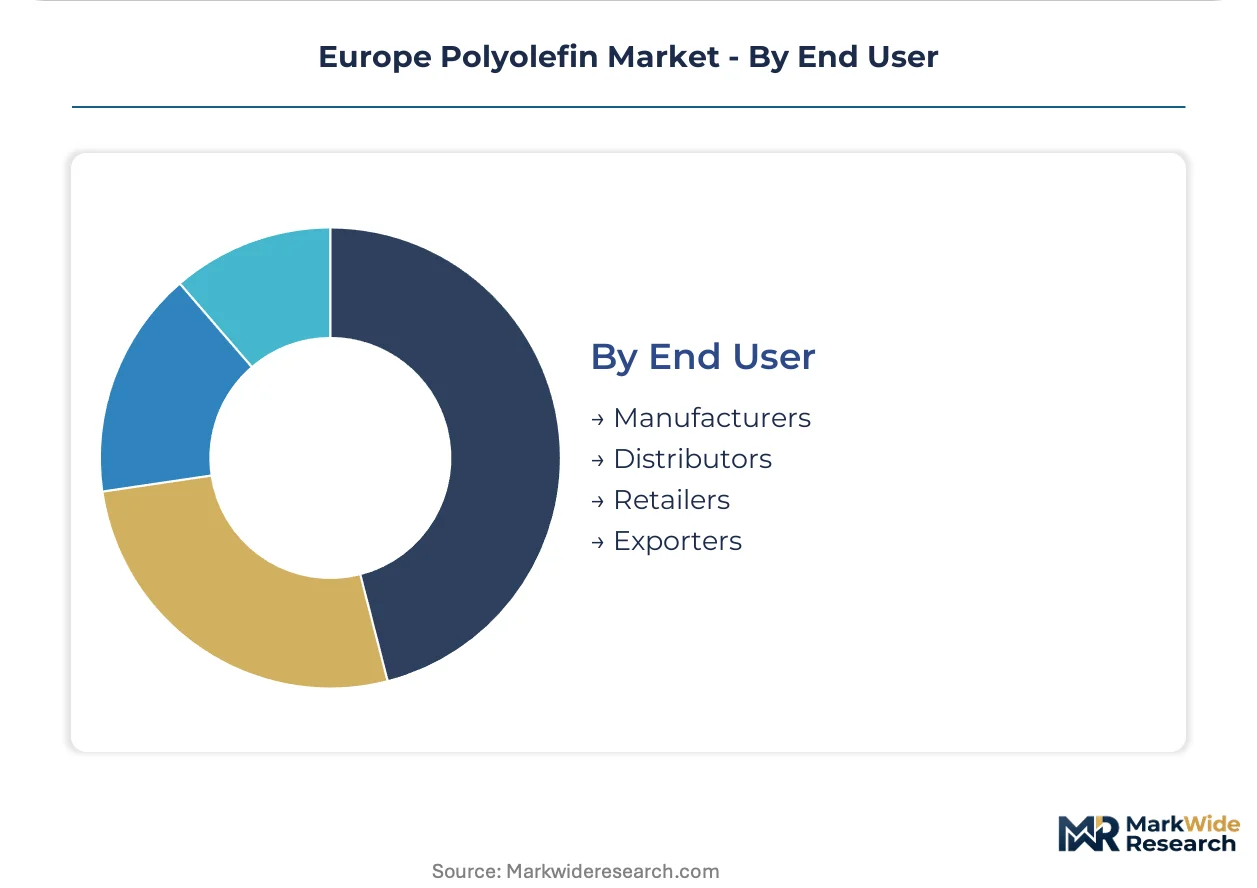
End User:
Customer type shapes service intensity and contract structure across the value chain.
- Manufacturers:Integrated petrochemical complexes and standalone polymerization units source monomer feedstock through North Sea cracker networks or import arbitrage. Ruhr-based producers leverage backward integration into naphtha cracking to buffer margin compression.
- Distributors:Regional stockholding intermediaries manage working capital for small-batch converters.
- Retailers:Private-label packaging specifiers influence resin selection through sustainability scorecards.
- Exporters:Merchant traders arbitrage European premium pricing against Middle Eastern volume supply.
Manufacturers anchor procurement volume. Retailer sustainability specifications are expanding most quickly as downstream influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European polyolefin demand. German automotive converters absorb premium copolymer pricing for qualification-locked supply, while Southern European packaging buyers arbitrage spot resin against Middle Eastern import offers.
Germany
BMW and Audi lightweighting mandates drive polypropylene consumption for underhood thermal management components. EU Green Deal carbon border adjustments pressure Ruhr-based crackers toward catalytic process upgrades. The North Rhine-Westphalia cluster anchors integrated petrochemical complexes where INEOS leverages North Sea feedstock integration.
France
Saur and Veolia infrastructure renewal programs specify High-Density Polyethylene pipe resins for water distribution leakage reduction. EFSA safety standards constrain post-consumer recycled content compliance timelines for flexible food-grade films. The Hauts-de-France region concentrates packaging converter investment adjacent to Belgian resin supply corridors.
Netherlands
Gas Phase reactor capacity clusters create geographic supply concentration risk during planned turnaround seasons. REACH registration timelines accelerate substitution demand for compliant catalyst systems. Rotterdam port infrastructure enables naphtha import arbitrage for crackers serving Northwest European derivative demand.
Belgium
Antwerp's petrochemical ring hosts polyethylene capacity serving French and German converter markets. F-Gas Regulation phase-down schedules force refrigeration-grade foam blowing agent transitions toward hydrocarbon alternatives. The Flanders region anchors Borealis Borstar technology specialization for differentiated polypropylene output.
Italy
Appliance manufacturers accelerate qualification timelines for insulated packaging reformulations ahead of 2027 regulatory thresholds. CE marking compliance requirements reshape procurement specifications for block copolymer grades. Lombardy-based converters face margin compression from specification-driven consolidation among German automotive tier-one suppliers.
Europe Polyolefin Market Competitive Landscape
Integrated petrochemical majors and technology-specialized licensors split the market between feedstock-advantaged scale and differentiated process IP. Concentration is moderate, with Ruhr-based crackers and Benelux Gas Phase clusters anchoring regional supply. Two archetypes dominate: backward-integrated producers leveraging North Sea naphtha networks, and technology licensors monetizing proprietary catalytic platforms. Competitive moves center on metallocene elastomer retrofits and specialty copolymer portfolio expansion.
Within the technology-licensor tier, INEOS Group AG and LyondellBasell Industries Holdings B.V exemplify divergent positioning strategies. INEOS occupies the feedstock-integrated archetype through its North Sea cracker network. LyondellBasell represents the IP-licensing model via its Spheripol and Spherizone platforms. Borealis AG anchors the specialty-differentiation vector through Borstar technology deployment.
| Leading Market Players |
|---|
| INEOS Group AG |
| LyondellBasell Industries Holdings B.V |
| Borealis AG |
| BASF SE |
| Exxon Mobil Corporation |
| TotalEnergies SE |
| SABIC |
| Arkema S.A |
| Eni SpA |
| Others |
Pricing and Supply Chain Analysis
Gas Phase reactor utilization rates above 85% across Netherlands and Belgian clusters have tightened spot polyethylene availability, forcing converters toward longer-term offtake contracts and amplifying supplier pricing leverage during turnaround seasons.
Pricing Analysis
Technical service bundles and catalyst system licensing fees now generate lifetime value exceeding base resin margins for European producers. Pricing stratifies across metallocene elastomer premiums, Borstar-grade specialty copolymers, and commodity spot polyethylene tiers. Cost compression in commodity grades is intensifying because Middle Eastern import arbitrage undercuts Ruhr-based naphtha crackers. Southern European packaging converters exhibit highest price sensitivity, while German automotive tier-one suppliers absorb premium copolymer pricing for qualification-locked supply.
Supply Chain Analysis
Contract manufacturing concentration rests with INEOS, Borealis, and LyondellBasell licensing networks anchoring Northwest European capacity. Feedstock sourcing draws from North Sea naphtha crackers, US ethane import terminals, and Rotterdam-arbitraged Middle Eastern volumes. Single-source vulnerability concentrates around metallocene catalyst organometallic expertise held by limited European licensors. Distribution runs through integrated petrochemical complexes directly to large converters, with regional stockholders managing small-batch working capital.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EU Green Deal emissions benchmarks splinter demand into bio-based feedstock tiers, metallocene specialty grades, and mechanical recycling-compliant specifications.
For Market Incumbents: Harden backward integration into renewable naphtha alternatives before carbon border adjustment thresholds harden. Consolidate Spheripol and Spherizone licensing control to constrain new capacity entrants. Defensive moves must address metallocene catalyst sourcing concentration risk and emerging bio-based feedstock competitors.
For New Entrants and Emerging Players: Build out mechanical recycling purification capabilities for food-contact EFSA compliance, the most penetrable white space as post-consumer feedstock quality variability constrains incumbent expansion. Target French water utility HDPE pipe specifications under Saur and Veolia infrastructure renewal programs. Go-to-market angle centers on circularity certification bundled with technical service.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because commodity resin trading margins are narrowing toward integrated feedstock-advantaged scale players. Acquisition target archetype: Solution Process unit owners with metallocene elastomer retrofit potential. Signal to watch: ECHA substance evaluation acceleration forcing catalyst system substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock | Captures EU Green Deal emissions premiums ahead of carbon border adjustment implementation. |
| Metallocene Elastomer Retrofit | Converts Solution Process units to automotive sealing applications commanding specialty margins. |
| Mechanical Recycling Purification Scale-up | Enables food-contact EFSA compliance under PPWR recycled content mandates. |
| Catalyst System Licensing Expansion | Monetizes Spheripol and Spherizone IP across European licensee networks. |
| Long-term Supply Agreement with Automotive Tier-Ones | Locks in Bavarian OEM nesting strategies requiring captive technical service capabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with plant managers at Ruhr-based crackers, procurement leads at German automotive tier-one suppliers, technical R&D directors at catalyst licensors, and distribution channel partners in Benelux; and secondary validation through Cefic trade statistics, SEC 10-K filings of listed petrochemical majors, EU ETS emissions registries, and customs naphtha import records. Bottom-up capacity modeling triangulated against top-down demand aggregation across packaging, automotive, and construction end-uses.
Forecast inputs considered grade tier differentiation, end-use industry qualification requirements, regional production hub clustering, and technology platform migration paths across the analysis window. CAGRs derived from elasticity-adjusted volume projections incorporating EU Green Deal regulatory phase-in schedules and REACH registration substitution timelines. Industry-specific inputs included cracker operating rate assumptions and metallocene capacity conversion feasibility curves.
Stress conditions across naphtha-ethane feedstock spreads, carbon border adjustment rate assumptions, and catalyst technology migration speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from ECHA regulatory acceleration or Middle Eastern capacity expansion. Cross-checking against Cefic production statistics and EU ETS verified emissions data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyimides Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Bio-Polybutadiene Market