
 US Automotive Thermoplastic Polymer Composites Market | 2026-2036
US Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Thermoplastic Polymer Composites Market Analytics
US resin compounders and fiber suppliers is shifting capacity toward automotive-qualified grades as electrification reshapes material specifications. Celanese Corporation leverages its integrated polyacetal and engineered materials portfolio to supply OEMs with high-flow formulations for complex geometries. BASF anchors its position through backward integration into polyamide polymerization, securing captive supply for glass-filled compounds demanded by domestic vehicle assemblers.
Automotive thermoplastic polymer composites combine continuous or discontinuous reinforcing fibers with thermoplastic matrices such as polypropylene, polycarbonate, or nylon, processed via injection molding or compression molding to achieve specific strength-to-weight ratios exceeding 150 MPa per g/cm³ for structural load-bearing applications. These materials primarily replace metal stampings and thermoset composites to reduce vehicle mass while maintaining crash performance and design flexibility. Polypropylene compounds dominate current volumes due to cost position and recyclability, though polycarbonate blends command premium positioning in transparent and aesthetic interior components where surface quality requirements are most demanding. Injection molding technology leads equipment utilization across the value chain, while 3D printing occupies an emerging niche for prototyping and low-volume tooling applications where lead time compression justifies higher unit economics.
NHTSA crashworthiness standards and EPA fuel economy regulations jointly determine material selection thresholds for exterior panels and structural parts, with compliance costs rising for formulations that fail to meet simultaneous stiffness and impact criteria. California Air Resources Board rules extend these requirements through state-level zero-emission vehicle mandates that propagate into national platform designs. Stakeholders must monitor evolving battery enclosure specifications and federal Buy America content rules as these frameworks increasingly dictate composite qualification pathways and supplier eligibility for domestic OEM procurement programs.
Market Dynamics
Electric vehicle platform architectures are forcing material qualification cycles to compress from 48 months to 24 months as OEMs redesign thermal management systems and battery enclosures around thermoplastic composites.
Growth Catalysts
- EPA Fuel Economy Standards:Corporate Average Fuel Economy targets pressure OEMs to substitute metal stampings with glass-reinforced polypropylene in underbody shields and structural reinforcements.
- Glass Fiber Mat Thermoplastics (GMT):Compression-molded GMT processes enable mid-volume production of seat backs and load floors with 40% mass reduction versus steel assemblies.
- Michigan Manufacturing Corridor:Tier-1 compounders cluster within 150 miles of Detroit assembly plants, reducing logistics costs for just-in-time delivery of engineered resins.
Market Restraints
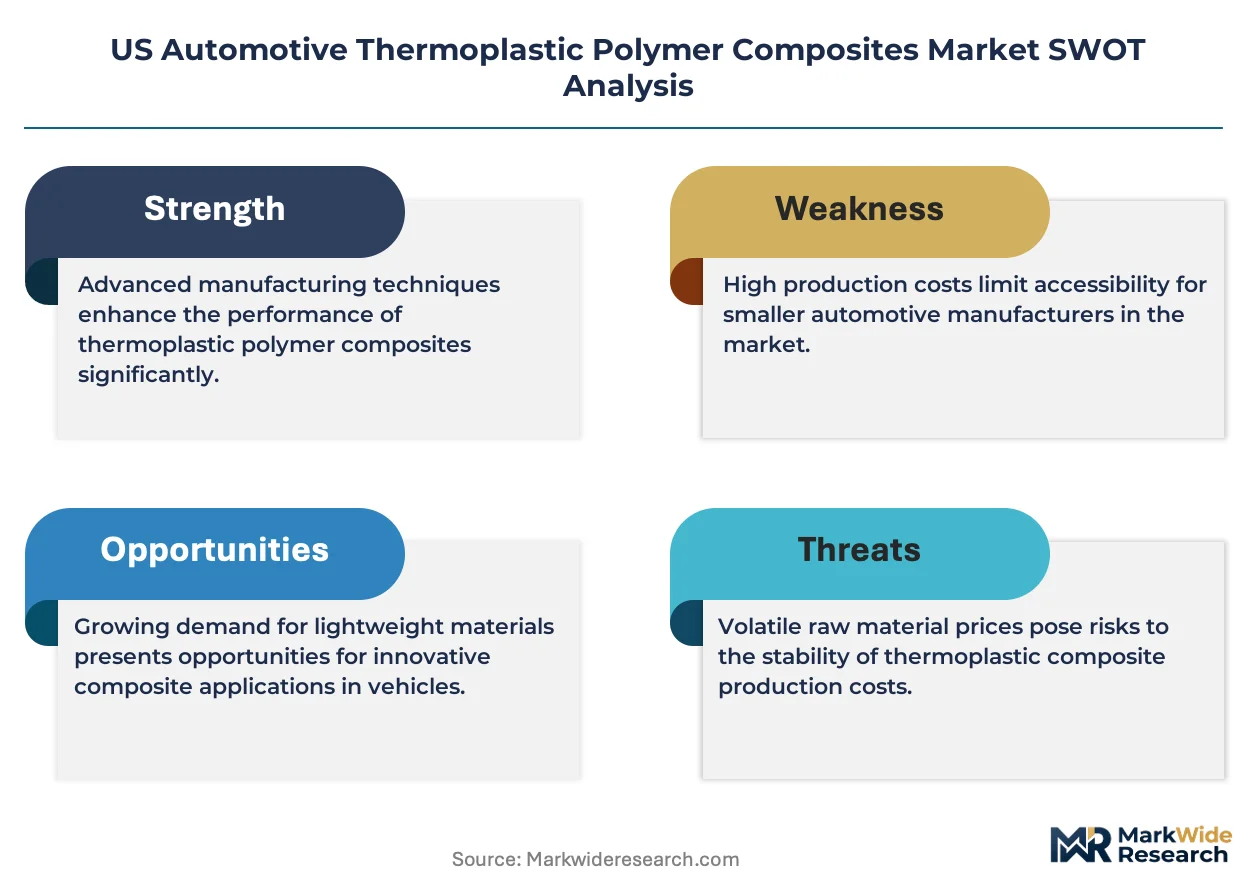
- Polypropylene Feedstock Volatility:Propylene monomer prices track crude oil and natural gas liquids, compressing compounder margins during upstream petrochemical disruptions.
- Carbon Fiber Concentration:US domestic PAN precursor capacity remains limited to two primary suppliers, constraining qualification of continuous carbon-reinforced grades for structural battery enclosures.
- Thermoset Substitution Lock-in:Sheet molding compound retains cost advantage in Class A body panels, slowing thermoplastic penetration in exterior applications.
Strategic Opportunities
- Texas Gulf Coast Resin Expansion:New ethane cracker investments near Corpus Christi create feedstock proximity for polypropylene compounders serving southern US vehicle assembly.
- Overmolding Metal Inserts:Hybrid processing bonds thermoplastic composites to aluminum stampings in crash structures, opening structural applications previously reserved for metals.
- California ZEV Mandate Propagation:Advanced Clean Cars II rules extend through 2035, accelerating thermoplastic adoption in thermal runaway barriers for battery packs.
Industry Challenges
- Simulation Engineer Scarcity:Shortage of specialists in anisotropic material modeling for fiber orientation prediction delays part validation cycles.
- NHTSA Crash Certification Timelines:Full-vehicle pedestrian impact testing for thermoplastic front-end modules requires 18-24 month lead times, constraining platform refresh schedules.
- Recyclate Qualification Complexity:Post-industrial regrind incorporation limits vary by OEM specification, complicating closed-loop material strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Thermoplastic Polymer Composites Market |
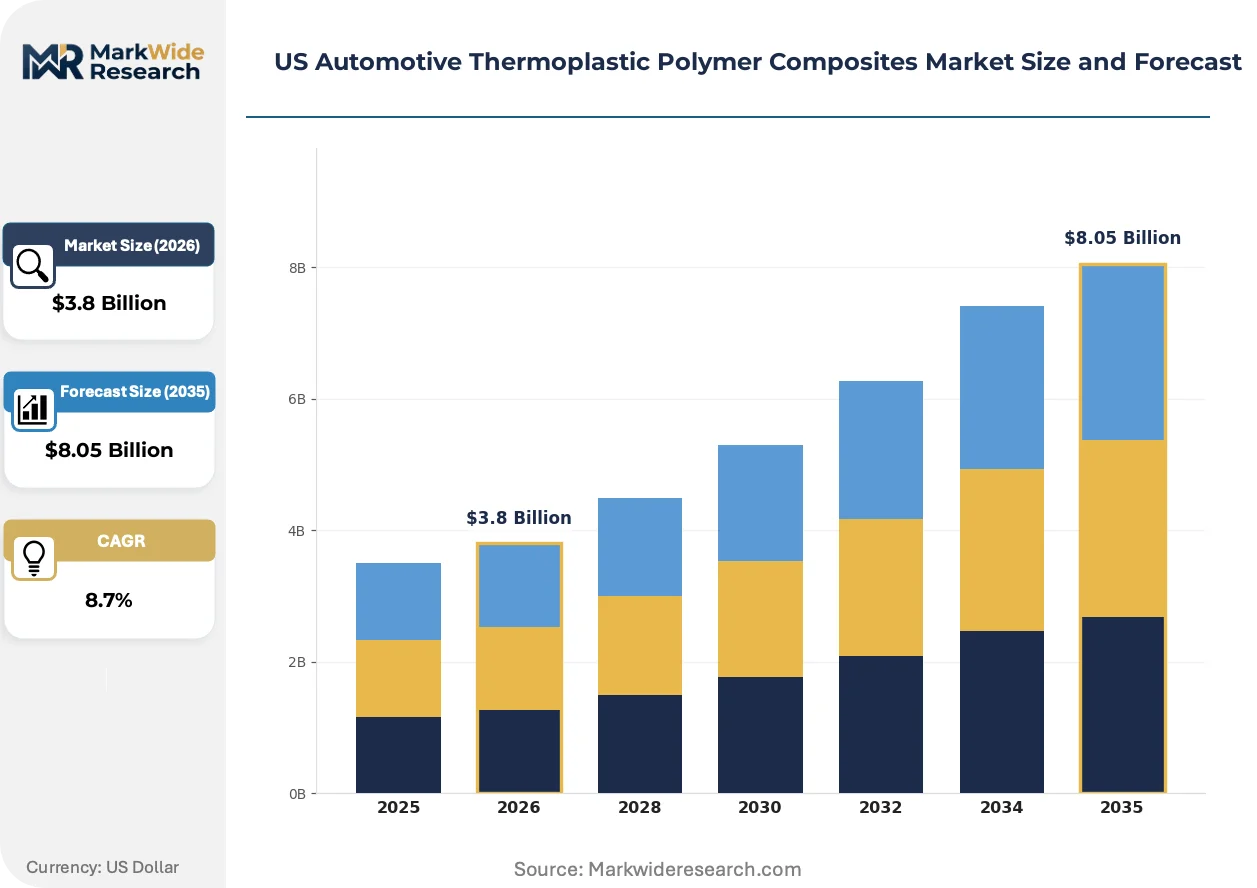
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, Nylon, Acrylonitrile Butadiene Styrene End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Interior Components, Exterior Panels, Structural Parts, Under-the-Hood Applications Technology: Injection Molding, Thermoforming, Compression Molding, 3D Printing |
| Companies Covered | 3B-Fiberglass, Celanese Corporation, BASF, Toray Industries, DuPont de Nemours, Solvay, Gurit, Cytec Industries Inc., Arkema Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Thermoplastic Polymer Composites Market Evolving Landscape
Material-process combinations are compressing development cycles while expanding the performance envelope for structural automotive applications previously reserved for metals or thermosets.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are converging with automated fiber placement to produce tailored blanks for local reinforcement in seat structures and front-end carriers. Tier-1 suppliers in Michigan and Ohio are piloting in-situ consolidation lines that weld unidirectional tapes into complex preforms without secondary processing. This convergence is collapsing the cost gap between stampable thermoplastic composites and aluminum extrusions in chassis subframes.
California Air Resources Board rules now require battery enclosure materials to meet simultaneous flame resistance and electrical isolation criteria under UN 38.3 testing protocols. Compounders are reformulating glass-filled polyamides with halogen-free flame retardants to satisfy these multi-attribute specifications. The passenger EV segment faces the steepest compliance burden, with OEMs pre-qualifying materials two model cycles ahead of production.
Buyer concentration among Detroit Three OEMs has compressed supplier qualification timelines from 36 months to 18 months for secondary structural applications. Tier-2 compounders are bypassing traditional distributor networks to establish direct technical service relationships with platform engineering teams. This channel shift is most pronounced in battery electric vehicle programs, where material selection occurs 24 months earlier in the development cycle than for internal combustion platforms.
US Automotive Thermoplastic Polymer Composites Market Segmentation
Material specification pathways diverge sharply across buyer types in the US automotive thermoplastic polymer composites market. OEM platform engineers prioritize crash certification and thermal management performance, while Tier-1 suppliers optimize for mold cycle efficiency and resin cost stability.
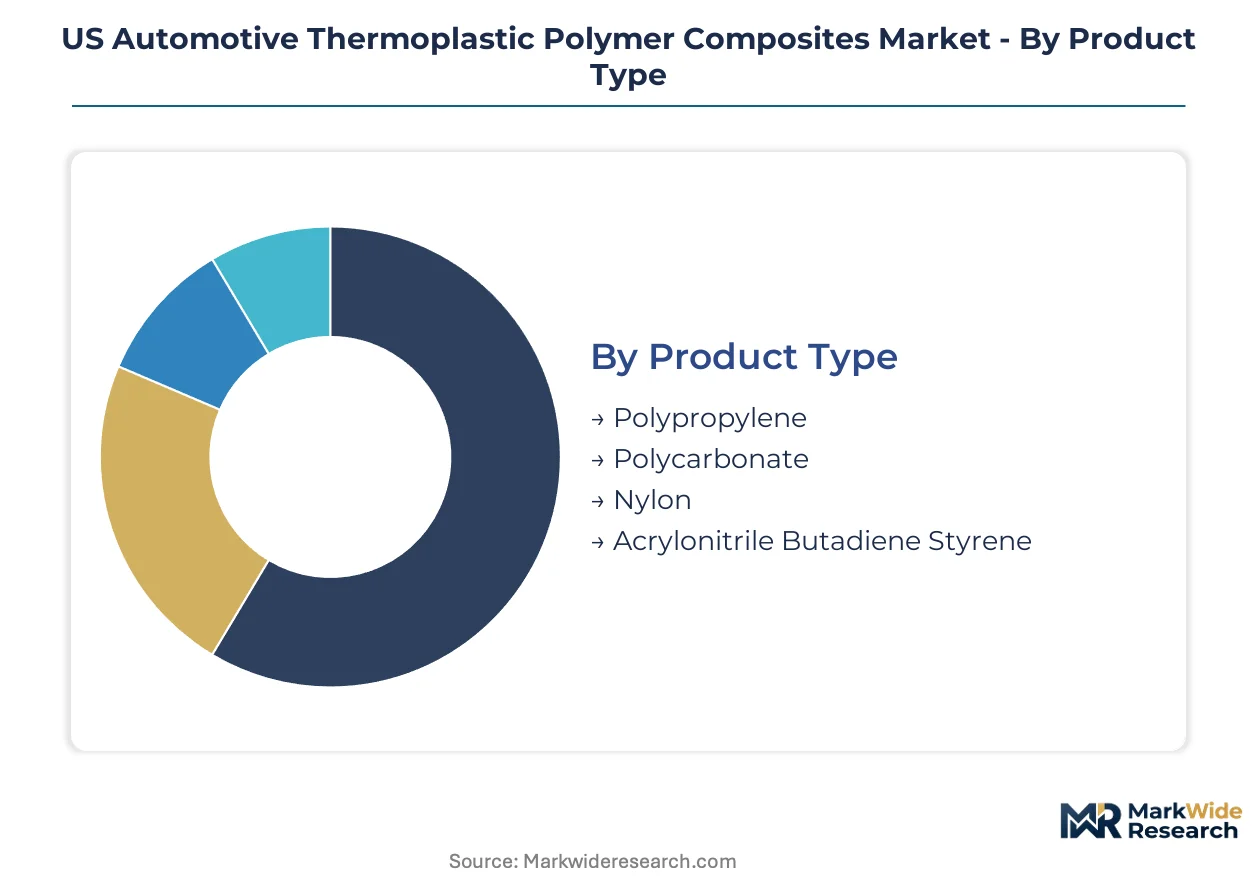
Product Type:
Cost tier separates commodity compounders from engineered resin specialists serving load-bearing applications.
- Polypropylene:Glass-reinforced polypropylene compounds dominate underbody shields and bumper beams due to density advantages and established recycling infrastructure. Michigan-based Tier-1 suppliers specify these grades for high-volume Detroit Three platforms where per-part cost targets sit below aluminum alternatives.
- Nylon:Polyamide 6 and 6,6 formulations with 30-50% glass fiber reinforcement withstand under-the-hood temperatures exceeding 150°C in charge air coolers and engine covers. OEM thermal management teams specify these grades for hybrid and battery electric vehicle programs where heat rejection requirements intensify.
- Polycarbonate:Transparent polycarbonate blends serve interior trim and lighting applications requiring optical clarity and UV stability.
- Acrylonitrile Butadiene Styrene:ABS compounds fill lower-temperature interior fittings where surface aesthetics and paintability matter more than structural load.
Volume sits with polypropylene; growth tilts toward nylon as electrification raises thermal performance thresholds.
End User:
Procurement authority determines specification control and qualification timeline compression.
- OEMs:Detroit Three platform engineering teams hold final material approval authority for structural and safety-critical applications, driving 18-month qualification cycles through direct compounder relationships. Ford, General Motors, and Stellantis maintain captive material databases that lock in resin grades across multiple model years.
- Tier-1 Suppliers:Magna, Lear, and Adient specify compounded resins for seat structures and interior modules, leveraging volume aggregation to negotiate resin pricing. These suppliers operate technical centers within 50 miles of Detroit assembly plants to support just-in-time sequencing.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source through distributor networks with longer lead times and smaller lot sizes.
- Aftermarket Providers:Collision repair and restoration suppliers prioritize material availability over OEM certification, accepting broader specification tolerances.
Decision authority concentrates with OEMs; commercial momentum flows through Tier-1 supplier consolidation.
Application:
Performance requirements escalate from interior aesthetics through structural crash management.
- Under-the-Hood Applications:Battery enclosures, cooling modules, and power electronics housings demand simultaneous flame resistance, electrical isolation, and thermal conductivity. CARB Advanced Clean Cars II rules now mandate UN 38.3 compliance for battery pack materials, forcing reformulation of glass-filled polyamides with halogen-free flame retardants.
- Structural Parts:Front-end carriers, seat frames, and cross-members require stiffness-to-weight ratios above 150 MPa per g/cm³. Compression-molded glass mat thermoplastics achieve 40% mass reduction versus steel stampings in these applications.
- Interior Components:Door panels, instrument carriers, and console structures prioritize surface quality and acoustic dampening over structural load.
- Exterior Panels:Class A surfaces remain thermoset-dominated; thermoplastics penetrate only non-appearance structural skins.
Regulatory pressure clusters in under-the-hood; structural parts offer the steepest expansion trajectory as metal replacement accelerates.
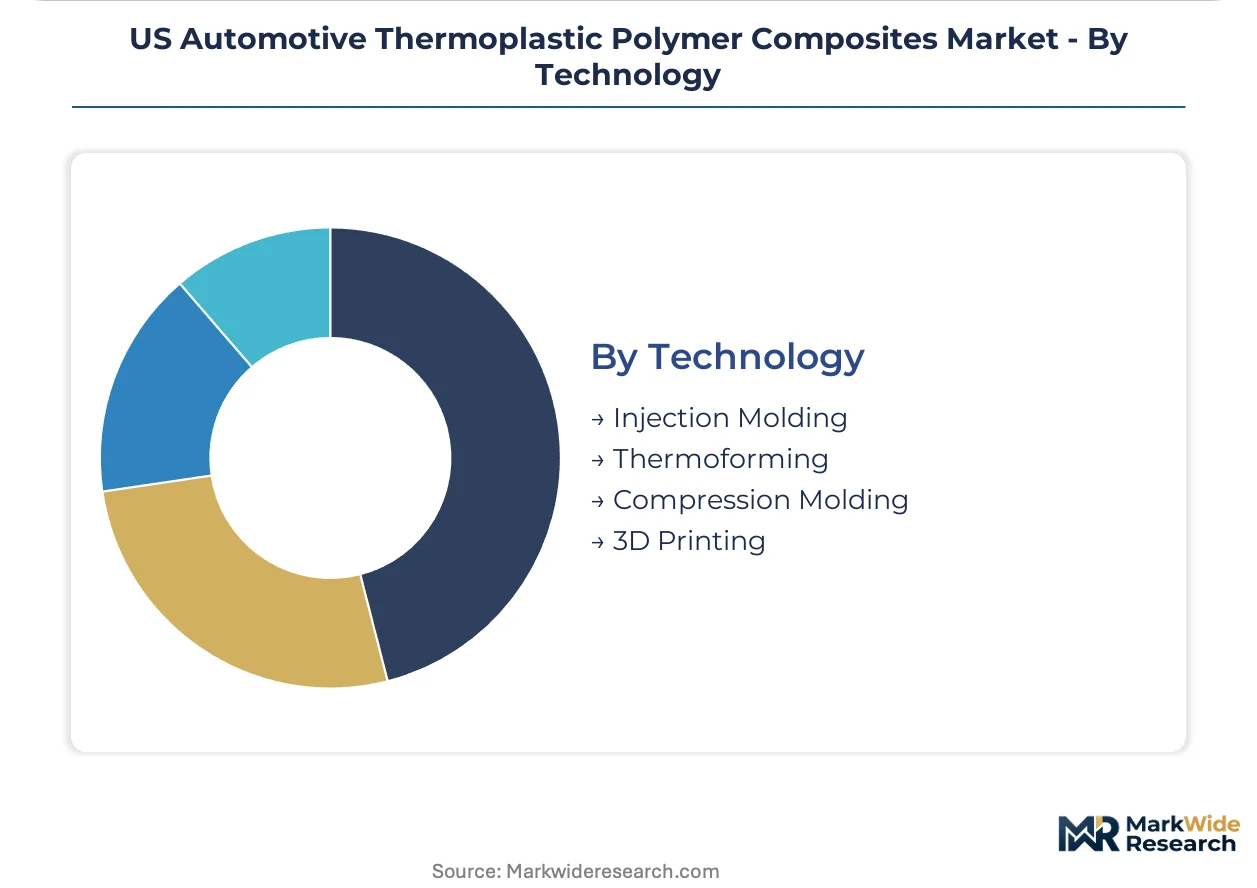
Technology:
Cycle time and capital intensity separate high-volume automotive production from prototyping and repair.
- Injection Molding:High-pressure injection of glass-reinforced compounds dominates Michigan manufacturing corridors, with 60-second cycle times enabling millions of parts annually for Detroit Three platforms. Electric vehicle battery enclosures are forcing mold flow simulation upgrades to predict fiber orientation in complex geometries.
- Compression Molding:Glass mat thermoplastic processing serves mid-volume structural applications like seat backs and load floors where 40% fiber content by weight delivers required stiffness.
- Thermoforming:Heated sheet processing produces large-area interior panels with lower tooling costs than injection molding.
- 3D Printing:Fused filament fabrication and selective laser sintering occupy prototyping and low-volume tooling niches where lead time compression justifies higher unit economics.
Equipment utilization centers on injection molding; capability investment tilts toward compression molding as GMT applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethane crackers along the Texas Gulf Coast supply propylene feedstock that feeds compounders serving southern vehicle assembly plants. Michigan's automotive corridor concentrates Tier-1 supplier technical centers within tight logistics radius of Detroit Three OEM headquarters. California's regulatory mandates propagate into national platform designs through zero-emission vehicle requirements.
Michigan
Detroit Three platform engineering teams specify glass-reinforced polypropylene for underbody shields and structural reinforcements. NHTSA crashworthiness standards drive material qualification cycles that compress timelines for battery electric vehicle programs. Tier-1 suppliers cluster within 50 miles of Flint and Detroit assembly operations to support just-in-time resin delivery.
Texas
New ethane cracker investments near Corpus Christi create feedstock proximity for polypropylene compounders serving southern US vehicle assembly. EPA fuel economy standards pressure OEMs to substitute metal stampings with lightweight composites in structural applications. Resin producers are expanding compounding capacity to capture logistics advantages for Gulf Coast automotive customers.
California
Advanced Clean Cars II rules extend through 2035, mandating UN 38.3 compliance for battery pack materials including thermal runaway barriers. CARB regulations propagate into national platform designs as OEMs consolidate architectures across state lines. Compounders in the state are reformulating glass-filled polyamides with halogen-free flame retardants to satisfy multi-attribute specifications.
Ohio
Compression-molded glass mat thermoplastic processing serves mid-volume structural applications like seat backs and load floors with 40% mass reduction versus steel. NHTSA pedestrian impact testing requirements constrain platform refresh schedules for thermoplastic front-end modules. Technical centers in the state pilot in-situ consolidation lines that weld unidirectional tapes into complex preforms.
South Carolina
BMW and Volvo assembly operations drive specification of carbon-reinforced grades for structural battery enclosures in premium electric vehicle platforms. Limited domestic PAN precursor capacity constrains qualification of continuous fiber-reinforced thermoplastics for these applications. Suppliers in the region are establishing direct technical service relationships with platform engineering teams to compress 18-month qualification timelines.
US Automotive Thermoplastic Polymer Composites Market Competitive Landscape
Global majors compete with regional champions across resin formulation and fiber reinforcement capabilities in the US automotive thermoplastic polymer composites market. The supplier base organizes into three tiers: integrated chemical conglomerates with captive polymerization assets, specialized compounders focused on automotive-qualified grades, and regional fiber suppliers serving specific geographic markets. Dominant competitive moves include backward integration into polyamide polymerization to secure supply security and strategic partnerships with Tier-1 suppliers to compress qualification timelines.
Within the integrated chemical tier, BASF and Celanese Corporation exemplify archetypes of backward-integrated resin producers controlling polymerization through compounding. Among fiber reinforcement specialists, 3B-Fiberglass occupies a position serving glass mat thermoplastic applications. DuPont de Nemours sits within the engineered materials segment with historical strength in polyamide formulations. These three named entities anchor competitive positioning without exhaustive market coverage, as the preliminary list indicates 15–20 companies will populate the final study.
| Leading Market Players |
|---|
| 3B-Fiberglass |
| Celanese Corporation |
| BASF |
| Toray Industries |
| DuPont de Nemours |
| Solvay |
| Gurit |
| Cytec Industries Inc. |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
CARB Advanced Clean Cars II compliance requirements gate qualified supply access and premium-tier pricing power for battery enclosure materials. OEMs pre-qualify halogen-free flame-retardant polyamides two model cycles ahead, locking compounders with certified grades into long-term offtake premiums while excluding uncertified competitors from EV platform procurement.
Pricing Analysis
Warranty-backed technical service bundling separates automotive-qualified compounders from commodity resin suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with OEM direct contracts commanding 15-20 point premiums over distributor channels. Cost compression in glass-reinforced polypropylene intensifies because propylene monomer volatility transfers downstream, squeezing compounder margins during petrochemical disruptions. Tier-2 suppliers serving aftermarket collision repair exhibit highest price sensitivity; OEM platform engineering teams demonstrate lowest sensitivity where crash certification timelines dominate total cost of ownership.
Supply Chain Analysis
Post-industrial regrind flows and closed-loop recyclate qualification create reverse-logistics complexity for Tier-1 suppliers. Feedstock concentration in Texas Gulf Coast ethane crackers and Michigan compounding corridors draws from propylene monomer and glass fiber mat inputs. Single-source vulnerability in domestic PAN precursor capacity constrains continuous carbon-reinforced thermoplastic availability for structural battery enclosures. Distribution runs through just-in-time sequencing networks radiating from Detroit assembly clusters, with 150-mile logistics radius dictating supplier location decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around electrification-driven qualification barriers that eliminate compounders lacking OEM platform engineering relationships. EPA fuel economy standards and CARB zero-emission mandates compress development timelines, forcing capital-constrained regional players toward exit or acquisition.
For Market Incumbents: Anchor captive polyamide polymerization capacity to secure supply security as electrification reshapes material specifications. BASF's backward integration model demonstrates defensibility; Celanese's high-flow formulation expertise protects against emerging Asian compounders. Prioritize direct technical service relationships with Detroit Three platform teams to lock in 18-month qualification cycles before secondary structural applications commoditize. For New Entrants and Emerging Players: The price-point gap between premium OEM-certified grades and economy-tier distributor resins opens white-space in southern US vehicle assembly corridors. Target Texas Gulf Coast resin expansion zones where new ethane cracker proximity reduces logistics disadvantages versus incumbent Michigan clusters. Pursue overmolding metal insert partnerships with Tier-1 suppliers seeking hybrid processing capabilities for crash structures. For Investors and Strategic Acquirers: CARB rule propagation into national platform designs is the leading indicator that battery enclosure material demand will outpace general automotive composite growth. Five-to-ten year viability favors compounders with halogen-free flame retardant formulation capabilities and established UN 38.3 testing relationships. Monitor Tier-2 compounder distress signals as qualification timeline compression and simulation engineer scarcity raise capital intensity beyond regional player capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Polymerization | BASF's captive supply model secures resin availability for Detroit Three OEM programs. |
| Long-term Supply Agreement with Tier-1 Suppliers | Direct technical service relationships compress Magna and Lear qualification timelines. |
| Green Manufacturing Transition to Halogen-free Formulations | CARB UN 38.3 compliance opens battery enclosure procurement to reformulated polyamides. |
| Joint Venture for Continuous Fiber-reinforced Thermoplastic Capacity | South Carolina carbon-reinforced grades address BMW and Volvo structural enclosure demand. |
| Geographic Manufacturing Footprint Expansion to Texas Gulf Coast | Corpus Christi ethane cracker proximity reduces propylene feedstock logistics costs. |
Research Methodology
SEC 10-K filings, EPA regulatory dockets, and IHS Markit vehicle production databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and resin compounder technical directors validated demand assumptions and qualification timeline compression trends. Bottom-up and top-down triangulation reconciled part-level content per vehicle estimates against aggregate resin consumption figures from customs and trade data.
Bottom-up modeling segmented volume and value across the projection horizon by material type, propulsion architecture, and application tier. The analytical framework incorporated vehicle class, content per vehicle, and regional production cluster dimensions to derive CAGRs from platform-level build rate assumptions and material substitution elasticities. NHTSA crash certification timelines and CARB regulatory phase-in schedules served as industry-specific forecast inputs.
Inputs from OEM engineering databases and Tier-1 supplier technical centers were available through the study window; gaps in pre-production battery platform specifications introduce uncertainty bands around electrification-driven demand acceleration. Forecasts reflect assumptions regarding EPA fuel economy standard stringency and domestic PAN precursor capacity expansion. Practitioners should monitor CARB rule propagation velocity and simulation engineer labor market tightness for early signals of qualification timeline disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Vinyl Acetate Homopolymer Market