
 Fluoropolymers in Healthcare Market | 2026-2036
Fluoropolymers in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoropolymers in Healthcare Market Foresight
North American specialty resin producers is repositioning fluoropolymer capacity toward medical-grade certification tiers. The Chemours Company leverages its vertical integration from fluorspar to finished resin to sustain pricing power in implantable-grade polytetrafluoroethylene. Daikin Industries anchors its healthcare portfolio in high-purity perfluoroalkoxy for pharmaceutical fluid handling, while Solvay differentiates through radiation-stable ethylene tetrafluoroethylene formulations for diagnostic imaging equipment.
Fluoropolymers in healthcare comprise a family of carbon-fluorine backbone polymers—principally polytetrafluoroethylene, perfluoroalkoxy, and fluorinated ethylene propylene—engineered for chemical inertness, thermal stability, and low surface energy, with medical grades requiring extractables testing below microgram-per-gram thresholds for blood-contacting applications. Polytetrafluoroethylene dominates current revenue as the established standard for vascular grafts and catheter linings, while perfluoroalkoxy represents the fastest-expanding product category driven by its superior melt-processability in drug delivery system housings. Among applications, implantable components command the deepest margin pools due to multi-year qualification cycles and limited supplier lists, whereas diagnostic equipment coatings are maturing into a price-sensitive segment with commoditized specifications.
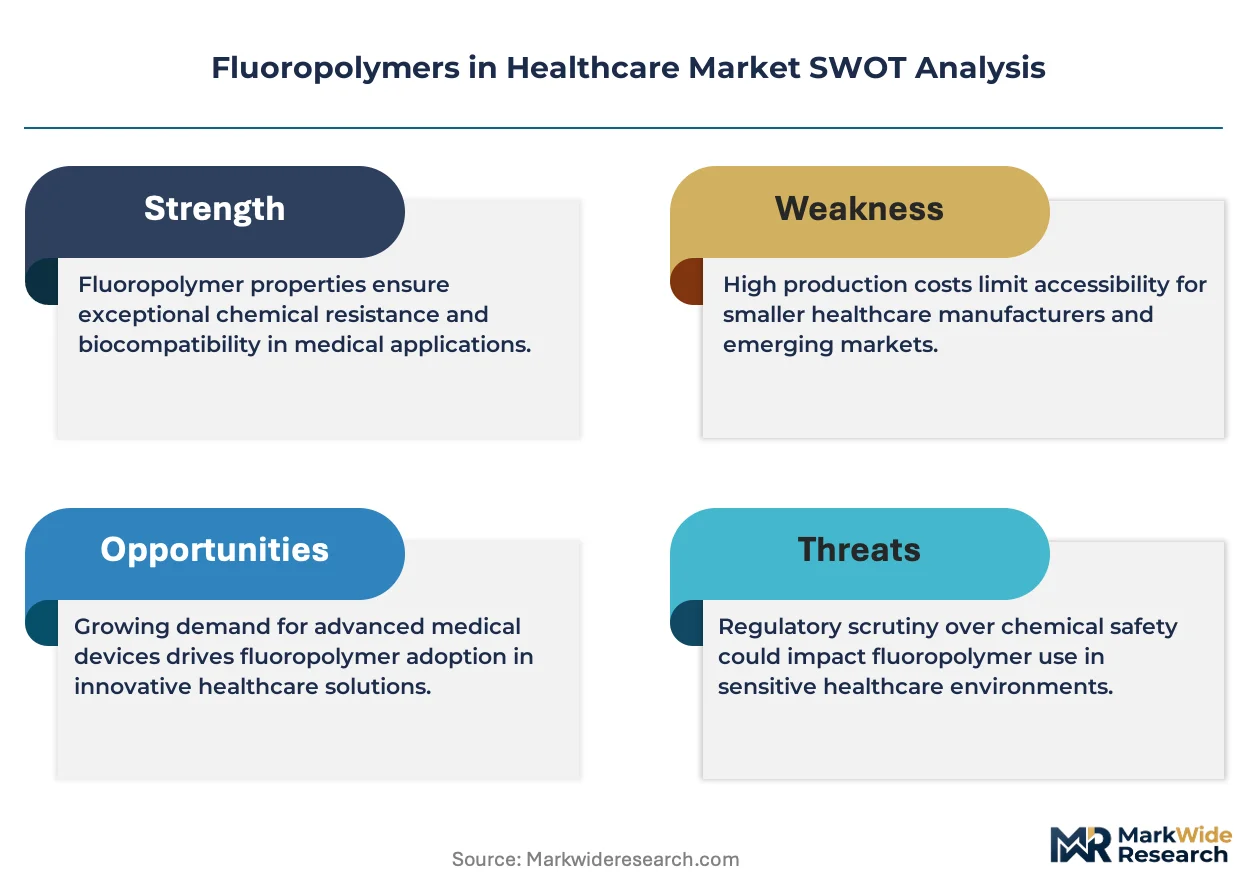
The FDA enforces biocompatibility standards through ISO 10993-1 harmonized guidance, while the EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification for fluoropolymer-containing implants, effectively raising compliance costs for non-European exporters. China's National Medical Products Administration is accelerating local registration requirements for imported fluoropolymer raw materials used in Class III devices, reshaping supply chain geography. Stakeholders must monitor regulatory divergence between FDA breakthrough device pathways and EU MDR clinical evidence expectations when allocating R&D across fluoropolymer product platforms.
Market Dynamics
Medical-grade fluoropolymer supply chains are consolidating around vertically integrated resin producers capable of certifying extractable thresholds below microgram-per-gram limits for permanent implant applications.
Growth Catalysts
- Minimally invasive cardiovascular expansion:Catheter manufacturers in Germany and the United States are expanding fluoropolymer procurement for structural heart procedures requiring lubricious, thromboresistant linings.
- ISO 10993-1 harmonization:The FDA's alignment with international biocompatibility protocols streamlines dual-market approval pathways for implantable-grade polytetrafluoroethylene devices.
- Localized pharmaceutical manufacturing:China's eastern manufacturing corridor is driving demand for high-purity perfluoroalkoxy in single-use fluid handling systems for biologics production.
Market Restraints
- Fluorspar supply concentration:Raw material sourcing depends on concentrated mining operations in Mongolia and China, creating geopolitical exposure for Western resin producers.
- EU MDR clinical evidence burdens:The Medical Device Regulation's post-market surveillance requirements for permanent implants extend qualification timelines and elevate compliance costs for non-European suppliers.
- Silicone substitution in diagnostics:Lower-cost silicone elastomers are displacing fluorinated ethylene propylene in non-critical diagnostic equipment coatings where chemical resistance requirements moderate.
Strategic Opportunities
- Drug delivery system localization:India's PLI scheme for medical devices incentivizes domestic fluoropolymer conversion capacity for insulin pen and inhaler components.
- Radiation-stable formulations:Solvay's ethylene tetrafluoroethylene platforms address unmet demand in diagnostic imaging equipment requiring gamma sterilization compatibility without degradation.
- Point-of-care device miniaturization:Melt-processable perfluoroalkoxy enables complex geometries in portable hemodialysis and continuous glucose monitoring housings.
Industry Challenges
- Extractables validation bottlenecks:Blood-contacting applications require 18-24 month qualification cycles for new resin grades, compressing R&D portfolio flexibility.
- Cross-border registration fragmentation:China's NMPA is accelerating local registration requirements for imported fluoropolymer raw materials in Class III devices, forcing supply chain reconfiguration.
- Specialized polymer processing expertise:Medical-grade fluoropolymer conversion demands precision molding and sintering capabilities scarce outside established healthcare manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoropolymers in Healthcare Market |
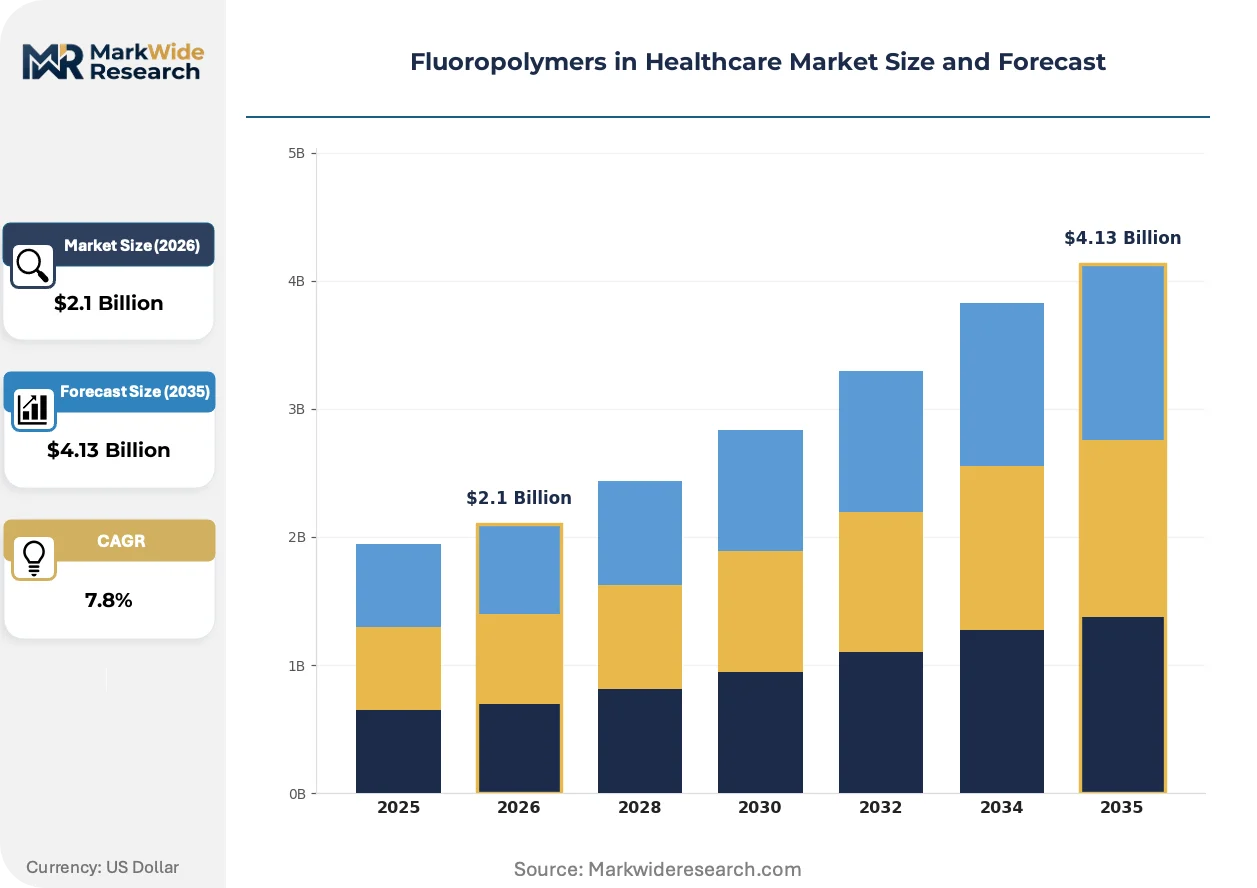
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polytetrafluoroethylene, Fluorinated Ethylene Propylene, Perfluoroalkoxy, Ethylene Tetrafluoroethylene, Fluoroelastomers Application: Medical Devices, Drug Delivery Systems, Diagnostic Equipment, Surgical Instruments, Implantable Components End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Pharmaceutical Manufacturers, Medical Device Companies Delivery Mode: Injection Molding, Extrusion, Film Manufacturing, Coating Processes, Additive Manufacturing |
| Companies Covered | The Chemours Company, Daikin Industries Ltd., Solvay S.A., 3M Company, AGC Inc., W.L. Gore & Associates, Arkema S.A., Saint-Gobain, Zeus Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoropolymers in Healthcare Market Shifts & Advancements
Additive manufacturing of patient-specific implants is disrupting traditional fluoropolymer component sourcing, while regulatory convergence and procurement centralization are compressing supplier qualification cycles.
High-temperature sintering of porous polytetrafluoroethylene for vascular grafts is decentralizing production from centralized resin converters to hospital-adjacent cleanroom facilities. Cardiovascular device manufacturers in the United States and Germany are piloting point-of-care graft fabrication using certified resin feedstock. This distributed manufacturing model is compressing logistics costs and enabling same-day customization for complex anatomies.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon production is constraining feedstock availability for fluoropolymer resin manufacturing in Europe. German and Belgian chemical producers are redirecting capacity toward medical-grade certification tiers to preserve margin pools amid volume restrictions. Implantable device manufacturers are dual-qualifying Asian resin sources to mitigate supply continuity risks from European regulatory compression.
Consolidated procurement by multinational hospital systems is displacing distributor-mediated sourcing for fluoropolymer-containing devices. IDN-based contracting in the United States now captures 60% of catheter and graft purchasing decisions, compressing price negotiation cycles. This concentration is visible most acutely in cardiovascular service line agreements where standardization incentives override legacy supplier relationships.
Fluoropolymers in Healthcare Market Segmentation
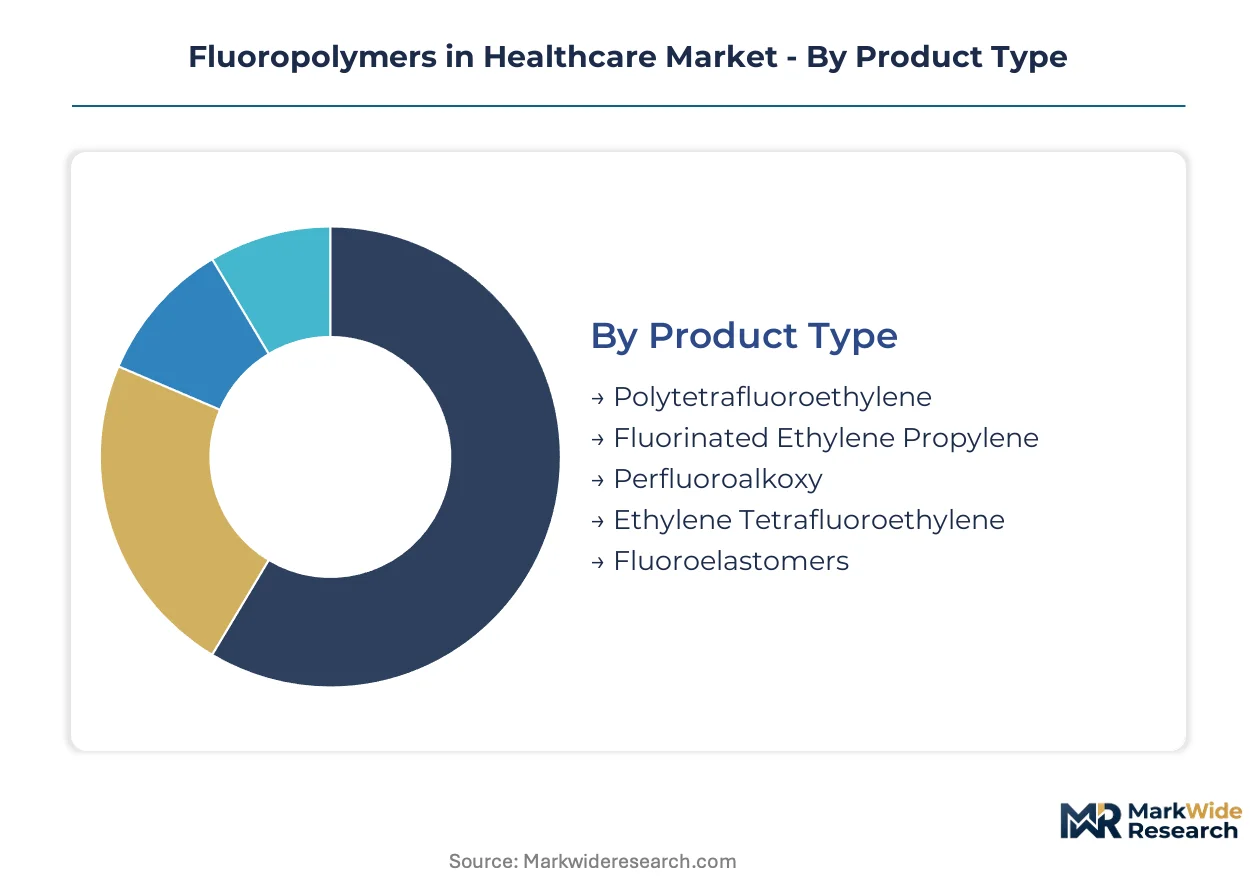
Fluoropolymer procurement decisions in healthcare diverge sharply across product grades, with implantable applications demanding multi-year qualification cycles while diagnostic segments prioritize cost efficiency. Understanding these segment-specific requirements enables suppliers to align certification investments with margin capture potential.
Product Type:
Buyers differentiate primarily by biocompatibility certification tier and melt-processability requirements for specific device geometries.
- Polytetrafluoroethylene:Carbon-fluorine backbone polymer with exceptional chemical inertness and low coefficient of friction, serving as the established standard for vascular grafts and catheter linings. Demand concentrates with cardiovascular device manufacturers in Germany and the United States seeking thromboresistant surfaces for structural heart procedures.
- Perfluoroalkoxy:Semi-crystalline fluoropolymer offering superior melt-flow characteristics for complex injection molding. Pharmaceutical fluid handling systems in China's eastern manufacturing corridor drive procurement volumes for single-use bioprocessing components.
- Fluorinated Ethylene Propylene:Copolymer with lower processing temperatures than PTFE, enabling cost-effective extrusion for diagnostic tubing.
- Ethylene Tetrafluoroethylene:Radiation-stable formulation preferred for diagnostic imaging equipment housings requiring gamma sterilization compatibility.
- Fluoroelastomers:Cross-linked fluorinated polymers providing elastic sealing properties for medical device gaskets and O-rings.
Volume sits with polytetrafluoroethylene; growth tilts toward perfluoroalkoxy.
Application:
Application selection determines regulatory pathway complexity and supplier qualification duration.
- Implantable Components:Permanent blood-contacting devices including vascular grafts and stent coatings requiring ISO 10993-1 compliant extractables testing below microgram-per-gram thresholds. Extended qualification cycles limit supplier lists to vertically integrated resin producers.
- Medical Devices:Catheters, guidewires, and minimally invasive instruments utilizing fluoropolymer linings for lubricity. German and US manufacturers are expanding procurement for structural heart procedures.
- Drug Delivery Systems:Insulin pens, inhaler housings, and implantable pumps leveraging melt-processable grades for complex geometries.
- Diagnostic Equipment:Imaging device components and laboratory instrumentation coatings where silicone elastomers increasingly compete on cost.
- Surgical Instruments:Electrosurgical tools and laparoscopic devices requiring electrical insulation and sterilization resistance.
Implantable components command the deepest margin pools; diagnostic equipment coatings are commoditizing fastest.
End User:
End user scale and purchasing concentration reshape fluoropolymer sourcing relationships.
- Medical Device Companies:Original equipment manufacturers designing fluoropolymer into catheter, graft, and delivery system platforms. IDN-based contracting in the United States now captures the majority of cardiovascular purchasing decisions.
- Pharmaceutical Manufacturers:Biologics producers in China and India sourcing high-purity fluid handling systems for single-use manufacturing.
- Hospitals:Acute care facilities procuring finished devices through consolidated service line agreements.
- Diagnostic Laboratories:Clinical and research labs purchasing analytical equipment with fluoropolymer fluid pathways.
- Ambulatory Surgical Centers:Outpatient facilities selecting cost-optimized devices with standardized specifications.
Procurement leverage concentrates with medical device companies; pharmaceutical manufacturers are localizing fastest.
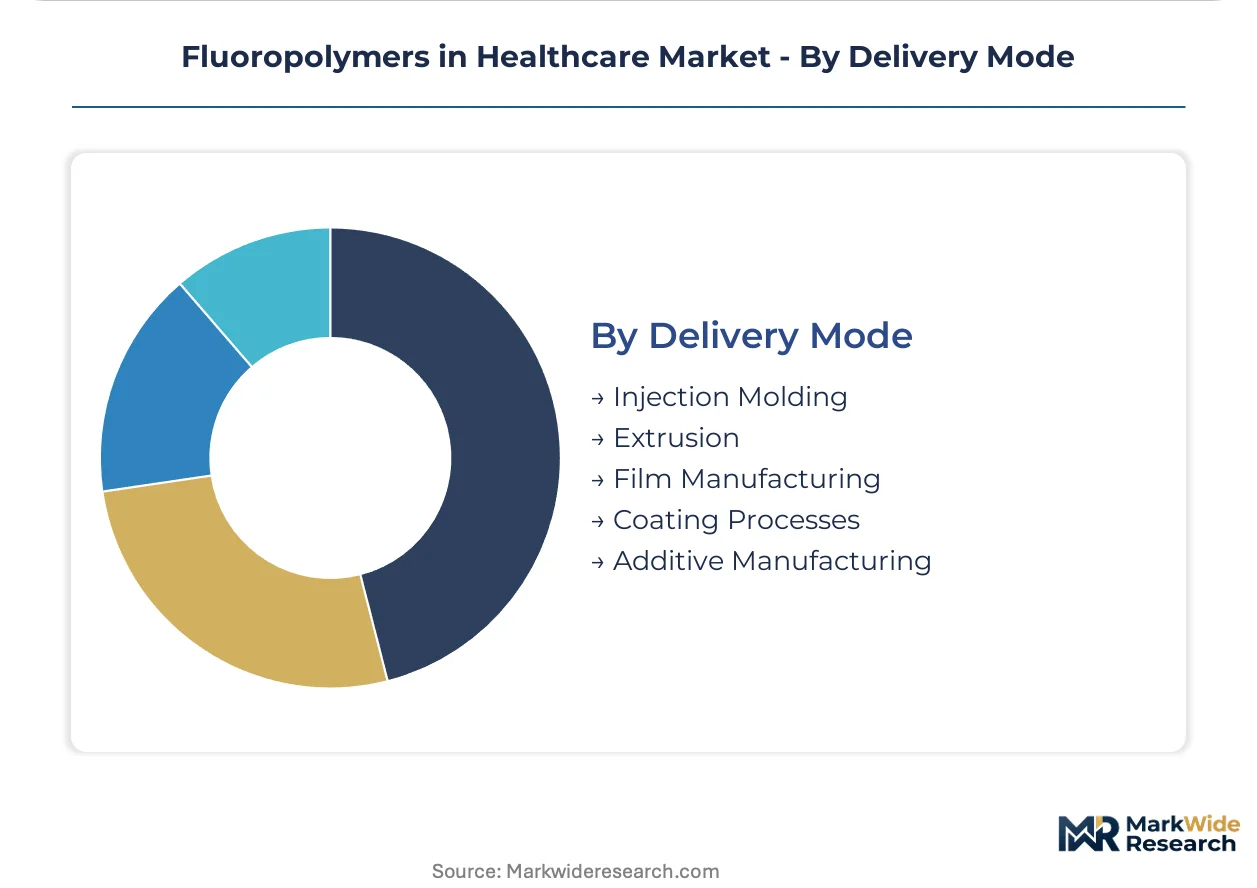
Delivery Mode:
Processing technology selection constrains achievable geometries and surface specifications.
- Extrusion:Continuous profile manufacturing for catheter shafts and tubing requiring tight dimensional tolerances.
- Injection Molding:High-volume production of drug delivery housings and surgical instrument handles.
- Film Manufacturing:Thin-gauge sheeting for barrier membranes and packaging applications.
- Coating Processes:Surface deposition techniques for thromboresistant linings on metal substrates.
- Additive Manufacturing:Emerging point-of-care fabrication of patient-specific vascular grafts from certified resin feedstock.
Extrusion dominates current volume; additive manufacturing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mongolia and China's concentrated fluorspar mining operations anchor raw material security for fluoropolymer resin production, while finished medical-grade material conversion clusters in Germany, the United States, China, and Japan.
United States
Catheter manufacturers in Minnesota and Massachusetts are expanding fluoropolymer procurement for structural heart procedures requiring thromboresistant linings. The FDA's ISO 10993-1 harmonization streamlines biocompatibility testing for implantable-grade polytetrafluoroethylene devices. The Twin Cities medical device corridor concentrates precision molding capabilities for vascular graft fabrication.
Germany
Cardiovascular device producers in Baden-Württemberg and Bavaria are piloting point-of-care graft fabrication from certified resin feedstock. The EU F-Gas Regulation's hydrofluorocarbon phase-down is constraining domestic feedstock availability and redirecting capacity toward medical-grade certification tiers. The Stuttgart industrial cluster hosts specialized sintering operations for porous polytetrafluoroethylene vascular applications.
China
Domestic medical device producers in the Yangtze River Delta are localizing fluoropolymer sourcing for Class III implantable devices. The National Medical Products Administration is accelerating local registration requirements for imported raw materials, forcing supply chain reconfiguration. Shanghai and Suzhou manufacturing corridors drive procurement volumes for high-purity perfluoroalkoxy in single-use bioprocessing systems.
Japan
Pharmaceutical fluid handling system manufacturers in Osaka and Tokyo are sourcing radiation-stable formulations for gamma sterilization compatibility. The Ministry of Economy, Trade and Industry supports domestic resin certification for blood-contacting applications. The Kansai region concentrates precision extrusion capabilities for diagnostic tubing with tight dimensional tolerances.
India
Medical device producers in Maharashtra and Gujarat are leveraging the PLI scheme to build domestic fluoropolymer conversion capacity for insulin pen and inhaler components. The Central Drugs Standard Control Organization is tightening import substitution incentives for critical raw materials. The Mumbai-Pune industrial belt attracts investment in melt-processable grade fabrication for drug delivery housings.
Fluoropolymers in Healthcare Market Competitive Landscape
Global majors compete with regional champions across certification tiers and geographic proximity to device manufacturing clusters. The market structures around vertically integrated resin producers capable of certifying extractable thresholds below microgram-per-gram limits for permanent implant applications. Three archetypes dominate: fluorspar-to-resin integrators controlling upstream feedstock, specialty compounders focusing on medical-grade purity tiers, and precision converters with hospital-adjacent cleanroom capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress supplier lists.
Among North American resin producers, The Chemours Company exemplifies the integrated archetype with captive fluorspar sourcing. Daikin Industries occupies a position among Asia-Pacific compounders emphasizing high-purity grades for pharmaceutical applications. Solvay S.A. anchors the European specialist tier with radiation-stable formulation capabilities.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries Ltd. |
| Solvay S.A. |
| 3M Company |
| AGC Inc. |
| W.L. Gore & Associates |
| Arkema S.A. |
| Saint-Gobain |
| Zeus Industrial Products |
| Others |
Supply & Pricing Matrix
Captive fluorspar-to-resin integration anchors both supply security and pricing power for Western producers serving implantable-grade fluoropolymer tiers, while Asian compounders compete on pharmaceutical-grade purity without upstream mineral control.
Pricing Analysis
Extended extractables validation warranties separate premium implantable-grade polytetrafluoroethylene from unbundled diagnostic-grade fluorinated ethylene propylene. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993-1 certification depth, with vertically integrated producers commanding sustainable premiums. Cost compression in diagnostic equipment coatings intensifies as silicone elastomers displace fluoropolymers in non-critical applications. Pharmaceutical manufacturers exhibit lowest price sensitivity due to single-use system purity requirements, whereas ambulatory surgical centers prioritize economy-tier standardization.
Supply Chain Analysis
Medical-grade certification gating restricts qualified resin sources to producers with demonstrated microgram-per-gram extractables control. Raw material sourcing draws from concentrated fluorspar mining in Mongolia and China, with finished conversion clustering in Germany, the United States, and Japan. Feedstock availability hinges on geopolitical exposure from concentrated mining operations and EU F-Gas Regulation phase-down constraints. Distribution runs through vertically integrated resin producers directly to medical device OEMs, bypassing distributor intermediation for implantable applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluoropolymer healthcare market is becoming a vertical-integration race as players pursue captive fluorspar sourcing to defend margin pools against regulatory-driven feedstock constraints.
For Market Incumbents: Deepen backward integration into fluorspar mining or offtake agreements to secure feedstock continuity amid EU F-Gas phase-down and Chinese export licensing shifts. Expand medical-grade sintering capacity in hospital-adjacent cleanroom clusters to capture point-of-care graft fabrication demand. Lock in multi-year qualification cycles with cardiovascular OEMs before Asian resin producers achieve implantable-grade certification parity.
For New Entrants and Emerging Players: Contract manufacturers with idle precision molding capacity offer the fastest channel to qualified production without capital-intensive resin certification. Target India's PLI-subsidized medical device corridors for insulin pen and inhaler component conversion, where melt-processable perfluoroalkoxy demand outpaces domestic supply. Pursue pharmaceutical fluid handling partnerships in China's eastern manufacturing corridor as localization mandates displace imported raw materials.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialty compounders with validated pharmaceutical-grade purity tiers and regional proximity to device manufacturing clusters. Five-to-ten year viability favors producers with demonstrated regulatory navigation across FDA, EU MDR, and NMPA frameworks. Watch for NMPA local registration enforcement as the inflection signal triggering supply chain reconfiguration and acquisition premiums for China-qualified assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar | Chemours' captive mineral sourcing insulates implantable-grade PTFE margins from EU F-Gas feedstock constraints. |
| Medical-Grade Sintering Expansion | Hospital-adjacent cleanroom capacity captures cardiovascular OEM demand for point-of-care graft customization. |
| Pharmaceutical Purity Certification | Daikin's high-purity PFA positioning secures bioprocessing system contracts in China's Yangtze River Delta. |
| Radiation-Stable Formulation Development | Solvay's ETFE platforms address diagnostic imaging OEM requirements for gamma sterilization compatibility. |
| Dual-Qualification with Asian Resin Sources | Implantable device manufacturers mitigate EU regulatory compression risks through supply chain diversification. |
Research Methodology
Multi-period observation of catheter procurement volumes, regulatory submission timelines, and resin certification milestones anchored the trend analysis, supplemented by interviews with biomedical engineers at cardiovascular device manufacturers, procurement leads at hospital systems, technical directors at specialty resin compounders, and regulatory affairs specialists navigating FDA and EU MDR pathways. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, SEC 10-K resin segment disclosures, and trade flow data. Bottom-up volume modeling triangulated against top-down market sizing across product grades and application tiers.
Segment-weighting approaches distributed value estimates across implantable components, medical devices, drug delivery systems, diagnostic equipment, and surgical instruments, with further stratification by polytetrafluoroethylene, perfluoroalkoxy, fluorinated ethylene propylene, ethylene tetrafluoroethylene, and fluoroelastomer product types. CAGRs were derived from regression analysis of historical procurement patterns and projected qualification cycle compression. Forecast inputs incorporated EU F-Gas phase-down trajectories, NMPA localization enforcement timelines, and minimally invasive cardiovascular procedure expansion rates.
Caveats apply where fluorspar supply disruptions, accelerated NMPA registration mandates, or silicone substitution breakthroughs in diagnostic applications could materially shift the outlook. A model refresh is warranted upon material change in regulatory divergence between FDA breakthrough device pathways and EU MDR clinical evidence expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
PEKK Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Polymer Resin Market