
 Global Acetabular Prostheses Market | 2026-2036
Global Acetabular Prostheses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acetabular Prostheses Market Foresight
A capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in acetabular prostheses. Zimmer Biomet leverages captive forging capacity for titanium alloy cups across multiple continents. Stryker anchors its position through proprietary porous coating technology for cementless fixation. Medacta International specializes in patient-matched instrumentation that reduces operative variability.
Acetabular prostheses are hemispherical implants that replace the damaged hip socket, typically manufactured from titanium alloys, cobalt chromium, or ceramic composites with porous surface architectures designed for osseointegration or cemented mechanical fixation. Cementless prostheses now command the dominant share of revision-resistant primary procedures, while dual mobility cups represent the fastest-growing category due to their dislocation resistance in active patient cohorts. Ceramic-on-polyethylene material pairings concentrate margin pools where wear debris reduction justifies premium positioning.
FDA premarket notification requirements under 510(k) and EMA Medical Device Regulation (MDR) compliance frameworks govern biocompatibility validation and clinical evidence thresholds for market access. ISO 5832 material standards and ASTM F2077 testing protocols define the mechanical property benchmarks that differentiate qualified suppliers from marginal entrants. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA orthopedic panel guidance updates that could reshape approval timelines and competitive positioning.
Market Dynamics
Cementless fixation architectures are consolidating procurement standards across hip arthroplasty networks, compressing qualification timelines for porous-coated titanium suppliers while elevating biocompatibility documentation burdens under FDA and EMA frameworks.
Growth Catalysts
- EMA MDR Article 10 compliance:Harmonized clinical evidence requirements are streamlining cross-border market access for qualified manufacturers with established notified body relationships.
- Active patient cohorts:Younger recipients demanding higher activity tolerances are pulling dual mobility cup configurations into primary procedure protocols.
- Osseointegration surface engineering:Plasma-sprayed titanium and trabecular metal architectures are expanding cementless adoption in revision-resistant applications.
Market Restraints
- Cobalt chromium feedstock volatility:Mining concentration in the Democratic Republic of Congo and South Africa exposes alloy pricing to geopolitical supply interruptions.
- Notified body capacity bottlenecks: EMA MDR designation backlogs are extending technical file review timelines for mid-tier manufacturers without legacy CE certificates.
- Ceramic fracture risk:Brittle failure modes in third-generation alumina components constrain expansion into high-impact patient segments.
Strategic Opportunities
- India's orthopedic infrastructure:Government medical device parks and CDSCO fast-track pathways are attracting contract manufacturers seeking cost-advantaged export bases.
- AI-assisted preoperative planning:Integration of machine learning with patient-matched instrumentation is reducing cup positioning variability in complex anatomies.
- Japan's super-aged society:METI reimbursement incentives for minimally invasive approaches are opening channels for compact instrument sets in regional hospitals.
Industry Challenges
- Polyethylene sterilization validation:Cross-linked UHMWPE oxidation resistance testing demands extended aging studies that compress R&D cycle efficiency.
- ISO 5832-3 metallurgical certification:Cobalt chromium molybdenum casting porosity standards require capital-intensive vacuum investment casting upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acetabular Prostheses Market |
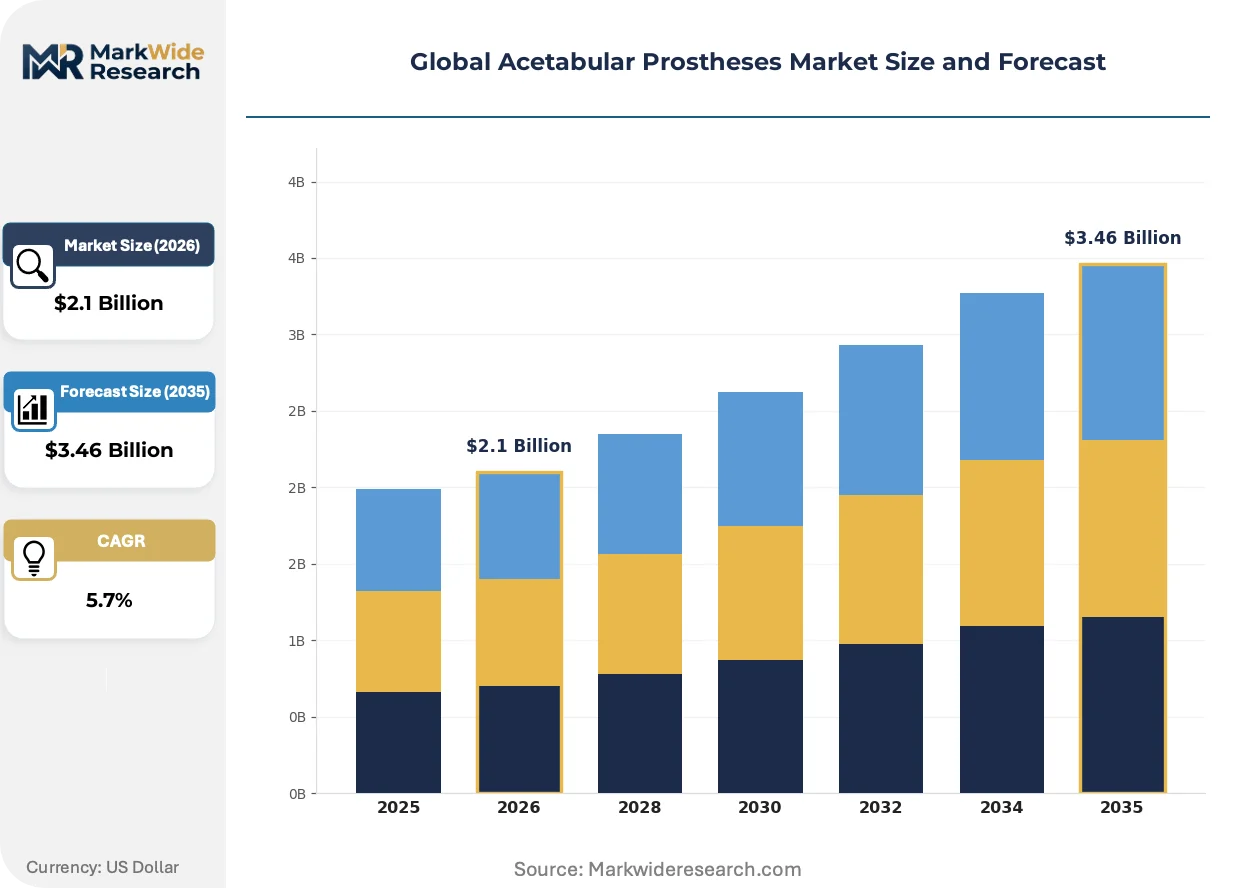
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.46 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented Prostheses, Cementless Prostheses, Hybrid Prostheses, Dual Mobility Cups Material: Titanium Alloys, Cobalt Chromium, Polyethylene, Ceramic, Stainless Steel Application: Osteoarthritis Treatment, Rheumatoid Arthritis, Hip Fracture Repair, Avascular Necrosis End User: Orthopedic Clinics, Ambulatory Surgery Centers, Specialty Hospitals, Rehabilitation Centers |
| Companies Covered | Zimmer Biomet, Stryker, DePuy Synthes, Smith & Nephew, Aesculap, Exactech, Medacta International, Corin, Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acetabular Prostheses Market Shifts & Advancements
Digital manufacturing and surface engineering are compressing development cycles while regulatory data requirements expand, creating asymmetric advantages for manufacturers with integrated metrology and clinical evidence generation capabilities.
Patient-matched 3D-printed acetabular implants with integrated trabecular architectures are miniaturizing operative footprints in complex revision cases. Academic medical centers in Germany and Japan are adopting these configurations for Paprosky type III defects. The technology is miniaturizing conventional reaming requirements and reducing operative time in pelvic discontinuity reconstructions.
FDA's 510(k) Third Party Review Program expansion is compressing clearance timelines for well-established titanium alloy predicate devices. The industrial consequence accelerates competitive entry for manufacturers with existing biocompatibility dossiers. Porous-coated cups with ASTM F2077 fatigue validation are capturing disproportionate review resource allocation.
Hospital buying consortiums are consolidating vendor panels around single-source instrumentation platforms that reduce sterilization burden and tray complexity. Integrated delivery networks in the United States are displacing independent distributors with direct manufacturer contracts. This concentration is most visible in Medicare Advantage-covered procedures where episode-of-care cost accountability drives standardization.
Global Acetabular Prostheses Market Segmentation
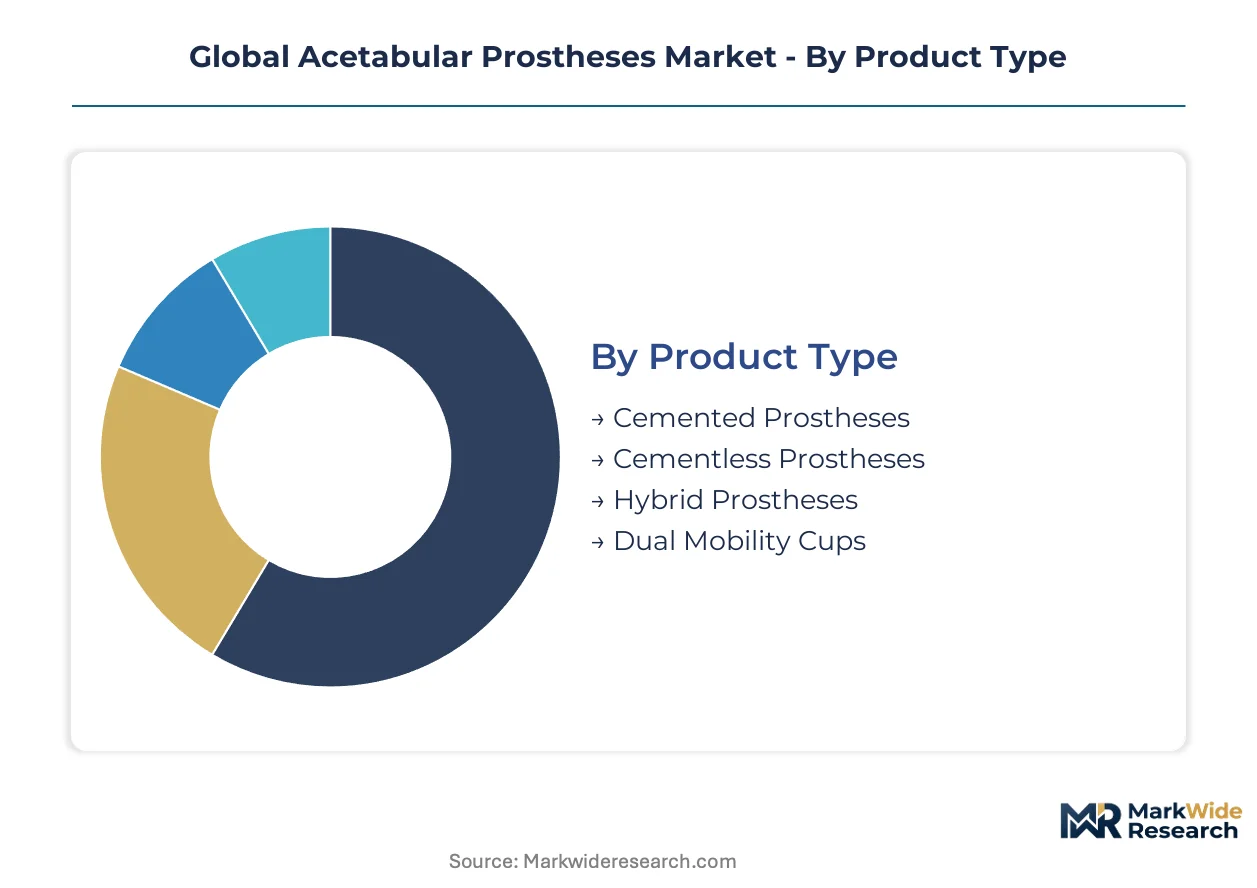
Segmentation in acetabular prostheses reveals how procurement decisions bifurcate between revision-resistant premium configurations and cost-optimized standard protocols. Manufacturers align R&D portfolios to these divergent margin architectures while navigating tightening biocompatibility documentation requirements.
Product Type:
Premium fixation technologies capture disproportionate margin pools where osseointegration performance justifies reimbursement premiums.
- Cementless Prostheses:Porous-coated titanium and trabecular metal surfaces enable biological fixation without bone cement. Demand concentrates in the United States and Germany where younger patient cohorts and revision-resistant protocols dominate hip arthroplasty networks.
- Dual Mobility Cups:Articulating liners with large-diameter femoral heads deliver superior dislocation resistance. Japanese orthopedic clinics are pulling these configurations into primary procedures for active elderly patients under METI reimbursement incentives.
- Cemented Prostheses:Polymethylmethacrylate fixation remains prevalent in femoral neck fracture repair among octogenarians.
- Hybrid Prostheses:Combines cementless acetabular cups with cemented femoral stems in select revision scenarios.
The dominant share belongs to cementless prostheses, while dual mobility cups are expanding most quickly.
Material:
Material selection tracks directly to wear debris profiles and the litigation risk calculus surrounding revision surgery.
- Titanium Alloys:Ti-6Al-4V ELI and commercially pure titanium dominate porous-coated cup substrates. German manufacturers leverage captive forging capacity to supply ASTM F136-compliant forgings across European hospital networks.
- Ceramic:Alumina and zirconia-toughened alumina deliver minimal wear debris in polyethylene pairings. Japanese regulators at PMDA scrutinize third-generation ceramic fracture databases before approving new component geometries.
- Cobalt Chromium:Cast and wrought alloys persist in femoral head applications despite feedstock volatility from Congolese mining concentration.
- Polyethylene:Cross-linked UHMWPE liners dominate articulating surfaces with vitamin E stabilization gaining traction.
- Stainless Steel:316LVM retains niche usage in constrained revision constructs where cost sensitivity overrides performance optimization.
Titanium alloys command the largest installed base, though ceramic is climbing the fastest on wear debris reduction protocols.
Application:
Procedure volume distribution reflects demographic aging patterns and the penetration of hip preservation alternatives.
- Osteoarthritis Treatment:Degenerative joint disease drives the overwhelming majority of primary total hip arthroplasty. United States Medicare Advantage networks are consolidating vendor panels around standardized osteoarthritis pathways with episode-of-care accountability.
- Hip Fracture Repair:Trauma indications demand expedited surgical protocols with higher cemented fixation rates. Indian government medical device parks are attracting contract manufacturers targeting cost-sensitive fracture repair instrumentation.
- Rheumatoid Arthritis:Inflammatory arthropathy patients require specialized bearing surfaces given systemic bone quality compromise.
- Avascular Necrosis:Younger patient demographics in this segment pull toward durable ceramic-on-ceramic or ceramic-on-polyethylene pairings.
Osteoarthritis treatment holds the dominant share, while hip fracture repair is gaining share fastest on aging population trajectories.
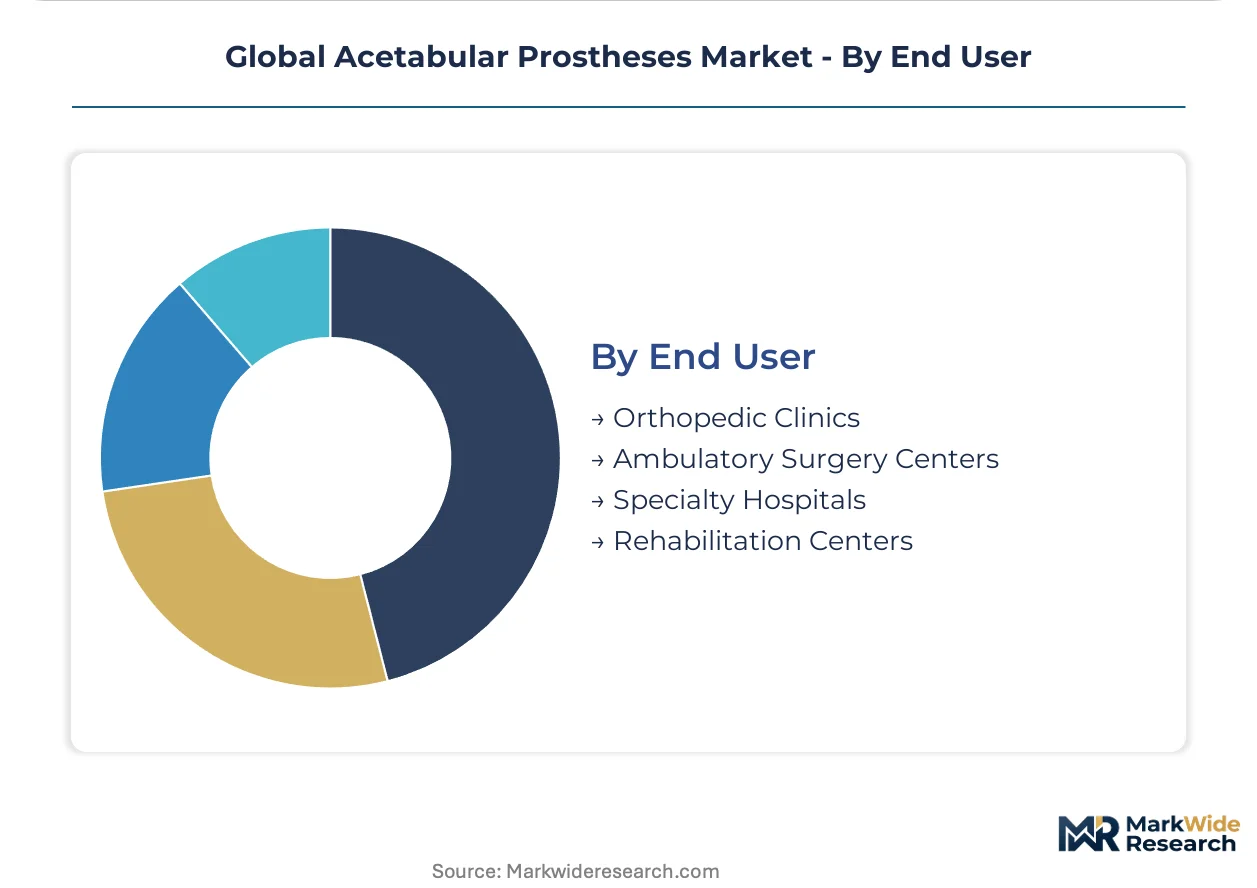
End User:
Site-of-service economics are restructuring purchasing authority away from independent surgeons toward institutional procurement.
- Orthopedic Clinics:Dedicated arthroplasty centers concentrate surgical volume and instrumentation standardization. German outpatient clinics are adopting patient-matched 3D-printed implants for complex Paprosky type III defects.
- Ambulatory Surgery Centers:Same-day discharge protocols demand compact instrument sets and streamlined sterilization workflows. United States ASC networks are displacing independent distributors with direct manufacturer contracts.
- Specialty Hospitals:Academic medical centers generate clinical evidence and train on emerging fixation technologies.
- Rehabilitation Centers:Post-acute facilities influence component selection through readmission risk feedback to referring surgeons.
Orthopedic clinics retain the dominant share, though ambulatory surgery centers are expanding most quickly on site-of-service payment differentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in acetabular prostheses track surgical infrastructure maturity and regulatory reciprocity agreements. Germany and the United States maintain trade surpluses in porous-coated titanium components, while India and China scale contract manufacturing for cost-optimized standard cups.
United States
Medicare Advantage episode-of-care accountability is consolidating vendor panels around standardized instrumentation platforms. FDA's 510(k) Third Party Review Program compresses clearance timelines for established titanium alloy predicates. Integrated delivery networks in the Midwest and Southeast are displacing independent distributors with direct manufacturer contracts.
Germany
Outpatient orthopedic clinics concentrate surgical volume and drive procurement standardization across cementless fixation protocols. EMA MDR Article 10 harmonized requirements streamline cross-border market access for qualified manufacturers with established notified body relationships. Academic medical centers in Bavaria and North Rhine-Westphalia adopt patient-matched 3D-printed implants for complex Paprosky type III defects.
Japan
METI reimbursement incentives for minimally invasive approaches pull dual mobility cup configurations into primary procedures for active elderly patients. PMDA scrutinizes third-generation ceramic fracture databases before approving new component geometries. The Kansai and Kanto regions deepen hip arthroplasty infrastructure with compact instrument sets in regional hospitals.
India
Government medical device parks and CDSCO fast-track pathways attract contract manufacturers seeking cost-advantaged export bases for standard cemented prostheses. Government hospitals in Maharashtra and Gujarat drive volume in femoral neck fracture repair among aging populations. Domestic production scales for hip fracture instrumentation targeting price-sensitive public procurement.
Switzerland
Swissmedic oversight of biocompatibility documentation elevates qualification barriers for marginal entrants while rewarding established suppliers with premium positioning. The Basel and Zurich clusters concentrate precision forging capacity for ASTM F136-compliant titanium substrates. Academic-industry partnerships advance surface engineering for osseointegration performance.
Global Acetabular Prostheses Market Competitive Landscape
Concentration sits with diversified orthopedic conglomerates possessing captive metallurgical capacity and proprietary porous coating technologies. The vendor base organizes around three strategic archetypes: integrated manufacturers with multi-continental forging operations, technology licensors specializing in patient-matched instrumentation, and contract assemblers serving cost-optimized procurement channels. Competitive moves center on M&A for surface engineering capabilities and strategic partnerships with academic medical centers for clinical evidence generation.
Within the integrated-manufacturer tier, Zimmer Biomet and Stryker exemplify archetypes defined by metallurgical control and coating differentiation respectively. Medacta International occupies a position representing patient-matched instrumentation specialization. These three entities anchor competitive dynamics across premium fixation segments where biocompatibility dossiers and notified body relationships determine market access velocity.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| DePuy Synthes |
| Smith & Nephew |
| Aesculap |
| Exactech |
| Medacta International |
| Corin |
| Biomet |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for cobalt chromium feedstock lock in both supply access and price visibility for integrated manufacturers, insulating procurement costs from Democratic Republic of Congo mining volatility while compressing margin flexibility for component assemblers without legacy supplier relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across cementless fixation tiers. Three-tier pricing structure across premium porous-coated titanium, standard wrought alloy substrates, and economy cemented configurations tracks ASTM F2077 fatigue validation levels. Pricing pressure stems from hospital buying consortiums consolidating vendor panels around single-source instrumentation platforms. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize osseointegration performance over unit cost.
Supply Chain Analysis
Inventory buffers for titanium alloy forgings extend lead times when German and Swiss precision forging capacity runs at utilization ceilings. Raw material flows draw from Australian rutile sand, South African ferrochrome, and Ukrainian titanium sponge. Single-source vulnerability concentrates in plasma-spray coating equipment from specialized vendors. Distribution runs through integrated delivery networks displacing independent distributors in United States Medicare Advantage markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hip preservation alternatives including resurfacing implants and biologic cartilage restoration, which threaten to delay primary arthroplasty indications in younger osteoarthritis cohorts.
For Market Incumbents: Compound surface engineering differentiation through captive plasma-spray capacity expansion and trabecular metal architecture patents. Defend against dual mobility cup commoditization by embedding patient-matched instrumentation into hospital system partnerships. Priority leverage sits with EMA MDR notified body relationship depth to accelerate technical file reviews. For New Entrants and Emerging Players: Post-acute rehabilitation feedback loops represent an underserved service layer where incumbents under-serve readmission risk analytics. Target Indian government medical device parks for cost-advantaged export base establishment. Penetrate through CDSCO fast-track pathway navigation for standard cemented prostheses. For Investors and Strategic Acquirers: Porous coating technology licensors with ASTM F2077 validation dossiers represent the named acquisition target archetype. Five-to-ten year viability hinges on ceramic-on-polyethylene wear debris litigation exposure. Signal to monitor: FDA 510(k) Third Party Review Program expansion accelerating predicate-based competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for titanium alloy predicate devices under Third Party Review Program. |
| CE Marking Pathway | EMA MDR Article 10 compliance streamlines cross-border hospital system procurement. |
| Hospital System Partnership | Integrated delivery network contracts displace independent distributor margins. |
| Software Companion Development | AI-assisted preoperative planning reduces cup positioning variability in complex anatomies. |
| Reimbursement Strategy | METI incentives for minimally invasive approaches open regional hospital channels in Japan. |
Research Methodology
The analysis maps cementless fixation, dual mobility, cemented, and hybrid prosthesis configurations, each validated through orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interview findings triangulate against FDA 510(k) databases, EMA MDR technical file registries, hospital procurement databases, and CMS Medicare claims data. Bottom-up surgical volume estimates reconcile with top-down manufacturer revenue disclosures.
Consistency checks validated volume and value outputs against ASTM F2077 fatigue validation benchmarks and ISO 5832 material standard adoption rates across the projection horizon. Segmentation dimensions span fixation technology, material substrate, application indication, and end-user site-of-service. CAGRs derive from surgical volume trajectories, procedure mix shifts, and reimbursement pathway evolution. Forecast inputs incorporate PMDA ceramic fracture database scrutiny timelines and CDSCO fast-track pathway throughput.
Underlying assumptions cover EMA MDR notified body capacity normalization, cobalt chromium feedstock price stability, and hip preservation alternative penetration ceilings, with deviation risk concentrated in geopolitical mining disruptions and ceramic component litigation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Trial Prostheses Market
Medical Devices
Global Surgical Drills Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Mexico General Surgical Devices Market