
 Blood Preparation Market | 2026-2036
Blood Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Preparation Market Analysis
Plasma fractionation revenue is rewriting profit architecture across the blood preparation value chain. CSL Behring leverages vertically integrated plasma collection networks across multiple continents. Grifols sustains manufacturing scale through controlled plasma supply agreements with regional donation centers. Baxter International anchors hospital contracting relationships through specialized albumin and immunoglobulin formulations.
Blood preparation encompasses the collection, processing, storage, and distribution of human blood components for therapeutic transfusion and plasma-derived medicinal products, requiring maintenance at specific temperature ranges and anticoagulant preservation to ensure viability. Plasma fractionation dominates value generation through its role in producing clotting factors, immunoglobulins, and albumin for chronic disease management. Automated blood collection technology is accelerating donor throughput efficiency while reducing manual handling contamination risks. Transfusion services applications concentrate demand in tertiary care settings where complex surgical and oncology protocols require component-specific matching.
FDA blood banking regulations, EU MDR device classification requirements, and WHO blood safety standards collectively enforce pathogen reduction mandates and traceability protocols across collection and distribution networks. These frameworks elevate compliance costs for smaller blood centers while favoring operators with integrated quality management systems. Stakeholders must monitor evolving plasma protein therapeutic indications and regional donor base demographics to align capacity investments with shifting therapeutic demand profiles.
Market Dynamics
Automated blood collection systems are compressing operational margins at manual-processing blood centers while concentrating throughput advantages among early adopters with capital reserves for platform upgrades.
Growth Catalysts
- FDA pathogen reduction mandates:Regulatory requirements for nucleic acid testing and bacterial detection are expanding addressable market for specialized reagent suppliers and automated screening platforms.
- Tertiary care surgical volumes:Complex oncology and cardiovascular procedures at academic medical centers are driving component-specific matching protocols that favor sophisticated transfusion services infrastructure.
- Plasma fractionation yield improvements:Chromatographic purification advances are extracting higher immunoglobulin and albumin volumes per liter of source plasma, improving collection economics for donor network operators.
Market Restraints
- Source plasma supply concentration:United States donor base provides over sixty percent of global plasma for fractionation, creating geographic dependency risk for European and Asian manufacturers.
- Refrigerated storage energy costs:Cold chain maintenance for red cell concentrates and platelets requires continuous 1-6°C and 20-24°C environments, exposing blood centers to electricity price volatility.
- Recombinant factor VIII substitution:Hemophilia A patients in developed markets are switching to synthetic clotting factors, compressing demand for plasma-derived equivalents.
Strategic Opportunities
- India's expanding hospital infrastructure:Private healthcare chains in Mumbai, Delhi, and Bangalore are building in-house blood component laboratories, creating demand for automated processing equipment.
- WHO blood safety initiative alignment:National blood policy reforms in middle-income countries are mandating centralized testing and component preparation, opening public procurement channels.
- Leukoreduction filter technology convergence:Integration of filtration systems with automated collection platforms is enabling real-time component separation at donation sites.
Industry Challenges
- Specialized immunohematology technologist shortage:Complex antibody identification and cross-matching procedures require certified personnel that blood banks struggle to recruit and retain.
- EU MDR device reclassification timelines:Blood collection and processing equipment faces extended conformity assessment periods, delaying product launches and freezing R&D budgets.
- Legacy LIS-BBIS integration complexity:Hospital laboratory information systems require costly middleware development to interface with modern blood bank information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Preparation Market |
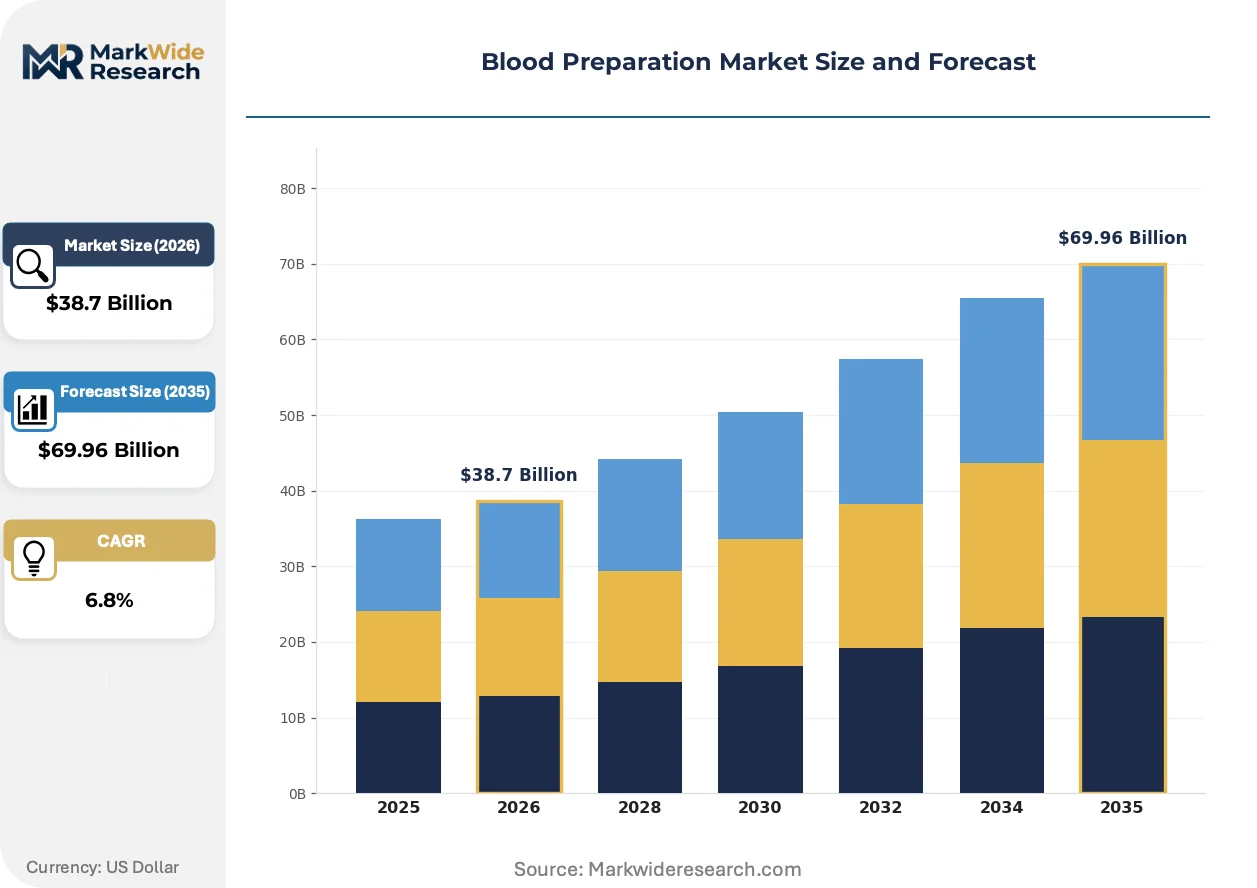
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Blood Cells, Plasma, Platelets, Whole Blood Delivery Mode: Direct Blood Donation, Automated Blood Collection, Emergency Transport, Blood Bank Technology: Filtration, Freezing, Separation, Refrigeration Application: Transfusion Services, Surgical Procedures, Hematology, Research |
| Companies Covered | CSL Behring, Takeda Pharmaceutical, Grifols, Baxter International, Octapharma, Pfizer, AstraZeneca, Abbott Laboratories, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Preparation Market Emerging Trajectories
Pathogen inactivation chemistry and automated component separation are converging to reshape collection economics, while regulatory pressure on traceability is accelerating digital platform adoption across the supply chain.
Photochemical pathogen reduction technology using amotosalen and ultraviolet light treatment is rendering obsolete traditional reactive screening models for platelet and plasma units. Major hospital transfusion services in Germany and Japan are adopting these systems as standard protocol. The shift is compressing time-to-release for blood products while adding per-unit processing costs that favor high-volume collection centers.
EU MDR device classification requirements are reclassifying blood collection sets and apheresis equipment into higher-risk categories, triggering enhanced clinical evidence requirements. Manufacturers must now submit post-market surveillance data and periodic safety update reports. German and French notified bodies are prioritizing submissions from operators with existing ISO 13485 quality management certifications, creating backlog advantages for established suppliers.
Consolidated procurement by hospital purchasing alliances is displacing individual blood center negotiations across the United States. Group purchasing organizations are standardizing specifications for collection containers, filters, and reagents, compressing supplier margins. This concentration is most visible in the Southeast and Midwest, where regional health systems have merged transfusion service operations under unified supply contracts.
Blood Preparation Market Segmentation
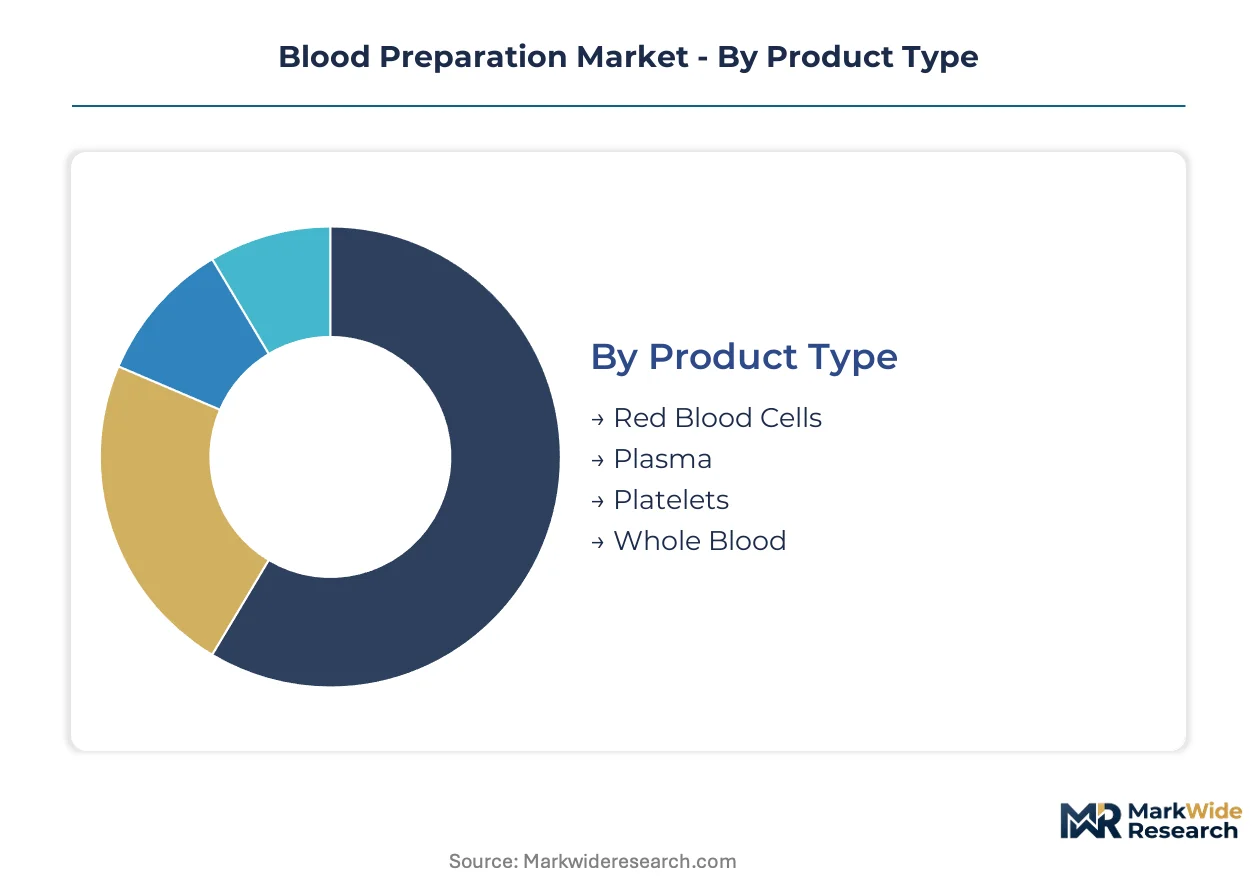
Blood preparation markets segment across biological product characteristics, collection methodologies, and clinical end-uses. Each dimension carries distinct margin profiles, regulatory pathways, and capital intensity requirements that shape supplier positioning.
Product Type:
Clinical use-cases span trauma resuscitation through chronic disease management, with each blood component serving differentiated therapeutic protocols.
- Red Blood Cells:Concentrated erythrocyte suspensions in additive solutions maintain oxygen-carrying capacity for 35-42 days at 1-6°C. Demand concentrates in cardiovascular surgical suites across the United States and Japan where complex bypass procedures require type-specific matching.
- Plasma:Source material for fractionation into albumin, immunoglobulins, and clotting factors drives the highest per-liter economics in the value chain. German and Japanese aging populations are expanding therapeutic plasma needs for immunodeficiency and neurological indications.
- Platelets:Apheresis-derived units stored at 20-24°C with agitation support oncology transfusion protocols.
- Whole Blood:Unseparated donations retain military and rural emergency applications where component processing infrastructure is absent.
The dominant share belongs to Plasma, while Red Blood Cells is closing the gap fastest.
Delivery Mode:
Collection infrastructure investments separate high-throughput operators from regional blood centers serving limited catchment areas.
- Automated Blood Collection:Apheresis platforms extract specific components while returning remaining blood constituents to donors, enabling higher-frequency donation schedules. CSL Behring and Grifols deploy mobile collection fleets across multiple continents to secure source plasma supply.
- Direct Blood Donation:Designated donor-recipient matching serves specialized immunohematology cases requiring rare antigen-negative units.
- Blood Bank:Centralized processing and distribution hubs maintain inventory for hospital transfusion services.
- Emergency Transport:Helicopter and ground-based cold chain logistics deliver O-negative units to trauma centers within the golden hour window.
Automated Blood Collection commands the largest infrastructure footprint, with Blood Bank networks expanding most quickly in India's private hospital chains.
Technology:
Processing capabilities determine yield efficiency, pathogen safety margins, and shelf-life extension potential across the preparation workflow.
- Filtration:Leukoreduction and pathogen reduction filters remove white blood cells and inactivate residual infectious agents. German hospital transfusion services are adopting photochemical pathogen inactivation as standard protocol for platelet and plasma units.
- Separation:Centrifugation and chromatographic methods partition whole blood into component fractions with distinct therapeutic applications.
- Refrigeration:Controlled-temperature storage systems maintain component viability across distribution networks.
- Freezing:Glycerolization and rapid freezing preserve red cell concentrates for extended inventory cycles.
Filtration absorbs the highest consumables expenditure, while Separation technology is gaining share fastest through chromatographic purification advances.
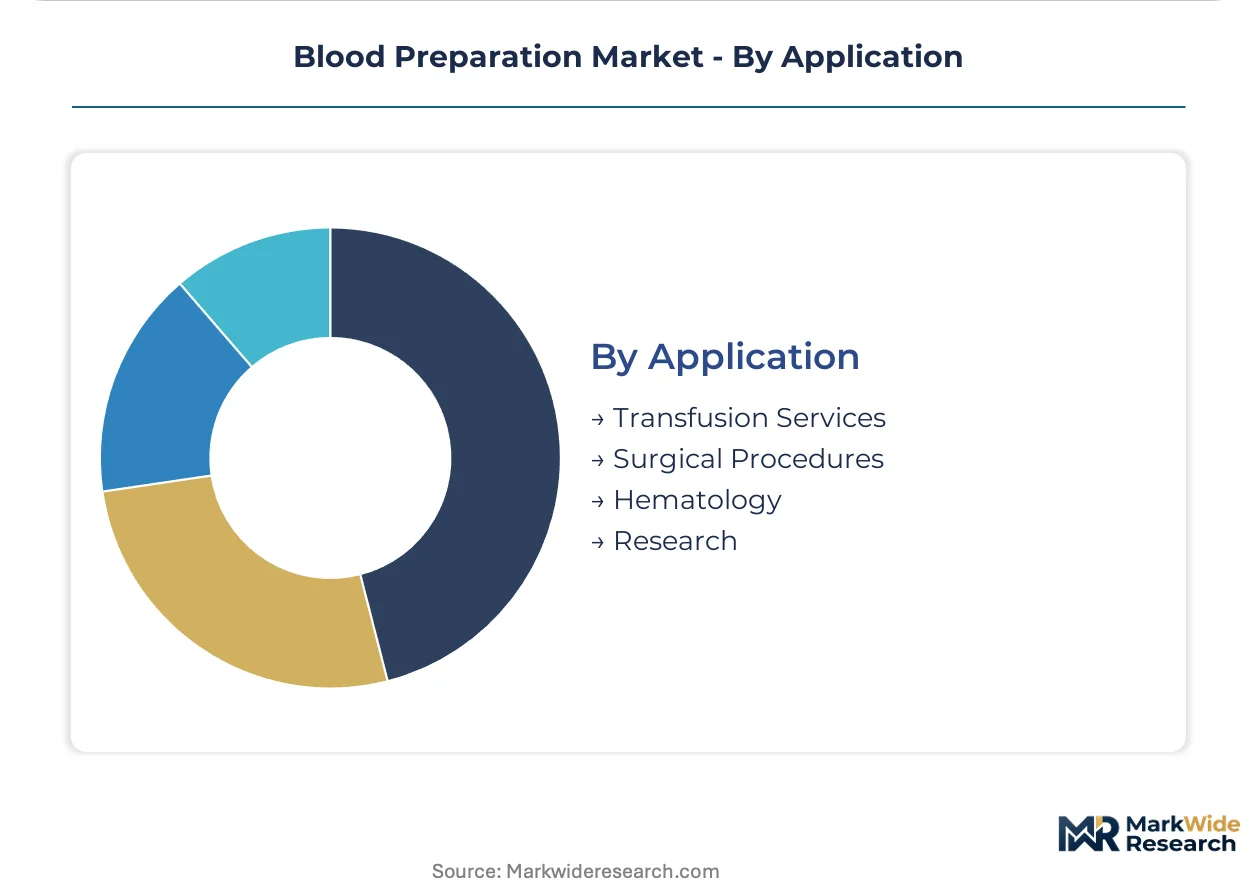
Application:
End-user sophistication ranges from standardized transfusion protocols to experimental cellular therapies with divergent regulatory and quality requirements.
- Transfusion Services:Hospital-based blood banks manage component inventory, cross-matching, and bedside administration for surgical and medical patients. Tertiary care centers in the United States concentrate demand for complex antibody identification and specialized matching protocols.
- Surgical Procedures:Elective and emergency interventions drive predictable consumption patterns for red cells and plasma derivatives.
- Hematology:Oncology and bone marrow transplant units require irradiated and CMV-negative components for immunocompromised recipients.
- Research:Academic and commercial laboratories utilize blood derivatives for assay development and cellular therapy manufacturing.
Transfusion Services generates the highest procedure volume, with Surgical Procedures climbing fastest as cardiovascular and orthopedic surgical volumes recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Developed markets emphasize plasma fractionation for chronic disease management, while emerging economies prioritize whole blood availability for trauma and maternal health applications.
United States
Automated apheresis collection networks dominate source plasma supply for fractionation operations. FDA pathogen reduction mandates and nucleic acid testing protocols enforce stringent safety standards across collection centers. The Research Triangle Park cluster in North Carolina and Boston-Cambridge corridor concentrate transfusion medicine research and specialized reagent manufacturing.
Germany
Hospital transfusion services drive demand for leukoreduced components and photochemical pathogen inactivation systems. EU MDR device reclassification requirements extend conformity assessment timelines for blood collection equipment manufacturers. The Rhine-Ruhr metropolitan region hosts centralized testing laboratories serving multi-hospital alliances with standardized component preparation protocols.
Japan
Aging demographics expand therapeutic plasma needs for immunodeficiency and neurological indications, with albumin consumption rising fastest among elderly populations. PMDA regulations align with international blood safety standards while maintaining domestic plasma self-sufficiency targets. The Kanto region surrounding Tokyo concentrates hospital transfusion services and specialized immunohematology reference laboratories.
India
Private healthcare chains in Mumbai, Delhi, and Bangalore are constructing in-house blood component laboratories to replace reliance on fragmented blood bank networks. National blood policy reforms mandate centralized testing and component preparation under WHO safety initiative alignment. The National Capital Region and Maharashtra state clusters are deploying automated processing equipment at scale.
China
Domestic plasma collection volume constraints limit fractionation capacity expansion despite rising immunoglobulin demand for immunology and infectious disease applications. NMPA regulations enforce traceability protocols across collection and distribution networks with batch release testing requirements. The Yangtze River Delta region concentrates plasma fractionation facilities serving hospital systems in Shanghai and Jiangsu province.
Blood Preparation Market Vendor Landscape
Capability concentration sits with plasma fractionation specialists commanding vertically integrated donor networks; scale advantage sits with diversified healthcare conglomerates leveraging hospital contracting relationships. The market structure organizes around three tiers: integrated plasma collectors with continental collection footprints, specialized fractionators dependent on contracted supply agreements, and diversified medical technology vendors bundling blood preparation equipment with broader hospital solutions. Dominant competitive moves include backward integration into plasma supply through donor center acquisitions and technology licensing partnerships for automated collection platform deployment.
Among integrated plasma specialists, CSL Behring and Grifols exemplify the archetype of operators with captive donor network control across multiple continents. Baxter International occupies a position representing diversified healthcare conglomerates anchoring hospital relationships through specialized protein formulations. These three entities collectively illustrate the competitive spectrum from pure-play plasma economics to bundled hospital supply positioning.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical |
| Grifols |
| Baxter International |
| Octapharma |
| Pfizer |
| AstraZeneca |
| Abbott Laboratories |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic refrigerated cargo corridors linking United States collection centers to European fractionation facilities impose freight costs that compound geographic supply concentration, forcing price stratification between integrated plasma collectors with captive donor networks and smaller operators dependent on contracted supply agreements.
Pricing Analysis
Long-term offtake contracts between plasma fractionators and donor network operators dominate pricing architecture, with spot market transactions limited to distressed inventory or supply shortfalls. Three-tier pricing structure across premium pathogen-reduced plasma, standard source plasma, and economy-grade whole blood separates CSL Behring and Grifols from regional blood centers. Cost compression in standard-grade plasma is intensifying because automated collection platforms reduce per-liter processing overhead. Hospital purchasing alliances exhibit highest price sensitivity, while specialized immunohematology reference laboratories demonstrate lowest sensitivity due to irreplaceable matching protocols.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for fractionated plasma derivatives, with immunoglobulin and albumin shipments facing regulatory inspection delays at ports of entry. Manufacturing concentrates in United States, Germany, and Japan, with source plasma collection drawing from American donor bases exceeding sixty percent of global volume. Chromatographic resins, sterile collection bags, and nucleic acid testing reagents constitute critical input dependencies. Single-source vulnerability for apheresis equipment components threatens collection capacity expansion timelines. Distribution runs through hospital purchasing alliances and group purchasing organizations consolidating procurement across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant factor VIII substitution for hemophilia A patients constitutes an existential substitution threat that plasma-derived product incumbents must neutralize through yield improvements and chronic disease indication expansion.
For Market Incumbents: Build regulatory moat through FDA pathogen reduction compliance certification and EU MDR device classification pre-clearance. Secure captive plasma supply through backward integration into donor center networks across India's National Capital Region and Maharashtra state clusters. Counter recombinant substitution threat by expanding immunoglobulin indications into neurological therapeutic areas. Leverage automated collection platform deployment to compress per-liter economics below recombinant manufacturing cost curves.
For New Entrants and Emerging Players: Build out leukoreduction filter technology integration with mobile apheresis platforms as the most penetrable white-space target. Target India's private hospital chains in Mumbai, Delhi, and Bangalore constructing in-house blood component laboratories. Pursue WHO blood safety initiative alignment as go-to-market angle for public procurement channels in middle-income countries mandating centralized testing infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core blood preparation assets amid plasma fractionation margin compression. Long-term viability hinges on operators controlling continental donor networks with automated collection density. Monitor recombinant factor VIII prescription volume trends in developed markets as inflection indicator for plasma-derived product demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Collection Platform Deployment | CSL Behring and Grifols mobile fleets across multiple continents secure source plasma supply against recombinant substitution. |
| Pathogen Reduction Technology Licensing | German hospital transfusion services adopting photochemical inactivation as standard protocol compress time-to-release economics. |
| Donor Network Acquisition | Backward integration into United States and India donor centers eliminates contracted supply agreement vulnerability. |
| EU MDR Device Pre-Certification | ISO 13485 quality management certification creates backlog advantages at German and French notified bodies. |
| Plasma Fractionation Yield Improvement | Chromatographic purification advances extract higher immunoglobulin volumes per liter, improving collection economics. |
Methodological Framework
A spread of perspectives from plasma collection center operators, hospital transfusion service directors, fractionation facility plant managers, and regulatory affairs specialists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA blood banking guidance documents, EU MDR device classification databases, WHO blood safety standards, and hospital procurement contract filings. Bottom-up donor network capacity modeling and top-down therapeutic plasma demand estimation provided triangulation across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, collection methodology, processing technology, and clinical end-use application, with regional regulatory cluster as the blood preparation-specific dimension. CAGRs derived from historical plasma collection volume trajectories, surgical procedure growth rates, and fractionation capacity expansion announcements. Industry-specific forecast inputs incorporated pathogen reduction mandate implementation timelines and recombinant factor substitution adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified healthcare conglomerates or accelerated recombinant product launches would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Skin Tac Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Swabs Collection Kit Market