
 Kyphoplasty Systems Market | 2026-2036
Kyphoplasty Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Kyphoplasty Systems Market Analytics
Procedure bundling is pivoting toward integrated kyphoplasty kits that combine balloons, bone cement, and delivery systems under single SKUs. Medtronic leverages its broad spine portfolio to anchor hospital contracting power across vertebral augmentation. Stryker sustains competitive pressure through specialized bone substitute formulations and cement mixing systems. Merit Medical Systems differentiates via targeted outpatient clinic channels and compact delivery platforms.
Kyphoplasty systems encompass percutaneous vertebral augmentation instruments including inflatable bone tamps, polymethylmethacrylate or calcium phosphate cements, and image-guided insertion tools designed to restore vertebral body height and stabilize compression fractures. Balloon kyphoplasty occupies the dominant revenue position due to established reimbursement codes and surgeon familiarity, while robotic assistance represents the fastest-expanding technology segment as hospitals seek to reduce radiation exposure and improve cannulation accuracy. Ambulatory surgical centers emerge as a high-growth end user channel where streamlined procedure workflows and lower fixed costs concentrate margin capture.
FDA 510(k) clearance requirements govern bone cement biocompatibility and mechanical performance standards, while the EU Medical Device Regulation imposes strengthened clinical evidence and post-market surveillance obligations on European manufacturers. Japan's PMDA maintains distinct pharmaceutical and medical device classification rules for bone cements that influence market entry sequencing. Stakeholders must monitor evolving CMS reimbursement determinations for same-day kyphoplasty procedures and assess how robotic navigation investments reshape capital equipment purchasing cycles.
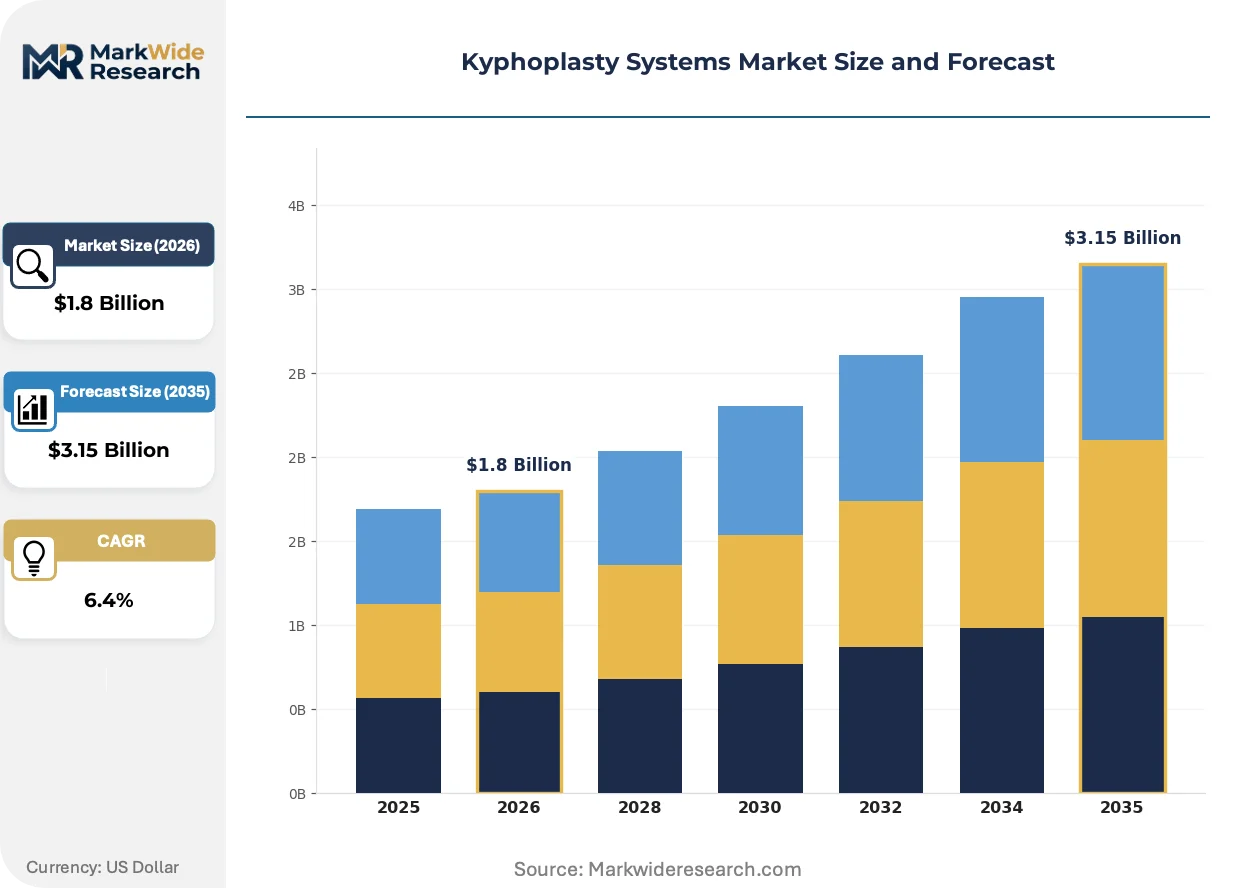
Market Dynamics
Ambulatory surgical centers are consolidating kyphoplasty procedures into same-day workflows, compressing capital equipment cycles and forcing manufacturers to redesign delivery platforms for outpatient throughput rather than hospital OR integration.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States sustain procedure volumes through established Medicare and statutory health insurance reimbursement for vertebral augmentation.
- MDR compliance investments:European manufacturers accelerating clinical evidence generation for bone cement biocompatibility under strengthened post-market surveillance obligations.
- Robotic navigation:Hospitals adopting image-guided cannulation systems to reduce fluoroscopy exposure and improve pedicle targeting accuracy.
Market Restraints
- PMMA price volatility:Methyl methacrylate monomer supply disruptions constrain bone cement production margins and batch consistency.
- Single-source balloon tamp concentration:Three contract manufacturers control silicone elastomer molding for inflatable bone tamps, creating supply vulnerability.
- Vertebroplasty substitution:Unaugmented cement injection procedures compete on cost in cash-pay markets and developing health systems.
Strategic Opportunities
- India outpatient expansion:Private hospital chains building dedicated spine day-surgery units create first-mover positioning for compact cement delivery systems.
- Bioresorbable cements:Calcium phosphate formulations converging with osteoconductive scaffolds open pediatric and young-adult fracture indications beyond osteoporotic segments.
- CMS same-day determination:Proposed reimbursement alignment for ASC-based kyphoplasty creates channel arbitrage potential against hospital outpatient department billing.
Industry Challenges
- Interventional radiology staffing:Shortage of dual-trained spine surgeons and radiologists limits procedural capacity expansion in community hospital settings.
- 510(k) predicate drift:FDA narrowing acceptable equivalence claims for next-generation bone cements extends regulatory timelines and resubmission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kyphoplasty Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Kyphoplasty, Vertebroplasty, Injectable Bone Cement, Imaging Guidance End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Fluoroscopy, CT Navigation, Ultrasound Guidance, Robotic Assistance Procedure Type: Minimally Invasive Surgery, Open Surgery, Emergency Procedure, Elective Procedure |
| Companies Covered | Medtronic, Stryker, Merit Medical Systems, DePuy Synthes, IZI Medical Products, MicroPort Scientific Corporation, Smith & Nephew, CareFusion, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kyphoplasty Systems Market Evolving Landscape
Device miniaturization and radiation reduction technologies are converging to redefine procedural economics, shifting competitive advantage from cement chemistry to workflow integration and disposable system design.
Robotic-assisted cannulation systems are electrifying kyphoplasty workflows by automating needle trajectory planning and real-time depth control. Ambulatory surgical centers in the United States are piloting these platforms to eliminate C-arm repositioning and reduce staff radiation badge exposure. This electrifying capability compresses procedure time from forty-five to under twenty minutes, enabling same-day throughput targets that disposable kit economics alone cannot achieve.
The EU Medical Device Regulation is tightening clinical evidence requirements for bone cement mechanical performance and long-term biocompatibility. Manufacturers must now submit prospective registry data rather than retrospective case series for CE marking renewals. High-viscosity cement formulations face disproportionate scrutiny, pushing R&D investment toward standardized rheological testing protocols and post-market fracture registry participation.
Hospital procurement committees are unbundling kyphoplasty capital equipment from disposable contracts, separating balloon tamp and cement mixer purchases from annual volume commitments. Integrated delivery networks in Germany and Japan are driving this fragmentation to optimize total cost-per-procedure across multi-site spine centers. The shift pressures manufacturers to demonstrate standalone ROI for navigation platforms rather than relying on captive cement sales for equipment amortization.
Kyphoplasty Systems Market Segmentation
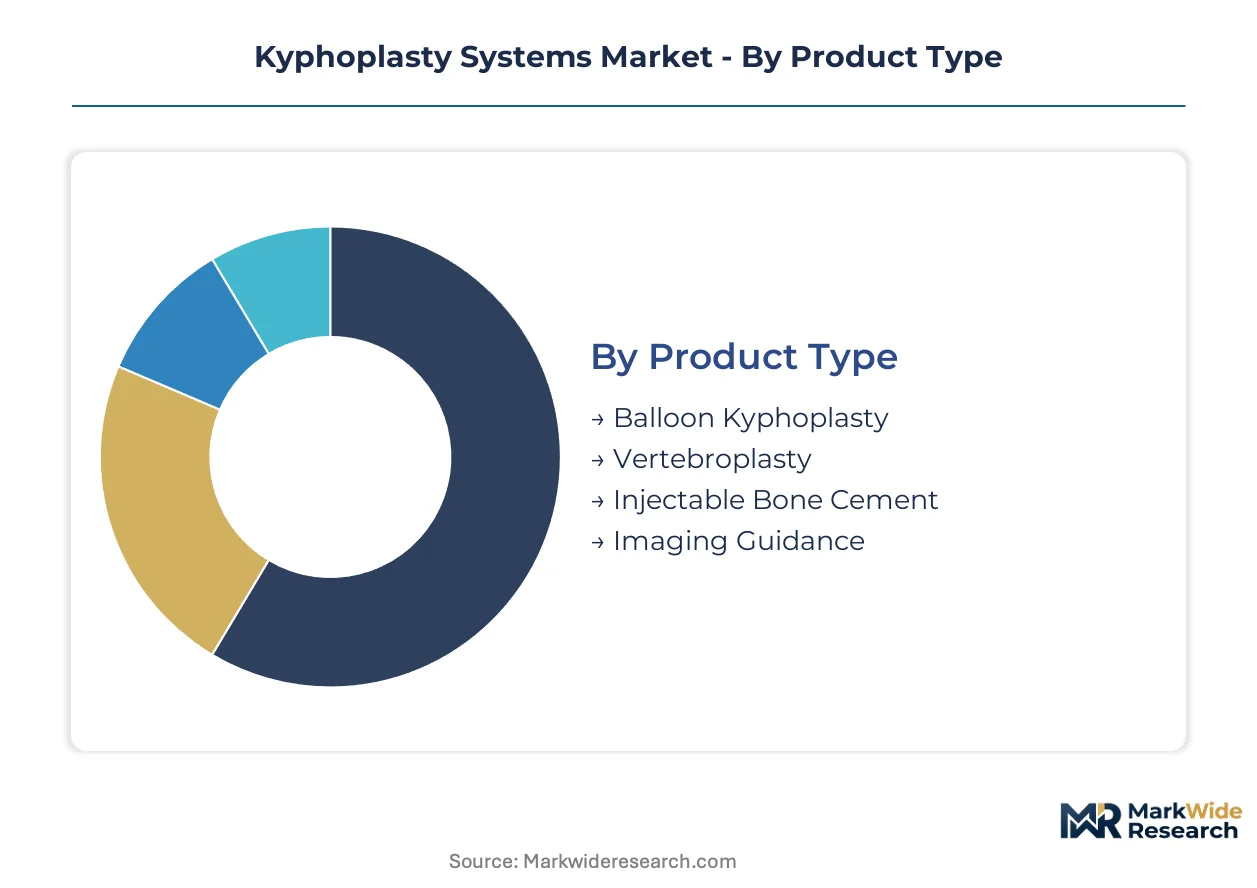
Kyphoplasty system manufacturers configure product portfolios across four distinct segmentation axes. Each dimension shapes procurement decisions, reimbursement pathways, and competitive positioning differently across hospital and outpatient settings.
Product Type:
Product architecture determines capital intensity, disposable economics, and surgeon training requirements for vertebral augmentation procedures.
- Balloon Kyphoplasty:Inflatable bone tamps create a controlled cavity before cement injection, restoring vertebral height in osteoporotic compression fractures. United States Medicare reimbursement sustains hospital procedure volumes, though PMMA monomer supply volatility constrains manufacturing margins.
- Vertebroplasty:Direct cement injection without cavity creation offers lower device cost and faster operative time. Demand concentrates in cash-pay markets and developing health systems where cost compression outweighs height restoration objectives.
- Injectable Bone Cement:Polymethylmethacrylate and calcium phosphate formulations with modified viscosity and setting times enable targeted delivery through narrow-gauge needles. Rheological standardization under EU MDR post-market surveillance obligations accelerates quality system investments.
- Imaging Guidance:C-arm fluoroscopy integration kits and navigation software reduce radiation exposure and improve cannulation accuracy. Ambulatory surgical centers adopt compact, mobile systems to enable same-day throughput without fixed radiology infrastructure.
Balloon kyphoplasty leads on scale; imaging guidance leads on momentum.
End User:
Site-of-care economics reshape device specifications, with throughput requirements and reimbursement differentials driving divergent product configurations.
- Hospitals:Integrated operating rooms with fixed C-arms and anesthesia support handle complex multi-level fractures and trauma cases. Capital equipment purchasing cycles extend 5-7 years, locking manufacturers into long-term disposable supply agreements.
- Outpatient Clinics:Physician-owned spine practices perform elective kyphoplasty with local anesthesia and conscious sedation. Compact cement mixing systems and single-use delivery platforms dominate procurement specifications.
- Ambulatory Surgical Centers:Streamlined workflows target sub-30-minute procedure times with immediate discharge protocols. FDA 510(k) clearance for same-day protocols enables CMS reimbursement alignment that captures margin against hospital outpatient department billing.
- Rehabilitation Centers:Post-acute settings manage conservative care and fracture risk assessment, generating referral flows rather than direct procedure demand. Fall prevention programs and bone density screening create upstream patient identification.
Hospitals anchor revenue concentration; ambulatory surgical centers drive expansion velocity.
Technology:
Visualization and navigation modalities determine radiation exposure, procedural precision, and capital deployment requirements across clinical settings.
- Fluoroscopy:Real-time X-ray imaging remains the standard of care for needle placement and cement injection monitoring. Surgeon radiation exposure and C-arm repositioning time create workflow friction that alternative modalities seek to eliminate.
- CT Navigation:Pre-procedural planning with intraoperative registration improves pedicle targeting accuracy in anatomically challenging cases. Germany and Japan lead adoption where capital equipment budgets accommodate navigation platform amortization.
- Ultrasound Guidance:Radiation-free visualization of soft tissue and bone surface offers particular utility in cervical and pediatric applications. Image quality limitations in obese patients and through bone restrict mainstream spine adoption.
- Robotic Assistance:Automated needle trajectory planning and depth control reduce fluoroscopy time from minutes to seconds. Steepest expansion trajectory among all technology segments as hospitals seek to differentiate spine service lines and reduce staff radiation badge exposure.
Fluoroscopy retains installed base dominance; robotic assistance captures disproportionate capital investment growth.
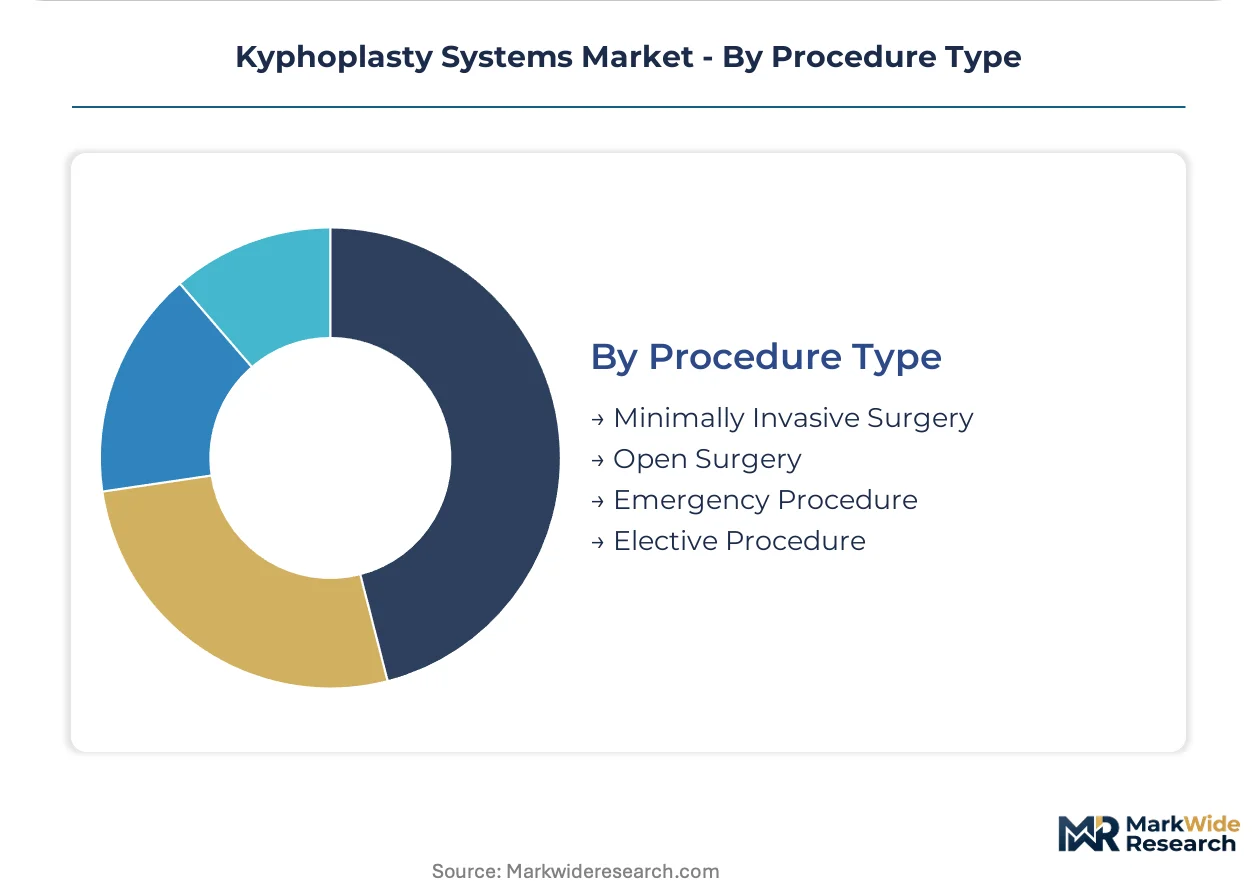
Procedure Type:
Clinical indication and urgency classification determine anesthesia requirements, device selection, and reimbursement coding for vertebral augmentation.
- Minimally Invasive Surgery:Percutaneous access through 8-11 gauge needles under local or conscious sedation enables same-day discharge. Balloon kyphoplasty and vertebroplasty both deploy through this access approach, with device choice driven by fracture chronicity and height loss severity.
- Open Surgery:Direct visualization through laminectomy or corpectomy addresses retropulsed bone fragments and neural compression. Adjunctive kyphoplasty stabilizes anterior column reconstruction in trauma and tumor cases requiring decompression.
- Emergency Procedure:Acute traumatic or pathologic fractures with neurologic deficit demand rapid stabilization. Off-hours device availability and surgeon call coverage constraints limit procedure volume concentration to tertiary referral centers.
- Elective Procedure:Subacute osteoporotic compression fractures with persistent pain beyond 6-8 weeks of conservative management. Outpatient clinic and ambulatory surgical center channels capture this indication through scheduled, protocolized workflows.
Minimally invasive surgery leads on scale; elective procedures lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kyphoplasty systems originated in the United States during the 1990s, with the first balloon-assisted vertebral augmentation procedures performed at academic medical centers in California. The technology subsequently diffused to Germany and Japan through surgeon training programs and regulatory harmonization efforts.
United States
Medicare reimbursement for CPT code 22523 sustains hospital outpatient and ambulatory surgical center procedure volumes. FDA 510(k) clearance pathways govern bone cement biocompatibility standards and imaging-guided delivery system approvals. The Minneapolis-St. Paul corridor hosts major spine device manufacturers and integrated delivery networks that negotiate multi-year disposable supply contracts.
Germany
Statutory health insurance (GKV) coverage for vertebral augmentation procedures supports consistent demand among aging populations in Bavaria and North Rhine-Westphalia. EU Medical Device Regulation strengthened clinical evidence requirements for bone cement mechanical performance and post-market surveillance. The Tuttlingen surgical instrument cluster concentrates precision manufacturing capabilities for kyphoplasty balloon tamps and delivery cannulas.
Japan
PMDA maintains distinct pharmaceutical and medical device classification rules for polymethylmethacrylate bone cements that influence market entry sequencing for foreign manufacturers. Super-aged demographic profiles in Kanto and Kansai regions generate sustained procedure demand for osteoporotic compression fracture treatment. Tokyo academic medical centers pioneer robotic-assisted cannulation adoption to reduce surgeon fluoroscopy exposure.
India
Private hospital chains in Maharashtra and Karnataka are building dedicated spine day-surgery units to capture elective kyphoplasty volumes from tier-1 urban centers. CDSCO medical device registration requirements for bone cements create regulatory navigation complexity for multinational entrants. Apollo and Max Healthcare networks in Delhi-NCR pilot compact cement delivery platforms designed for outpatient throughput.
Australia
Medicare Benefits Schedule item numbers for vertebral augmentation procedures vary by state, creating reimbursement fragmentation across New South Wales and Victoria. TGA conformity assessment procedures align with EU MDR standards for bone cement biocompatibility documentation. Sydney and Melbourne private hospital groups invest in mobile C-arm systems to enable same-day kyphoplasty workflows outside traditional radiology departments.
Kyphoplasty Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated system bundling versus standalone disposable sourcing. The vendor base concentrates around diversified spine portfolios, specialized bone substitute formulators, and targeted outpatient channel specialists. Three strategic archetypes dominate: full-line spine conglomerates anchoring hospital contracting power, cement chemistry specialists differentiating through rheological formulations, and ambulatory-focused innovators optimizing compact delivery platforms. Competitive moves center on unbundling capital equipment from disposable contracts and accelerating robotic navigation platform placements.
Among diversified spine conglomerates, Medtronic and Stryker occupy positions that exemplify full-line contracting strategies. Medtronic leverages broad portfolio breadth to anchor multi-year hospital agreements. Stryker represents specialized bone substitute formulation capabilities. Merit Medical Systems sits within the outpatient channel specialist archetype, targeting ambulatory surgical center workflows with compact system designs.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Merit Medical Systems |
| DePuy Synthes |
| IZI Medical Products |
| MicroPort Scientific Corporation |
| Smith & Nephew |
| CareFusion |
| Globus Medical |
| Others |
Value Network & Pricing Analysis
Balloon-kyphoplasty premium tiers diverge sharply from vertebroplasty commodity tiers, with the former commanding bundled-equipment contracts in United States hospital systems and the latter competing on per-unit cement cost in Indian outpatient clinics. This bifurcation forces manufacturers to maintain dual supply chains: precision silicone molding for inflatable tamps in Germany's Tuttlingen cluster versus standardized PMMA mixing in lower-cost Asian facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs kyphoplasty system procurement, with FDA 510(k) clearance tier and robotic navigation compatibility as primary differentiation drivers. Pricing pressure stems from CMS reimbursement compression for same-day ASC procedures, squeezing margins on disposable kits. Ambulatory surgical centers exhibit highest price sensitivity, while German integrated delivery networks prioritize total cost-per-procedure over unit pricing.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement committees mandate qualified suppliers for both silicone balloon tamps and PMMA monomer precursors. Supply concentrates in Germany for precision elastomer molding, China for methyl methacrylate chemical feedstock, and the United States for final sterile assembly. Single-source vulnerability in medical-grade silicone creates structural risk, while distribution runs through GPO contracts and direct hospital agreements with 5-7 year lock-in periods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CMS same-day reimbursement rates in the United States exceed statutory health insurance coverage in Germany by enough margin to justify ASC channel investment despite higher regulatory compliance costs.
For Market Incumbents: Extend balloon-tamp manufacturing capacity in Tuttlingen to capture EU MDR-compliant supply premiums while accelerating robotic navigation platform placements in Tokyo academic centers. Vertebral augmentation substitution by unaugmented vertebroplasty in cash-pay markets demands defensive bundling of imaging guidance with cement delivery systems. Channel control through GPO contract renewal cycles remains the critical lever against outpatient-focused entrants. For New Entrants and Emerging Players: FDA 510(k) clearance for same-day ASC protocols in the United States opens a window for compact cement delivery platforms targeting sub-30-minute procedure workflows. Private hospital chains in Maharashtra and Karnataka building dedicated spine day-surgery units represent the most penetrable geography. Go-to-market through Apollo and Max Healthcare network pilot programs enables rapid volume scaling without tertiary hospital infrastructure investment. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance investments exceed €10 million for prospective registry data generation, forcing mid-tier European manufacturers toward exit. Long-term viability across the analysis window favors cement chemistry specialists with osteoconductive scaffold pipelines over pure-play balloon manufacturers. Watch CDSCO registration timelines for bone cements in India as the inflection signal for outpatient channel arbitrage potential.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Navigation Platform Placement | Reduces fluoroscopy exposure in Tokyo academic centers while differentiating spine service lines. |
| CE Marking Pathway Acceleration | EU MDR compliance investments lock out mid-tier competitors lacking prospective registry capabilities. |
| ASC Channel Partnership | CMS same-day reimbursement alignment captures margin against hospital outpatient department billing. |
| Osteoconductive Scaffold R&D | Calcium phosphate formulations open pediatric indications beyond saturated osteoporotic segments. |
| India CDSCO Registration | First-mover positioning in Maharashtra and Karnataka day-surgery units enables volume scaling. |
Research Methodology
Direct dialogue with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored qualitative findings, supplemented by FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across product type and end-user segments.
Unit economics and installed-base projections across the analysis window derived from segmentation by technology modality, site-of-care configuration, and geographic regulatory cluster. CAGRs emerged from logistic diffusion modeling of robotic navigation adoption, PMMA price elasticity coefficients, and ASC penetration curves. Industry-specific inputs included PMDA pharmaceutical-device classification timelines and CDSCO registration backlog data.
Revisions become necessary when methyl methacrylate monomer supply disruptions, EU MDR enforcement intensity, or CMS reimbursement determination shifts materialize. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Intramedullary Nails Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market