
 Saudi Arabia Spinal Surgery Devices Market | 2026-2036
Saudi Arabia Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Spinal Surgery Devices Market Analytics
Minimally invasive surgical navigation is reconfiguring how spinal fixation systems are designed, manufactured, and deployed in Saudi Arabia. Medtronic leverages its integrated surgical ecosystem to anchor premium positioning across major hospital networks. Stryker sustains competitive pressure through specialized instruments for percutaneous access. Globus Medical differentiates via robotic-assisted placement platforms that reduce revision rates.
Saudi Arabia spinal surgery devices encompass implants, instruments, biologics, and fixation hardware engineered from titanium alloys, PEEK polymers, and demineralized bone matrices to restore spinal stability, correct deformity, and enable neural decompression. Fusion implants incorporating porous titanium architectures and rhBMP-2 biologics currently command the deepest margin pools due to reimbursement premiums and technical complexity. Minimal invasive treatment modalities represent the fastest-expanding segment as SFDA-cleared navigation systems penetrate surgical centers beyond tertiary hospitals. Degenerative disc disease applications dominate procedure volumes, though scoliosis correction in pediatric populations generates disproportionate per-case revenue.
SFDA, the Ministry of Health, and the Saudi Food and Drug Authority's medical device technical regulations govern product registration, clinical evidence requirements, and post-market surveillance for spinal implants. These frameworks elevate barriers for uncertified manufacturers while accelerating approvals for devices with GCC harmonized standards. Stakeholders must monitor localization thresholds under Vision 2030 industrial policy, as domestic manufacturing partnerships increasingly determine tender eligibility and long-term contract security.
Market Dynamics
SFDA medical device technical regulations and Ministry of Health localization mandates are compressing market access timelines while redistributing procurement authority toward domestic manufacturing partnerships.
Growth Catalysts
- Minimally Invasive Navigation Systems:Percutaneous fixation platforms reduce hospital stay duration and revision risk. Tertiary care centers in Riyadh and Jeddah deploy these for complex deformity correction.
- Vision 2030 Localization Thresholds:Domestic manufacturing partnerships determine tender eligibility for cervical and lumbar implant systems. SFDA registration pathways accelerate for GCC-harmonized standards.
- RhBMP-2 Biologics Integration:Demineralized bone matrices with recombinant proteins command reimbursement premiums. Fusion procedures incorporating these biologics deepen margin pools.
Market Restraints
- Titanium Alloy Input Volatility:Porous titanium architectures for spinal implants face raw material price fluctuation. Supply concentration among specialty alloy producers elevates cost uncertainty.
- SFDA Clinical Evidence Requirements:Post-market surveillance obligations extend registration timelines. Small manufacturers lack resources for longitudinal outcome studies.
- PEEK Polymer Substitution Limits:Radiolucent interbody cages face competition from 3D-printed titanium alternatives. Material switching costs lock hospitals into existing inventory systems.
Strategic Opportunities
- Eastern Province Surgical Centers:Secondary hospitals in Dammam and Khobar remain underpenetrated for robotic-assisted placement platforms. Outpatient spine procedures expand addressable volume.
- Pediatric Scoliosis Correction:Deformity applications in adolescent populations generate disproportionate per-case revenue. Specialized instrumentation gaps create white space.
- Integrated Surgical Ecosystems:Navigation-robotics convergence enables single-vendor contracting. Hospital networks consolidate procurement around full-platform providers.
Industry Challenges
- Neuro-navigation Specialist Scarcity:Surgical teams require extended training for computer-assisted spinal fixation. Workforce development lags behind equipment installation.
- Legacy Imaging System Integration:Pre-operative planning software must interface with hospital PACS infrastructure. Compatibility failures delay operating room utilization.
- SFDA Re-registration Cycles:Periodic license renewal demands updated clinical data submission. Documentation burden consumes regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Spinal Surgery Devices Market |
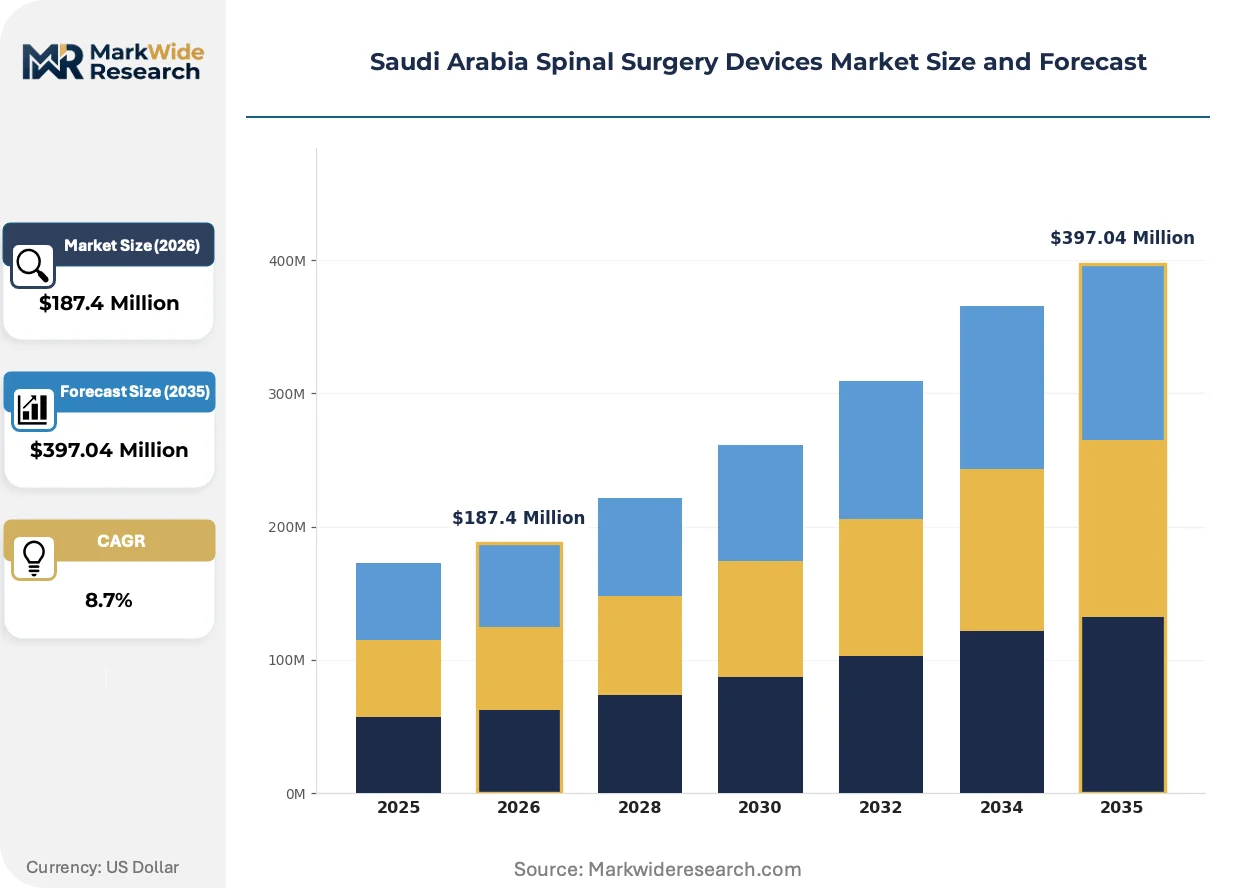
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Instruments, Biologics, Fixation Devices User Type: Hospitals, Surgical Centers, Clinics, Rehabilitation Facilities Treatment Type: Decompression, Fusion, Minimal Invasive, Revision Surgery Application: Degenerative Disc Disease, Scoliosis, Spinal Stenosis, Trauma |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, NuVasive, Zimmer Biomet, Globus Medical, ZimVie, Orthofix Medical, Baxter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Spinal Surgery Devices Market Evolving Landscape
Robotic-assisted surgical platforms are compressing revision rates while reshaping how hospital networks evaluate capital equipment vendors.
Computer-assisted navigation is digitizing pre-operative planning and intraoperative guidance for pedicle screw placement. Tertiary centers in Riyadh adopt these systems at accelerating pace as SFDA clears additional platforms. Real-time 3D imaging is digitizing surgical workflow efficiency and reducing fluoroscopy exposure.
SFDA medical device technical regulations now mandate post-market clinical follow-up for Class III spinal implants. Manufacturers must submit adverse event data quarterly rather than annually. High-risk biologics and fusion systems face the steepest compliance burden, driving consolidation among registrants.
Hospital procurement committees now bundle navigation hardware with disposables contracts spanning multi-year horizons. Traditional device-only vendors lose access as integrated platform providers capture tender awards. This concentration is most visible in Ministry of Health tertiary centers where capital budgeting authority has centralized.
Saudi Arabia Spinal Surgery Devices Market Segmentation
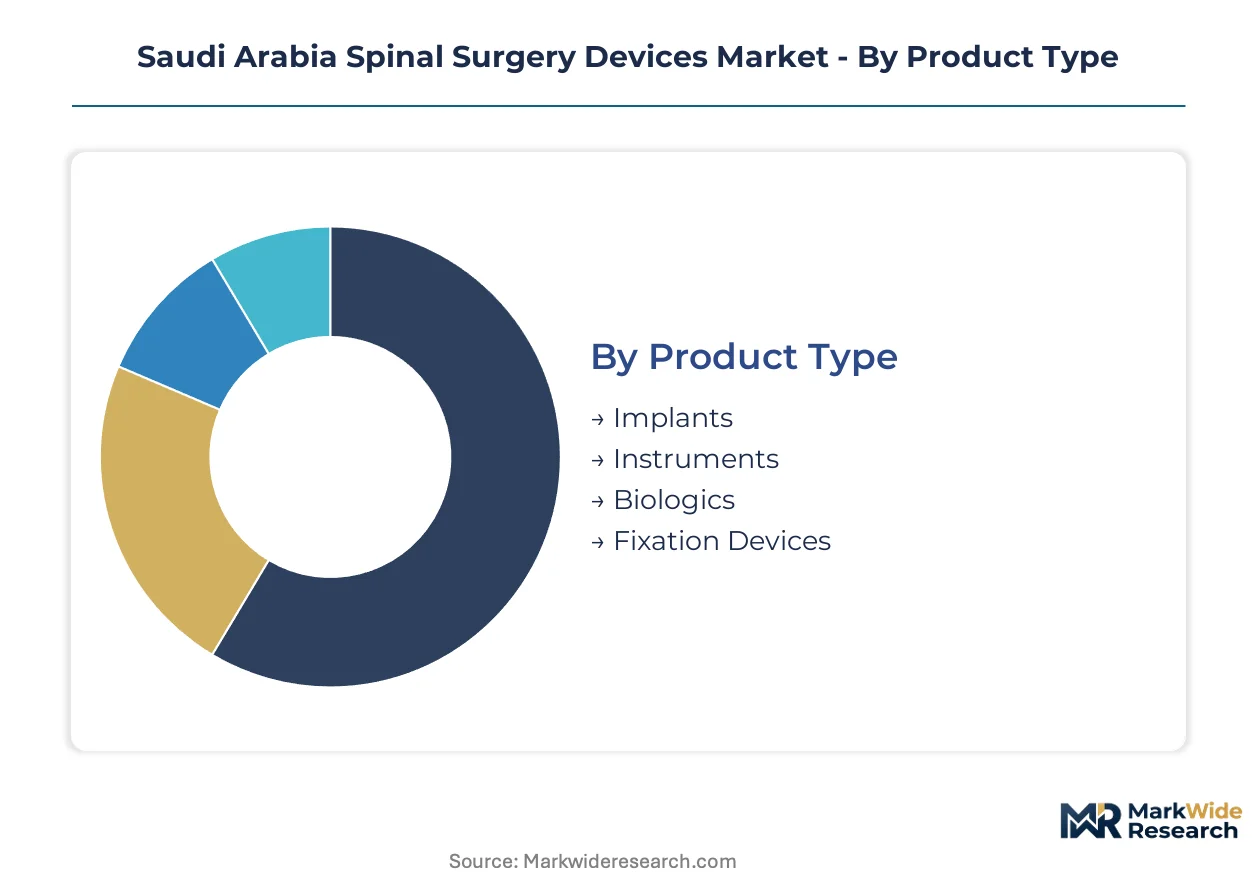
Spinal surgery device procurement in Saudi Arabia fragments across hardware categories, care settings, and procedural approaches. Each dimension carries distinct margin profiles and regulatory exposure under SFDA frameworks.
Product Type:
Cost tier stratification separates commoditized instruments from premium implant systems with biologic augmentation.
- Implants:Titanium alloy cages, PEEK interbody devices, and porous architectures dominate capital allocation. Tertiary centers in Riyadh concentrate demand for patient-specific 3D-printed constructs as SFDA clears additive manufacturing pathways.
- Biologics:Demineralized bone matrices and rhBMP-2 formulations command reimbursement premiums. Fusion procedures incorporating these biologics deepen margin pools while extending procedure times.
- Instruments:Specialized retractors, drills, and distractors support open and percutaneous approaches. Procurement bundles increasingly subsume instrument costs within implant contracts.
- Fixation Devices:Pedicle screw systems, rods, and connectors stabilize spinal segments. Eastern Province hospitals upgrade legacy stainless steel inventories to titanium platforms.
Implants command the established base. The steepest expansion runs through biologics.
User Type:
Customer type determines purchasing authority, with centralized Ministry of Health procurement diverging from private network decision-making.
- Hospitals:Tertiary centers perform complex deformity correction and multi-level fusion. Riyadh and Jeddah facilities drive navigation system adoption as capital budgets consolidate.
- Surgical Centers:Ambulatory settings in Dammam and Khobar expand outpatient spine procedure volumes. SFDA clearance for same-day discharge protocols accelerates instrument investment.
- Clinics:Diagnostic and conservative management sites refer surgical candidates to hospital networks. Imaging equipment compatibility shapes referral relationships.
- Rehabilitation Facilities:Post-operative care centers coordinate with implanting surgeons on recovery protocols. Device selection influences rehabilitation timelines and readmission risk.
Hospitals anchor volume concentration. Surgical centers are climbing the fastest as outpatient migration accelerates.
Treatment Type:
Application complexity drives technology requirements, with minimal invasive modalities demanding specialized navigation infrastructure.
- Minimal Invasive:Percutaneous fixation and tubular retractor systems reduce tissue disruption. Tertiary centers deploy these for selective nerve root decompression with shorter length of stay.
- Fusion:Interbody and posterolateral arthrodesis procedures consume the deepest implant inventory. Degenerative disc disease applications in adult populations sustain procedural frequency.
- Decompression:Laminectomy and discectomy address neural impingement without instrumentation. Cost pressure favors conservative implant selection in public hospital tenders.
- Revision Surgery:Hardware removal and replacement procedures face elevated complication rates. Scar tissue and anatomical distortion demand specialized explant instrumentation.
Fusion procedures anchor reimbursement volume. Minimal invasive approaches gain share fastest as navigation costs decline.
Application:
Clinical indication determines patient demographics, procedure complexity, and device performance requirements.
- Degenerative Disc Disease:Age-related disc collapse and herniation generate the highest procedure count. Lumbar fusion and artificial disc replacement concentrate in Ministry of Health tertiary centers.
- Scoliosis:Adolescent idiopathic and adult degenerative deformities require specialized instrumentation. Pediatric cases in Riyadh generate disproportionate per-case revenue due to construct complexity.
- Spinal Stenosis:Central and foraminal narrowing drives decompression demand. Elderly patient comorbidities favor minimal invasive approaches to reduce operative risk.
- Trauma:Fracture stabilization and spinal cord injury management demands rapid implant availability. Emergency procurement protocols bypass standard tender cycles.
Degenerative disc disease commands the established base. The steepest expansion runs through scoliosis correction as pediatric specialty centers expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Saudi Arabia concentrate purchasing authority across tertiary networks in Riyadh and Jeddah. SFDA registration pathways and Ministry of Health localization mandates redistribute tender eligibility toward domestic manufacturing partnerships. Capital budgeting for navigation-integrated platforms now centralizes at the network level rather than individual facility discretion.
Riyadh
Tertiary care centers in Riyadh drive demand for robotic-assisted placement platforms and patient-specific 3D-printed constructs. SFDA-cleared additive manufacturing pathways accelerate adoption of porous titanium architectures. King Faisal Specialist Hospital and Research Centre anchors complex deformity correction volumes, with multi-level fusion procedures consuming the deepest implant inventory.
Eastern Province
Secondary hospitals in Dammam and Khobar remain underpenetrated for navigation systems despite expanding outpatient spine procedure volumes. Ministry of Health capital allocation prioritizes same-day discharge protocol enablement. Saudi Aramco Medical Services Organization facilities upgrade legacy stainless steel fixation inventories to titanium platforms.
Western Region
Jeddah's private hospital networks consolidate procurement around integrated surgical ecosystems spanning navigation hardware and disposables. King Abdulaziz University Hospital anchors pediatric scoliosis correction volumes. Western Region facilities generate disproportionate per-case revenue from adolescent deformity instrumentation.
NEOM Northwest
Greenfield healthcare infrastructure under Vision 2030 creates tender opportunities for full-platform providers bundling capital equipment and consumables. NEOM Health and Wellbeing District procurement specifications favor GCC-harmonized standards for accelerated SFDA registration. Robotics-convergent navigation systems target first-mover positioning in this undeveloped surgical services market.
Saudi Arabia Spinal Surgery Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's spinal surgery devices market. Integrated platform vendors capture multi-year bundled contracts spanning navigation hardware and implant disposables. Product-specialist manufacturers defend position through biologics augmentation and specialized instrumentation. Dominant competitive moves include strategic partnerships with domestic manufacturers for localization compliance and technology licensing for navigation-robotics convergence.
Within the integrated platform tier, Medtronic and Stryker occupy positions anchoring premium hospital network relationships. Stryker's percutaneous access specialization and Medtronic's surgical ecosystem breadth exemplify divergent channel-control strategies. Globus Medical represents the robotic-assisted placement archetype, with its platform reducing revision rates in tertiary center deployments. Johnson & Johnson sits within the diversified medical technology conglomerate tier, leveraging cross-divisional contracting leverage.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| NuVasive |
| Zimmer Biomet |
| Globus Medical |
| ZimVie |
| Orthofix Medical |
| Baxter |
| Others |
Value Network & Pricing Analysis
Riyadh's concentration of tertiary surgical centers concentrates procurement leverage for titanium alloy cages and PEEK interbody devices, compressing margin pools for manufacturers lacking integrated navigation platforms. SFDA registration costs and Ministry of Health localization mandates amplify pricing power asymmetries between full-platform vendors and component specialists.
Pricing Analysis
Cost-plus contracts with titanium alloy indexation dominate public hospital tenders, while private networks negotiate bundled navigation-disposable agreements spanning multi-year horizons. Price differentiation separates GCC-harmonized SFDA registrants from non-certified imports. Pricing pressure intensifies in standard fixation devices as Eastern Province secondary hospitals consolidate procurement. Surgical centers exhibit highest price sensitivity; tertiary deformity correction centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Export control regimes on precision machining equipment and surgical navigation software limit technology transfer to domestic Saudi manufacturing partnerships. Specialty titanium alloy feedstock concentrates in USA, Germany, and Japan. PEEK polymer resin and rhBMP-2 biologics draw from Swiss and USA pharmaceutical suppliers. Single-source vulnerability runs through robotic-assisted placement platform controllers. Distribution runs through Ministry of Health central procurement and private hospital GPO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi spinal surgery devices market rewards manufacturers who control navigation-robotics integration capabilities, while surgical teams with computer-assisted fixation expertise remain scarce. This capability gap determines contract awards more than implant pricing alone.
For Market Incumbents: Entrench platform dominance by deepening backward integration into titanium alloy machining and securing exclusive biomedical engineer training partnerships with King Faisal Specialist Hospital. Consolidate procurement committee relationships before SFDA re-registration cycles force clinical data resubmission. Navigation-robotics convergence represents the critical defensive lever against specialized percutaneous access competitors. For New Entrants and Emerging Players: Establish a beachhead in pediatric scoliosis correction instrumentation, where specialized construct complexity limits integrated platform penetration. Target Eastern Province surgical centers in Dammam and Khobar, where navigation system underpenetration creates white space for robotic-assisted placement platforms. Partner with domestic manufacturers for SFDA localization compliance rather than building independent registration capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologics-augmented fusion specialists with rhBMP-2 formulation capabilities and patient-specific 3D-printed construct pipelines. Long-term viability hinges on navigation-robotics convergence mastery rather than commoditized fixation hardware. Watch SFDA clearance timelines for additive manufacturing pathways as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Localization Partnership | Domestic manufacturing joint ventures unlock Ministry of Health tender eligibility under Vision 2030 mandates. |
| Navigation-Robotics Convergence | Integrated platform bundling captures multi-year hospital contracts and displaces instrument-only vendors. |
| Pediatric Scoliosis Specialization | Complex deformity instrumentation generates disproportionate per-case revenue in Riyadh specialty centers. |
| RhBMP-2 Biologics Integration | Fusion procedure augmentation deepens margin pools through reimbursement premiums and technical complexity. |
| Eastern Province Expansion | Secondary hospital navigation system deployment captures outpatient spine procedure volume migration. |
Research Methodology
Desk research of SFDA medical device registration databases, Ministry of Health procurement tender records, and GCC harmonized standards documentation preceded structured interviews with spinal surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Primary fieldwork with tertiary care centers in Riyadh and Jeddah was cross-validated against secondary sources including SFDA adverse event reporting systems and Vision 2030 industrial policy frameworks. Bottom-up procedure volume estimates and top-down market sizing were triangulated to produce segment-level outputs.
Assumptions regarding SFDA registration pathway efficiency, titanium alloy input cost stability, and navigation system adoption curves were held fixed across the projection horizon, while localization partnership formation rates and pediatric specialty center expansion were varied in sensitivity scenarios. Segmentation modeling incorporated product type, user type, treatment approach, and clinical indication dimensions. CAGRs were derived from procedure volume growth rates and per-case device intensity trends, with biologics penetration and robotic-assisted placement adoption as key forecast inputs.
Stress conditions across titanium alloy price volatility, SFDA re-registration timeline extension, and neuro-navigation specialist training throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Ministry of Health capital allocation continuity and GCC regulatory harmonization progress. Material shifts in Vision 2030 localization enforcement or SFDA Class III implant evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market