
 Orthobiologics Market | 2026-2036
Orthobiologics Market Size, Share, and Industry Trends Forecast 2026-2036
Orthobiologics Market Analysis
North American manufacturing capacity for demineralized bone matrix and synthetic graft materials is reshaping supply availability for hospitals and specialty clinics. Zimmer Biomet Holdings, Inc. leverages its integrated tissue processing network to control raw material flows from donor recovery to finished sterile grafts. Medtronic plc anchors its position through sustained R&D spending on next-generation bone morphogenetic protein formulations. Stryker Corporation differentiates via proprietary carrier technologies that extend graft handling time in the surgical field.
Orthobiologics comprise biologically active materials derived from autologous, allogeneic, or synthetic sources, engineered to stimulate bone healing, cartilage repair, or soft tissue regeneration through osteoconductive, osteoinductive, or osteogenic mechanisms; these products typically incorporate collagen scaffolds, ceramic matrices, or living cell populations maintained within defined viability thresholds. Bone grafts occupy the largest revenue pool within product type segmentation, reflecting established reimbursement and surgeon familiarity, while stem cell therapies represent the fastest-expanding category as regulatory pathways for autologous cellular products mature across major jurisdictions. Within application segmentation, spine surgery generates the highest absolute consumption volumes, though wound healing applications are gaining traction as bioactive scaffolds demonstrate efficacy in diabetic ulcer management.
The FDA regulates orthobiologics through its Center for Devices and Radiological Health and Center for Biologics Evaluation and Research, with product classification determining whether 510(k), PMA, or BLA pathways apply; the EU Medical Device Regulation and its companion in vitro diagnostic framework impose additional clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. ISO 13485 quality management certification serves as a baseline expectation for supplier qualification by major hospital systems and group purchasing organizations. Stakeholders must monitor evolving FDA guidance on regenerative medicine advanced therapy designations and corresponding reimbursement negotiations with CMS and private payers.
Market Dynamics
Hospital procurement departments now prioritize cell-based bone graft substitutes as surgeons migrate toward minimally invasive spinal fusion techniques, compressing traditional allograft volumes while elevating premium biologic pricing power.
Growth Catalysts
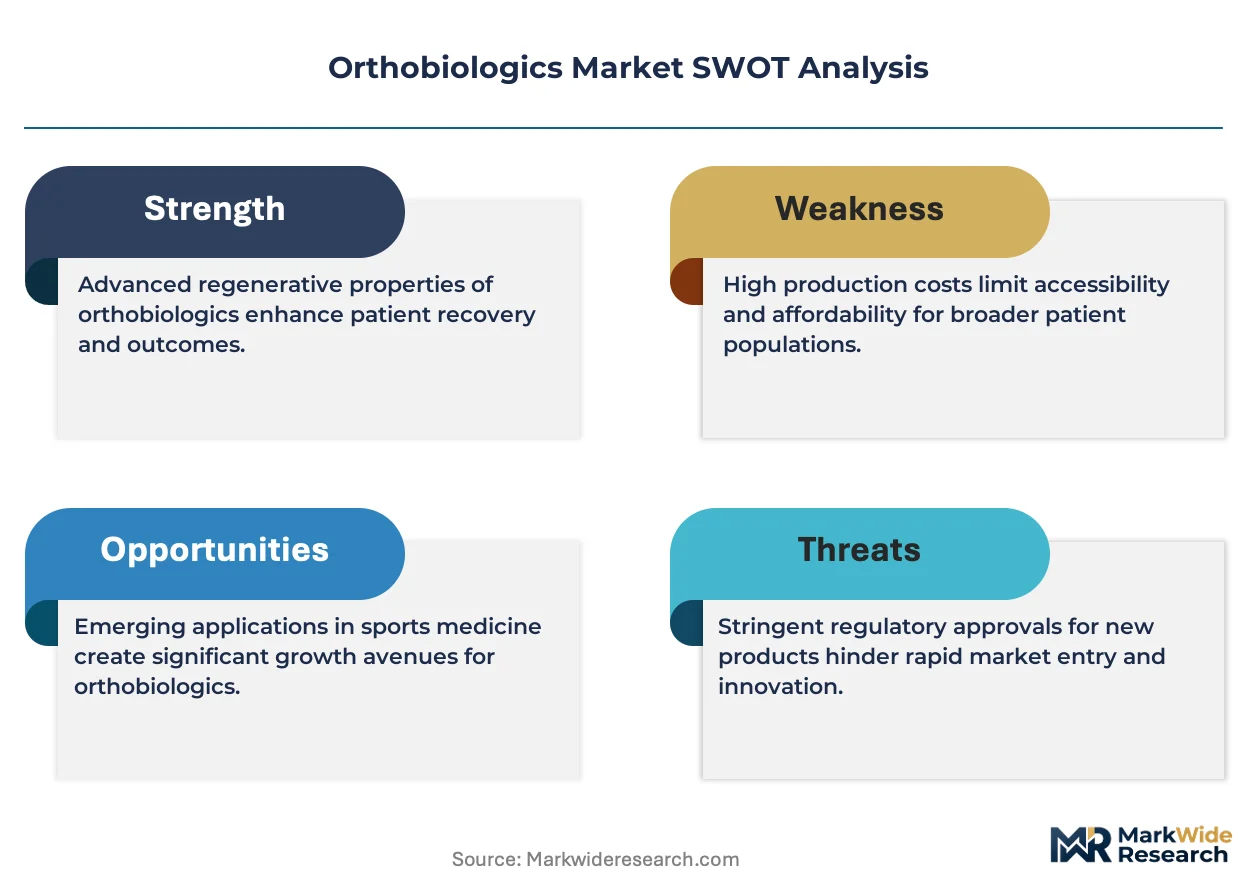
- FDA 510(k) pathway maturation:The FDA's streamlined clearance framework for combination products accelerates product development timelines and reduces regulatory uncertainty for manufacturers pursuing bone morphogenetic protein formulations.
- Ambulatory surgery center expansion:United States outpatient facilities now capture a rising share of orthobiologic procedures, creating dedicated demand for graft handling technologies that extend surgical field viability.
- Stem cell therapy regulatory convergence:Autologous cellular product pathways are maturing across major jurisdictions, enabling commercial scale-up of living cell populations for cartilage repair applications.
Market Restraints
- Allogeneic tissue supply concentration:North American tissue processing networks control donor recovery flows, creating single-source vulnerability for demineralized bone matrix availability.
- Reimbursement compression:CMS and private payer negotiations impose pricing ceilings on bone graft substitutes, constraining margin expansion despite rising clinical adoption.
- Synthetic ceramic substitution:Hydroxyapatite and beta-tricalcium phosphate formulations offer cost advantages in volume-sensitive hospital contracts, threatening premium biologic penetration.
Strategic Opportunities
- Diabetic ulcer wound healing:Bioactive scaffolds demonstrate efficacy in chronic wound management, opening reimbursement pathways outside traditional orthopedic surgery.
- EU MDR regulatory tailwind:The Medical Device Regulation's clinical evidence requirements favor established manufacturers with post-market surveillance infrastructure, consolidating competitive position.
- Point-of-care cell processing:Autologous concentration systems enable same-procedure bone marrow aspirate preparation, reducing logistics costs and cold-chain dependency.
Industry Challenges
- Viability maintenance logistics:Living cell products require controlled temperature transport and time-sensitive delivery, complicating distribution to rural surgical centers.
- ISO 13485 certification timelines:Quality management system audits for combination products extend supplier qualification periods, delaying new vendor onboarding by major group purchasing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthobiologics Market |
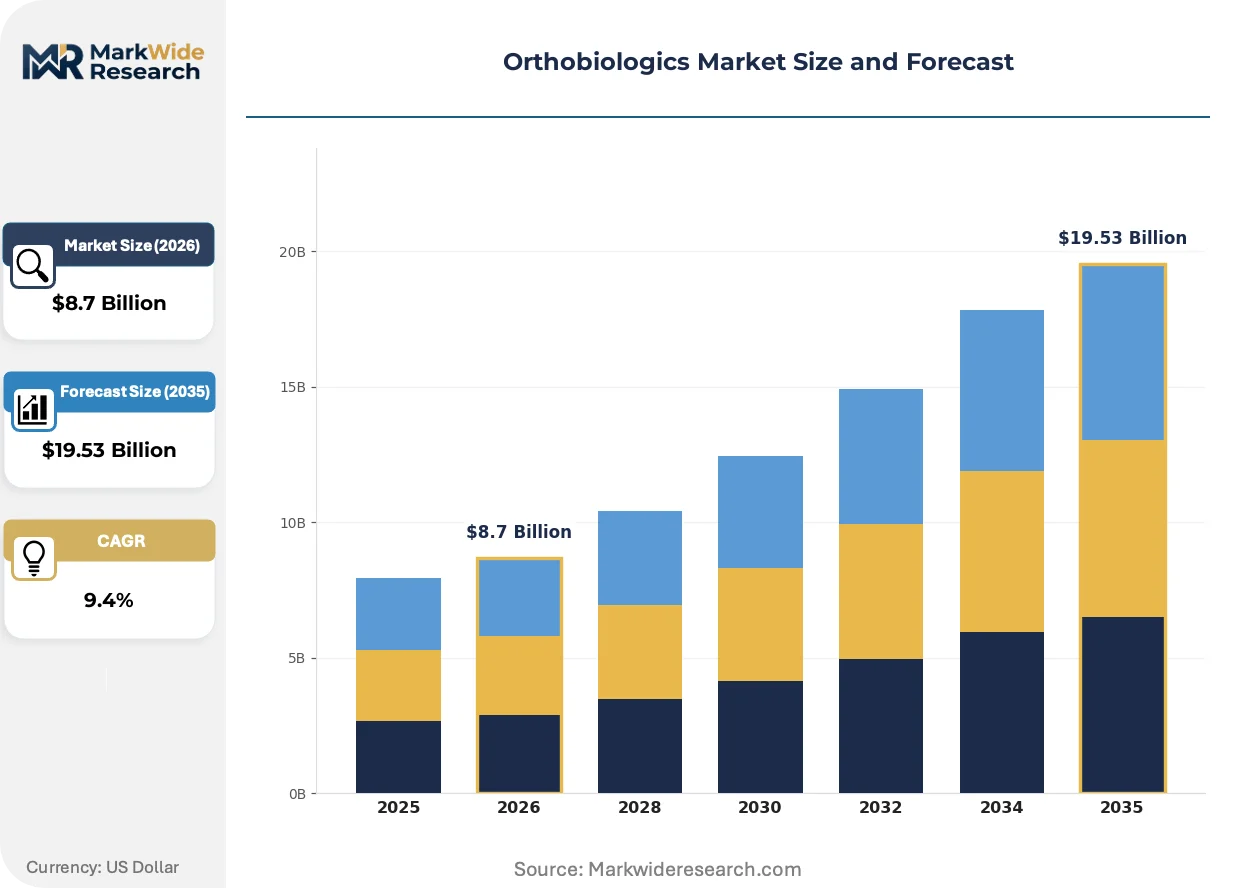
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
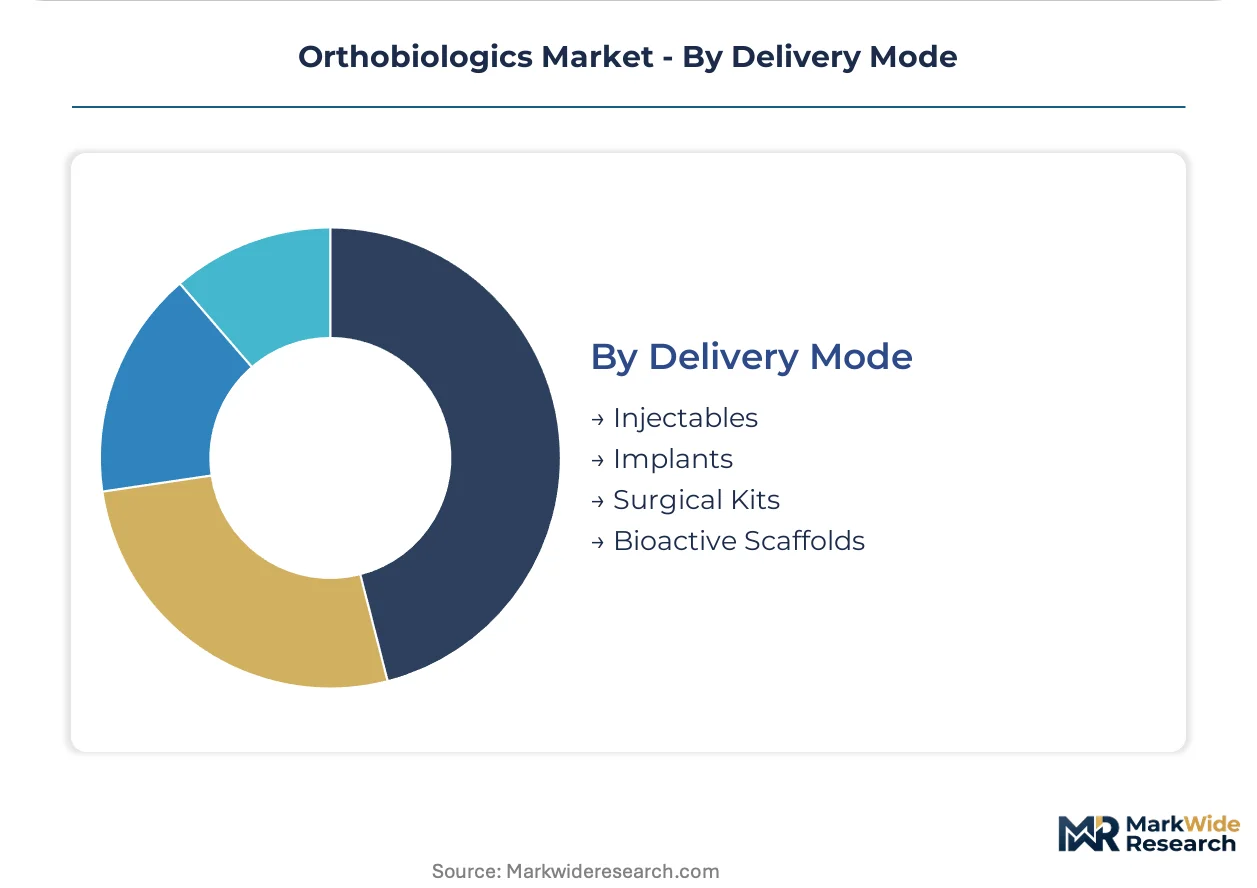
| Segmentation | Product Type: Bone Grafts, Stem Cells, Degradation Products, Growth Factors Application: Orthopedics, Spine Surgery, Wound Healing, Dental Surgery End User: Hospitals, Specialty Clinics, Research Institutes, Rehabilitation Centers Delivery Mode: Injectables, Implants, Surgical Kits, Bioactive Scaffolds |
| Companies Covered | Zimmer Biomet Holdings, Inc., Medtronic plc, Stryker Corporation, Johnson & Johnson, DePuy Synthes, Bioventus LLC, Arthrex, Inc., Globus Medical, Anika Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthobiologics Market Emerging Trajectories
Digital surgical planning and point-of-care biologic preparation are compressing traditional supply chain intermediaries while elevating real-time graft customization capabilities.
Three-dimensional bioprinting of patient-specific scaffolds is virtualizing preoperative graft design, enabling orthopedic surgeons to match implant geometry to individual defect morphology. Academic medical centers in the United States and Germany are piloting these systems for complex spinal reconstruction cases. The technology is virtualizing the role of off-the-shelf allograft distributors by collapsing design-to-implant timelines from weeks to hours.
EMA's evolving guidance on advanced therapy medicinal products is tightening clinical evidence requirements for stem cell-based orthobiologics seeking European market access. Manufacturers must now submit extended follow-up data on osteogenic outcomes, extending development timelines. Small and mid-sized developers are responding by prioritizing United States FDA submissions first, deferring European commercialization.
Surgeon preference for extended graft handling time is reshaping carrier technology specifications, with proprietary collagen and synthetic matrices displacing traditional hydration protocols. Ambulatory surgery centers in Florida and Texas are specifying minimum working time thresholds in procurement contracts. This behavioral shift favors integrated manufacturers with in-house biomaterial formulation capabilities over pure tissue processors.
Orthobiologics Market Segmentation
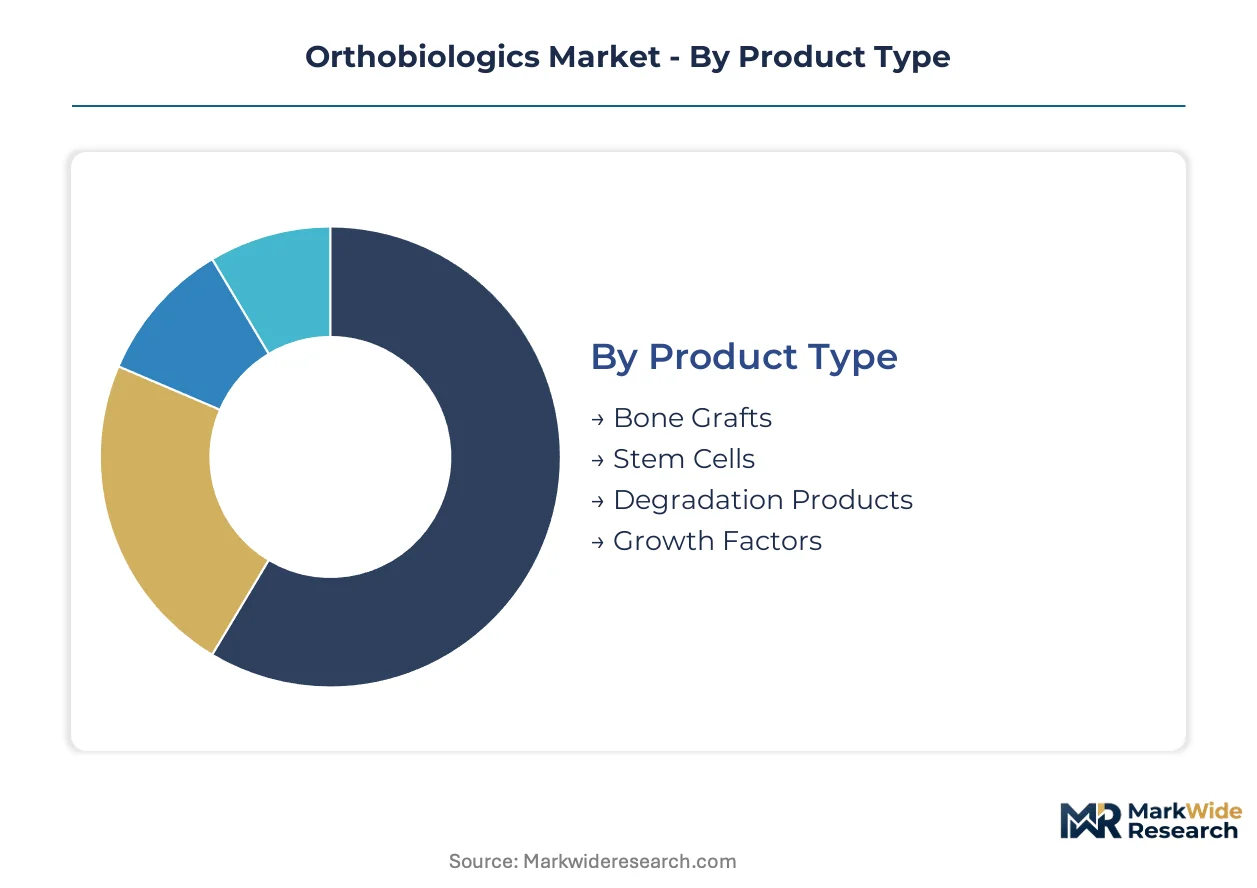
Orthobiologics segmentation reveals how procurement priorities diverge across surgical settings and patient acuity levels. Product type selection drives reimbursement coding complexity, while delivery mode specifications determine distribution infrastructure requirements.
Product Type:
Cost tier stratification separates established allograft commodities from premium cell-based alternatives commanding differentiated pricing power.
- Bone Grafts:Demineralized bone matrix and synthetic ceramic formulations provide osteoconductive scaffolding for spinal fusion and trauma repair. Hospital procurement in the United States prioritizes these products for high-volume orthopedic service lines, though reimbursement compression constrains margin expansion.
- Stem Cells:Autologous and allogeneic cellular therapies exploit osteogenic differentiation pathways to accelerate bone regeneration. Academic medical centers in Germany and the United States are piloting point-of-care concentration systems, reducing cold-chain logistics costs while maintaining viability thresholds.
- Degradation Products:Resorbable polymer carriers control release kinetics of bioactive agents during tissue remodeling.
- Growth Factors:Recombinant bone morphogenetic proteins deliver targeted osteoinductive signaling for non-union fractures.
Bone grafts hold installed capacity. Stem cells are rotating up the share rankings.
Application:
Procedure volume concentration varies dramatically by surgical specialty, with spine cases generating the highest absolute biologic consumption per operation.
- Spine Surgery:Minimally invasive fusion techniques intensify demand for cell-based bone graft substitutes that integrate through smaller access corridors. Ambulatory surgery centers in Texas and Florida now specify extended graft handling times in procurement contracts, favoring proprietary carrier technologies.
- Wound Healing:Bioactive scaffolds demonstrate efficacy in diabetic ulcer management, opening reimbursement pathways outside traditional orthopedic surgery. CMS coverage determinations for chronic wound applications are expanding addressable patient populations beyond surgical candidates.
- Orthopedics:Trauma and joint reconstruction applications leverage allograft availability for large-volume defect filling.
- Dental Surgery:Ridge augmentation and sinus lift procedures consume smaller graft volumes with premium pricing tolerance.
Spine surgery holds installed capacity. Wound healing is rotating up the share rankings.
End User:
Customer type determines procurement sophistication, with integrated delivery networks exercising greater vendor consolidation power than independent practices.
- Hospitals:Group purchasing organizations negotiate multi-year contracts for bone graft substitutes, leveraging case volume commitments against price ceilings. ISO 13485 certification serves as a non-negotiable supplier qualification threshold for system-wide approval.
- Specialty Clinics:Orthopedic and podiatric practices prioritize graft handling convenience and same-day availability over unit cost minimization. Point-of-care cell processing systems enable these settings to bypass traditional tissue bank intermediaries.
- Research Institutes:Academic medical centers pilot three-dimensional bioprinting systems for patient-specific scaffold fabrication.
- Rehabilitation Centers:Post-acute settings consume bioactive wound care products for pressure ulcer and surgical site management.
Hospitals hold installed capacity. Specialty clinics are rotating up the share rankings.
Delivery Mode:
Supply concentration characteristics differ by physical form, with liquid formulations requiring cold-chain infrastructure that solid implants bypass.
- Implants:Pre-formed demineralized bone matrix strips and synthetic ceramic wedges accommodate standardized defect geometries. Manufacturing capacity for these products concentrates in North American tissue processing networks controlling donor recovery flows.
- Injectables:Flowable graft materials enable percutaneous delivery in minimally invasive spine procedures. Surgeon preference for these formulations is compressing traditional allograft volumes while elevating premium biologic pricing power.
- Surgical Kits:Procedure-specific combinations streamline operating room workflow and reduce sterile field contamination risk.
- Bioactive Scaffolds:Engineered matrices combine structural support with controlled growth factor release for complex reconstruction cases.
Implants hold installed capacity. Injectables are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's role in orthobiologic distribution, connecting North American tissue processing networks to continental hospital systems through temperature-controlled pharmaceutical corridors.
United States
Ambulatory surgery centers in Texas and Florida are specifying extended graft handling times in procurement contracts, compressing traditional allograft volumes while elevating premium biologic pricing power. FDA's 510(k) clearance framework for combination products continues shaping product development timelines and clinical evidence requirements. The Greater Boston corridor anchors academic medical center pilot programs for three-dimensional bioprinting of patient-specific scaffolds.
Germany
Academic medical centers in Munich and Berlin are piloting point-of-care cell processing systems that reduce cold-chain logistics costs while maintaining viability thresholds for autologous therapies. EMA's evolving guidance on advanced therapy medicinal products is tightening clinical evidence requirements for stem cell-based orthobiologics seeking European market access. The Baden-Württemberg medical technology cluster concentrates manufacturing capacity for proprietary carrier technologies.
Switzerland
Swissmedic's regulatory pathway for combination products attracts developers seeking parallel FDA-European submission strategies, compressing time-to-market for bone morphogenetic protein formulations. The country's precision manufacturing base supports ISO 13485-certified suppliers qualifying for major hospital system contracts. Basel's pharmaceutical corridor hosts specialized logistics providers maintaining controlled-temperature transport for living cell products.
Japan
PMDA's regenerative medicine framework is maturing pathways for autologous cellular products, enabling commercial scale-up of living cell populations for cartilage repair applications. METI's industrial policy prioritizes biomaterial formulation capabilities within the Osaka-Kobe medical device cluster. Tokyo's academic hospitals are specifying minimum working time thresholds for graft handling technologies in procurement contracts.
India
CDSCO's evolving regulatory stance on allogeneic tissue products is creating qualification pathways for demineralized bone matrix imports while domestic tissue processing networks develop. The Maharashtra pharmaceutical corridor is attracting contract manufacturers seeking ISO 13485 certification for supplier qualification by international group purchasing organizations. Bangalore's medical technology cluster is piloting cost-advantaged synthetic ceramic formulations for volume-sensitive hospital contracts.
Orthobiologics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in tissue processing and carrier formulation. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with integrated tissue networks, mid-cap biologic specialists with proprietary carrier technologies, and emerging point-of-care cell processing developers. Dominant competitive moves include backward integration into donor recovery flows and technology licensing agreements for extended graft handling formulations.
Among diversified platform operators, Zimmer Biomet Holdings, Inc., Medtronic plc, and Stryker Corporation occupy positions that exemplify the integrated tissue processing archetype. Zimmer Biomet represents captive supply chain control from donor recovery through finished sterile grafts. Medtronic anchors sustained research and development positioning on next-generation bone morphogenetic protein formulations. Stryker exemplifies differentiation through proprietary carrier technologies that extend graft handling time specifications demanded by ambulatory surgery center procurement contracts.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Medtronic plc |
| Stryker Corporation |
| Johnson & Johnson |
| DePuy Synthes |
| Bioventus LLC |
| Arthrex, Inc. |
| Globus Medical |
| Anika Therapeutics, Inc. |
| Others |
Supply Flow & Price Mechanics
North American tissue processing networks controlling donor recovery flows anchor margin capture downstream through captive supply of demineralized bone matrix to hospital systems and group purchasing organizations. Premium biologic pricing power concentrates with integrated manufacturers possessing in-house biomaterial formulation capabilities, while synthetic ceramic substitutes erode margin pools in volume-sensitive contracts.
Pricing Analysis
FDA's 510(k) clearance framework dictates the pricing tier structure across premium cell-based grafts, standard allograft commodities, and economy synthetic formulations. Three-tier pricing structure across premium, standard, and economy levels separates proprietary carrier technologies with extended handling times from hydration-dependent traditional products. Cost compression in standard allograft tiers is intensifying because hydroxyapatite and beta-tricalcium phosphate formulations win volume-sensitive hospital contracts. Ambulatory surgery centers in Texas and Florida demonstrate least price sensitivity, prioritizing graft handling convenience and minimum working time thresholds over unit cost minimization.
Supply Chain Analysis
Extended payment terms from integrated delivery networks and supply-chain finance facilities from specialized healthcare distributors shape working capital requirements for tissue processors. Manufacturing capacity for demineralized bone matrix and synthetic graft materials concentrates in the United States, Germany, and Switzerland, with North American tissue banks controlling donor recovery flows. Raw material dependencies center on allogeneic tissue donations, collagen scaffolds, and ceramic precursors. Single-source vulnerability in allogeneic tissue supply creates structural risk for manufacturers without diversified donor network contracts. Distribution runs through temperature-controlled pharmaceutical corridors connecting tissue processing facilities to hospital systems and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthobiologics sits in early-cycle expansion as ambulatory surgery center adoption of minimally invasive spinal fusion techniques accelerates demand for premium cell-based graft substitutes beyond traditional allograft penetration rates.
For Market Incumbents: Pre-empt synthetic ceramic substitution threats by deepening backward integration into proprietary carrier technology development and securing exclusive supply agreements with high-volume ambulatory surgery center networks. Prioritize ISO 13485 certification maintenance and point-of-care cell processing system deployment to defend against mid-cap biologic specialists with differentiated handling time specifications.
For New Entrants and Emerging Players: Pursue diabetic ulcer wound healing applications as the most penetrable segment, exploiting expanding CMS coverage determinations for chronic wound management outside traditional orthopedic surgery. Target specialty clinics in Florida and Texas with same-day availability value propositions and point-of-care autologous concentration systems that bypass traditional tissue bank intermediaries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap biologic specialists possessing proprietary carrier formulations but lacking integrated tissue processing networks. Long-term viability hinges on regulatory pathway maturation for autologous cellular products across FDA and EMA jurisdictions. Watch EMA's evolving guidance on advanced therapy medicinal products as the inflection signal for European commercialization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Cell Processing Deployment | Reduces cold-chain logistics costs for autologous therapies at ambulatory surgery centers. |
| Proprietary Carrier Technology Development | Extends graft handling times to meet Texas and Florida procurement contract specifications. |
| Diabetic Ulcer Reimbursement Strategy | Opens CMS coverage pathways for bioactive scaffolds beyond traditional orthopedic surgery. |
| EU MDR Clinical Evidence Buildout | Consolidates competitive position for established manufacturers with post-market surveillance infrastructure. |
| Three-Dimensional Bioprinting Pilot Programs | Virtualizes preoperative graft design for complex spinal reconstruction at academic medical centers. |
Methodological Framework
A standing panel of orthopedic surgeons, hospital procurement managers, GPO contracts specialists, and biomedical engineers provided ongoing calibration across the study period. Primary interviews with tissue processing executives and regulatory affairs leads combined with secondary validation from FDA 510(k) filings, EMA submission databases, hospital procurement contracts, and CMS coverage determinations. Bottom-up demand modeling across product type, application, end user, and delivery mode segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Scenario-bracketing framed analytical approach across the analysis window, with volume and value outputs reflecting segmentation by product tier, surgical specialty, facility type, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and technology substitution curves. Forecast inputs incorporated ambulatory surgery center expansion rates, stem cell therapy regulatory pathway maturation, and synthetic ceramic penetration thresholds in volume-sensitive contracts.
Sensitivities concentrate around FDA guidance evolution on regenerative medicine advanced therapy designations, EMA clinical evidence requirement tightening, and CMS reimbursement compression for bone graft substitutes. Forecasts reflect documented assumptions regarding surgeon adoption curves, tissue supply availability, and competitive technology substitution dynamics. Macroeconomic contraction affecting elective procedure volumes, regulatory pathway delays for combination products, or breakthrough synthetic graft efficacy demonstrations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Personalized Orthopaedic Implant Market