
 Global Orthopedic Navigation Systems Market | 2026-2036
Global Orthopedic Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Navigation Systems Market Foresight
Multi-source component procurement is repositioning supply strategies across orthopedic navigation manufacturing. Stryker leverages captive optical sensor production to secure margin control over its navigation platforms. Zimmer Biomet sustains broad hospital system relationships that anchor its installed base across joint replacement applications. Medtronic competes through deep spine surgery integration, where its navigation systems pair with implant portfolios.
Orthopedic navigation systems are computer-assisted platforms that track surgical instrument position relative to patient anatomy using optical, electromagnetic, or image-guided tracking technologies, typically achieving sub-millimeter accuracy to guide implant placement and bone resection. These systems serve primarily to reduce mechanical alignment errors, lower revision surgery rates, and enable minimally invasive approaches in complex orthopedic procedures. Computer-assisted surgery occupies the largest revenue share among product types due to its established clinical validation and broad compatibility with existing OR infrastructure. Robotic-assisted surgery represents the fastest-expanding segment, driven by capital investment from hospital networks seeking differentiation in joint replacement programs. Image-guided navigation commands premium pricing in spine applications, where fluoroscopy reduction and screw placement accuracy justify higher system costs.
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and market access costs for navigation system manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain design choices and international commercialization strategies. Stakeholders must monitor evolving CMS reimbursement determinations for computer-assisted orthopedic procedures, as coverage decisions will directly influence hospital capital allocation and adoption velocity across outpatient settings.
Market Dynamics
Hospital procurement committees now prioritize total cost of ownership over capital expenditure, forcing navigation system vendors to restructure pricing around per-procedure economics and bundled service agreements rather than upfront hardware sales.
Growth Catalysts
- EU MDR conformity requirements:Stricter CE marking obligations under the EU Medical Device Regulation are accelerating replacement cycles for legacy navigation platforms across German and French hospital networks.
- Ambulatory surgical centers:Rising procedural volumes in United States outpatient settings are expanding the addressable base for compact, mobile navigation systems designed for same-day discharge protocols.
- Optical tracking miniaturization:Advances in infrared camera array design are reducing system footprints and enabling integration into standard operating room configurations without structural renovation.
Market Restraints
- High-precision optical sensor supply:Concentrated manufacturing of position-tracking cameras in East Asian component hubs creates vulnerability to geopolitical trade friction and export control disruptions.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for software-heavy navigation platforms now require extensive clinical validation, extending time-to-market by twelve to eighteen months.
- Fluoroscopy-based alternatives:Conventional C-arm imaging retains cost advantages in spine procedures at community hospitals, limiting navigation penetration in price-sensitive acute care segments.
Strategic Opportunities
- Japan's super-aged society:METI healthcare infrastructure investments targeting centenarian population clusters are subsidizing navigation system deployment in regional orthopedic centers.
- Software-as-a-service models:Subscription-based navigation licensing is converging with cloud-based surgical planning platforms, reducing capital barriers for mid-tier United States health systems.
- India's PLI scheme:Production-linked incentives for medical electronics manufacturing are attracting contract assembly partners to establish navigation component fabrication within the country.
Industry Challenges
- Electromagnetic interference mitigation:Operating room densification with multiple powered devices complicates calibration of magnetic tracking systems, requiring specialized engineering support.
- ISO 13485 audit readiness:Maintaining quality management system certification across distributed software development teams strains documentation resources for emerging navigation vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Navigation Systems Market |
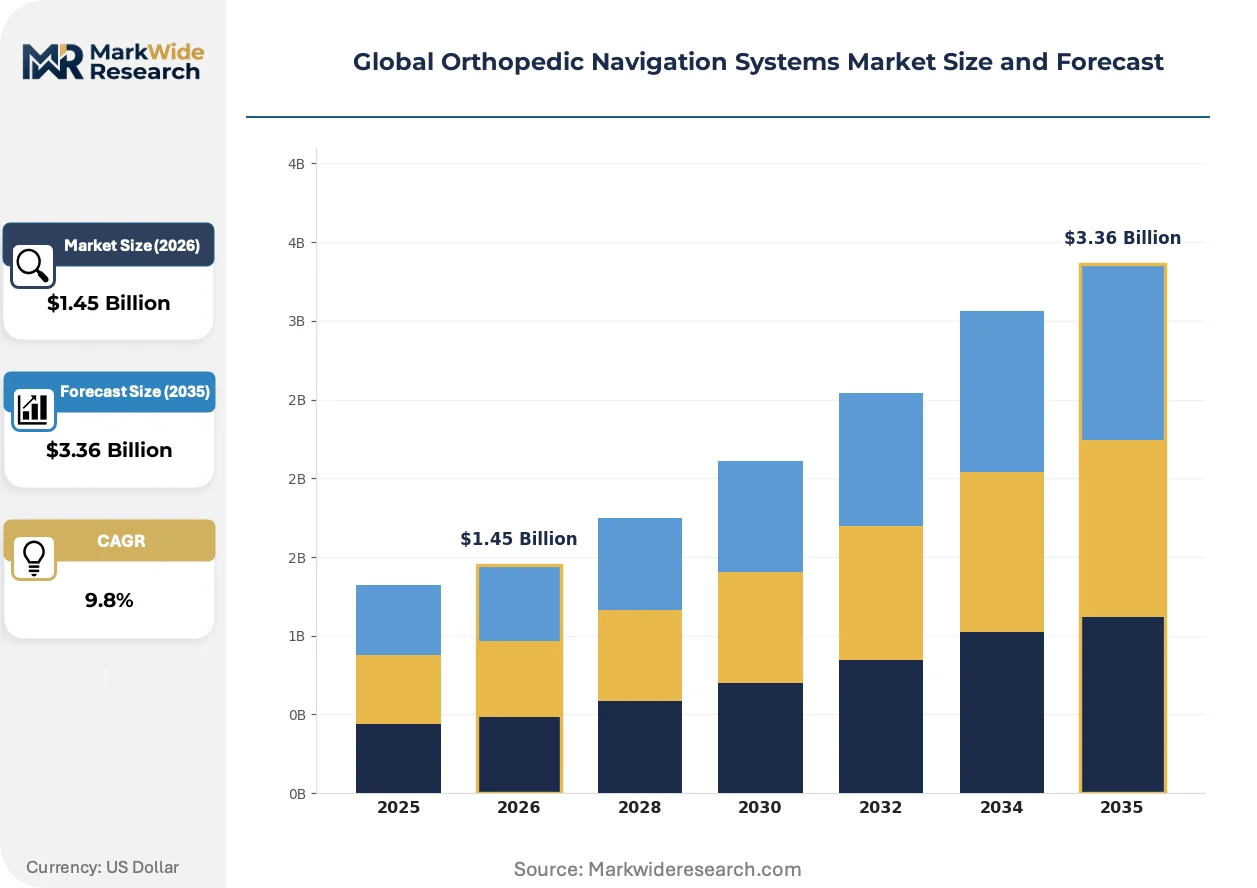
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computer-assisted Surgery, Robotic-assisted Surgery, Fluoroscopic Navigation, Electromagnetic Navigation End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Optical Navigation, Image-guided Navigation, Intraoperative CT, Ultrasound Navigation Application: Joint Replacement, Spine Surgery, Trauma Surgery, Sports Medicine |
| Companies Covered | Smith+Nephew, DePuy Synthes, Stryker, Amplitude Surgical, Globus Medical, Zimmer Biomet, B. Braun SE, Kinamed Incorporated, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Navigation Systems Market Shifts & Advancements
Navigation platforms are evolving from standalone hardware into interconnected surgical ecosystems, with artificial intelligence, augmented reality, and cloud analytics embedding throughout the procedure workflow.
Machine learning algorithms trained on intraoperative kinematic data are converging with real-time bone registration to predict optimal implant positioning before resection occurs. Academic medical centers in the United States and Germany are piloting these predictive modules during total knee arthroplasty. This convergence is compressing the learning curve for junior surgeons and reducing case-to-case alignment variability.
EU MDR post-market surveillance requirements now mandate systematic collection of real-world performance data for Class IIb and Class III navigation systems. Manufacturers must establish periodic safety update reports and trend analysis protocols. Spine navigation platforms face the steepest compliance burden, as screw placement accuracy metrics must be tracked across diverse hospital IT environments.
Hospital procurement committees increasingly unbundle navigation hardware from proprietary implant contracts, forcing vendors to compete on standalone system performance. United States integrated delivery networks are leading this disintermediation, leveraging scale to negotiate à la carte pricing. Orthopedic service line administrators now benchmark navigation accuracy specifications independently of instrument tray commitments.
Global Orthopedic Navigation Systems Market Segmentation
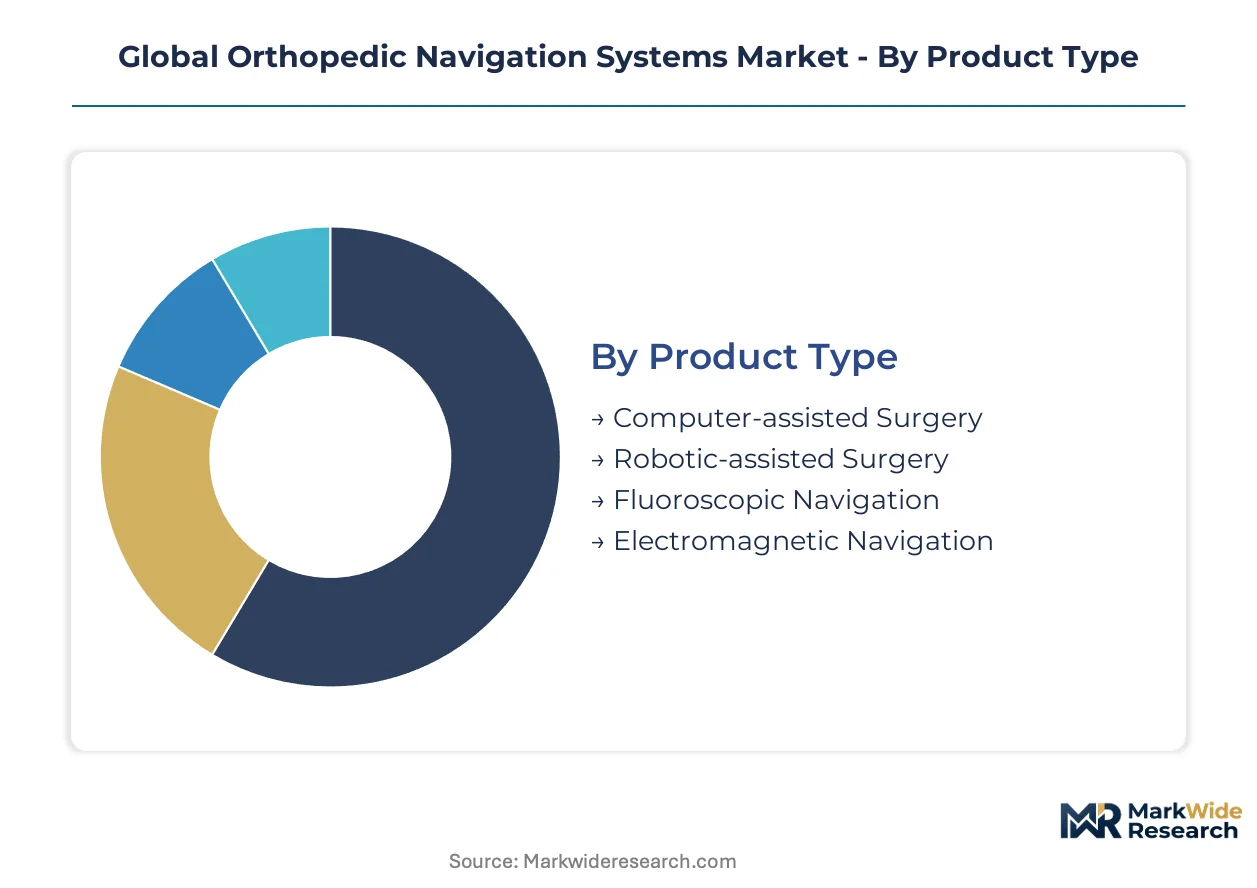
Orthopedic navigation systems segment across multiple technical and commercial dimensions, each carrying distinct upgrade cycles and procurement criteria. Hospital capital committees evaluate these categories through different lenses: capital intensity, OR footprint, and compatibility with existing surgical workflows.
Product Type:
Replacement cycles vary sharply across product categories, with legacy electromagnetic platforms facing accelerated obsolescence as optical and robotic systems displace installed bases.
- Computer-assisted Surgery:Software-driven platforms integrating preoperative imaging with intraoperative instrument tracking via optical arrays or electromagnetic sensors. Demand concentrates in German university hospitals and United States academic medical centers where alignment accuracy studies justify capital expenditure despite longer procedure times.
- Robotic-assisted Surgery:Active or semi-active robotic arms executing bone resection under surgeon supervision, typically paired with proprietary navigation software. United States integrated delivery networks are expanding fastest here, attracted by marketing differentiation in crowded joint replacement markets and bundled payment optimization.
- Fluoroscopic Navigation:C-arm integrated systems providing real-time 2D/3D imaging overlay for instrument guidance. Japanese regional orthopedic centers favor these for spine applications where capital constraints limit full robotic adoption.
- Electromagnetic Navigation:Magnetic field-based tracking without line-of-sight requirements, enabling smaller hardware footprints. India's emerging private hospital chains are deploying these in price-sensitive trauma applications where OR space is limited.
Volume placements concentrate in Computer-assisted Surgery; the faster expansion belongs to Robotic-assisted Surgery.
End User:
Procurement authority and reimbursement pathways diverge meaningfully across care settings, shaping vendor sales strategies and system configuration requirements.
- Hospitals:Tertiary and community facilities with dedicated orthopedic service lines, typically purchasing through multi-year capital equipment cycles. German hospital federations negotiate centralized procurement for navigation platforms, extracting volume discounts across regional networks.
- Ambulatory Surgical Centers:Outpatient facilities performing same-day joint replacement and arthroscopy. United States ASCs are expanding navigation adoption fastest as CMS reimbursement shifts favor lower-acuity settings and compact, mobile systems reduce per-case overhead.
- Orthopedic Clinics:Specialized facilities focused on sports medicine and minor joint procedures. These settings in Japan's urban corridors increasingly lease navigation capabilities through equipment-as-a-service arrangements.
- Rehabilitation Centers:Post-acute facilities occasionally deploying navigation for revision assessment or preoperative planning. Demand here remains nascent, constrained by limited surgical volume and capital access.
Revenue concentration sits with Hospitals; Ambulatory Surgical Centers are climbing the fastest.
Technology:
Technical performance specifications and integration complexity create distinct margin profiles across tracking modalities.
- Optical Navigation:Infrared camera arrays tracking reflective markers on instruments and bone references, achieving sub-millimeter accuracy in standard OR lighting. United States spine surgery departments prioritize these for pedicle screw placement where electromagnetic interference from powered instruments degrades alternative systems.
- Image-guided Navigation:Preoperative CT or MRI fused to intraoperative anatomy via registration algorithms. German trauma centers command premium pricing here for complex pelvic fracture repair where 3D anatomical visualization reduces revision rates.
- Intraoperative CT:Mobile CT scanners integrated with navigation software for real-time anatomical verification. Japanese super-aged regional hospitals are piloting these for osteoporotic spine surgery where preoperative imaging inadequately captures bone quality.
- Ultrasound Navigation:Sonography-based tracking for soft tissue visualization and bone surface mapping. Sports medicine applications in United States collegiate athletic programs favor these for shoulder arthroscopy where radiation exposure concerns limit fluoroscopy.
Installed base dominance belongs to Optical Navigation; Image-guided Navigation is gaining share fastest.
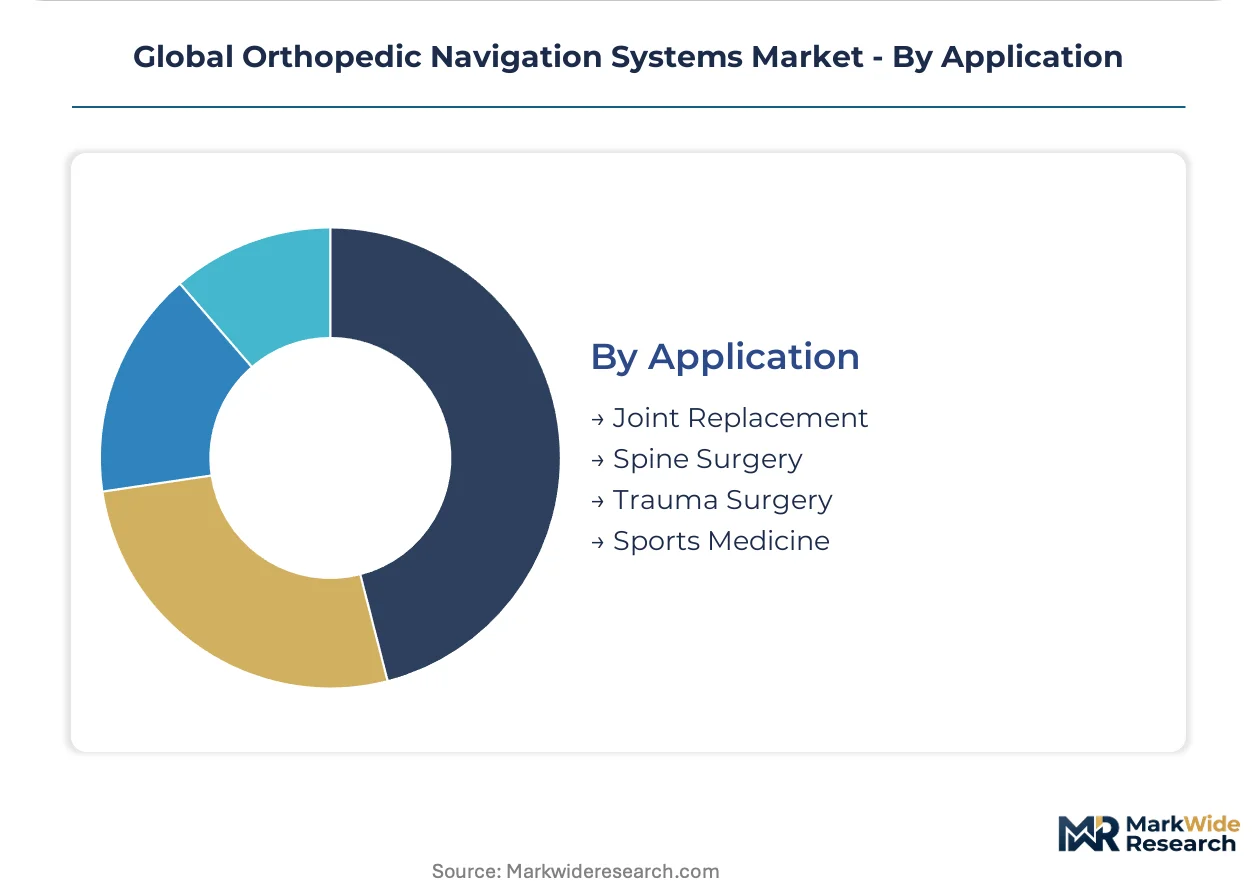
Application:
Clinical evidence depth and reimbursement specificity vary dramatically across surgical specialties, filtering which navigation technologies achieve viable adoption.
- Joint Replacement:Total knee and hip arthroplasty procedures where mechanical alignment directly impacts implant longevity. United States hospital networks with bundled payment contracts for joint episodes are expanding navigation deployment to reduce costly revision burden.
- Spine Surgery:Pedicle screw fixation, deformity correction, and tumor resection requiring sub-millimeter accuracy near neural structures. German spine centers lead European adoption here, driven by medicolegal pressure around screw misplacement complications.
- Trauma Surgery:Fracture reduction and fixation in acute settings where navigation must integrate with fluoroscopy and external fixation. India's tier-2 private hospitals are emerging users as PLI scheme subsidies reduce equipment import costs.
- Sports Medicine:Ligament reconstruction and cartilage repair procedures demanding anatomical precision with minimal invasiveness. Japanese professional baseball team medical facilities have become reference sites for shoulder navigation in throwing athletes.
Procedure volume concentrates in Joint Replacement; Spine Surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical sensor fabrication clusters in East Asia anchor component supply for navigation system assembly, while demand concentrates in aging economies with established surgical infrastructure and reimbursement pathways for computer-assisted procedures.
United States
Integrated delivery networks in Texas and the Midwest are expanding robotic navigation deployment to optimize bundled payment contracts for joint replacement episodes. FDA 510(k) clearance timelines for software-heavy platforms now extend twelve to eighteen months, elevating compliance costs for new entrants. The Greater Boston corridor hosts reference sites for machine learning-enhanced navigation in academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia command premium pricing for image-guided navigation in complex pelvic trauma and spine deformity correction. EU MDR post-market surveillance mandates now require systematic tracking of screw placement accuracy metrics across diverse hospital IT environments. The Baden-Württemberg industrial belt concentrates optical component engineering talent serving navigation OEMs.
Japan
Regional orthopedic centers in Chubu and Kyushu are piloting intraoperative CT navigation for osteoporotic spine surgery under METI healthcare infrastructure subsidies targeting centenarian population clusters. PMDA consultation procedures for novel tracking algorithms are compressing premarket review cycles for domestic manufacturers. Osaka-based hospital networks are establishing equipment-as-a-service arrangements for compact navigation platforms.
India
Tier-2 private hospitals in Maharashtra and Gujarat are deploying electromagnetic navigation systems for trauma applications as PLI scheme subsidies reduce equipment import costs. CDSCO medical device registration requirements are harmonizing with ASEAN standards to accelerate market access for multinational vendors. The Karnataka medical technology corridor is attracting contract assembly partners for navigation component fabrication.
United Kingdom
NHS England integrated care systems in the Midlands and North England are negotiating centralized procurement for computer-assisted surgery platforms to standardize alignment protocols across joint replacement pathways. MHRA recognition of EU MDR certifications is maintaining market access continuity post-Brexit. The Oxford-Cambridge arc hosts clinical validation studies for augmented reality navigation in minimally invasive hip procedures.
Global Orthopedic Navigation Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to unbundle hardware from proprietary implant contracts and reposition around per-procedure economics. The vendor base concentrates among diversified medtech conglomerates with captive surgical implant portfolios, mid-scale navigation specialists, and emerging robotics platforms. Three archetypes define positioning: integrated implant-navigation bundlers, standalone accuracy-technology vendors, and capital-light software licensors. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping market structure.
Among diversified medtech conglomerates, Stryker, Zimmer Biomet, and Medtronic exemplify distinct strategic postures. Stryker occupies a position anchored in captive optical sensor production and deep hospital system relationships. Zimmer Biomet represents the implant-navigation bundling archetype with broad installed base penetration across joint replacement applications. Medtronic sits within the spine-focused integration tier, where navigation platforms pair with implant portfolios to serve deformity correction and tumor resection workflows.
| Leading Market Players |
|---|
| Smith+Nephew |
| DePuy Synthes |
| Stryker |
| Amplitude Surgical |
| Globus Medical |
| Zimmer Biomet |
| B. Braun SE |
| Kinamed Incorporated |
| Medtronic |
| Others |
Supply & Pricing Matrix
United States integrated delivery networks and German hospital federations concentrate procurement authority, anchoring contract-based long-term offtake agreements that bundle navigation hardware with multi-year service commitments and per-procedure analytics licensing.
Pricing Analysis
Warranty coverage and software maintenance bundling separate premium navigation platforms from unbundled economy alternatives where service contracts carry separate negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and optical tracking accuracy specifications. Cost compression in economy tiers intensifies because India's PLI scheme subsidizes domestic assembly, eroding import price premiums. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German university hospitals prioritize accuracy specifications over unit economics.
Supply Chain Analysis
India's PLI scheme and local-content mandates for medical electronics manufacturing are redirecting contract assembly partners toward domestic navigation component fabrication, reducing reliance on East Asian optical sensor hubs. High-precision infrared camera arrays and electromagnetic field generators draw from concentrated production in Japan, Germany, and South Korea. Single-source vulnerability in position-tracking camera supply creates exposure to export control disruptions. Distribution runs through orthopedic implant distributors with captive navigation specialists and direct hospital system contracts for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigation system vendors face a vertical-integration race where captive optical sensor production and proprietary software ecosystems determine margin control and customer lock-in durability.
For Market Incumbents: Extend cloud-based surgical planning platform integration to deepen software subscription revenue and reduce hardware replacement cycle dependency. Consolidate optical component supply through backward integration into infrared camera array manufacturing, countering emerging robotics platforms that threaten standalone navigation margins. Fortify ISO 13485 audit readiness across distributed development teams to accelerate EU MDR conformity timelines.
For New Entrants and Emerging Players: The gap between premium robotic-assisted systems and economy electromagnetic platforms opens white-space opportunity in India's tier-2 private hospitals and United States ambulatory surgical centers. Target trauma applications in price-sensitive markets where OR space constraints favor compact magnetic tracking. Pursue equipment-as-a-service arrangements with Japanese orthopedic clinics to bypass capital expenditure barriers.
For Investors and Strategic Acquirers: The window for entry favors software-centric navigation specialists with FDA 510(k) clearance momentum and cloud analytics capabilities over hardware-heavy legacy platforms. Long-term viability hinges on recurring revenue models displacing upfront capital sales. Monitor CMS reimbursement determinations for computer-assisted orthopedic procedures as the critical inflection signal for hospital capital allocation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity accelerates replacement cycles across German and French hospital networks. |
| Hospital System Partnership | United States integrated delivery networks negotiate à la carte navigation pricing unbundled from implants. |
| Software Companion Development | Machine learning modules for predictive implant positioning compress surgeon learning curves in academic centers. |
| Reimbursement Strategy | CMS coverage decisions for computer-assisted procedures directly influence outpatient adoption velocity. |
| FDA Submission | 510(k) clearance timelines for software-heavy platforms now extend twelve to eighteen months. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital purchasing committees, biomedical engineers, GPO contracts managers, and orthopedic service line administrators. FDA 510(k) databases, EU MDR notified body certificates, CMS Medicare reimbursement schedules, and hospital procurement databases supplied validation layers. Bottom-up installation base modeling and top-down capital expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across optical navigation, robotic-assisted surgery, and electromagnetic tracking segments calibrated penetration assumptions over the projection horizon. Technology type, application specialty, end-user setting, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from procedure volume trajectories, replacement cycle analysis, and capital intensity benchmarks specific to ambulatory surgical center expansion and super-aged society infrastructure investments.
Underlying measurement precision varies by segment; robotic-assisted surgery and image-guided navigation carry tighter precision than legacy electromagnetic platforms due to clearer installation tracking. Forecasts reflect documented assumptions around reimbursement pathway stability, regulatory clearance timelines, and component supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Orthopaedic Cushions Market