
 Animal External Fixation Market | 2026-2036
Animal External Fixation Market Size, Share, and Industry Trends Forecast 2026-2036
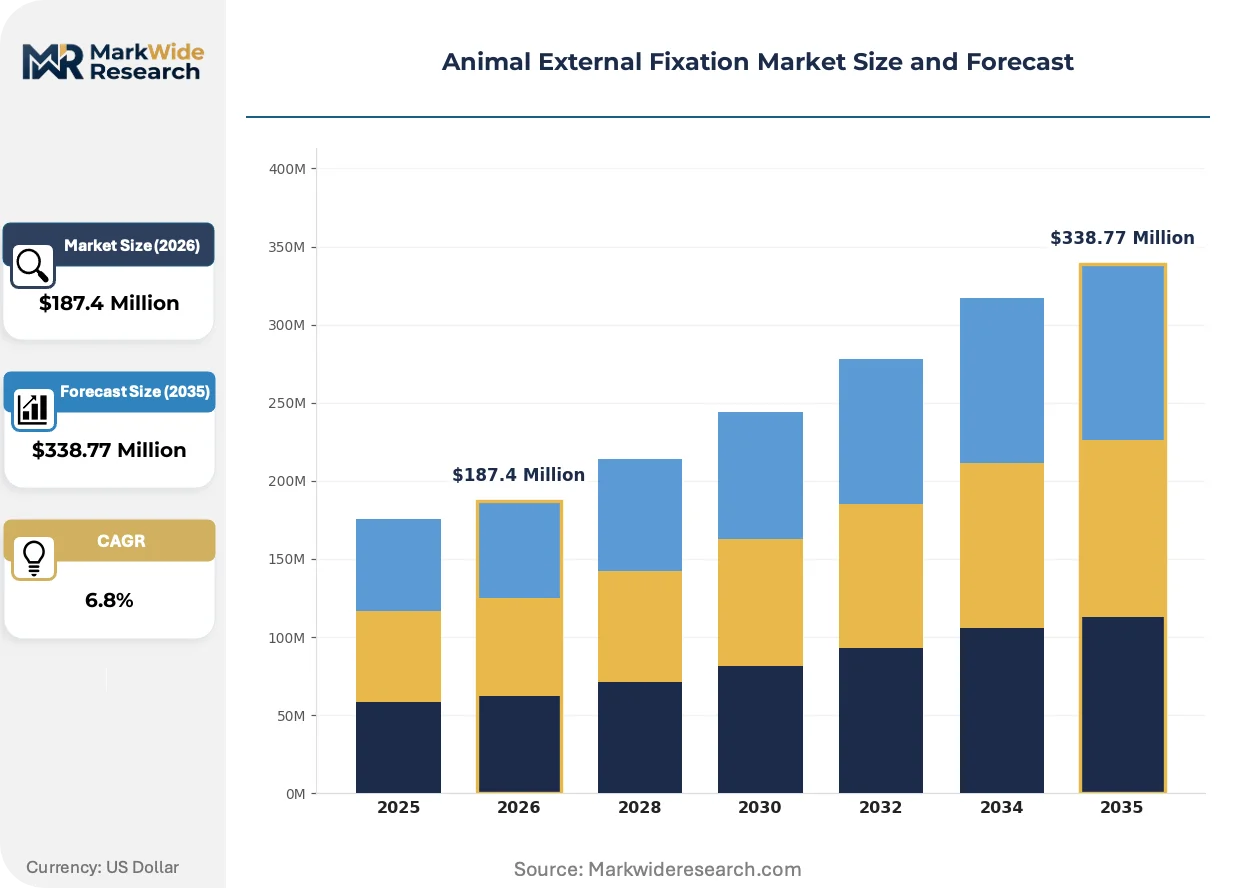
Animal External Fixation Market Outlook
North American manufacturing expansion is rewriting supply dynamics for precision veterinary orthopedic hardware. DePuy Synthes leverages its human orthopedic heritage to dominate titanium alloy processing for veterinary applications. IMEX Veterinary anchors its position through specialized linear fixator systems designed for equine and companion animal limb reconstruction. Kyon AG differentiates via proprietary locking plate technology that extends into external fixation hybrid configurations.
Animal external fixation comprises skeletal stabilization apparatus employing percutaneous pins connected to external frames, typically constructed from stainless steel or carbon fiber with pin diameters ranging from 1.6mm to 4.0mm depending on patient species and bone dimension. These systems enable gradual correction of angular limb deformities, fracture stabilization, and limb lengthening without implant burial, reducing secondary surgery requirements for hardware removal. Ring fixators occupy the premium tier due to complex assembly protocols and specialized surgeon training requirements, while linear fixators capture volume through simplified application in general veterinary practice. Titanium alloy commands pricing power where corrosion resistance and magnetic resonance imaging compatibility justify material cost premiums over standard stainless steel alternatives.
The FDA Center for Veterinary Medicine enforces biocompatibility and sterility standards that shape product development timelines and market entry costs for implantable veterinary devices. ISO 10993 biological evaluation protocols increasingly influence purchasing decisions at university veterinary teaching hospitals and specialty referral centers. Stakeholders must monitor evolving reimbursement frameworks for advanced veterinary surgical procedures as pet insurance penetration expands and owner willingness to fund complex orthopedic interventions shifts demand trajectories across practice tiers.
Market Dynamics
Veterinary specialty hospitals are consolidating purchasing power and demanding titanium-compatible imaging workflows, compressing margins for stainless steel fixator suppliers while elevating technical certification requirements across the supply base.
Growth Catalysts
- ISO 10993 Biological Evaluation:University veterinary teaching hospitals now mandate full biocompatibility testing suites for implantable devices, creating procurement preference for certified manufacturers.
- Equine Sports Medicine:Thoroughbred racing and show jumping disciplines drive demand for limb-lengthening ring fixators capable of gradual angular correction.
- Pet Insurance Penetration:Rising coverage rates for complex orthopedic procedures enable owners to fund external fixation surgeries previously deferred due to cost constraints.
Market Restraints
- Titanium Alloy Supply Concentration:Aerospace and human medical sectors dominate titanium bar stock allocation, creating input scarcity for veterinary device fabricators.
- Specialized Surgeon Training:Ring fixator assembly requires advanced orthopedic fellowship credentials, limiting addressable procedure volume to referral-tier hospitals.
- Stainless Steel Substitution Ceiling:Magnetic resonance imaging incompatibility of standard stainless steel pins blocks adoption in neurosurgical and spinal trauma applications.
Strategic Opportunities
- Carbon Fiber Frame Hybridization:Combining radiolucent carbon fiber connecting rods with titanium pins enables intraoperative imaging without frame disassembly.
- Telemedicine-Enabled Postoperative Monitoring:Remote pin tract assessment via digital imaging reduces follow-up visit burden for rural and exurban companion animal practices.
- CE Marking Pathway Expansion:EU MDR harmonization creates streamlined market entry for veterinary devices meeting human-grade sterilization and biocompatibility standards.
Industry Challenges
- Biomechanical Engineer Talent Scarcity:Finite pool of specialists capable of patient-specific fixator configuration limits customization service scalability.
- FDA Center for Veterinary Medicine Review Timelines:Extended premarket notification cycles for novel implantable materials delay revenue recognition by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal External Fixation Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring Fixators, Linear Fixators, Hybrid Fixators, Monolateral Fixators End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Farm Owners Material: Stainless Steel, Carbon Fiber, Titanium Alloy, Polymer Application: Orthopedic Surgery, Trauma Management, Soft Tissue Repair, Limb Lengthening |
| Companies Covered | IMEX Veterinary, Veterinary Orthopedic Implants (VOI), DePuy Synthes, Orthomed, Securos Surgical, BioMedtrix, Kyon AG, Arthrex, Movora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal External Fixation Market Strategic Shifts
Titanium alloy processing capabilities are migrating from human orthopedic suppliers into veterinary-specific product lines, while regulatory convergence and buyer consolidation reshape competitive requirements.
Carbon fiber connecting rods are displacing stainless steel in premium external fixation frames due to radiolucency advantages during intraoperative fluoroscopy. University veterinary teaching hospitals in the United States and Germany are specifying carbon-titanium hybrid configurations for complex limb reconstruction cases. The technology is migrating from equine specialty centers into companion animal trauma protocols as manufacturing scale reduces unit economics.
EU MDR and FDA Center for Veterinary Medicine are synchronizing biocompatibility documentation requirements for implantable devices, elevating testing costs for smaller manufacturers. Veterinary device firms must now maintain dual regulatory files to serve transatlantic markets. European university hospitals are responding by consolidating procurement around suppliers with established human medical regulatory track records.
Specialty veterinary hospital networks are centralizing orthopedic purchasing through group procurement organizations, displacing individual clinic buying autonomy. Independent practices in suburban United States markets face margin compression as corporate-owned referral centers capture complex trauma cases. This concentration is most visible in California, Texas, and Florida metropolitan corridors where specialty hospital density exceeds national averages.
Animal External Fixation Market Segmentation
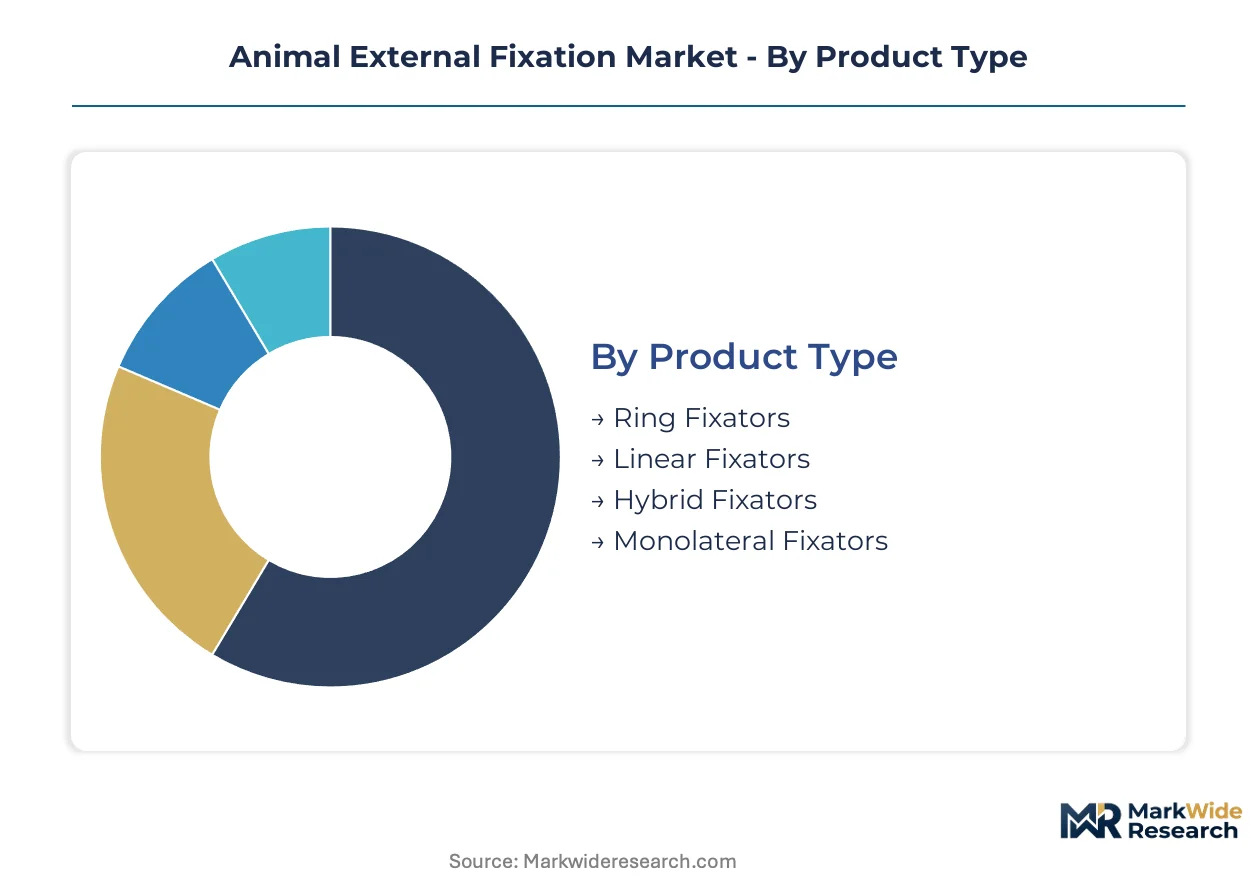
Segmentation in animal external fixation reveals distinct procurement patterns across veterinary practice tiers. University teaching hospitals prioritize MRI-compatible materials and biocompatibility certification, while general clinics optimize for cost-efficiency in trauma stabilization.
Product Type:
Mature configurations dominate general practice volumes, while emerging hybrid architectures capture complex reconstruction referrals.
- Ring Fixators:Circular frame assemblies with adjustable tension wires enable gradual angular correction and limb lengthening through precise mechanical distraction. Demand concentrates at equine sports medicine centers in Kentucky and Florida, driven by Thoroughbred racing's intolerance for postoperative limb length discrepancy. Ring fixators retain volume leadership; hybrid fixators hold the steepest expansion curve.
- Linear Fixators:Unilateral bar configurations with perpendicular pins offer simplified application for general veterinary practitioners managing acute fractures. Companion animal trauma cases in suburban United States markets drive procurement, with corporate veterinary networks standardizing on specific manufacturer platforms to reduce inventory complexity.
- Hybrid Fixators:Combined ring-linear architectures merge circular frame stability with unilateral application speed for complex metaphyseal fractures.
- Monolateral Fixators:Single-sided pin-bar systems provide minimal frame bulk for small-breed companion animals with limited soft tissue clearance.
Ring fixators command premium pricing through specialized surgeon training requirements; linear fixators scale through simplified inventory and reduced technical barriers.
End User:
Procurement authority is shifting from individual practitioners toward consolidated purchasing organizations, reshaping supplier engagement models.
- Veterinary Clinics:General practice settings manage straightforward fracture stabilization with linear fixator systems, often deferring complex cases to referral networks. Independent clinics in exurban United States markets face margin compression as corporate specialty centers capture trauma revenue.
- Animal Hospitals:Multi-specialty referral institutions maintain titanium alloy inventories and advanced imaging workflows for complex orthopedic reconstruction. University-affiliated hospitals in California, Texas, and New York specify ISO 10993-certified devices exclusively, creating procurement preference for established manufacturers with human medical regulatory track records.
- Research Institutions:Academic veterinary schools drive protocol development and surgeon training for emerging fixation techniques.
- Farm Owners:Agricultural end-users prioritize cost minimization for production animal limb salvage in cattle and swine operations.
Animal hospitals capture the highest procedure value per case; veterinary clinics represent the largest absolute case volume.
Material:
Cost-performance tradeoffs stratify material selection across practice tiers, with imaging compatibility driving upgrade cycles.
- Stainless Steel:Standard 316L surgical grade dominates general practice procurement through favorable unit economics and established supply chains. MRI incompatibility limits adoption in neurosurgical and spinal trauma applications, creating substitution pressure at university teaching hospitals.
- Titanium Alloy:Ti-6Al-4V ELI grade commands pricing premiums where corrosion resistance and magnetic resonance imaging compatibility justify material costs. Aerospace and human medical sectors dominate titanium bar stock allocation, creating input scarcity for veterinary device fabricators.
- Carbon Fiber:Radiolucent connecting rods enable intraoperative fluoroscopy without frame disassembly, displacing stainless steel in premium configurations.
- Polymer:Resorbable and radiolucent options serve niche applications in pediatric orthopedic and temporary stabilization scenarios.
Stainless steel retains installed base dominance; titanium alloy is climbing the fastest through specialty hospital procurement mandates.
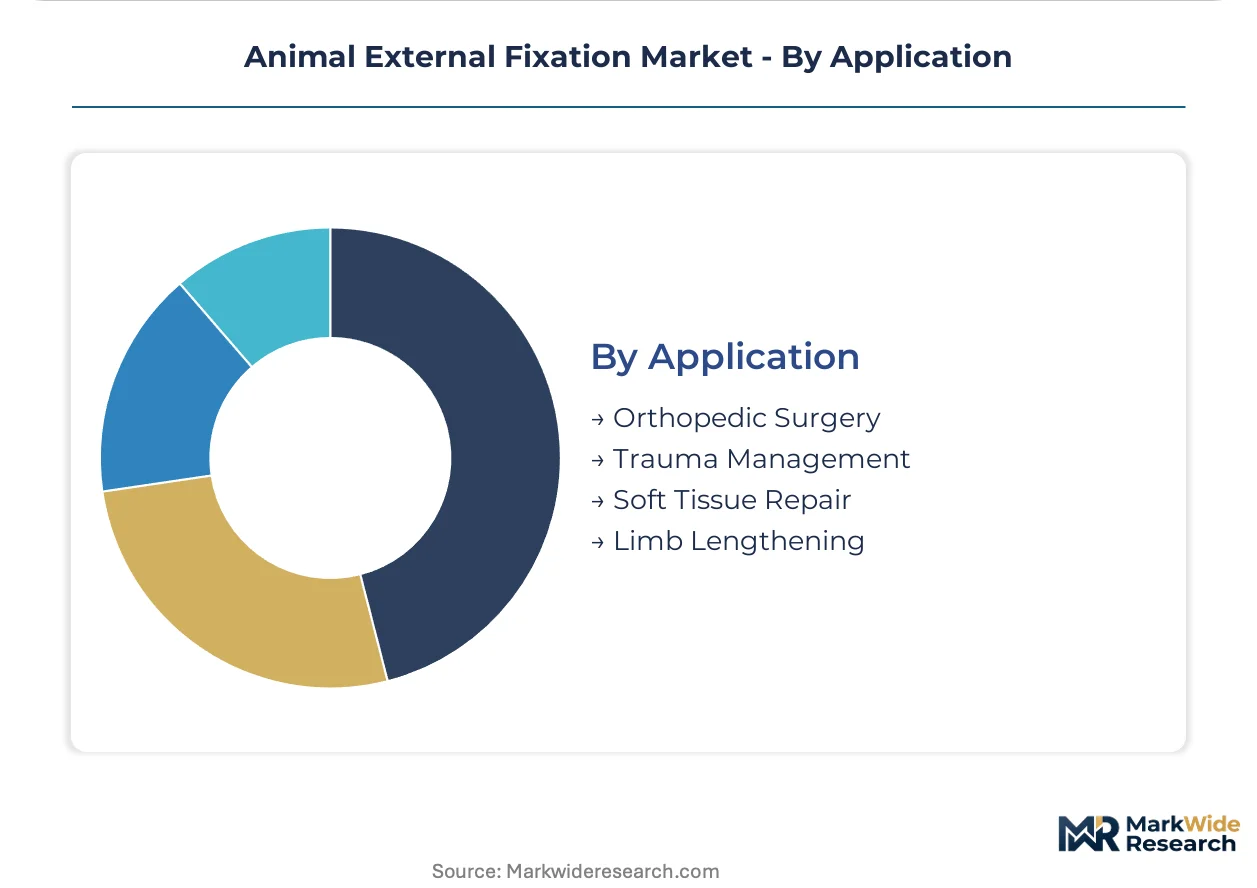
Application:
Procedure complexity and reimbursement availability determine material and product selection within each application domain.
- Orthopedic Surgery:Planned limb deformity correction and joint arthrodesis procedures specify carbon-titanium hybrid configurations for intraoperative imaging flexibility. German and United States university hospitals lead protocol standardization, with ring fixator assembly requirements limiting addressable volume to fellowship-trained surgeons.
- Trauma Management:Acute fracture stabilization drives linear fixator volume through emergency department protocols at general veterinary practices. Pet insurance penetration enables owner funding of external fixation surgeries previously deferred due to cost constraints.
- Soft Tissue Repair:Tendon and ligament reconstruction applications employ external fixation for postoperative immobilization and protected motion.
- Limb Lengthening:Gradual mechanical distraction for congenital or acquired limb length discrepancy concentrates at equine and companion animal referral centers.
Trauma management generates the highest absolute procedure volume; limb lengthening captures the steepest expansion trajectory through sports medicine specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine protocols anchor demand in the United States, while ISO 10993 certification requirements reshape procurement patterns across university veterinary hospitals in Germany, the United Kingdom, and Japan.
United States
Kentucky and Florida equine sports medicine centers drive ring fixator procurement for Thoroughbred racing applications. The FDA Center for Veterinary Medicine maintains biocompatibility standards that extend product development timelines for implantable devices. Specialty hospital networks in California, Texas, and Florida metropolitan corridors consolidate orthopedic purchasing through group procurement organizations.
Germany
University veterinary teaching hospitals in Munich and Leipzig specify carbon-titanium hybrid configurations for complex limb reconstruction. EU MDR harmonization elevates sterilization and biocompatibility documentation requirements for implantable veterinary devices. The Baden-Württemberg region hosts precision manufacturing clusters supplying radiolucent carbon fiber connecting rods to European markets.
United Kingdom
Companion animal trauma cases in Greater London and Southeast England sustain linear fixator demand through corporate veterinary networks. The Veterinary Medicines Directorate aligns with EU MDR standards for implantable device market authorization. Scotland's equine referral centers concentrate limb-lengthening procedures for Highland pony and Clydesdale breeding programs.
Japan
Small-breed companion animal demographics in Tokyo and Osaka metropolitan areas favor monolateral fixator systems with minimal frame bulk. PMDA consultation procedures for veterinary medical devices create parallel regulatory pathways alongside human pharmaceutical oversight. The Kansai region maintains titanium alloy processing capabilities serving domestic and Asia-Pacific veterinary device fabricators.
Switzerland
Equine orthopedic specialization in Bern and Zurich veterinary hospitals sustains premium fixation system procurement. Swissmedic maintains veterinary medical device registration requirements that exceed baseline EU MDR compliance thresholds. The Basel pharmaceutical manufacturing corridor extends precision metallurgy expertise into veterinary implantable device supply chains.
Animal External Fixation Market Competitive Environment
Capability concentration sits with specialized veterinary orthopedic manufacturers; scale advantage sits with diversified human medical device conglomerates. The market structures around three tiers: human orthopedic heritage players leveraging titanium processing scale, dedicated veterinary specialists commanding surgeon training relationships, and regional fabricators serving cost-sensitive agricultural segments. Strategic moves center on carbon fiber hybridization investments and telemedicine-enabled postoperative monitoring platform development.
Within the human orthopedic heritage tier, DePuy Synthes exemplifies titanium alloy processing migration into veterinary-specific product lines. Among dedicated veterinary specialists, IMEX Veterinary and Kyon AG occupy positions anchored in specialized fixator architectures and proprietary locking plate technology respectively. These three entities represent the capability-scale spectrum: diversified metallurgy scale, linear fixator specialization, and hybrid configuration innovation.
| Leading Market Players |
|---|
| IMEX Veterinary |
| Veterinary Orthopedic Implants (VOI) |
| DePuy Synthes |
| Orthomed |
| Securos Surgical |
| BioMedtrix |
| Kyon AG |
| Arthrex |
| Movora |
| Others |
Value Chain & Pricing Dynamics
Titanium bar stock allocation in the United States, Japan, and Germany concentrates among aerospace and human medical fabricators, leaving veterinary device manufacturers to absorb premium input costs or downgrade to stainless steel alternatives. This upstream scarcity funnels margin pools toward specialty hospital networks with procurement mandates for MRI-compatible titanium systems, compressing returns for general practice suppliers locked into commoditized stainless steel configurations.
Pricing Analysis
United States veterinary clinics pay 40-60% premiums over European counterparts for identical titanium alloy fixator systems due to FDA Center for Veterinary Medicine compliance costs and fragmented distributor networks. Three-tier pricing structure across premium carbon-titanium hybrids, standard titanium configurations, and economy stainless steel kits reflects ISO 10993 certification grade and surgeon training bundling. Cost compression in the stainless steel tier is intensifying because corporate veterinary networks are standardizing on single-source platforms. General veterinary clinics exhibit highest price sensitivity, while university teaching hospitals prioritize imaging compatibility over unit economics.
Supply Chain Analysis
Ti-6Al-4V ELI feedstock draws from precision metallurgy clusters in the United States, Germany, and Japan, with aerospace contract priority creating allocation bottlenecks for veterinary device fabricators. Raw material dependencies center on titanium sponge, surgical-grade stainless steel rod, and carbon fiber pre-preg for radiolucent connecting rods. Single-source vulnerability concentrates in titanium alloy bar stock where human orthopedic OEMs command volume preference. Distribution runs through veterinary specialty distributors and group purchasing organizations that consolidate procurement authority across hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specialty hospital network consolidation and group purchasing organization expansion, fragmenting pricing autonomy for independent veterinary clinics and elevating technical certification requirements for suppliers.
For Market Incumbents: Entrench titanium alloy processing capabilities through captive supply agreements with precision metallurgy suppliers in Germany or Japan, insulating against aerospace sector allocation priority. Deepen surgeon training relationships at university veterinary teaching hospitals to lock in procurement preference for ISO 10993-certified configurations. Carbon fiber hybridization investments defend position against radiolucency demands from equine sports medicine centers. For New Entrants and Emerging Players: Pursue telemedicine-enabled postoperative monitoring platforms for rural and exurban companion animal practices underserved by referral-tier hospitals. White-space targets include CE-marked carbon-titanium hybrid systems for EU MDR-harmonized markets and cost-optimized linear fixator configurations for farm owner segments in Brazil and Australia. Direct-to-clinic digital distribution bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward veterinary-specialist manufacturers with established FDA Center for Veterinary Medicine regulatory track records and proprietary locking plate or ring fixator architectures. Long-term viability hinges on carbon fiber hybridization capabilities and telemedicine platform integration rather than commodity stainless steel volume. Watch for pet insurance penetration inflection as a demand accelerator for premium titanium configurations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | EU MDR harmonization accelerates transatlantic market entry for biocompatibility-certified manufacturers. |
| Carbon Fiber Frame Hybridization | Radiolucent connecting rods enable intraoperative fluoroscopy without frame disassembly at university hospitals. |
| Telemedicine Platform Development | Remote pin tract assessment reduces follow-up burden for rural companion animal practices. |
| Titanium Supply Agreement | Captive metallurgy contracts insulate veterinary fabricators from aerospace allocation priority. |
| Surgeon Training Certification | Fellowship program partnerships lock in procurement preference at specialty referral centers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine premarket notification databases, ISO 10993 biological evaluation protocols, and veterinary hospital procurement records. Interviews with orthopedic surgeons at university teaching hospitals, biomedical engineers at specialty referral centers, group purchasing organization contracts managers, and titanium alloy procurement leads at device fabricators inform demand-side validation. Secondary sources include customs trade data for veterinary implantable device imports, SEC filings from diversified human medical device conglomerates, and equine sports medicine center procedure registries. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue allocations.
Forecast inputs span product type segmentation across ring, linear, hybrid, and monolateral fixator configurations; material tier stratification by stainless steel, titanium alloy, carbon fiber, and polymer; and end-user categorization across veterinary clinics, animal hospitals, research institutions, and farm owners. CAGRs derive from regression analysis of historical procedure volume growth against pet insurance penetration trajectories and specialty hospital network expansion rates across the analysis window. Industry-specific inputs include Thoroughbred racing injury incidence data and ISO 10993 certification adoption curves at university veterinary hospitals.
Macroeconomic conditions sit as an overlay; deviation in pet owner discretionary spending, veterinary labor availability, or titanium commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding specialty hospital consolidation pace and regulatory synchronization between FDA Center for Veterinary Medicine and EU MDR frameworks. Cross-checking against equine sports medicine procedure registries and companion animal insurance claims databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Global Artificial Joints Market