
 Cartilage Repair Market | 2026-2036
Cartilage Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Cartilage Repair Market Analysis
Aftermarket service revenue from implant maintenance and revision instrumentation is tilting toward biologics platforms that require specialized handling. Zimmer Biomet Holdings anchors its position through manufacturing scale across multiple continental production facilities. Arthrex differentiates via deep specialization in arthroscopic delivery systems and surgeon training ecosystems. Smith+Nephew navigates European reimbursement complexity through dedicated health economics teams.
Cartilage repair encompasses surgical and non-surgical interventions to restore articular hyaline cartilage, typically involving scaffolds with pore sizes of 150-400 microns to enable chondrocyte infiltration and extracellular matrix deposition. Its primary purpose is to delay or prevent total joint arthroplasty in younger active patients with focal chondral defects. Cell therapy platforms command premium pricing due to autologous processing requirements and cold-chain logistics, while synthetic implants face margin compression from commoditization in sports injury applications. Microfracture remains the volume leader despite inferior long-term durability, whereas 3D bioprinting attracts R&D capital for its potential to replicate zonal cartilage architecture.
FDA oversees biologics regulation through CBER and CDRH divisions, while the EU Medical Device Regulation imposes clinical evidence requirements on implantable scaffolds. These frameworks elevate barriers for new entrants but protect incumbent innovators with established quality management systems. Stakeholders must monitor reimbursement decisions by CMS and Germany's G-BA, as these determine whether novel therapies shift from cash-pay niches to standard-of-care coverage.
Market Dynamics
Autologous cell therapy platforms are compressing development timelines through streamlined FDA 510(k) pathways, while hospital systems simultaneously expand orthopedic service lines to capture migrating outpatient joint procedures.
Growth Catalysts
- Statutory reimbursement frameworks:Germany's G-BA mandates coverage for cartilage restoration procedures, converting cash-pay niches into standard-of-care volumes and anchoring European demand concentration.
- Arthroscopic delivery innovation:Specialized instrumentation enables minimally invasive implant placement, reducing recovery windows and expanding candidate pools beyond elite athletes to aging active populations.
- Biologics cold-chain infrastructure:Dedicated logistics networks now support viable chondrocyte transport from biopsy to processing facilities, extending cell therapy reach beyond major metropolitan clusters.
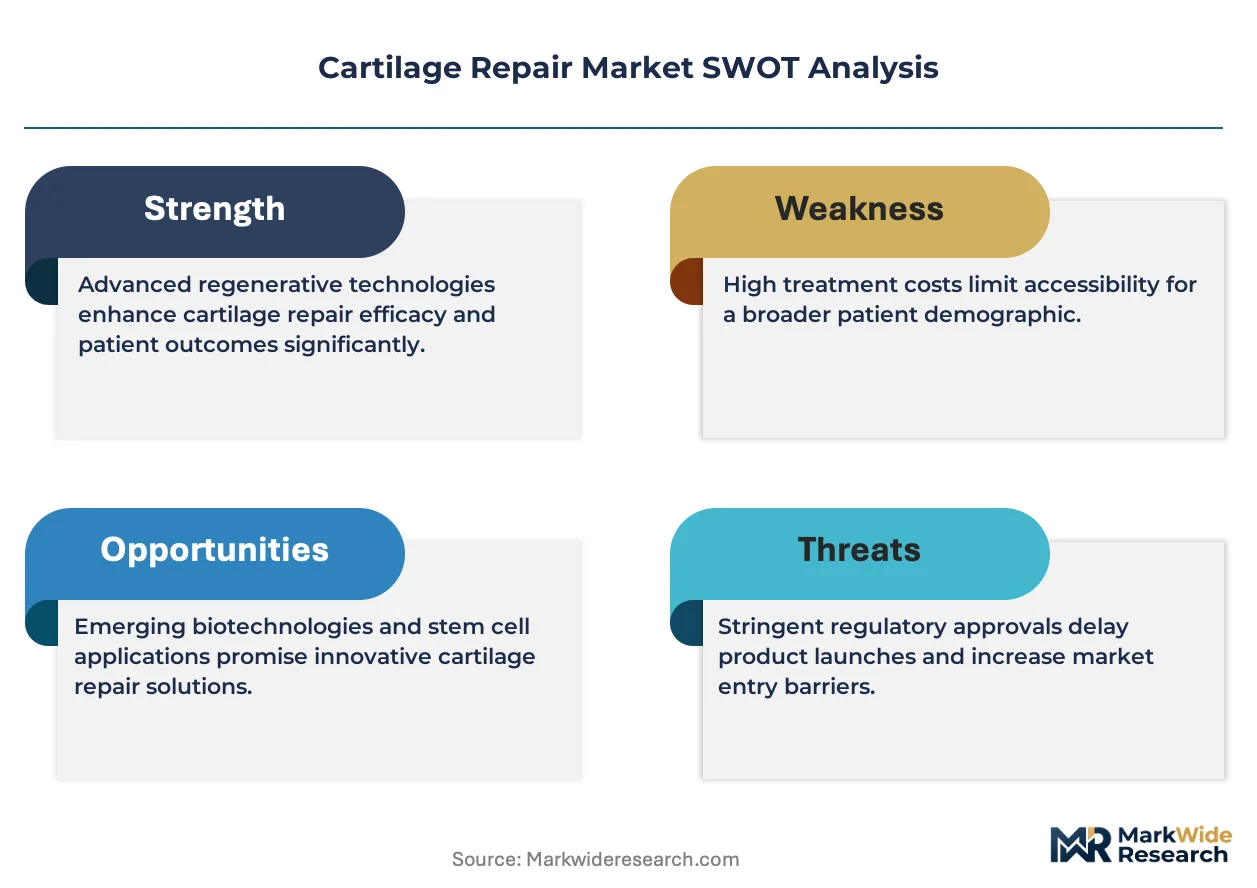
Market Restraints
- Autologous processing cost structure:Patient-specific cell expansion requires certified cleanroom facilities and skilled technicians, creating fixed cost burdens that synthetic scaffold manufacturers avoid.
- Long-term durability uncertainty:Microfracture procedures demonstrate inferior five-to-ten year outcomes versus total joint arthroplasty, limiting payer willingness to authorize premium biologics for older patients.
- EU MDR clinical evidence requirements:Implantable scaffolds now demand extended follow-up data for CE marking, elevating documentation burdens that favor incumbents with established quality management systems.
Strategic Opportunities
- 3D bioprinting convergence:Integration of additive manufacturing with zonal cartilage architecture replication offers pathway to hyaline-mimetic implants, attracting venture capital beyond traditional orthopedics.
- Outpatient procedure migration:Ambulatory surgery centers seek differentiated service lines, creating channel expansion for manufacturers offering compact instrumentation and surgeon training ecosystems.
- CMS transitional pass-through payments:Novel biologics qualify for temporary reimbursement premium during evidence accumulation, enabling market entry before permanent coverage determinations finalize.
Industry Challenges
- Chondrocyte isolation technician scarcity:Certified cell processing specialists concentrate at academic medical centers, constraining production scale-up for decentralized therapy platforms.
- Scaffold pore architecture standardization:Variable 150-400 micron specifications across manufacturers complicate comparative effectiveness research and payer technology assessments.
- Revision instrumentation interoperability:Proprietary implant designs lock hospitals into single-vendor maintenance contracts, fragmenting aftermarket service revenue capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartilage Repair Market |
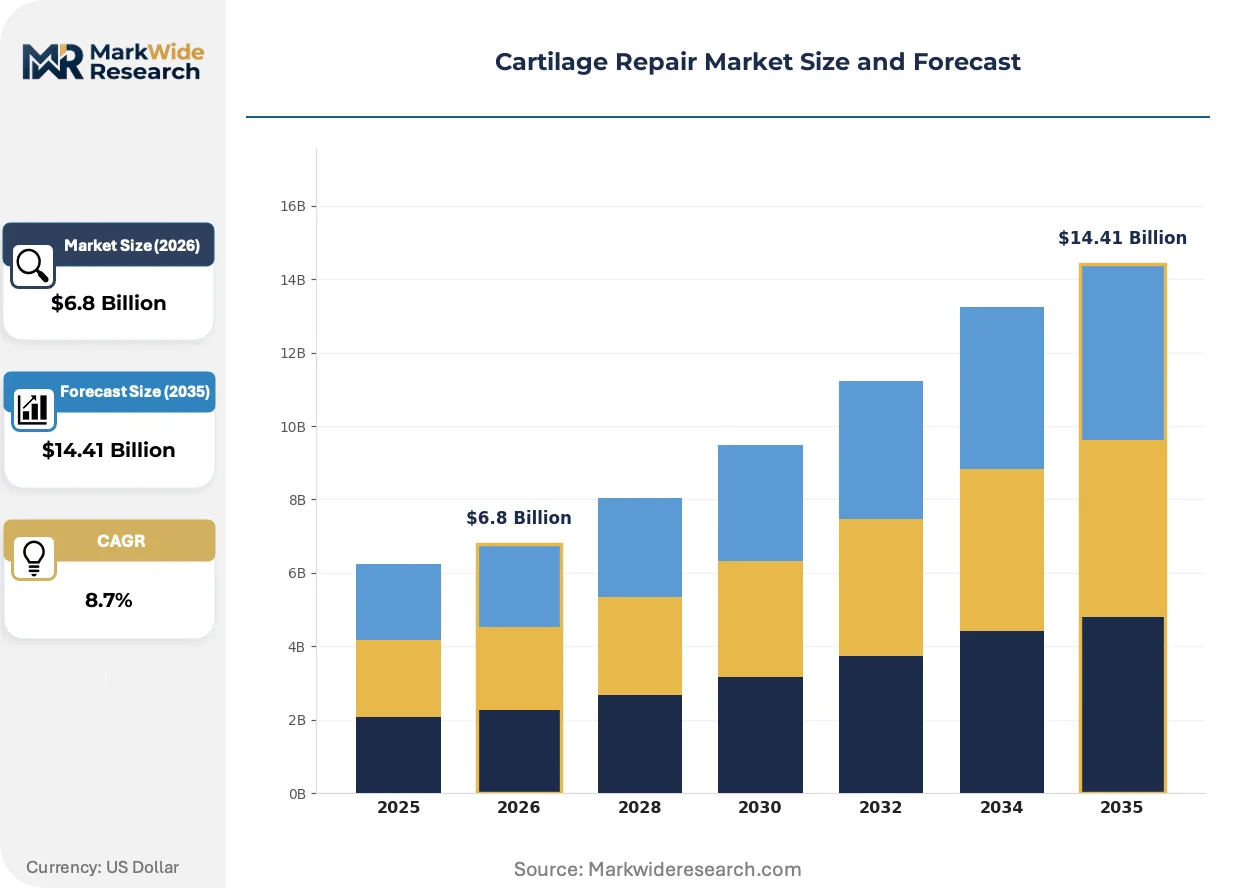
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Synthetic Implants, Cell Therapy, Injectable Treatments Application: Knee Injuries, Osteoarthritis Management, Sports Injuries, Joint Reconstruction Technology: Microfracture, Osteochondral Grafting, Autologous Chondrocyte Implantation, 3D Bioprinting End User: Hospitals, Orthopedic Clinics, Research Institutions, Rehabilitation Centers |
| Companies Covered | Vericel Corporation, Zimmer Biomet Holdings, Arthrex, Stryker Corporation, Smith+Nephew, DePuy Synthes, Anika Therapeutics, CONMED Corporation, Geistlich Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartilage Repair Market Emerging Trajectories
Biologics platforms are actively displacing mechanical implants across focal chondral defect treatment, driven by payer tolerance for premium pricing when joint preservation delays arthroplasty.
3D bioprinting of zonal cartilage constructs is collapsing the boundary between synthetic scaffolds and autologous tissue engineering. Academic medical centers in Germany and the United States are piloting patient-specific implants that replicate superficial, middle, and deep cartilage zones. This convergence is compressing the addressable market for first-generation collagen matrices that lack architectural specificity.
FDA's CBER and CDRH divisions are harmonizing oversight frameworks for combination products that merge cellular components with structural carriers. The revised guidance reduces redundant review cycles for developers of autologous chondrocyte-seeded scaffolds. Orthopedic biologics specialists are responding by consolidating regulatory affairs functions previously split across device and biologic submission tracks.
Hospital procurement committees are consolidating vendor relationships around full-service cartilage repair programs rather than discrete product categories. Integrated delivery networks in North America now bundle implant supply with surgeon training and patient-reported outcome tracking. This behavioral shift concentrates purchasing authority at health system headquarters, reducing distributor influence over individual orthopedic surgeons.
Cartilage Repair Market Segmentation
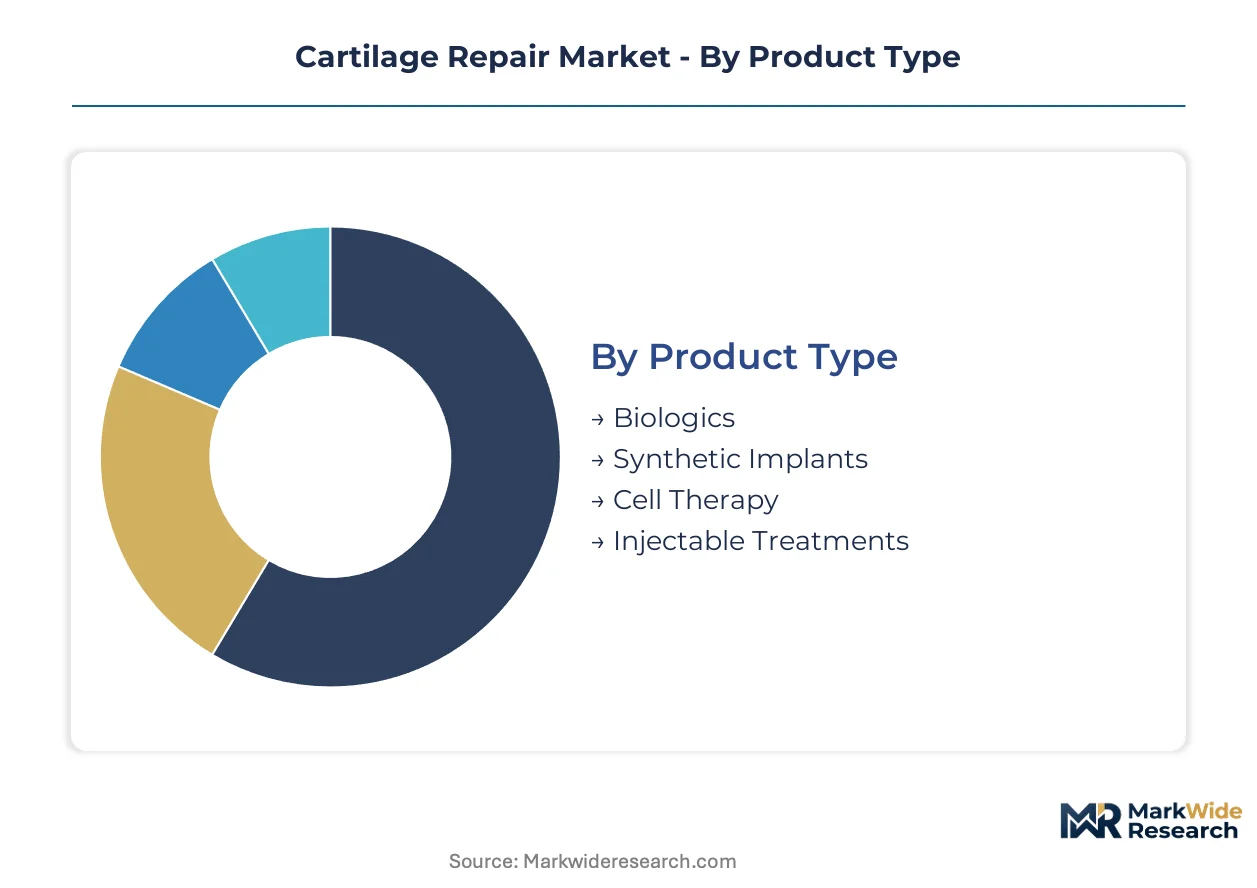
Cartilage repair segmentation reflects divergent cost structures, regulatory pathways, and clinical evidence requirements across biological and mechanical intervention categories. Understanding these divides enables targeted positioning against reimbursement thresholds and surgical volume concentration points.
Product Type:
Mature synthetic platforms coexist with emerging cell therapy modalities that command premium positioning through autologous processing complexity.
- Biologics:Collagen and hyaluronic acid-based matrices with 150-400 micron pore architectures enable chondrocyte infiltration. Demand clusters in Germany where G-BA mandates statutory reimbursement, converting cash-pay niches into standard-of-care volumes for focal chondral defects.
- Synthetic Implants:Polyurethane and polylactic acid scaffolds offer off-the-shelf availability without cold-chain logistics. Sports injury applications in ambulatory surgery centers drive volume, though margin compression from commoditization limits pricing power against biologics alternatives.
- Cell Therapy:Autologous chondrocyte expansion requires certified cleanroom facilities and FDA CBER oversight, creating fixed cost barriers that synthetic manufacturers avoid.
- Injectable Treatments:Hyaluronic acid and platelet-rich plasma formulations target early-stage osteoarthritis with minimally invasive delivery.
Biologics retains volume leadership; cell therapy holds the steepest expansion curve as cold-chain infrastructure extends beyond major metropolitan clusters.
Application:
Cost tier stratification separates joint preservation procedures from end-stage reconstruction, with reimbursement intensity varying by patient age and activity level.
- Knee Injuries:Focal chondral defects in younger active patients represent the core addressable population for cartilage restoration. Hospital systems in the United States expand orthopedic service lines to capture migrating outpatient procedures, anchoring demand concentration.
- Osteoarthritis Management:Injectable biologics target early degenerative changes before structural joint damage progresses. CMS transitional pass-through payments enable temporary reimbursement premiums during evidence accumulation for novel therapies.
- Sports Injuries:High-performance athletes drive adoption of arthroscopic delivery systems with reduced recovery windows.
- Joint Reconstruction:Revision procedures following failed primary interventions command premium instrumentation and specialized handling protocols.
Knee injuries dominates procedure volumes; osteoarthritis management is climbing the fastest as aging active populations expand candidate pools beyond elite athletes.
Technology:
Volume concentration in established techniques contrasts with R&D capital flows toward architectural replication capabilities.
- Microfracture:Bone marrow stimulation through subchondral drilling remains the volume leader despite inferior five-to-ten year durability versus total joint arthroplasty. Payer reluctance to authorize premium biologics for older patients sustains its position in cost-constrained settings.
- Autologous Chondrocyte Implantation:Two-stage procedures involving biopsy, cell expansion, and surgical implantation require certified technician specialists concentrated at academic medical centers. FDA 510(k) pathway compression accelerates development timelines for next-generation formulations.
- Osteochondral Grafting:Mosaicplasty and allograft transplantation transfer viable cartilage and bone for larger defect coverage.
- 3D Bioprinting:Additive manufacturing convergence with zonal architecture replication attracts venture capital beyond traditional orthopedics for patient-specific implants.
Microfracture retains volume leadership; 3D bioprinting holds the steepest expansion curve as academic medical centers in Germany and the United States pilot superficial, middle, and deep zone replication.
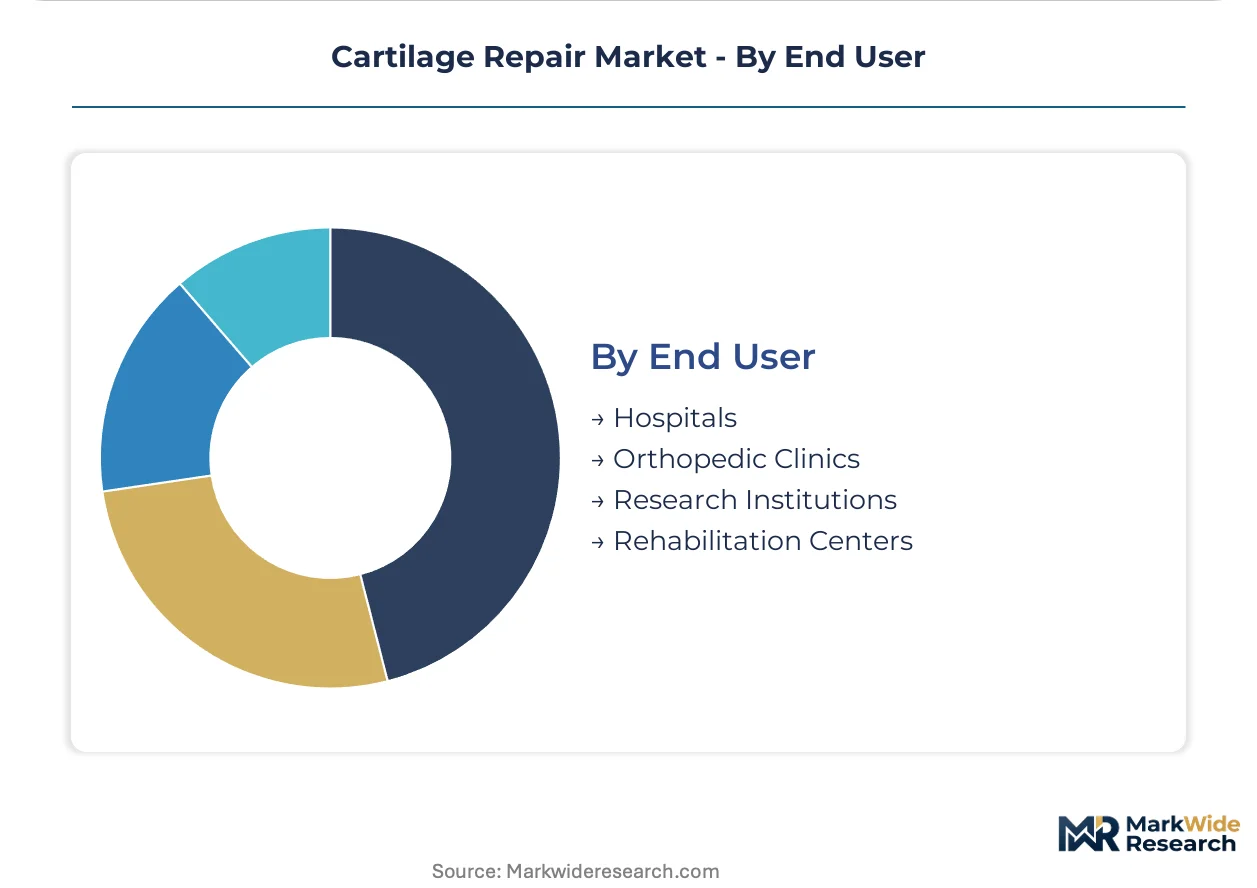
End User:
Customer type fragmentation between institutional settings and specialized clinics shapes procurement authority and vendor relationship structures.
- Hospitals:Integrated delivery networks in North America consolidate purchasing authority at headquarters level, bundling implant supply with surgeon training and patient-reported outcome tracking. This behavioral shift reduces distributor influence over individual orthopedic surgeons.
- Orthopedic Clinics:Ambulatory surgery centers seek differentiated service lines through compact instrumentation and dedicated health economics navigation teams for European reimbursement complexity.
- Research Institutions:Academic medical centers concentrate certified cell processing specialists, constraining production scale-up for decentralized therapy platforms.
- Rehabilitation Centers:Post-surgical recovery protocols extend care continuity beyond the acute intervention setting.
Hospitals retain volume leadership; orthopedic clinics are gaining share fastest as outpatient procedure migration accelerates across health system expansion strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity due to statutory reimbursement guarantees, while cash-pay markets in emerging economies exhibit acute sensitivity to out-of-pocket costs for cell therapy platforms.
United States
FDA CBER and CDRH oversight harmonization accelerates combination product approvals for autologous chondrocyte-seeded scaffolds. Hospital systems consolidate purchasing authority at integrated delivery network headquarters, bundling implant supply with surgeon training. Academic medical centers in Boston and the San Francisco Bay Area concentrate certified cell processing specialists for decentralized therapy scale-up.
Germany
G-BA statutory reimbursement mandates convert cartilage restoration from cash-pay niches into standard-of-care volumes with predictable demand. EU MDR clinical evidence requirements elevate documentation burdens that favor established quality management systems. Industrial clusters in Bavaria and Baden-Württemberg anchor orthopedic device manufacturing with dedicated health economics navigation teams.
United Kingdom
NICE technology appraisals determine NHS commissioning for novel biologics, creating evidence accumulation windows before permanent coverage. MHRA post-Brexit regulatory autonomy enables streamlined UK-specific approval pathways for autologous therapies. London and the Greater Manchester health innovation clusters pilot patient-reported outcome tracking for bundled procurement contracts.
Japan
PMDA conditional approval frameworks enable early market access for regenerative medicine products with ongoing efficacy monitoring. METI industrial policy directs venture capital toward 3D bioprinting convergence with zonal cartilage architecture replication. The Kanto region around Tokyo concentrates orthopedic research institutions with cold-chain logistics infrastructure for viable chondrocyte transport.
Switzerland
Swissmedic maintains alignment with EU MDR standards while preserving national flexibility for breakthrough therapy designations. Statutory health insurance coverage for cartilage procedures remains discretionary, sustaining premium pricing for proven modalities. Basel and Zurich host biologics manufacturing facilities with certified cleanroom capacity for autologous cell expansion.
Cartilage Repair Market Vendor Landscape
Integrated orthopedic conglomerates and specialized arthroscopy developers split the market into scale-driven and precision-focused camps. Consolidation pressure intensifies as hospital procurement committees demand full-service programs bundling implants, instrumentation, and outcome tracking. Three archetypes dominate: diversified device manufacturers with continental production footprints, arthroscopic delivery specialists with surgeon training ecosystems, and biologics pure-plays with autologous processing expertise. Competitive moves center on M&A for regulatory capabilities and strategic partnerships for cold-chain infrastructure extension.
Within the diversified manufacturer tier, Zimmer Biomet Holdings and Stryker Corporation exemplify scale-driven positioning through multi-continental manufacturing networks. Arthrex occupies a distinct specialization position as an arthroscopic delivery and training ecosystem anchor. Smith+Nephew represents the European-centric archetype navigating reimbursement complexity through dedicated health economics functions. These three companies illustrate how strategic positioning around manufacturing scale, delivery precision, or regulatory navigation determines competitive viability.
| Leading Market Players |
|---|
| Vericel Corporation |
| Zimmer Biomet Holdings |
| Arthrex |
| Stryker Corporation |
| Smith+Nephew |
| DePuy Synthes |
| Anika Therapeutics |
| CONMED Corporation |
| Geistlich Pharma |
| Others |
Supply Flow & Price Mechanics
Bavaria's orthopedic manufacturing cluster anchors European biologics production capacity, with certified cleanroom facilities for autologous chondrocyte expansion translating directly into premium pricing power for cell therapy platforms. Cold-chain infrastructure concentration in metropolitan hubs like Boston and Tokyo reinforces geographic tiering in service delivery costs.
Pricing Analysis
Aftermarket service revenue from implant maintenance and revision instrumentation anchors lifetime value capture for manufacturers. Three-tier pricing structure across premium biologics, standard synthetic scaffolds, and economy microfracture tiers reflects processing complexity and certification requirements under FDA CBER oversight. Pricing pressure stems from commoditization in sports injury synthetic applications, while statutory reimbursement in Germany renders that buyer segment least price-sensitive.
Supply Chain Analysis
Upstream feedstock of collagen matrices, hyaluronic acid formulations, and polyurethane scaffolds draws from Switzerland, Germany, and the United States for medical-grade raw material certification. Certified technician scarcity for chondrocyte isolation concentrates production at academic medical centers, creating single-source vulnerability for autologous platforms. Distribution runs through integrated delivery network headquarters bundling implants with surgeon training ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where established quality management systems under FDA CBER and EU MDR frameworks erect prohibitive documentation barriers for new entrants.
For Market Incumbents: Pre-empt emerging 3D bioprinting specialists by acquiring additive manufacturing capabilities for zonal cartilage architecture replication. Consolidate channel control through backward integration into certified cleanroom capacity, countering the threat of decentralized cell therapy platforms eroding geographic exclusivity.
For New Entrants and Emerging Players: Ambulatory surgery centers in North American secondary markets represent the most penetrable white-space target, with demand for compact arthroscopic instrumentation outpacing incumbent service coverage. A surgeon training ecosystem bundled with outcome tracking software offers differentiated go-to-market positioning against consolidated hospital procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA 510(k) pathway compression for autologous therapies accelerates development timelines relative to EU MDR clinical evidence requirements. Acquisition targets should display established CBER submission track records and cold-chain logistics partnerships. Watch CMS transitional pass-through payment renewal decisions as the critical inflection signal for biologics market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | G-BA coverage mandates in Germany convert cash-pay niches into standard-of-care volumes with predictable demand. |
| CE Marking Pathway | EU MDR clinical evidence requirements for implantable scaffolds favor incumbents with established quality systems. |
| Hospital System Partnership | Integrated delivery network bundling concentrates purchasing authority and reduces distributor influence over surgeons. |
| Manufacturing Scale-Up | Multi-continental production footprints under FDA CBER oversight anchor supply security for autologous platforms. |
| Software Companion Development | Patient-reported outcome tracking systems differentiate procurement bids in bundled vendor relationships. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation, and hospital procurement contract records preceded structured interviews with orthopedic surgeons, GPO contracts managers, biomedical engineers, and cell processing technicians. Secondary validation drew from CMS Medicare reimbursement data, Germany's G-BA benefit assessments, and SEC 10-K filings of listed device manufacturers. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across the analysis window.
Assumptions held reimbursement policy trajectories in Germany and the United States fixed while varying cell therapy adoption curves and synthetic scaffold commoditization rates. Segmentation modeling spanned product type, application, technology, and end-user dimensions with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves fitted to historical procedure volumes and payer authorization patterns, incorporating cold-chain infrastructure expansion as a supply-side constraint variable.
Practitioners should monitor FDA CBER guidance revisions and CMS national coverage determinations for early signals of pathway compression or expansion. Forecasts reflect these assumptions alongside EU MDR implementation enforcement intensity and academic medical center capacity utilization rates. Quarterly review of G-BA benefit assessment updates and hospital system vendor consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market