
 Intramedullary Nails Market | 2026-2036
Intramedullary Nails Market Size, Share, and Industry Trends Forecast 2026-2036
Intramedullary Nails Market Intelligence
Specialized contract manufacturing of titanium alloys in the United States and Switzerland is restructuring the supply chain for high-performance nails. This shift allows major device companies to focus on design and clinical validation. Stryker Corporation leverages its extensive distribution network to supply major trauma centers. Zimmer Biomet competes through its focus on integrated surgical systems and instrumentation for complex procedures.
An intramedullary nail is a metal rod surgically inserted into the medullary canal of a long bone, such as the femur or tibia. These devices, often made of titanium alloy for its biocompatibility and strength-to-weight ratio, provide internal fixation to stabilize fractures during healing. Interlocking nails for femoral and tibial fractures represent the largest application segment due to their rotational stability. The material landscape is dominated by titanium alloy, but bioabsorbable polymers are gaining share in pediatric fracture applications.
Market access requires stringent regulatory approvals, including 510(k) clearance from the US FDA and conformity with Europe's Medical Device Regulation (MDR). In China, the NMPA imposes specific clinical data requirements, influencing product launch timelines and design choices. Future competitive advantage will be determined by navigating these disparate regulatory pathways while demonstrating improved patient outcomes through verifiable clinical evidence.
Market Dynamics
The intramedullary nails market is defined by a structural shift towards specialized contract manufacturing for titanium alloys. This trend, combined with clinical validation of bioabsorbable polymers, is creating new supply chain dynamics and treatment possibilities.
Growth Catalysts
- Interlocking Nail Adoption:Trauma centers are increasingly using interlocking nails for complex femoral and tibial fractures, valuing their superior rotational stability.
- Aging Demographics:Advanced healthcare systems in countries like Germany see high orthopedic procedure volumes, driven by an aging population susceptible to fractures.
- Bioabsorbable Polymer Validation:Clinical acceptance of these materials creates new pathways for pediatric fracture treatment, avoiding secondary removal surgeries.
Market Restraints
- Regulatory Complexity:Gaining separate approvals like the FDA's 510(k) and Europe's MDR is a costly, time-consuming barrier for manufacturers.
- Titanium Cost Volatility:The primary material, titanium alloy, is subject to price fluctuations, impacting manufacturing costs and final device pricing.
- Poor Fixation in Osteoporotic Bone:Standard nail designs offer suboptimal purchase in weak bone, increasing the risk of fixation failure and complications.
Strategic Opportunities
- Smart Implant Integration:Incorporating sensors into nails to monitor healing offers a new frontier for data-driven postoperative care and improved outcomes.
- Trauma Care Expansion:Upgrades to trauma care infrastructure in large emerging economies like Brazil and India create a volume opportunity for standard nail systems.
- Anatomically Specific Nails:Developing nails for complex fracture patterns, such as periprosthetic fractures, addresses a key unmet clinical need for specialized fixation.
Industry Challenges
- Surgical Training Requirements:The effective use of advanced nailing systems and instrumentation requires specialized surgical training, creating a bottleneck for adoption in less-equipped facilities.
- Supply Chain Reconfiguration:Shifting production to specialized contract manufacturers in the US and Switzerland requires significant logistical oversight and quality control validation to maintain supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intramedullary Nails Market |
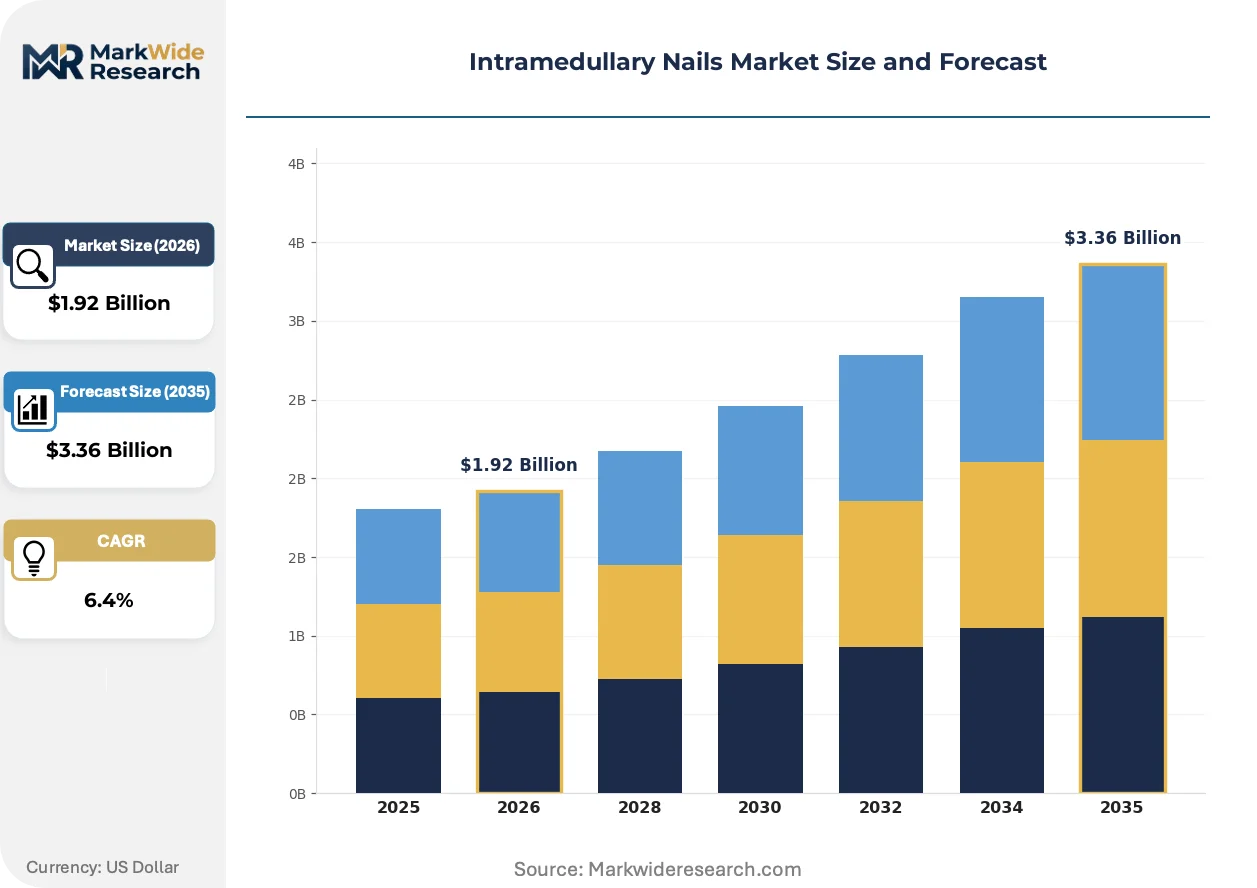
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Nails, Cannulated Nails, Interlocking Nails, Flexible Nails, Reconstruction Nails Application: Femoral Fractures, Tibial Fractures, Humeral Fractures, Clavicle Fractures, Pediatric Fractures End User: Orthopedic Clinics, Trauma Centers, Ambulatory Surgery Centers, Rehabilitation Facilities Material Type: Titanium Alloy, Stainless Steel, Cobalt Chromium, Bioabsorbable Polymers |
| Companies Covered | DePuy Synthes (Johnson & Johnson), Orthofix Medical Inc., Stryker Corporation, Arthrex, Inc., B. Braun Melsungen AG, Zimmer Biomet, Medtronic plc, Globus Medical, Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intramedullary Nails Market Strategic Shifts & Innovations
The competitive landscape for intramedullary nails is being reshaped by a focus on procedural efficiency and clinically validated patient outcomes. This shift prioritizes integrated surgical systems and materials that can demonstrate tangible benefits in healing and recovery times.
Next-generation bioabsorbable polymers function as temporary fixation devices that are absorbed by the body over time. These materials are gaining rapid acceptance in pediatric orthopedic surgery for specific fracture types. This clinical validation is consolidating the pediatric segment's preference away from traditional titanium implants that require a second removal procedure.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This regulation is forcing manufacturers to re-certify existing products and provide more extensive data to prove safety and performance. Devices with long-term clinical data are gaining an advantage, while some older products are being retired from the market.
A clear shift is occurring from purchasing standalone nails to procuring integrated surgical systems that include instrumentation, software, and implants. This disrupts the traditional sales model focused solely on the implant, favoring vendors who offer a complete procedural solution. This trend is most pronounced in high-volume trauma centers in the United States and Germany seeking to standardize procedures.
Intramedullary Nails Market Segmentation
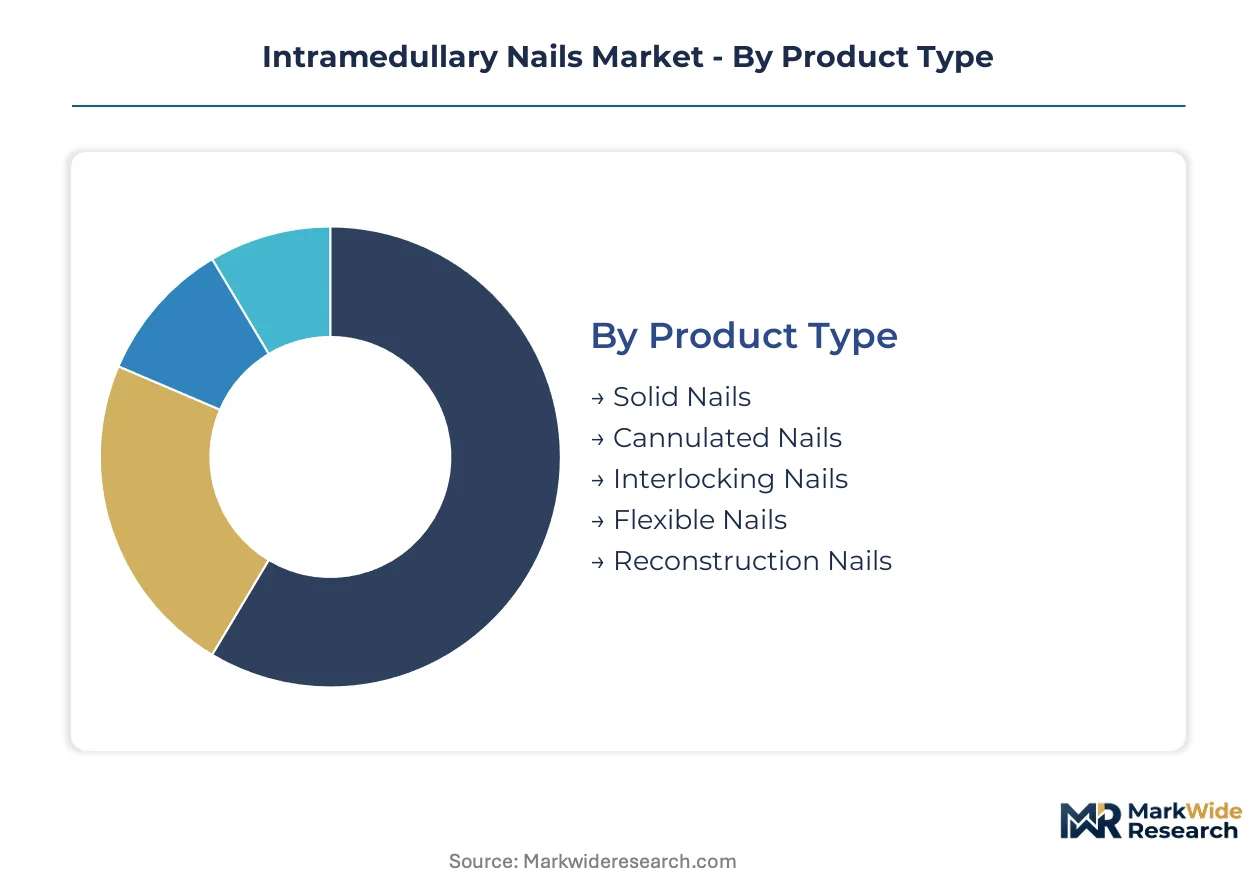
Intramedullary nails market segmentation reveals distinct demand patterns and technological requirements across various product types and applications. Understanding these segments helps manufacturers tailor product development and market access strategies to specific clinical needs and end-user preferences. The diverse material landscape further influences device performance and patient outcomes in orthopedic surgery.
Product Type:
The capital intensity associated with manufacturing different intramedullary nail product types varies significantly, driven by design complexity and required precision engineering.
- Interlocking Nails:These nails feature pre-drilled holes for screws that lock into the bone, providing superior rotational stability for complex fractures. Demand concentrates in major trauma centers in Germany, where high orthopedic procedure volumes require robust fixation solutions for femoral and tibial fractures.
- Cannulated Nails:Designed with a hollow core, these nails allow for easier insertion over a guide wire, streamlining surgical procedures and reducing operative time. Their adoption is accelerating in advanced healthcare systems in the United States, where procedural efficiency is a primary driver for surgical device selection.
- Solid Nails:These traditional nails offer basic intramedullary fixation, primarily used for simpler fracture patterns where rotational stability is less critical.
- Flexible Nails:Characterized by their smaller diameter and elasticity, flexible nails are often employed in pediatric orthopedics for diaphyseal fractures, accommodating bone growth.
- Reconstruction Nails:Specifically engineered for complex fractures involving bone loss or comminution, reconstruction nails provide enhanced stability for challenging anatomical repairs.
Interlocking Nails absorb the bulk of installed manufacturing capacity; Flexible Nails are expanding most quickly due to bioabsorbable polymer validation.
Application:
Application-specific demands dictate the design and material characteristics of intramedullary nails, ensuring optimal biomechanical performance for diverse fracture patterns.
- Femoral Fractures:These fractures, often high-energy injuries, require robust intramedullary nails that can withstand significant biomechanical stress and provide stable fixation. Trauma centers globally prioritize advanced femoral nailing systems for their proven efficacy in restoring limb function and promoting early mobilization.
- Pediatric Fractures:Treatment for pediatric fractures increasingly favors specialized nails, including flexible designs and bioabsorbable polymers, to minimize complications and avoid secondary removal surgeries. Clinical validation of bioabsorbable materials specifically drives demand in pediatric orthopedic surgery, particularly in Europe.
- Tibial Fractures:Tibial fractures, common in lower limb trauma, frequently utilize interlocking nails for stable fixation and early weight-bearing protocols.
- Humeral Fractures:Intramedullary nailing for humeral fractures provides stable fixation for shaft and proximal humerus injuries, supporting functional recovery in the upper limb.
- Clavicle Fractures:While less common for intramedullary nailing, clavicle fractures can benefit from specialized, smaller diameter nails in specific complex cases.
Femoral and Tibial Fractures represent the highest volume applications; Pediatric Fractures exhibit the steepest expansion trajectory due to material innovations.
End User:
The customer type and service level provided by end-user facilities significantly influence the procurement patterns and required product portfolios for intramedullary nails.
- Trauma Centers:These facilities handle a high volume of complex fractures, driving demand for advanced interlocking nails and integrated surgical systems that ensure rapid, effective intervention. Stryker Corporation leverages its extensive distribution network to supply major trauma centers in the United States.
- Orthopedic Clinics:Often serving as referral centers for less severe fractures or follow-up care, orthopedic clinics require a range of standard and specialized nails, frequently collaborating with hospitals for surgical procedures. Their purchasing decisions are influenced by patient demographics and local referral networks.
- Ambulatory Surgery Centers:Ambulatory Surgery Centers increasingly perform less complex orthopedic procedures, seeking cost-effective and efficient nailing solutions for suitable fracture types.
- Rehabilitation Facilities:While not performing surgeries, rehabilitation facilities indirectly influence demand by requiring stable fixation for effective post-operative recovery and physical therapy.
Trauma Centers remain the dominant end-user segment for high-performance nails; Ambulatory Surgery Centers are emerging as a growth area for specific procedures.
Material Type:
Material properties and associated regulatory hurdles fundamentally shape the development, clinical acceptance, and cost structure of intramedullary nails.
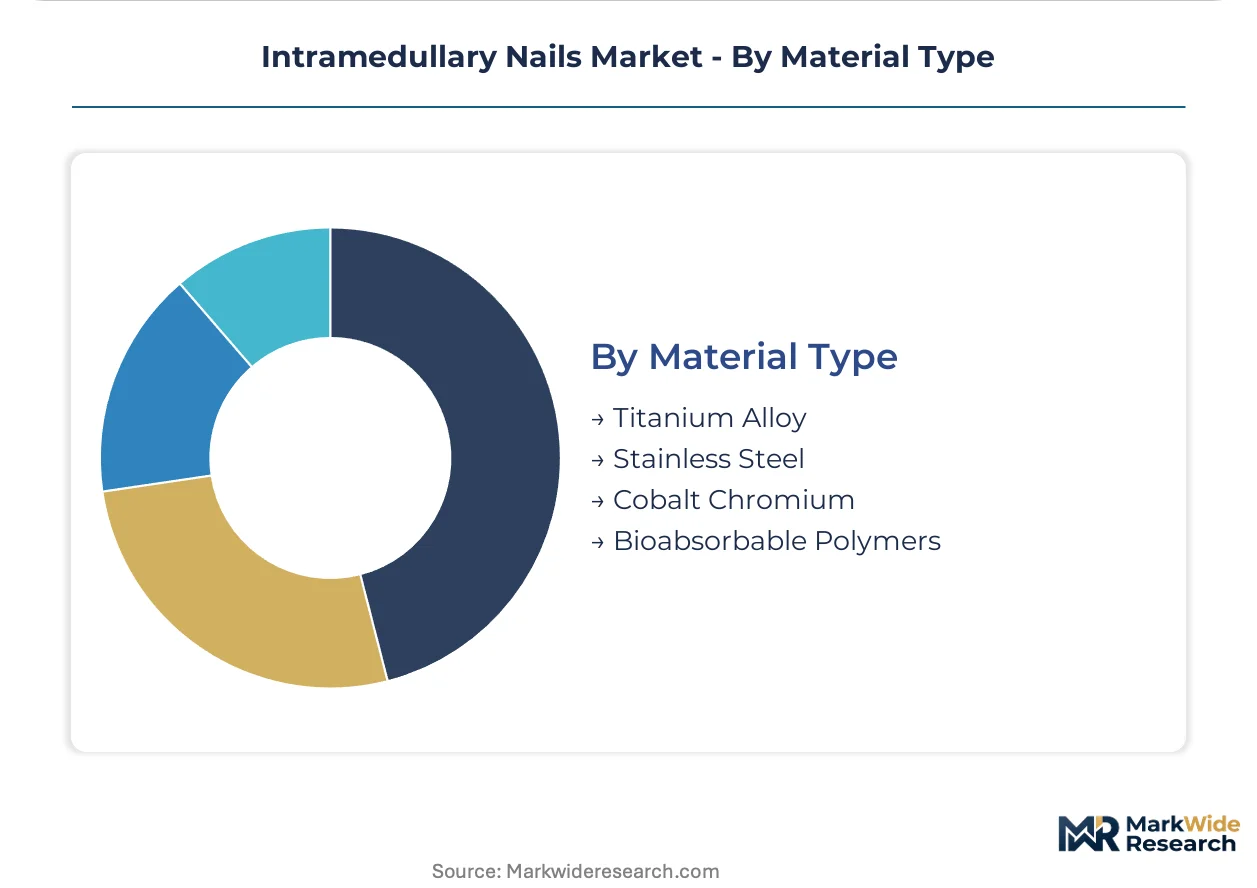
- Titanium Alloy:This material dominates the market due to its exceptional biocompatibility, high strength-to-weight ratio, and corrosion resistance, providing durable fixation for most adult fractures. Specialized contract manufacturing of titanium alloys in the United States is restructuring the supply chain.
- Bioabsorbable Polymers:These innovative materials offer temporary fixation that degrades over time, eliminating the need for a second removal surgery, particularly valued in pediatric applications. Clinical validation of these next-generation polymers creates new treatment pathways, especially in Europe.
- Stainless Steel:Stainless steel nails offer a cost-effective alternative to titanium, providing adequate strength and stiffness for certain fracture types, especially in price-sensitive markets.
- Cobalt Chromium:Used less frequently for nails, cobalt chromium alloys provide high strength and wear resistance, sometimes found in specific reconstructive or revision applications.
Titanium Alloy represents the established material of choice; Bioabsorbable Polymers are demonstrating disruptive potential in niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its advanced specialized contract manufacturing capabilities for titanium alloys, anchors the global supply chain for high-performance intramedullary nails. Demand patterns vary significantly across key geographies, influenced by healthcare infrastructure, regulatory frameworks, and demographic shifts. Material innovations, particularly bioabsorbable polymers, are creating new treatment pathways in specific regions.
United States
High orthopedic procedure volumes and advanced trauma centers drive significant demand for interlocking nails in the United States. The FDA's 510(k) clearance process influences product development and market entry strategies for new devices. Major medical device manufacturing clusters in the Midwest and Northeast continue to innovate in surgical systems and instrumentation.
Germany
Germany's aging demographics contribute to a high volume of orthopedic procedures, increasing the need for robust femoral and tibial fracture fixation. Europe's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence, shaping product availability. High-volume trauma centers in cities like Berlin and Munich actively standardize procedures with integrated surgical systems.
China
Expanding trauma care infrastructure in China creates a substantial volume opportunity for standard intramedullary nail systems. The NMPA imposes specific clinical data requirements, impacting product launch timelines and design choices for manufacturers. The Yangtze River Delta region is a significant hub for medical device manufacturing and distribution within the country.
India
India's growing healthcare sector and increasing incidence of road traffic accidents drive demand for both standard and advanced intramedullary nails. The Central Drugs Standard Control Organization (CDSCO) regulates medical device approvals, influencing market access for foreign manufacturers. Major metropolitan areas such as Mumbai and Delhi serve as key distribution centers for orthopedic implants.
Switzerland
Switzerland maintains a strong position in specialized contract manufacturing for high-performance titanium alloy nails, leveraging precision engineering expertise. Swissmedic, the national medical device regulator, ensures high safety and quality standards for devices marketed domestically. Clusters of advanced manufacturing and research facilities in regions like the Canton of Vaud contribute to material innovation.
Intramedullary Nails Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution networks, creating a tiered market structure. This landscape includes large, diversified medical device companies, specialized contract manufacturers, and innovators focusing on niche applications like bioabsorbable polymers. Strategic archetypes include integrated system providers, material specialists, and broad-portfolio suppliers. Competitive moves involve leveraging extensive distribution networks, focusing on clinical validation, and developing integrated surgical systems.
Among global device companies, Stryker Corporation exemplifies leveraging an extensive distribution network to supply major trauma centers. Zimmer Biomet occupies a position by focusing on integrated surgical systems and instrumentation for complex procedures. DePuy Synthes (Johnson & Johnson) also sits within this tier, offering a broad orthopedic portfolio across various fracture types and patient demographics.
| Leading Market Players |
|---|
| DePuy Synthes (Johnson & Johnson) |
| Orthofix Medical Inc. |
| Stryker Corporation |
| Arthrex, Inc. |
| B. Braun Melsungen AG |
| Zimmer Biomet |
| Medtronic plc |
| Globus Medical |
| Smith+Nephew |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) compliance gates qualified supply for advanced intramedullary nails, influencing premium-tier pricing for devices meeting these stringent material and clinical validation standards.
Pricing Analysis
Comprehensive warranty and after-sales service bundling differentiates pricing for integrated surgical systems in the intramedullary nails market. Value-based pricing models reward devices with extensive clinical validation data and robust after-sales support. Pricing pressure stems from titanium alloy cost volatility, impacting manufacturers' margins. Ambulatory Surgery Centers exhibit higher price sensitivity compared to major trauma centers, which prioritize advanced, high-performance solutions.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model optimize delivery of intramedullary nails to trauma centers and orthopedic clinics. Manufacturing of high-performance titanium alloy nails concentrates in the United States and Switzerland. The supply chain relies on titanium alloy and increasingly on specialized bioabsorbable polymers. Commodity price volatility for titanium alloy presents a structural risk, impacting distribution through extensive direct sales networks to healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intramedullary nails market is a vertical-integration race, with major device companies pursuing upstream control over specialized material manufacturing or downstream integration into comprehensive surgical systems. This strategic positioning aims to optimize supply and enhance procedural efficiency for end-users.
For Market Incumbents: Acquire specialized contract manufacturing capabilities in titanium alloy to mitigate supply chain risks and secure material access. Incumbents should also deepen investment in clinical validation for anatomically specific nails, addressing the threat of poor fixation in osteoporotic bone. Leveraging extensive distribution networks can reinforce market share against emerging bioabsorbable polymer solutions. This strategy protects core product lines from material innovation threats.
For New Entrants and Emerging Players: Europe's Medical Device Regulation (MDR) in Europe opens a window for new entrants with clinically validated bioabsorbable polymer solutions. Target the pediatric fracture segment, leveraging the benefit of avoiding secondary removal surgeries. Focus on developing anatomically specific nails for complex fracture patterns, addressing unmet clinical needs. A direct-to-hospital sales model emphasizing procedural efficiency can secure initial market penetration.
For Investors and Strategic Acquirers: Increased M&A activity in specialized contract manufacturing is the leading indicator that consolidation across the supply chain is accelerating. Long-term viability remains strong, driven by aging demographics and trauma care expansion over the next decade. Target mid-cap innovators in bioabsorbable polymers or smart implant integration for strategic investment. Watch for significant clinical validation milestones for next-generation material technologies as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Smart Nails | Secures market access for data-driven postoperative care solutions in the United States. |
| CE Marking Pathway for Bioabsorbable Polymers | Allows market entry for innovative, removal-free pediatric fracture treatments in Europe. |
| Hospital System Partnership for Integrated Systems | Standardizes surgical procedures and enhances market penetration in high-volume trauma centers. |
| Backward Integration into Titanium Alloy Forging | Secures critical raw material supply and stabilizes manufacturing costs for core products. |
| R&D Investment in Anatomically Specific Designs | Addresses complex fracture patterns and improves fixation outcomes for specialized patient needs. |
Research Approach
Independent corroboration across clinician interviews, hospital procurement data, and regulatory filings underwrites the qualitative findings of this market analysis. Primary interviews with orthopedic surgeons, hospital purchasing committees, and R&D directors at device companies informed key insights. Secondary validation drew from FDA 510(k) clearances, Europe's MDR documentation, and industry association reports. This approach ensured bottom-up market sizing triangulated with top-down industry trends.
Rate-of-change decomposition modeled the market's evolution across the analysis window, integrating volume and value drivers for each segment. The framework segmented demand by product type, application, end-user, and material type, alongside regional healthcare infrastructure maturity. Compound annual growth rates were derived from historical data and projected adoption curves. Key forecast inputs included aging demographics and regulatory approval timelines for new device innovations.
The model assumes a particular technology adoption path; alternative pathways for smart implant integration would alter the outlook. Forecasts reflect assumptions regarding material innovation and healthcare infrastructure development. Geopolitical events impacting titanium supply are a key risk factor. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Hip Resurfacing Implants Market