
 Global Orthopedic Digit Implants Market | 2026-2036
Global Orthopedic Digit Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Digit Implants Market Foresight
Orthopedic implant distribution is reconfiguring as specialized distributors consolidate their grip on ambulatory surgical centers and direct-to-hospital logistics. Stryker leverages its integrated trauma and extremities portfolio to control channel access across North American metropolitan clusters. Zimmer Biomet sustains competitive density through dedicated foot-and-ankle sales specialists who occupy the high-volume orthopedic clinic segment. Smith & Nephew navigates pricing pressure by extending service contracts that bundle digit implants with wound management protocols.
Orthopedic digit implants are metallic or polymeric devices engineered to replace or stabilize phalangeal and metacarpal bone structures, typically manufactured from titanium alloys or cobalt-chrome substrates with porous coatings to promote osseointegration. Their primary purpose is restoring mechanical function to fingers and toes compromised by trauma, degenerative joint disease, or congenital deformity. Plates and screws dominate procedural volume in fracture repair due to surgeon familiarity and instrument standardization across operating rooms. Minimally invasive devices represent the fastest-expanding technology category as ambulatory centers prioritize reduced soft-tissue disruption and shorter recovery protocols. 3D printing concentrates margin pools in complex revision cases where patient-specific geometries command premium positioning against commoditized catalog implants.
FDA 510(k) clearances and EU MDR conformity assessments shape product development timelines and market access trajectories for manufacturers serving Western regulatory jurisdictions. Japan's PMDA and China's NMPA impose additional clinical evidence requirements that filter entrants capable of sustaining multi-country registration investments. Stakeholders must monitor how FDA breakthrough device designations for biodegradable digit implants alter competitive timelines and reimbursement negotiations across payor categories.
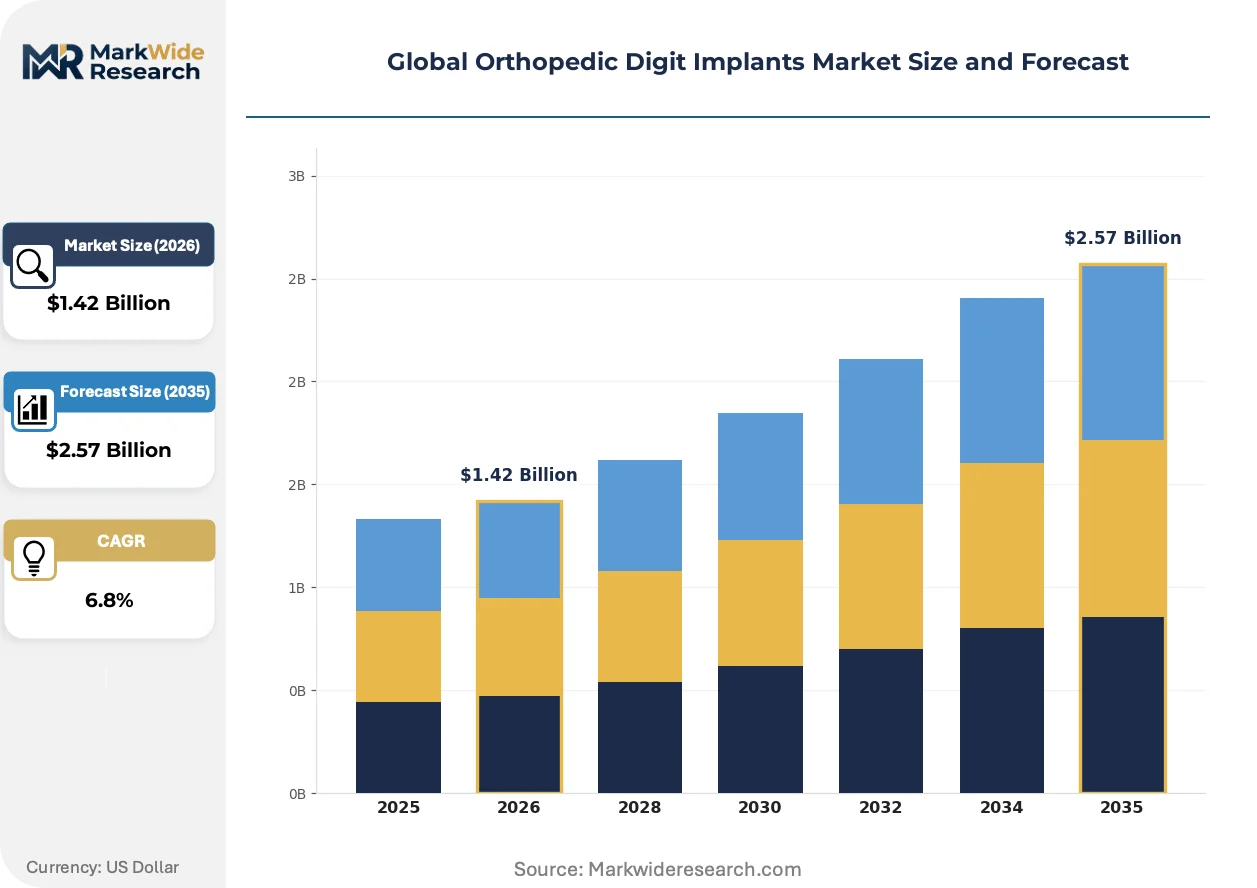
Market Dynamics
Site-of-care migration from inpatient hospitals to ambulatory surgical centers is compressing implant procurement cycles and forcing manufacturers to reconfigure logistics networks around same-day discharge protocols.
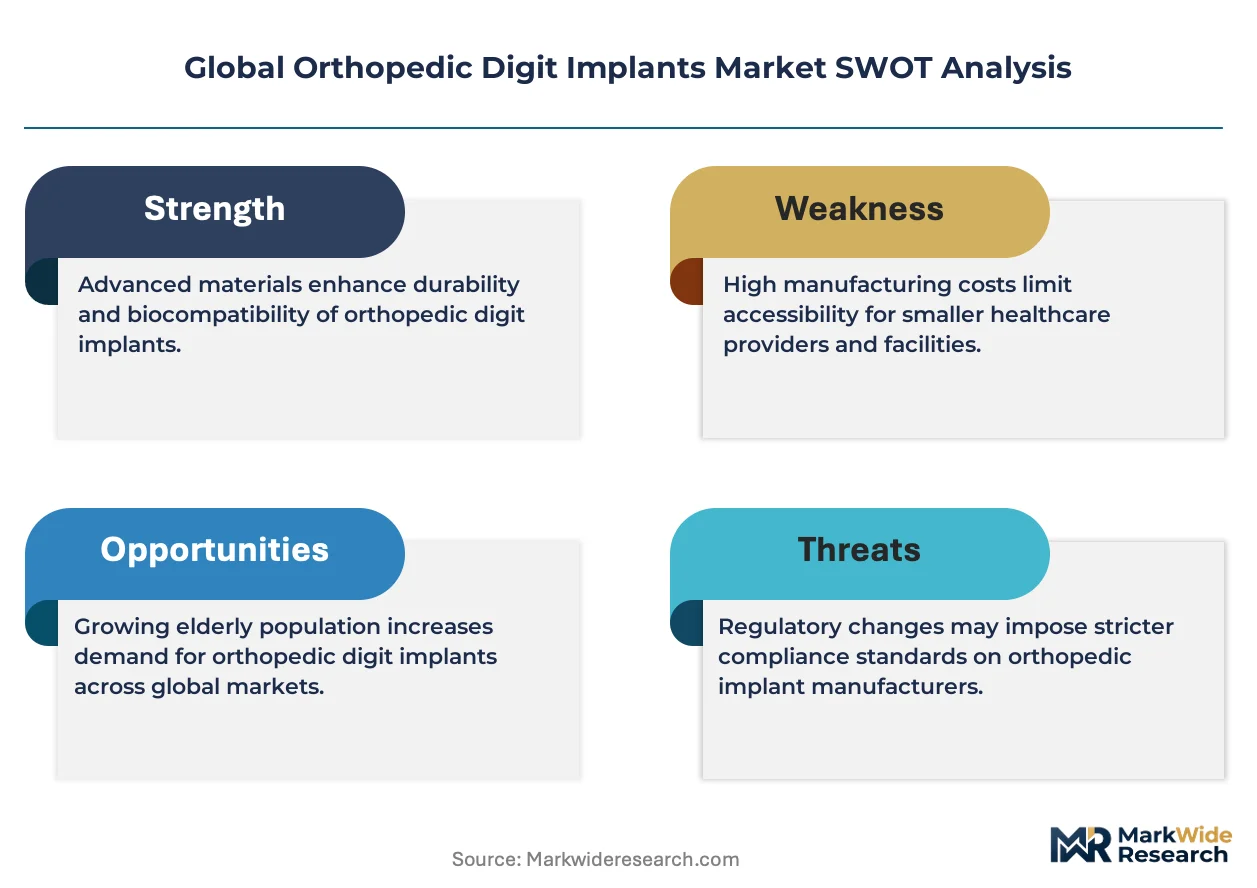
Growth Catalysts
- FDA 510(k) clearance compression:Streamlined pathways for patient-specific 3D-printed implants are accelerating commercialization timelines for complex revision geometries.
- Ambulatory surgical center expansion:United States outpatient facilities are adding dedicated extremities service lines that prioritize minimally invasive digit reconstruction procedures.
- Titanium alloy osseointegration coatings:Porous surface technologies are extending implant longevity and expanding indications to younger trauma demographics.
Market Restraints
- Cobalt-chrome feedstock concentration:Primary smelting capacity clusters in select mining jurisdictions create vulnerability to export restriction shocks.
- EU MDR technical documentation burden:Enhanced clinical evidence requirements for Class III devices are extending conformity assessment timelines by 12-18 months.
- External fixation substitution:Temporary stabilization devices retain preference in polytrauma cases where definitive implant timing is delayed.
Strategic Opportunities
- India orthopedic infrastructure buildout:Government hospital digit implant programs under national health mission schemes are creating volume anchors for mid-tier manufacturers.
- Bioresorbable polymer convergence:Magnesium alloy and polylactic acid composite platforms are opening pediatric deformity correction applications previously closed to permanent metal implants.
- Japan PMDA regenerative medicine fast-track:Cell-seeded implant frameworks qualify for conditional early approval pathways that compress development investment recovery periods.
Industry Challenges
- Orthopedic extremities fellowship scarcity:Limited specialized training programs in hand and foot surgery are constraining qualified surgeon pipeline growth.
- Multi-jurisdictional registration synchronization:Divergent FDA, PMDA, and NMPA clinical trial requirements force redundant evidence generation for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Digit Implants Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramedullary Nails, Plates & Screws, External Fixators, Bone Cement, Prosthetic Joints, Cerclage Wires Application: Fracture Repair, Osteoarthritis Management, Ligament Reconstruction, Bone Deformity Correction, Joint Stabilization, Spinal Fusion End User: Orthopedic Clinics, Specialized Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities, Research Institutes, Military Medical Units Technology: 3D Printing, Biodegradable Implants, Titanium Alloy, Coated Implants, Modular Systems, Minimally Invasive Devices |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Arthrex Inc, Acumed LLC, Extremity Medical LLC, Anika Therapeutics, Inc., VILEX, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Digit Implants Market Shifts & Advancements
Additive manufacturing workflows are penetrating implant production at the expense of conventional CNC machining, while regulatory frameworks race to adapt premarket review protocols to patient-matched geometries.
Patient-matched titanium lattice structures are hybridizing with topology optimization software to produce osseointegration surfaces previously unattainable through subtractive methods. Ambulatory surgical centers in Germany and Japan are adopting these implants for complex metacarpal revisions at triple the rate of standard catalog devices. The technology is hybridizing procurement specifications, forcing hospitals to abandon sole-source contracts in favor of design-service partnerships with additive manufacturers.
EU MDR Article 117 requirements for notified body involvement in implantable device quality system audits are elevating compliance costs for non-European manufacturers. The regulation is fragmenting market access timelines, with European Economic Area launches now lagging FDA clearances by 18-24 months. High-complexity 3D-printed digit implants face the steepest documentation burden, prompting some manufacturers to deprioritize CE marking in favor of United States and Japanese registrations.
Surgeon preference for single-use sterile-packed instrument kits is displacing traditional reusable tray systems in outpatient settings. United States ambulatory centers are negotiating all-inclusive per-procedure pricing that bundles implant, instrumentation, and disposable consumption. The shift is compressing distributor margins and forcing inventory consolidation onto manufacturers who must maintain consignment stock at point-of-care locations.
Global Orthopedic Digit Implants Market Segmentation
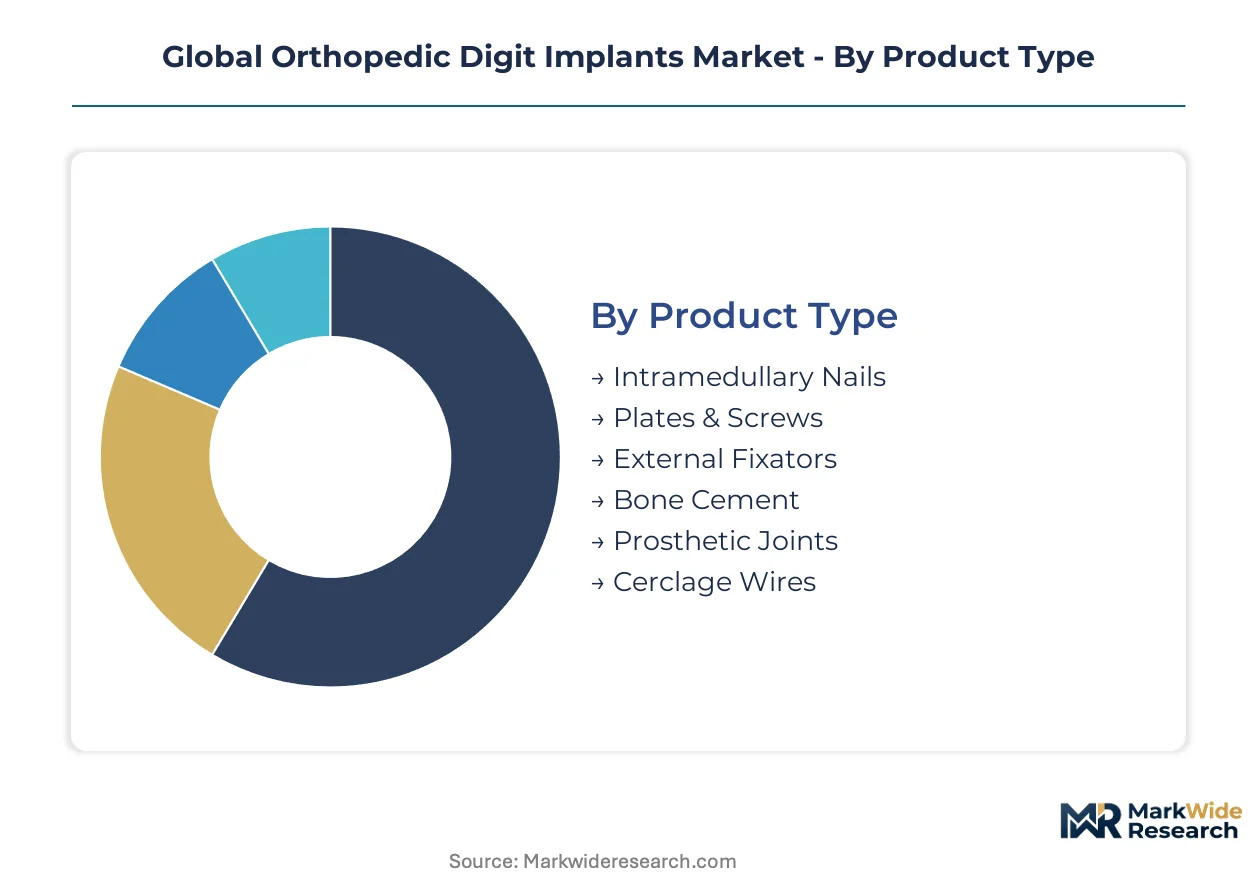
Orthopedic digit implant manufacturers must align production capacity with divergent clinical requirements across trauma reconstruction, degenerative joint replacement, and congenital deformity correction. Segmentation reveals where titanium alloy commoditization competes against patient-specific premium positioning.
Product Type:
Mature fixation hardware dominates procedural volume while emerging geometries capture revision case premiums.
- Intramedullary Nails:These cannulated devices stabilize phalangeal shaft fractures through intramedullary fixation with locking screw options. Demand concentrates in German trauma centers where AO Foundation instrumentation protocols standardize surgical training. Titanium elasticity matches bone biomechanics better than stainless alternatives.
- Plates & Screws:Anatomically contoured titanium plates with variable-angle locking technology address periarticular fractures. United States ambulatory surgical centers stock these in sterile single-use kits to eliminate reprocessing delays. Surgeon familiarity across generations sustains volume leadership despite newer alternatives.
- External Fixators:Ring and linear configurations provide temporary stabilization for open fractures with soft-tissue compromise.
- Bone Cement:Polymethylmethacrylate adjuncts secure implant fixation in osteoporotic bone.
- Prosthetic Joints:Silicone and metal-polyethylene articulations replace destroyed metacarpophalangeal and interphalangeal joints.
- Cerclage Wires:Stainless steel or titanium loops supplement plate fixation in comminuted patterns.
Plates & Screws retain volume leadership; Prosthetic Joints hold the steepest expansion curve.
Application:
Cost tier stratification separates high-volume trauma protocols from premium arthroplasty procedures.
- Fracture Repair:Acute trauma stabilization accounts for the majority of digit implant procedures across emergency departments and ambulatory centers. Japan's aging population generates particular demand for low-energy osteoporotic fracture fixation. Reimbursement bundles favor efficient hardware selection over premium alternatives.
- Osteoarthritis Management:Joint surface replacement and fusion address cartilage destruction in older demographics. German statutory health insurance covers silicone implant arthroplasty with established procedure codes. Younger patients increasingly seek surface replacement over fusion to preserve motion.
- Ligament Reconstruction:Suture anchor systems repair collateral ligament avulsions.
- Bone Deformity Correction:Gradual distraction osteogenesis addresses congenital or post-traumatic malalignment.
- Joint Stabilization:Fusion plates and interference screws manage instability patterns.
- Spinal Fusion:Cervical and lumbar applications extend manufacturer portfolios beyond extremities.
Fracture Repair commands the largest revenue pool; Osteoarthritis Management is expanding most quickly.
End User:
Customer type determines procurement sophistication and inventory carrying cost tolerance.
- Orthopedic Clinics:High-volume hand surgery practices in metropolitan United States clusters maintain consignment inventory for immediate case availability. These sites generate recurring demand for standard trauma hardware. Physician-owners negotiate direct manufacturer relationships to capture distributor margin.
- Specialized Hospitals:Academic medical centers in Japan and Germany handle complex revision referrals with multi-disciplinary teams. Their purchasing departments centralize implant selection across orthopedic subspecialties. Research participation influences device preference.
- Ambulatory Surgical Centers:United States outpatient facilities are consolidating extremities service lines with same-day discharge protocols.
- Rehabilitation Facilities:Post-acute settings manage implant rehabilitation protocols.
- Research Institutes:Biomechanical testing centers validate new implant designs.
- Military Medical Units:Combat trauma applications drive ruggedized fixation development.
Orthopedic Clinics sustain the highest procedure density; Ambulatory Surgical Centers are gaining share fastest.
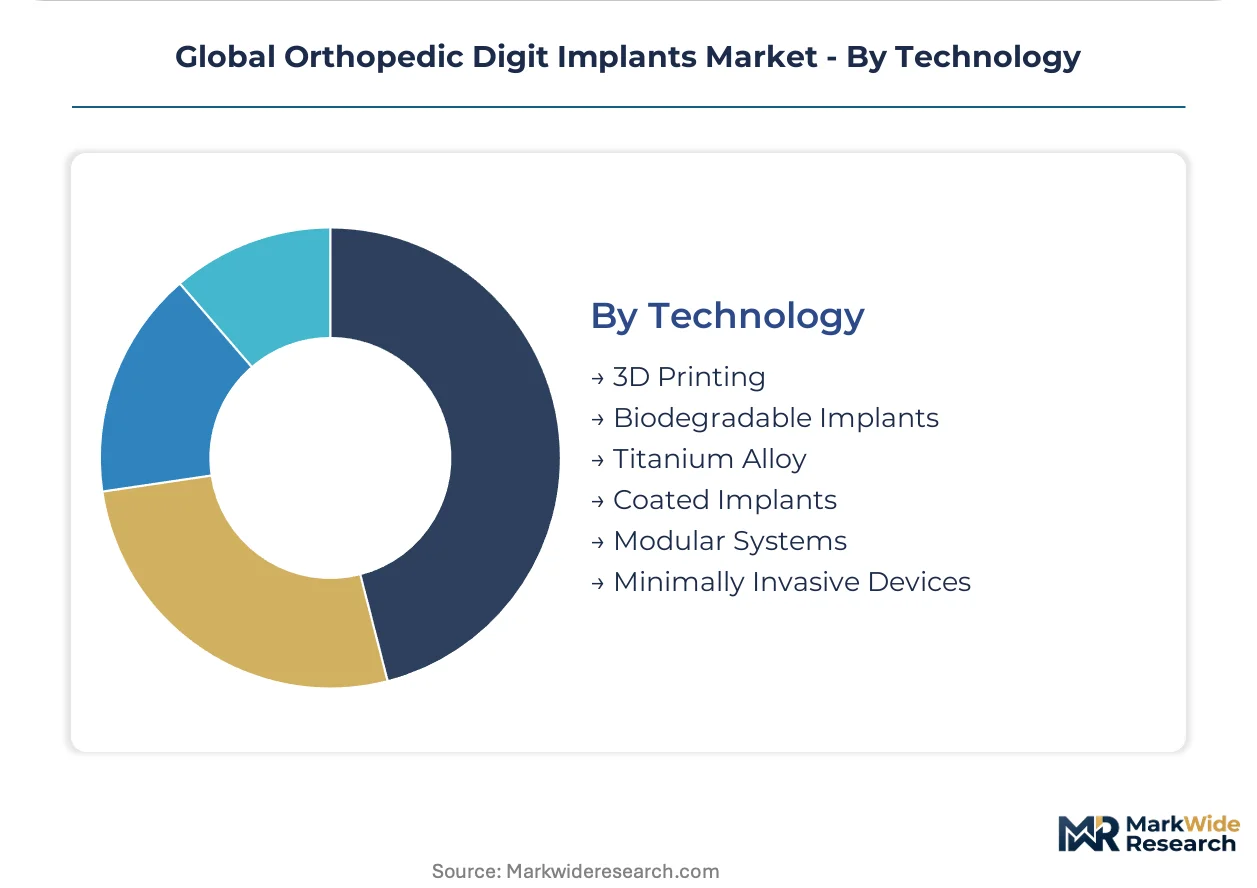
Technology:
Supply concentration in additive manufacturing equipment shapes competitive access to premium segments.
- 3D Printing:Electron beam melting produces patient-matched titanium lattice structures with topology-optimized porosity. German hospitals adopt these for complex metacarpal revisions at premium pricing against catalog alternatives. FDA breakthrough device designation accelerates clearance timelines for geometrically complex cases.
- Biodegradable Implants:Magnesium alloy and polylactic acid platforms eliminate secondary removal surgery in pediatric populations. Japan's PMDA regenerative medicine fast-track compresses approval timelines for resorbable scaffolds. Long-term degradation kinetics remain under clinical surveillance.
- Titanium Alloy:Ti-6Al-4V ELI dominates standard implant production with established supply chains.
- Coated Implants:Hydroxyapatite and porous plasma spray enhance osseointegration surfaces.
- Modular Systems:Interchangeable components reduce inventory breadth requirements.
- Minimally Invasive Devices:Percutaneous insertion instruments reduce soft-tissue disruption.
Titanium Alloy maintains manufacturing scale leadership; Biodegradable Implants present the steepest technology climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites Europe's distribution dominance for orthopedic implants, while direct air freight corridors from Memphis and Louisville anchor United States supply chain velocity.
United States
CMS reimbursement bundles for outpatient extremities procedures concentrate demand in ambulatory surgical centers across Texas, Florida, and Arizona retirement corridors. FDA 510(k) clearance timelines for patient-specific 3D-printed implants compress to 90-120 days under breakthrough device pathways. The Memphis logistics cluster supports same-day implant delivery to metropolitan surgical networks.
Germany
Statutory health insurance procedure codes for silicone joint arthroplasty sustain high-volume arthroplasty in Bavarian and North Rhine-Westphalian orthopedic clinics. EU MDR notified body audits extend conformity assessment timelines, filtering smaller manufacturers from CE marking pursuit. The Tuttlingen surgical instrument cluster integrates implant production with instrument sterilization logistics.
Japan
Aging demographics in Kansai and Chubu regions generate low-energy osteoporotic fracture volumes exceeding trauma case growth. PMDA regenerative medicine fast-track pathways compress biodegradable scaffold approvals to 24-month cycles. Tokyo metropolitan academic centers pioneer cell-seeded implant frameworks under conditional early approval schemes.
India
National Health Mission hospital digit implant programs under Ayushman Bharat create volume anchors for domestic manufacturers in Maharashtra and Gujarat. CDSCO medical device rules impose clinical trial requirements that foreign entrants navigate through local partnership structures. The Chennai orthopedic device corridor concentrates titanium machining capacity for export markets.
Switzerland
Swissmedic quality system audits for Class III implants maintain premium positioning for precision-manufactured trauma hardware. Proximity to Tuttlingen surgical networks enables just-in-time instrument kit consolidation. Geneva and Basel metropolitan clusters host extremities-focused orthopedic research consortia.
Global Orthopedic Digit Implants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios but deeper geometry expertise. The vendor base stratifies across three density layers: diversified orthopedic conglomerates with trauma-to-joint replacement breadth; mid-scale extremities-focused manufacturers with dedicated hand-and-foot sales infrastructure; and boutique additive fabricators serving patient-matched revision niches. Dominant competitive moves include strategic partnerships with ambulatory surgical center networks and backward integration into titanium powder supply.
Among diversified platform operators, Stryker, Zimmer Biomet, and Smith & Nephew occupy positions spanning catalog trauma hardware to patient-specific additive geometries. These manufacturers exemplify the integrated portfolio archetype, leveraging extremities specialization within broader orthopedic franchises to secure ambulatory center contracts. Their scale advantages concentrate in metropolitan United States clusters where surgeon training programs and implant procurement decisions intertwine.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| Arthrex Inc |
| Acumed LLC |
| Extremity Medical LLC |
| Anika Therapeutics, Inc. |
| VILEX, LLC |
| Others |
Supply & Pricing Matrix
Titanium alloy feedstock concentration in Chinese and Russian smelting jurisdictions anchors cost structures for standard digit implants while patient-specific additive geometries capture premium margin pools in revision cases. The pricing structure separates three tiers: premium patient-matched implants with design-service partnerships, standard catalog trauma hardware with volume contracting, and economy-grade cerclage wires with spot procurement.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between manufacturers and ambulatory surgical center networks. Three-tier pricing separates patient-matched additive implants from standard catalog plates and screws from economy cerclage wires. Price differentiation hinges on FDA breakthrough device designation status and consignment inventory terms. Pricing pressure stems from all-inclusive per-procedure bundling that compresses distributor margins. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with research participation show lowest.
Supply Chain Analysis
Upstream titanium sponge and cobalt-chrome powder production concentrates in China, Russia, and Kazakhstan. Feedstock sourcing draws from African mining jurisdictions for cobalt and Australian rutile deposits for titanium feedstock. Single-source vulnerability in electron beam melting equipment creates supply chain risk for additive manufacturers. Distribution runs through specialized orthopedic distributors with consignment stock at point-of-care locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward ambulatory surgical center networks as procurement consolidation accelerates across metropolitan United States clusters, fragmenting manufacturer pricing autonomy.
For Market Incumbents: Build captive titanium powder supply moats through backward integration into additive feedstock production. Secure exclusive design-service partnerships with high-volume ambulatory networks to lock out boutique additive competitors. Expand sterile single-use kit consignment capacity in Texas and Florida retirement corridors. Threat: boutique fabricators with patient-matched revision expertise. For New Entrants and Emerging Players: Build out biodegradable scaffold capabilities targeting Japan PMDA regenerative medicine fast-track pathways. White-space exists in pediatric digit deformity correction with magnesium alloy platforms. India's National Health Mission hospital programs offer penetrable volume anchors for mid-tier manufacturers. Go-to-market through local partnership structures navigating CDSCO clinical trial requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electron beam melting equipment and titanium powder atomization capacity. Long-term viability favors platform integrators with trauma-to-extremities breadth over component specialists. Acquisition target archetype: mid-scale extremities-focused manufacturers with dedicated hand-and-foot sales infrastructure. Signal to watch: FDA breakthrough device designation velocity for biodegradable digit implants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compresses 510(k) timelines to 90-120 days for patient-specific geometries. |
| Ambulatory Surgical Center Partnership | Locks in all-inclusive per-procedure pricing with same-day discharge protocols. |
| Backward Integration into Titanium Powder | Captures additive manufacturing feedstock margin and secures supply continuity. |
| EU MDR Notified Body Engagement | Navigates Article 117 quality system audits for Class III implant access. |
| Japan PMDA Regenerative Fast-Track | Accelerates biodegradable scaffold approvals under conditional early approval schemes. |
Research Methodology
The analysis maps trauma fixation hardware, joint replacement prosthetics, and patient-matched additive implants, each validated through hand surgeons, ambulatory center procurement directors, and biomedical engineers. Primary interviews with orthopedic clinic physician-owners, GPO contracts managers, and additive manufacturing engineers combined with secondary validation. Secondary sources include FDA 510(k) clearance databases, EU MDR notified body audit records, CMS Medicare reimbursement schedules, and hospital procurement contract filings. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue allocations.
Assumption sets held regulatory pathway timelines and ambulatory center penetration rates fixed while varying titanium alloy pricing and surgeon fellowship pipeline growth across the projection horizon. Segmentation dimensions modeled include product type, application, end-user facility type, and technology platform. CAGRs derive from procedure volume elasticity to aging demographic projections and reimbursement rate trajectories. Forecast inputs incorporate PMDA regenerative medicine approval velocity and EU MDR conformity assessment backlog data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified orthopedic conglomerates into additive manufacturing would shift outcomes. Specific risk factors include cobalt-chrome export restrictions, EU MDR technical documentation burden escalation, and orthopedic extremities fellowship scarcity constraining qualified surgeon supply. Cross-checking against CMS outpatient procedure volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Limb Salvage Systems Market