
 Digital Dental Cameras Market | 2026-2036
Digital Dental Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Dental Cameras Market Insights
The digital dental camera market is rebalancing between premium imaging suites and commodity handheld units. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to anchor the high-end segment with bundled software workflows. Carestream Dental competes through deep channel control in North American dental service organizations, while 3Shape specializes in open-architecture scanners that interoperate with third-party lab equipment.
Digital dental cameras are electro-optical devices that capture intraoral and extraoral anatomical structures using CMOS or CCD sensors with resolutions typically exceeding 720p, transmitting images via USB or wireless protocols for diagnostic review and patient communication. Their primary commercial purpose is to enhance treatment acceptance rates through visual case presentation and to satisfy insurance documentation requirements. Intraoral cameras lead volume shipments due to universal chairside adoption, while 3D imaging systems command the deepest margin pools from complex implant and orthodontic planning. Wireless technology is gaining fastest among mobile hygiene units and teledentistry deployments, though USB connectivity still dominates fixed operatory installations for latency-sensitive real-time video.
FDA 510(k) clearance pathways shape product launch timelines in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for intraoral devices sold in Europe. ISO 10993 biocompatibility standards govern materials that contact mucosal surfaces, creating compliance barriers for new entrants. Stakeholders must monitor how MDR notified body capacity constraints and FDA digital health pre-certification pilots reshape competitive access timelines.
Market Dynamics
CMOS sensor architecture is consolidating procurement decisions across dental service organizations, compressing legacy CCD supply chains while tightening documentation requirements from US insurers and European reimbursement authorities reshape fleet replacement cycles.
Growth Catalysts
- Reimbursement Documentation Mandates:US dental insurers now require intraoral imagery for pre-authorization of crown and bridge procedures, forcing independent practices to upgrade from analog impressions.
- CMOS Sensor Cost Curves:Wafer-scale manufacturing of backside-illuminated CMOS modules from Korean and Taiwanese foundries has collapsed per-unit sensor costs below CCD parity.
- German Precision Manufacturing:The Mittelstand dental equipment cluster around Lake Constance anchors global supply of high-resolution intraoral optics, creating dense supplier networks for adjacent component sourcing.
Market Restraints
- EU MDR Notified Body Bottlenecks:Stricter clinical evidence requirements for Class IIa intraoral devices under the 2017/745 regulation have extended European launch timelines by 14-18 months.
- Sony Image Sensor Dominance:Over 70% of premium dental camera modules rely on Sony CMOS supply, creating single-source vulnerability for manufacturers without alternative sensor qualification.
- Optical Glass Input Volatility:German and Japanese specialty glass suppliers face energy cost pressures, transmitting price instability into lens assembly costs.
Strategic Opportunities
- Teledentistry Platform Integration:Wireless intraoral cameras with cloud-native image pipelines are penetrating rural US health systems and Brazilian public dental networks.
- AI-Assisted Caries Detection:Convergence of real-time intraoral video streams with FDA-cleared machine learning algorithms creates premium pricing for diagnostic-augmented hardware.
- DSO Centralized Procurement:Large US dental service organizations are consolidating vendor relationships, favoring suppliers with enterprise-grade fleet management software and standardized training protocols.
Industry Challenges
- FDA 510(k) Predicate Device Navigation:Substantial equivalence determinations for novel wireless transmission protocols require extensive electromagnetic compatibility testing, stretching regulatory affairs team capacity.
- Legacy Practice Management Integration:Chairside cameras must interface with decade-old practice software from Dentrix, Eaglesoft, and Open Dental, demanding costly backward-compatible SDK development.
- Clinical Photography Training Gaps:Hygienist and assistant turnover in high-volume DSOs degrades image consistency, undermining the diagnostic value of captured intraoral documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Dental Cameras Market |
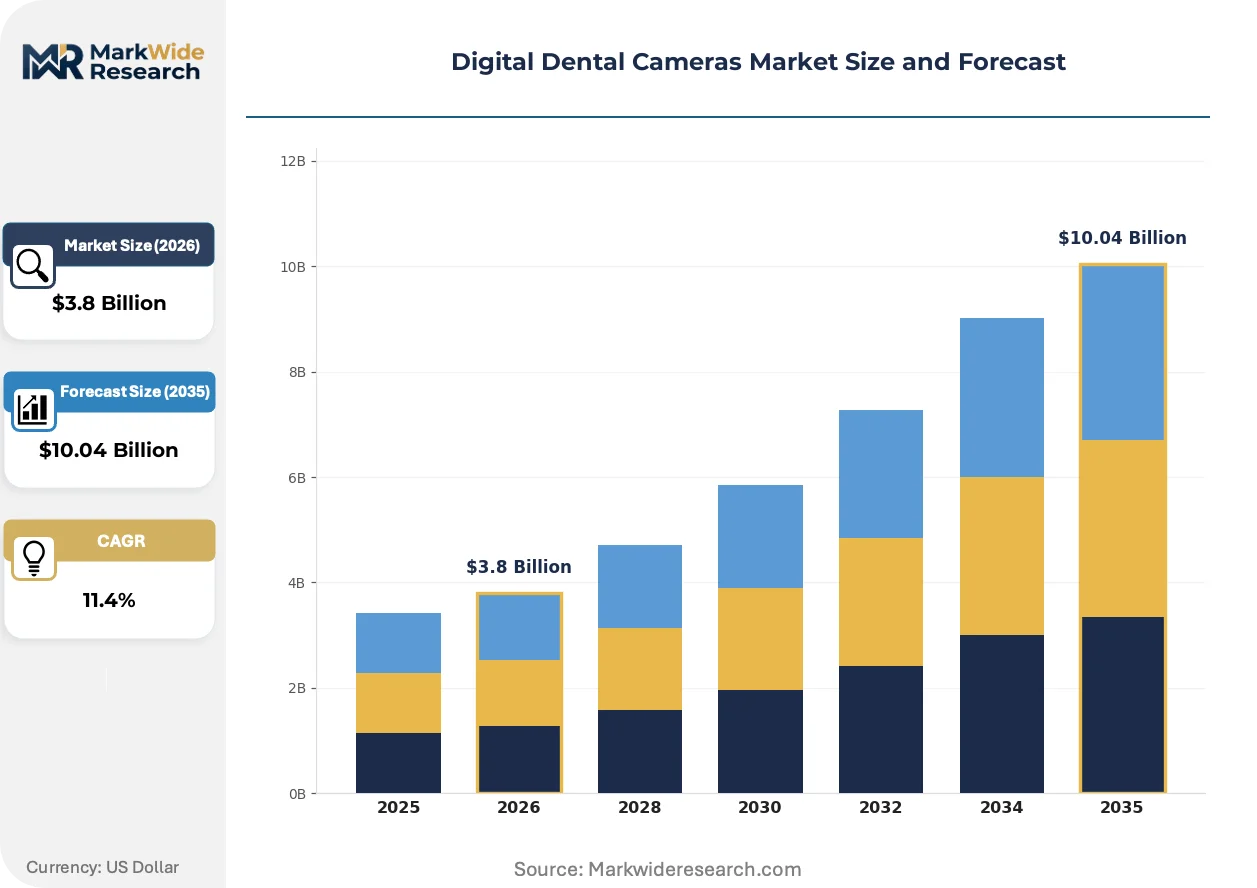
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Cameras, Extraoral Cameras, Handheld Cameras, 3D Imaging Systems End User: Dental Clinics, Hospitals, Research Institutions, Orthodontic Practices Technology: CCD, CMOS, Wireless, USB Connectivity Application: Diagnosis, Treatment Planning, Patient Education, Documentation |
| Companies Covered | Dentsply Sirona, Carestream Dental, Acteon Group, Planmeca, 3Shape, Durr Dental, KaVo Dental, Envista Holdings Corporation, VATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Dental Cameras Market Trends and Innovations
Wireless connectivity protocols and embedded AI inference engines are redefining hardware value capture, shifting competitive advantage from optical specifications to software-defined diagnostic workflows and enterprise data integration.
Backside-illuminated CMOS sensors with global shutter architectures are consolidating the mid-premium intraoral camera segment. DSO procurement teams now specify Sony IMX-based modules as baseline requirements for new chairside installations. This sensor homogenization is compressing differentiation among hardware-only vendors and forcing margin migration toward bundled software analytics.
The EU Medical Device Regulation's 2021 implementation deadline for Class IIa devices has triggered a regulatory segmentation divergence. Manufacturers with pre-MDR legacy approvals maintain European market access, while new entrants face stricter biocompatibility testing under ISO 10993-5 cytotoxicity protocols. German notified bodies TÜV SÜD and DEKRA have developed specialized dental device review tracks, concentrating European regulatory expertise in Bavaria.
DSO procurement offices are unbundling after-sales service from hardware acquisition, negotiating third-party maintenance contracts with regional dental equipment distributors. This disintermediation of OEM service revenue is most visible in Texas and Florida, where Heartland Dental and Smile Brands operate centralized fleet management centers. Independent practices retain traditional bundled purchasing, creating a two-tier channel structure.
Digital Dental Cameras Market Segmentation
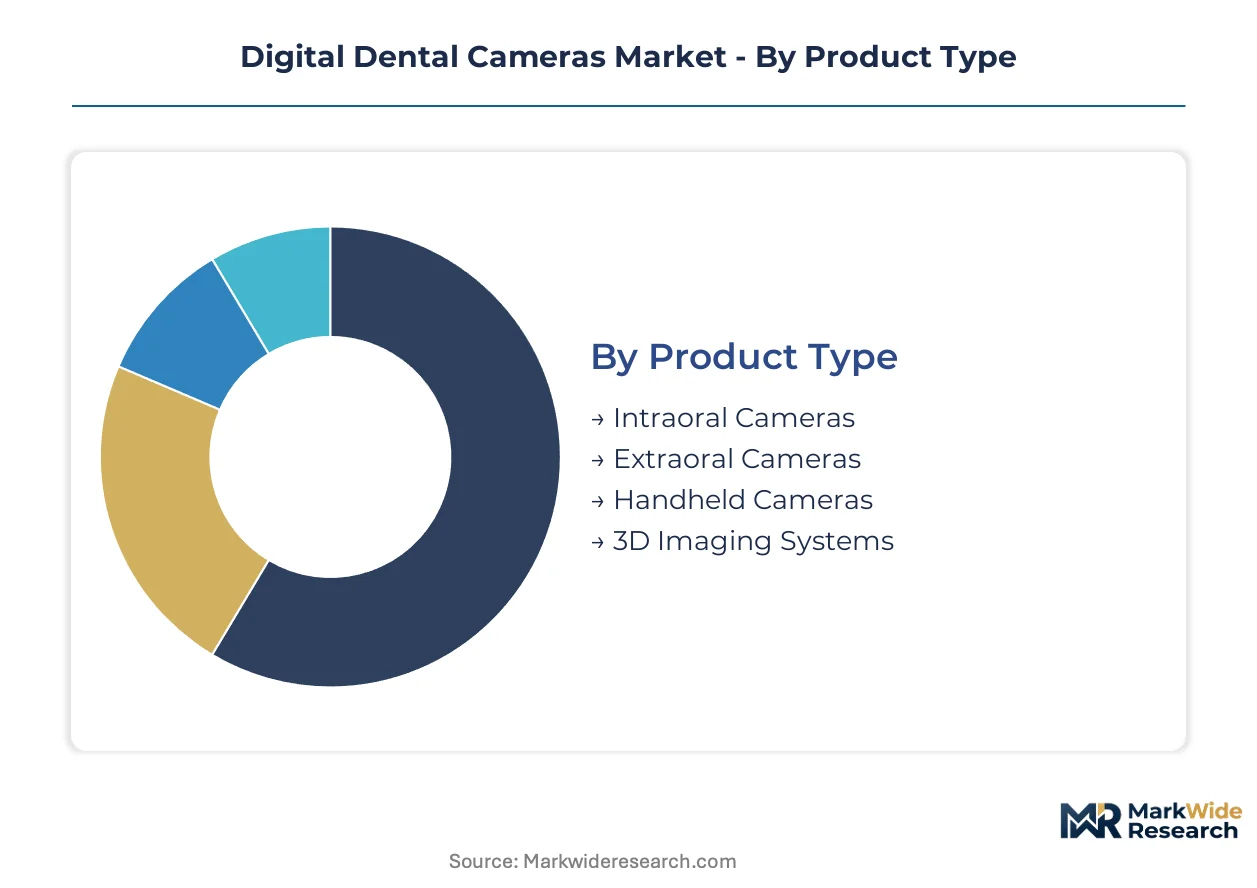
Segmentation in digital dental cameras reveals how regulatory pathways and procurement patterns diverge across device classes. Product type determines FDA 510(k) predicate requirements, while end-user concentration shapes channel economics and service bundling strategies.
Product Type:
FDA 510(k) clearance complexity escalates from handheld intraoral units to 3D imaging systems, with extraoral devices occupying an intermediate regulatory tier requiring electromagnetic compatibility validation.
- Intraoral Cameras:CMOS sensor-based handheld units with USB or wireless transmission capture real-time intraoral video at chairside. Dental clinics across the United States deploy these for insurance documentation mandates, with DSO procurement teams specifying Sony IMX sensor modules as baseline fleet standards.
- 3D Imaging Systems:Cone-beam computed tomography and structured-light scanners generate volumetric anatomical models for implant planning and orthodontic simulation. German precision manufacturers around Lake Constance anchor supply chains for high-resolution optical subassemblies, though EU MDR Class IIa certification bottlenecks extend European launch timelines.
- Extraoral Cameras:Wall-mounted or mobile units capture extraoral facial photography for orthodontic records and cosmetic case documentation.
- Handheld Cameras:Compact battery-operated devices enable mobile hygiene units and teledentistry deployments in rural health systems.
Intraoral cameras sit at the top of the volume ranking, with 3D imaging systems climbing the fastest as complex procedure volumes expand.
End User:
Customer concentration determines pricing power and service contract structures, with large DSO networks extracting volume discounts unavailable to fragmented independent practices.
- Dental Clinics:Independent and group practices generate the majority of unit demand, driven by insurance pre-authorization requirements for crown and bridge procedures. Texas and Florida DSOs operate centralized fleet management centers that disintermediate OEM service relationships.
- Hospitals:Academic medical centers and hospital-based dental departments prioritize 3D imaging integration with electronic health record systems, requiring HL7 interoperability and IT security compliance that smaller clinics bypass.
- Orthodontic Practices:Specialty providers concentrate demand for extraoral photography and 3D scanning systems to support clear aligner therapy workflows.
- Research Institutions:Universities and dental schools acquire high-specification imaging equipment for clinical validation studies and training programs.
Dental clinics command the deepest volume concentration, with hospitals expanding most quickly as health systems integrate oral health into primary care networks.
Technology:
Sensor architecture and connectivity protocols determine procurement specifications and backward compatibility requirements with legacy practice management software.
- CMOS:Backside-illuminated sensors from Korean and Taiwanese foundries have displaced legacy CCD modules through cost parity and superior low-light performance. Sony image sensor dominance creates supply concentration risk for manufacturers lacking alternative qualification pathways.
- Wireless:Bluetooth and Wi-Fi transmission protocols enable mobile hygiene workflows and cloud-native image pipelines for teledentistry platforms. Brazilian public dental networks and rural US health systems drive fastest adoption, though electromagnetic compatibility testing stretches FDA 510(k) timelines.
- CCD:Legacy charge-coupled device technology persists in installed base replacement cycles but faces accelerating obsolescence as CMOS wafer-scale manufacturing collapses per-unit costs.
- USB Connectivity:Wired protocols dominate fixed operatory installations where latency-sensitive real-time video transmission remains critical.
CMOS technology holds the dominant volume position, with wireless connectivity gaining share fastest as mobile and remote care models proliferate.
Application:
Use case specificity determines software integration depth and reimbursement eligibility, with diagnostic applications commanding premium pricing against documentation-only deployments.
- Diagnosis:AI-augmented caries detection and periodontal assessment algorithms create premium hardware pricing when bundled with FDA-cleared machine learning workflows. Real-time video analysis requires embedded inference engines that differentiate high-end intraoral camera systems.
- Documentation:Insurance pre-authorization and claims submission drives baseline intraoral camera adoption, with US dental insurers now mandating imagery for crown and bridge procedures.
- Treatment Planning:3D imaging integration with CAD/CAM workflows supports implant surgical guide fabrication and orthodontic appliance design.
- Patient Education:Chairside visual case presentation improves treatment acceptance rates through immediate anatomical visualization.
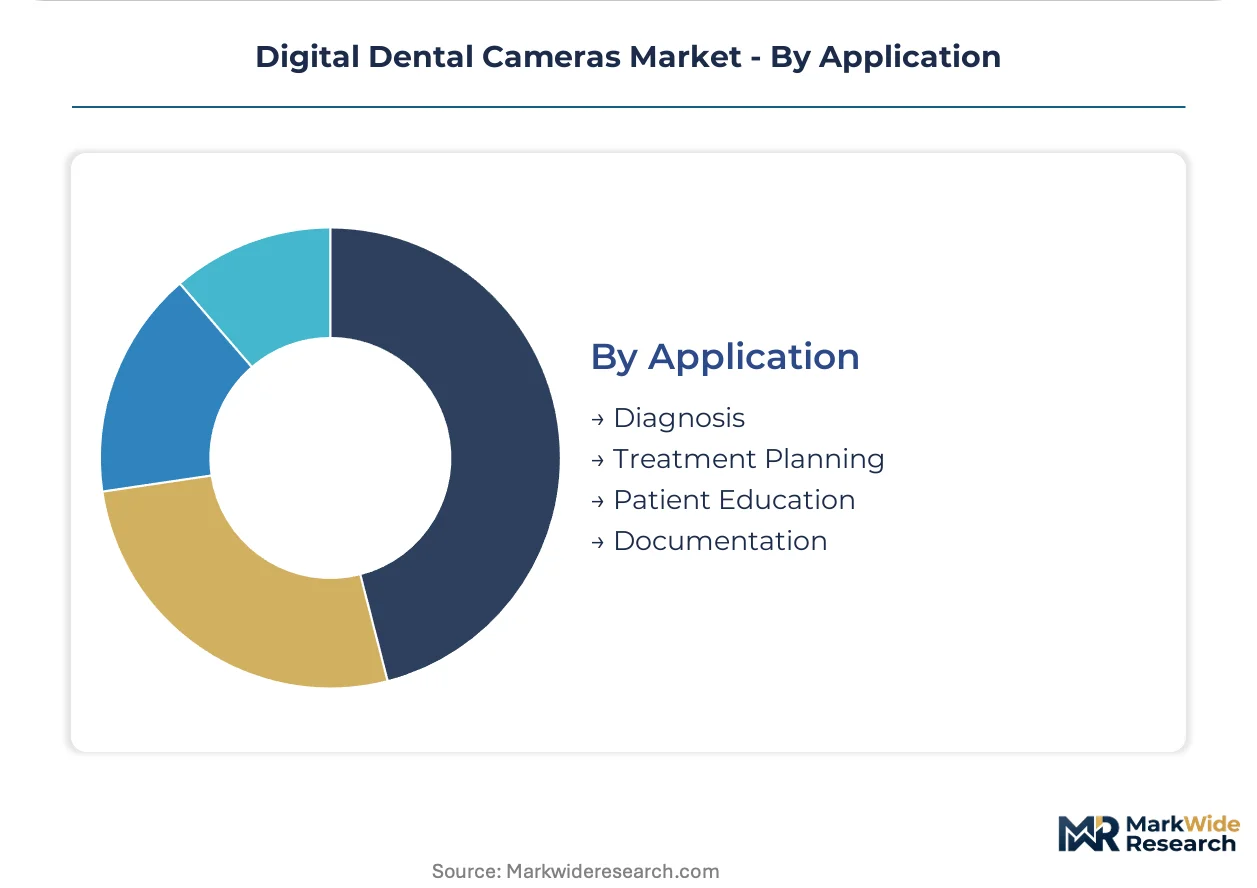
Documentation applications anchor current volume, with diagnosis expanding most quickly as regulatory clearance for AI-assisted algorithms proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys intraoral cameras at triple the per-clinic rate of Japan, yet German manufacturers still capture the premium optical subassembly market. This divergence reflects how reimbursement policy and precision manufacturing geography shape regional competitive dynamics differently.
United States
DSO networks in Texas and Florida operate centralized fleet management centers that disintermediate OEM service relationships. FDA 510(k) clearance pathways compress product launch timelines for wireless intraoral devices. The Dallas-Fort Worth metro anchors the largest concentration of dental service organization headquarters procurement offices.
Germany
The Mittelstand cluster around Lake Constance supplies high-resolution optical subassemblies to global camera manufacturers. EU MDR notified bodies TÜV SÜD and DEKRA have developed specialized dental device review tracks, concentrating regulatory expertise in Bavaria. Stuttgart-based precision optics fabricators face energy cost pressures from specialty glass supply volatility.
China
Domestic CMOS sensor foundries in Shanghai and Shenzhen are displacing legacy CCD imports for mid-market intraoral camera assembly. NMPA medical device registration requirements are harmonizing with international standards under revised Class II device pathways. The Yangtze River Delta hosts the densest concentration of dental equipment contract manufacturers.
Japan
Sony image sensor dominance creates supply concentration risk for manufacturers lacking alternative qualification pathways. PMDA regulatory timelines for wireless transmission protocols require extensive electromagnetic compatibility documentation. Tokyo and Osaka metropolitan areas concentrate demand from university dental schools and research institutions.
Brazil
Public dental networks in São Paulo and Minas Gerais are deploying wireless intraoral cameras for teledentistry platforms in rural health systems. ANVISA medical device registration pathways are streamlining for Class IIa intraoral devices under harmonized Mercosur standards. The São Paulo metropolitan corridor anchors Latin America's largest dental equipment import distribution hub.
Digital Dental Cameras Market Competitive Landscape
Top-tier vendors anchor integrated CAD/CAM ecosystems, while mid-tier specialists compete through open-architecture interoperability. The vendor base stratifies across three tiers: premium imaging suite providers, channel-controlled regional suppliers, and commodity hardware assemblers. Two strategic archetypes dominate: ecosystem bundlers leveraging software workflows, and component specialists capturing optical subassembly margins. M&A activity concentrates on wireless technology acquisitions and regional dental equipment distributor consolidation.
Among ecosystem-integrated multinationals, Dentsply Sirona and Carestream Dental exemplify contrasting channel strategies. Dentsply Sirona occupies a position within the premium-tier imaging suite segment, while Carestream Dental anchors North American DSO procurement relationships. KaVo Dental represents the German precision manufacturing archetype, sitting within the Mittelstand supplier network that feeds global camera assembly lines.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Carestream Dental |
| Acteon Group |
| Planmeca |
| 3Shape |
| Durr Dental |
| KaVo Dental |
| Envista Holdings Corporation |
| VATECH |
| Others |
Pricing and Supply Chain Analysis
Precision optics engineers concentrated around Germany's Lake Constance anchor global lens assembly capacity, with labor-cost differentials between Bavarian fabricators and Asian contract manufacturers generating three-tier pricing spreads across premium, standard, and economy intraoral camera tiers.
Pricing Analysis
Bundled after-sales service contracts versus unbundled hardware-only procurement splits the market into divergent pricing models. DSOs in Texas and Florida negotiate third-party maintenance arrangements that compress OEM service margins, while independent practices retain traditional bundled purchasing. Price differentiation hinges on Sony IMX sensor certification grade and ISO 10993 biocompatibility tier. Cost compression in mid-market CMOS modules intensifies as Korean foundry output expands. Mobile hygiene units and teledentistry deployments exhibit highest price sensitivity; integrated CAD/CAM ecosystem buyers show least.
Supply Chain Analysis
Optical glass supply rests on German and Japanese specialty producers facing energy cost volatility. CMOS sensor fabrication concentrates in South Korea, Taiwan, and Japan, with Sony image sensors feeding over seventy percent of premium dental camera modules. Backside-illuminated wafer production and precision lens grinding constitute critical input dependencies. Single-source vulnerability in Sony sensor qualification creates structural supply risk. Distribution runs through regional dental equipment distributors serving independent practices, alongside direct enterprise contracts with DSO procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital dental camera market represents a late-cycle quality story as reimbursement documentation mandates shift demand toward FDA-cleared, AI-augmented diagnostic specifications that command premium hardware pricing.
For Market Incumbents: Deploy backward integration into CMOS sensor qualification pathways to reduce Sony supply concentration. Anchor ecosystem stickiness through AI-assisted caries detection software bundled with chairside hardware. Counter emerging open-architecture scanner specialists by deepening CAD/CAM workflow integration. Fortify against DSO procurement disintermediation by developing proprietary fleet management analytics platforms. For New Entrants and Emerging Players: Rural US health systems and Brazilian public dental networks present underserved buyer archetypes with teledentistry-driven wireless camera demand. Penetrate mobile hygiene unit segments where incumbent service infrastructure remains thin. Exploit EU MDR notified body bottlenecks by targeting pre-MDR legacy approval holders for partnership or acquisition. Lead with cloud-native image pipelines and simplified practice management software integration. For Investors and Strategic Acquirers: Dental service organizations are the most active acquirer in this space, consolidating regional equipment distributors to capture procurement influence. Five-to-ten year viability favors component specialists with alternative sensor qualification and software-defined diagnostic workflows. Target acquisition archetypes include wireless transmission protocol developers and AI-assisted imaging algorithm holders. Watch FDA digital health pre-certification pilot expansion as inflection signal for accelerated product launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Sensor Qualification Pathway | Reduces Sony CMOS supply concentration risk for manufacturers seeking second-source validation. |
| AI-Assisted Caries Detection Clearance | FDA-cleared machine learning algorithms enable premium hardware pricing and diagnostic workflow bundling. |
| DSO Fleet Management Platform | Enterprise-grade software counters procurement disintermediation by Texas and Florida network operators. |
| EU MDR Specialized Review Track | Bavarian notified body concentration accelerates Class IIa intraoral device European market access. |
| Teledentistry Cloud Integration | Wireless image pipelines penetrate rural US health systems and Brazilian public dental networks. |
Research Methodology
Multiple input streams — clinician interviews, DSO procurement officer discussions, biomedical engineer consultations, and regulatory affairs specialist engagements — were reconciled with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and dental equipment customs data. Bottom-up intraoral camera shipment estimates and top-down imaging system revenue analysis were triangulated to establish market sizing.
Data-stream reconciliation across product type, technology architecture, end-user concentration, and application specificity dimensions shaped the analytical framework. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs incorporated CMOS sensor cost curve projections, DSO network expansion patterns, and reimbursement policy evolution across US and European jurisdictions.
Underlying measurement precision varies by segment; intraoral camera volume estimates carry tighter precision than emerging AI-augmented diagnostic hardware categories. Forecasts incorporate assumptions regarding FDA digital health pre-certification adoption and EU MDR notified body capacity normalization. Regulatory timeline delays, sensor supply disruptions, and DSO procurement consolidation represent specific risk factors that could revise projections. A small set of reimbursement mandate expansions and AI diagnostic clearance decisions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
US Orthodontics Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Dental Radiometer Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Calipers Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Irrigation Devices Market