
 Orthopedic Support Systems Market | 2026-2036
Orthopedic Support Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Support Systems Market Analysis
The orthopedic support systems market is recalibrating around a widening gap between premium carbon-fiber custom orthoses and commodity-grade polymer supports. Ottobock leverages its German engineering heritage to dominate the high-technology prosthetic-brace segment, while DJO LLC anchors its position through scale manufacturing of off-the-shelf rehabilitation products. Bauerfeind competes in the sports-medicine channel with differentiated compression and bracing systems that command premium placement in orthopedic clinics.
Orthopedic support systems encompass rigid, semi-rigid, and soft apparatus engineered to immobilize, stabilize, or mechanically assist musculoskeletal structures during recovery or chronic management; devices typically incorporate thermoformable plastics, aluminum uprights, or textile-based tensioning systems calibrated to specific torque and range-of-motion specifications. Braces fabricated from advanced composites capture disproportionate margin pools in post-surgical applications, while the home care channel sustains volume leadership through simplified fitting protocols and direct-to-patient distribution. Fabric-based supports represent the fastest-growing material category, displacing traditional foam constructions in preventative care segments where breathability and washability drive replacement cycles.
The FDA's 21 CFR Part 890 classification framework and the EU Medical Device Regulation (MDR) impose divergent conformity pathways that fragment market access strategies between North American and European suppliers. ISO 13485 quality management certification operates as a baseline gating requirement for contract manufacturing relationships with hospital purchasing consortiums. Stakeholders must monitor evolving reimbursement coding for remote patient monitoring integrations that promise to reshape how compliance and outcomes data justify durable medical equipment expenditure.
Market Dynamics
The orthopedic support systems market pivots on the structural tension between Germany's statutory rehabilitation insurance mandates and the FDA's accelerated 510(k) clearance pathway, which together compress commercialization timelines while fragmenting reimbursement protocols across Atlantic regulatory regimes.
Growth Catalysts
- Statutory rehabilitation frameworks:Germany's statutory rehabilitation insurance anchors demand for post-surgical bracing systems through mandated coverage of functional recovery devices.
- Carbon-fiber composite adoption:Advanced composite fabrication processes enable lighter load-bearing orthoses that penetrate premium post-operative segments previously served by aluminum uprights.
- Dynamic bracing protocols:Sports medicine clinics in North American metropolitan markets integrate range-of-motion adjustable systems into accelerated return-to-play protocols.
Market Restraints
- Petrochemical input volatility:Thermoformable polymer feedstock costs fluctuate with crude oil indices, compressing margins on commodity-grade supports manufactured at scale.
- MDR conformity bottlenecks:The EU Medical Device Regulation imposes extended clinical documentation requirements that delay market access for novel textile-based tensioning systems.
- Home care fitting limitations:Self-application protocols for rigid orthoses generate higher return rates when patients lack professional fitting support.
Strategic Opportunities
- Remote patient monitoring integration:Sensor-embedded braces that transmit compliance data to orthopedic clinics unlock new reimbursement coding pathways under evolving durable medical equipment frameworks.
- Fabric-based preventative segments:Breathable textile constructions displace foam supports in athletic prophylaxis applications where washability drives replacement frequency.
- Indian outpatient rehabilitation expansion:Private hospital chains in Maharashtra and Karnataka build dedicated orthopedic recovery centers that standardize bracing protocols.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for contract manufacturers stretch 12-18 months, gating relationships with hospital purchasing consortiums.
- Biomechanical engineering talent scarcity:Specialized expertise in torque calibration and range-of-motion specification concentrates in German and Swiss research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Support Systems Market |
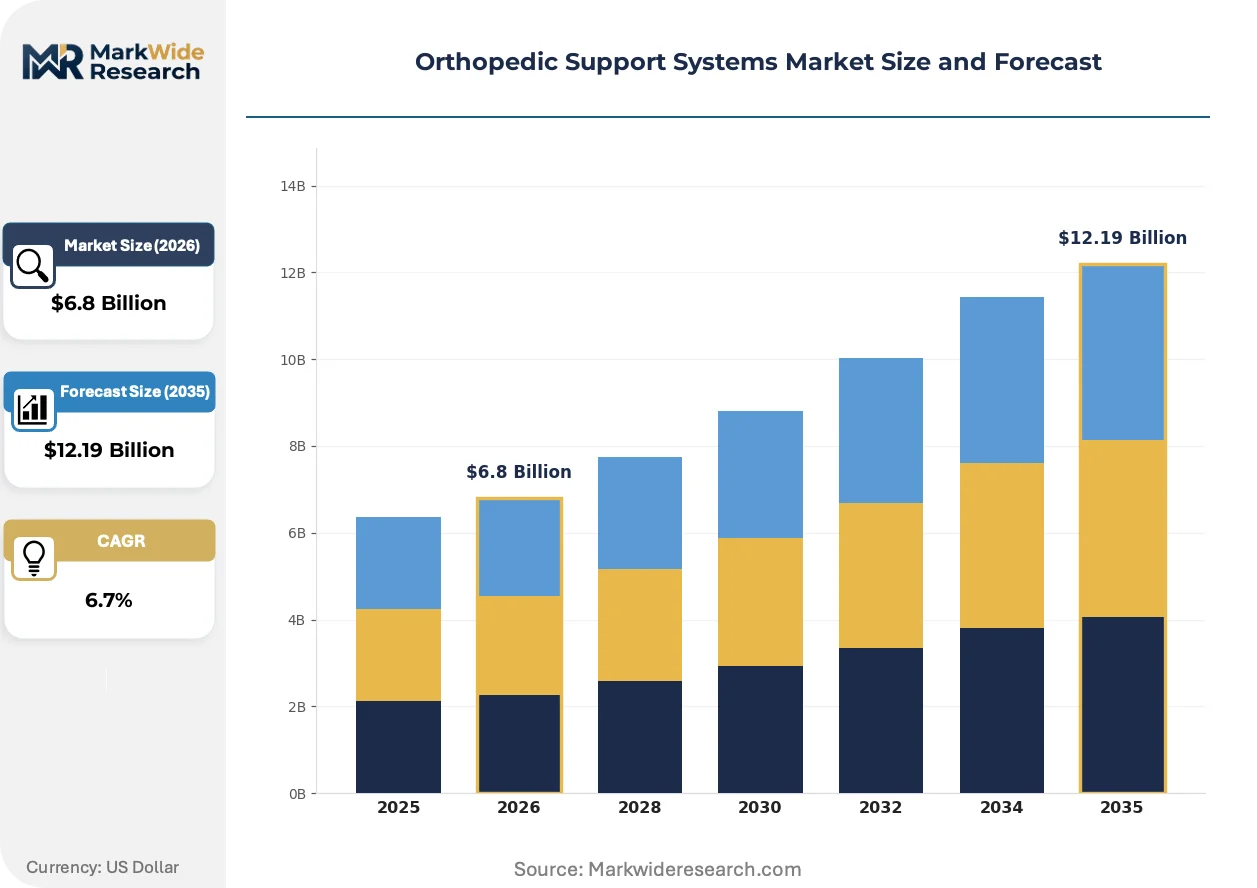
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Splints, Supports, Casts End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Material: Plastic, Fabric, Metal, Foam Application: Post-Surgery, Injury Recovery, Pain Management, Preventative Care |
| Companies Covered | Ottobock, Össur, DJO LLC, Breg Inc., Bauerfeind, DeRoyal Industries, Zimmer Biomet, 3M, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Support Systems Market Emerging Trajectories
Orthopedic support systems are undergoing material and regulatory recalibration as smart textiles, accelerated FDA pathways, and direct-to-patient distribution reshape how devices reach end-users and how value is captured across the value chain.
Additive manufacturing of patient-specific lattice structures is rewriting the economics of custom orthosis production. Orthopedic clinics in academic medical centers adopt 3D-printed ankle-foot orthoses with topology-optimized stiffness gradients. The technology is compressing turnaround times from casting to delivery from weeks to days while collapsing the traditional plaster-cast-to-thermoform workflow.
MDR Article 10 technical documentation requirements are elevating entry barriers for soft brace suppliers serving European markets. Manufacturers must now submit clinical evaluation reports for textile-based compression systems previously cleared through self-certification. German distributors report 40% of Asian suppliers have suspended EU market entry rather than absorb compliance costs.
Direct-to-consumer fitting platforms are fragmenting the traditional durable medical equipment channel. Patients in US suburban markets purchase off-the-shelf knee braces through telehealth-integrated e-commerce portals that provide video-guided sizing protocols. Sports medicine practices respond by unbundling professional fitting services from device markup, shifting revenue to consultation fees.
Orthopedic Support Systems Market Segmentation
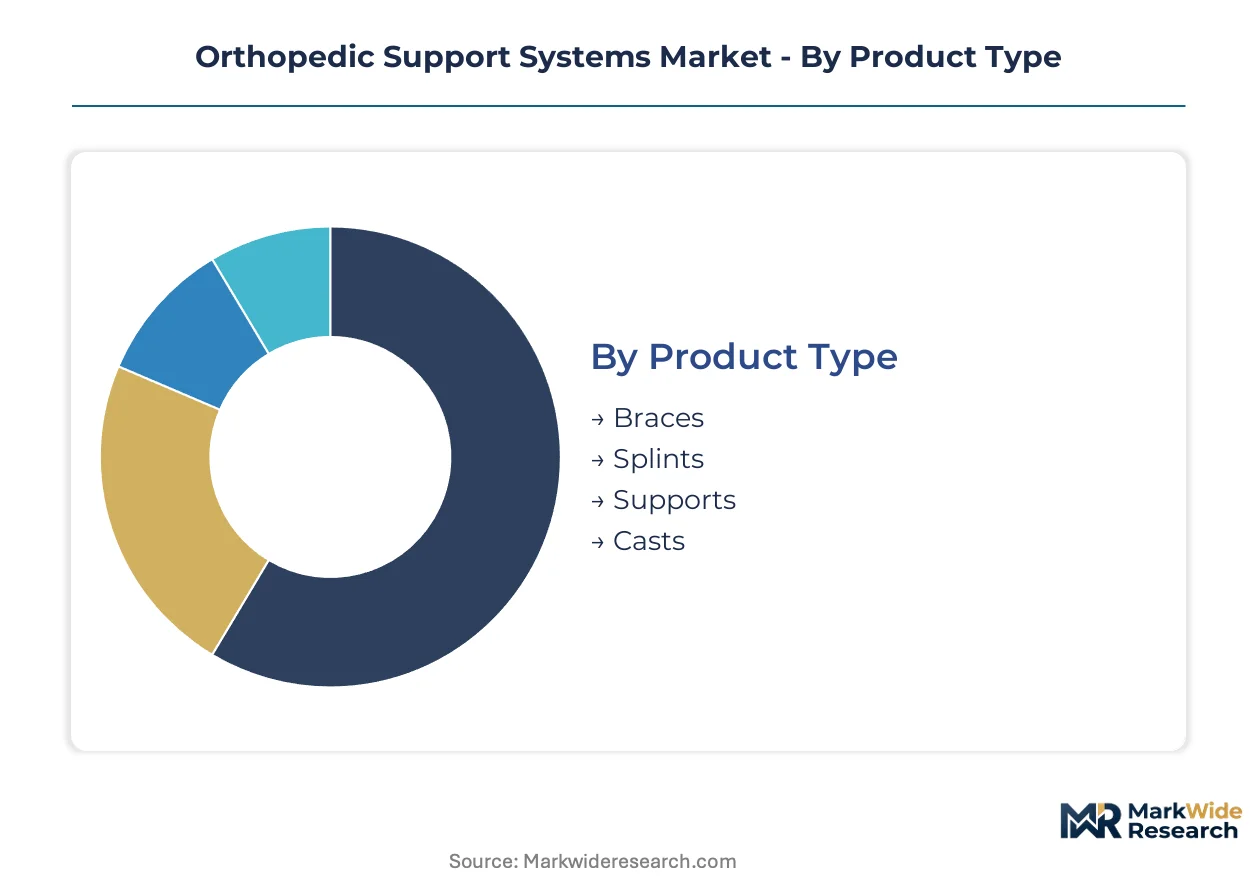
Orthopedic support systems fragment across four intersecting dimensions that determine reimbursement pathways, fitting protocols, and margin structures. Product type dictates manufacturing complexity and regulatory classification. Material selection governs weight, breathability, and washability—properties that increasingly drive replacement cycles in athletic and home care segments.
Product Type:
Clinical severity and immobilization duration anchor procurement decisions, with post-operative protocols demanding rigid stabilization while chronic management favors adjustable systems.
- Braces:Rigid and semi-rigid apparatus incorporating aluminum uprights or carbon-fiber struts calibrated to specific torque thresholds. Range-of-motion adjustable systems concentrate in North American sports medicine clinics where accelerated return-to-play protocols dominate rehabilitation timelines.
- Splints:Thermoformable polymer shells fabricated from low-temperature plastics that emergency departments mold to acute fracture presentations. Demand clusters in German trauma centers where statutory rehabilitation insurance mandates immediate stabilization prior to surgical referral.
- Supports:Soft textile constructions employing elastic tensioning and compression gradients. Fabric-based supports displace foam constructions in preventative care segments where breathability and washability drive replacement frequency.
- Casts:Traditional plaster and synthetic fiberglass enclosures for complete immobilization. Synthetic variants capture volume in Indian outpatient rehabilitation expansion where private hospital chains standardize fracture management protocols.
Braces lead on scale; supports lead on momentum.
End User:
Site-of-care economics reshape distribution models, with professional fitting services unbundling from device markup as direct-to-patient channels expand.
- Hospitals:Acute care settings requiring immediate trauma stabilization and post-surgical immobilization. German statutory rehabilitation insurance anchors demand through mandated coverage of functional recovery devices.
- Clinics:Outpatient orthopedic and sports medicine practices specializing in bracing protocols. Clinics in academic medical centers adopt 3D-printed ankle-foot orthoses with topology-optimized stiffness gradients.
- Rehabilitation Centers:Dedicated recovery facilities managing extended functional restoration. Ottobock's domestic manufacturing base supplies German rehabilitation infrastructure with premium carbon-fiber custom orthoses.
- Home Care:Self-application environments where simplified fitting protocols sustain volume leadership. Return rates climb when patients lack professional fitting support for rigid orthoses.
Home care leads on scale; rehabilitation centers lead on momentum.
Material:
Performance-to-weight ratios and petrochemical input volatility fragment supplier strategies between premium composite fabrication and commodity polymer scale manufacturing.
- Plastic:Thermoformable polymers including polyethylene and polypropylene for custom-molded shells. Petrochemical feedstock costs fluctuate with crude oil indices, compressing margins on commodity-grade supports manufactured at scale.
- Fabric:Breathable textile constructions employing knitted elastic, neoprene laminates, and moisture-wicking synthetics. Fabric-based supports represent the category expanding most quickly, displacing foam in athletic prophylaxis applications.
- Metal:Aluminum uprights and carbon-fiber composites for load-bearing orthoses. Advanced composite fabrication processes enable lighter structures that penetrate premium post-operative segments.
- Foam:Traditional polyurethane and EVA cushioning constructions. Foam retains presence in acute trauma splinting where cost minimization outweighs durability requirements.
Plastic leads on scale; fabric leads on momentum.
Application:
Reimbursement coding and clinical evidence requirements stratify the market between covered post-surgical devices and out-of-pocket preventative purchases.
- Post-Surgery:Immobilization and protected mobilization following orthopedic procedures. Braces fabricated from advanced composites capture disproportionate margin pools in post-surgical applications.
- Injury Recovery:Acute and subacute management of ligament, tendon, and fracture injuries. Dynamic bracing protocols integrate range-of-motion adjustable systems into accelerated rehabilitation timelines.
- Pain Management:Chronic musculoskeletal conditions requiring ongoing mechanical support. Compression systems command premium placement in orthopedic clinics managing osteoarthritis presentations.
- Preventative Care:Prophylactic bracing for athletic and occupational risk reduction. Breathable textile constructions displace foam supports where washability drives replacement frequency.
Post-surgery leads on scale; preventative care leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biomechanical engineering talent clusters anchor European orthopedic innovation, while US regulatory velocity and Asian manufacturing scale reshape competitive access patterns across distinct national healthcare frameworks.
United States
FDA's 510(k) clearance pathway accelerates commercialization timelines for Class II medical devices. Sports medicine clinics in metropolitan markets integrate dynamic bracing into return-to-play protocols. The Boston-Cambridge corridor concentrates academic medical centers adopting 3D-printed ankle-foot orthoses.
Germany
Statutory rehabilitation insurance mandates coverage of functional recovery devices. The EU Medical Device Regulation imposes extended clinical documentation requirements on textile-based systems. Ottobock's domestic manufacturing base in Duderstadt supplies rehabilitation infrastructure with premium carbon-fiber custom orthoses.
China
NMPA medical device classification governs market entry for thermoformable polymer supports. Private hospital chains in Shanghai and Beijing expand dedicated orthopedic recovery centers. The Yangtze River Delta concentrates contract manufacturers seeking ISO 13485 certification for export markets.
India
CDSCO medical device rules formalize registration pathways for imported braces and splints. Outpatient rehabilitation expansion in Maharashtra and Karnataka standardizes fracture management protocols. Mumbai's private hospital networks build dedicated orthopedic recovery centers with standardized bracing protocols.
Japan
PMDA's pharmaceutical and medical device agency oversees conformity assessment for load-bearing orthoses. METI's healthcare technology initiatives promote sensor-embedded compliance monitoring. The Kanto region around Tokyo concentrates aging-population demand for chronic pain management supports.
Orthopedic Support Systems Market Vendor Landscape
Top-tier vendors anchor the premium composite segment, while scale manufacturers dominate commodity-grade polymer supports. The vendor base stratifies across three tiers: German engineering heritage firms commanding carbon-fiber margins, US scale manufacturers capturing rehabilitation volume, and Asian contract fabricators supplying textile-based constructions. Competitive moves concentrate on M&A for technology access and geographic expansion into statutory reimbursement markets.
Within the premium-tier vector, Ottobock and Össur occupy positions exemplifying German and Nordic engineering archetypes. DJO LLC represents the scale-driven US rehabilitation product fabricator. Bauerfeind sits within the sports-medicine specialist tier. These three named entities anchor distinct competitive vectors without exhausting the market's structural complexity.
| Leading Market Players |
|---|
| Ottobock |
| Össur |
| DJO LLC |
| Breg Inc. |
| Bauerfeind |
| DeRoyal Industries |
| Zimmer Biomet |
| 3M |
| Stryker Corporation |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 10 technical documentation mandates gate qualified supply for textile-based braces while compressing premium-tier pricing access for Asian manufacturers unwilling to absorb clinical evaluation costs. German distributors report two in five suppliers have suspended EU market entry, tightening supply for compliant products and elevating pricing power for ISO 13485-certified domestic fabricators.
Pricing Analysis
The bundled-vs-unbundled service split separates professional fitting fees from device markup as telehealth-integrated platforms fragment durable medical equipment channels. Three-tier pricing structure across premium carbon-fiber custom orthoses, standard thermoformable polymer supports, and economy foam constructions reflects certification grade and vertical integration depth. Pricing pressure stems from petrochemical input volatility compressing margins on commodity-grade polymer supports manufactured at scale. Home care patients exhibit highest price sensitivity, while post-surgical segments anchored by statutory rehabilitation insurance demonstrate lowest sensitivity due to mandated coverage.
Supply Chain Analysis
Logistics and freight cost volatility from Asia-Europe routes is elevating landed costs for textile-based tensioning systems sourced from contract manufacturers. Supply concentrates in Germany for premium carbon-fiber composites, China for thermoformable polymer feedstocks, and Vietnam for breathable textile constructions. Raw material dependencies span crude oil derivatives for plastics, carbon fiber precursors from polyacrylonitrile, and knitted elastic synthetics. Single-source vulnerability concentrates in German biomechanical engineering talent clusters for torque calibration expertise. Distribution runs through hospital purchasing consortiums and direct-to-patient e-commerce portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 510(k) clearance velocity and EU MDR documentation burdens together accelerate demand for pre-certified supplier relationships. The statutory rehabilitation insurance frameworks in Germany and expanding outpatient rehabilitation infrastructure in India create dual demand anchors.
For Market Incumbents: Deploy backward integration into carbon-fiber composite fabrication to defend margin pools against Asian contract manufacturers. Acquire ISO 13485-certified textile suppliers to preempt MDR conformity bottlenecks. Lock hospital purchasing consortium relationships through exclusive GPO contracts before sensor-embedded compliance monitoring reshapes reimbursement coding.
For New Entrants and Emerging Players: Enter via direct-to-consumer fitting platforms targeting US suburban markets with video-guided sizing protocols for off-the-shelf knee braces. Target Indian outpatient rehabilitation expansion in Maharashtra and Karnataka where private hospital chains standardize bracing protocols without entrenched supplier relationships. Pursue white-label manufacturing for European distributors seeking compliant Asian supply alternatives.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ISO 13485-certified contract manufacturers because quality management system audits stretch 12-18 months, gating new competitor entry. Five-to-ten-year viability hinges on remote patient monitoring integration capabilities. Acquisition target archetype: textile-based support specialists with sensor-embedded R&D pipelines. Signal to watch: evolving reimbursement coding for compliance data transmission under durable medical equipment frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates commercialization timelines for Class II dynamic bracing systems in US metropolitan sports medicine markets. |
| CE Marking Pathway under MDR | Unlocks EU market access for textile-based compression systems previously cleared through self-certification. |
| Hospital System Partnership | Secures procurement relationships with German rehabilitation infrastructure anchored by statutory insurance mandates. |
| Software Companion Development | Enables sensor-embedded braces to transmit compliance data for evolving durable medical equipment reimbursement coding. |
| Reimbursement Strategy | Aligns product positioning with remote patient monitoring integrations reshaping orthopedic clinic expenditure justification. |
Methodological Framework
Multiple input streams — primary interviews with orthopedic clinicians and hospital purchasing committee members, secondary validation through FDA 510(k) filings and EU MDR technical documentation databases, and trade data on thermoformable polymer feedstock flows — were reconciled through bottom-up and top-down triangulation. Clinicians at academic medical centers adopting 3D-printed ankle-foot orthoses, biomedical engineers specifying torque calibration protocols, and GPO contracts managers at German rehabilitation centers provided qualitative demand assessments. Secondary sources encompassed hospital procurement databases, CMS durable medical equipment expenditure records, and customs data on carbon-fiber composite imports.
Data-stream reconciliation across product type, material category, end-user site of care, and application severity anchored the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed rigid versus soft apparatus, carbon-fiber versus polymer versus textile constructions, acute care versus home care environments, and post-surgical versus preventative applications. CAGRs were derived from installed base growth rates and replacement cycle frequencies. Forecast inputs included petrochemical price indices, ISO 13485 certification pipeline timelines, and statutory rehabilitation insurance coverage expansion trajectories.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in real-time compliance data from emerging Asian suppliers introduce uncertainty bands around EU market penetration assumptions. Forecasts reflect documented assumptions regarding MDR enforcement consistency and telehealth platform adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Hip Reconstruction Devices Market