
 Europe Refrigerated Transport Market | 2026-2036
Europe Refrigerated Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refrigerated Transport Market Intelligence
Driver shortages across Europe is bifurcating fleet modernization timelines, with larger operators accelerating automation while smaller hauliers delay replacement cycles. DHL Supply Chain leverages its pan-European network density to sustain multi-temperature route consolidation. NewCold Coöperatief U.A. anchors automated high-bay cold storage integration with captive transport fleets. STEF Group dominates temperature-controlled food distribution across France and Southern Europe through specialized dairy and protein logistics.
Refrigerated transport encompasses insulated vehicle bodies and active cooling systems designed to maintain cargo temperatures between minus 25 degrees Celsius and plus 15 degrees Celsius across distribution networks. The systems employ vapor-compression refrigeration units, phase-change materials, or cryogenic cooling to preserve perishable goods through controlled atmosphere management. Heavy-duty vehicles carry the bulk of intercity frozen freight volume, though light-duty vehicles are gaining share in last-mile pharmaceutical and meal-kit delivery. Smart temperature-control systems represent the fastest-expanding segment as real-time monitoring becomes mandatory for EU Good Distribution Practice compliance in pharmaceutical logistics.
The European Commission enforces F-Gas Regulation phasedowns through ECHA, while national transport authorities apply Euro VI emission standards that constrain diesel-powered refrigeration unit operations. EMA guidelines on medicinal product distribution mandate continuous temperature documentation, directly shaping fleet investment priorities for pharmaceutical-qualified vehicles. Stakeholders must weigh electrification timelines against cooling unit retrofit costs as zero-emission zones expand across Dutch, German, and Belgian urban centers.
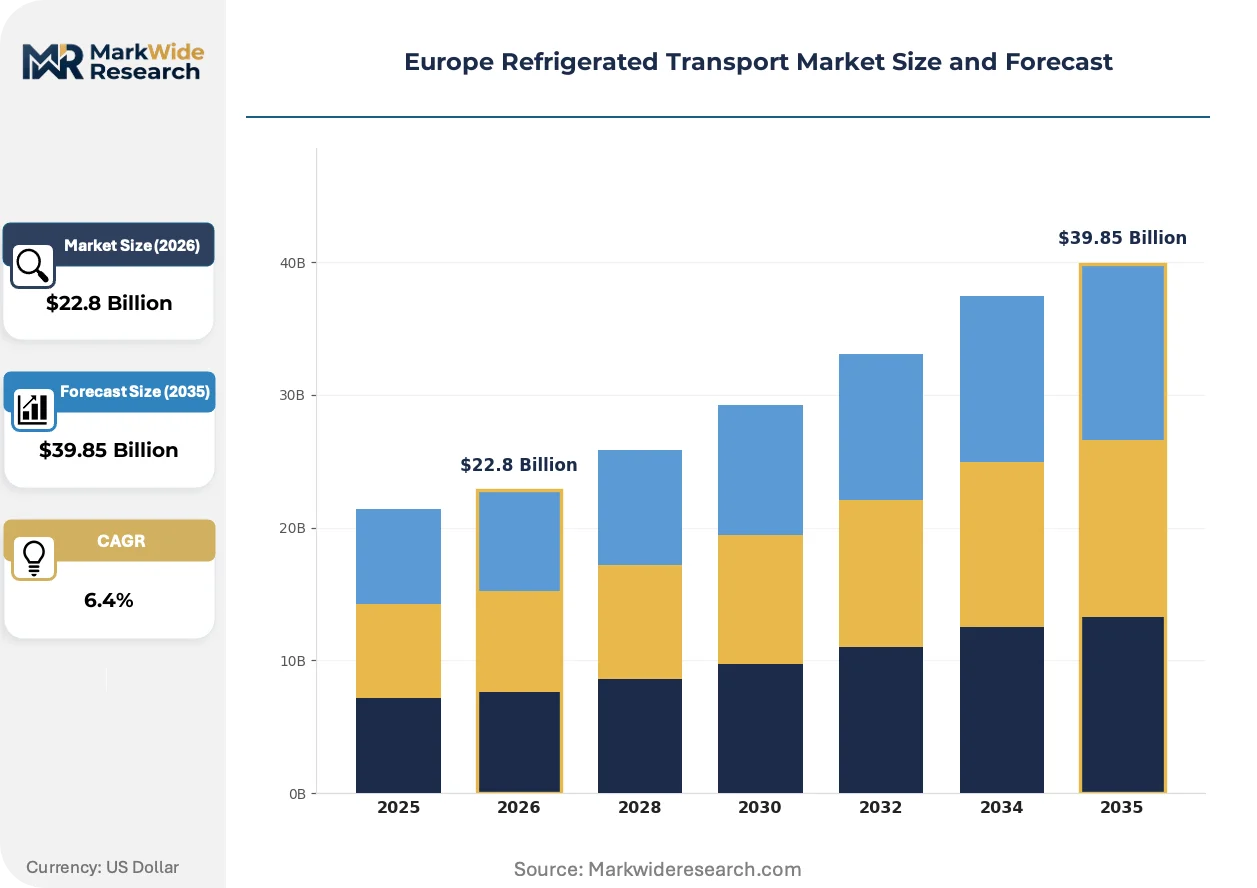
Market Dynamics
The EU F-Gas Regulation is compressing fleet replacement cycles as operators face simultaneous pressure to phase down hydrofluorocarbon refrigerants and electrify auxiliary power units before zero-emission zone mandates take effect in Dutch, German, and Belgian urban centers.
Growth Catalysts
- EMA Distribution Guidelines:Continuous temperature documentation mandates for medicinal products are forcing pharmaceutical-qualified vehicle investments across EU member states.
- Food Processing Cluster Density:Germany's concentrated meat, dairy, and prepared meal manufacturing bases generate sustained demand for multi-temperature distribution capacity.
- Phase-Change Materials:Cryogenic cooling systems are capturing share in last-mile pharmaceutical delivery where compressor noise and vibration compromise product integrity.
Market Restraints
- Refrigerant Input Volatility:Hydrofluorocarbon supply constraints under F-Gas phasedowns are elevating retrofit costs for existing vapor-compression fleets.
- Driver Availability Compression:Certified refrigeration operators are concentrating in Germany and France, leaving Southern and Eastern European hauliers exposed to wage inflation.
- Battery Energy Density Limits:Electric auxiliary power units cannot yet sustain minus 25 Celsius operations across full intercity routes without payload-compromising battery mass.
Strategic Opportunities
- Poland and Romania Cold Chain Gaps:Underpenetrated markets in Eastern Europe present first-mover advantages for temperature-controlled distribution infrastructure.
- EU Green Deal Fleet Incentives:Member state subsidies for zero-emission commercial vehicles are offsetting electrification capex for early-adopting operators.
- Real-Time Monitoring Convergence:Integration of IoT sensors with blockchain documentation is opening pharmaceutical compliance-as-a-service revenue streams.
Industry Challenges
- Multi-Certification Timelines:Vehicles must simultaneously achieve Euro VI, ATP agreement, and GDP compliance, extending procurement-to-deployment cycles.
- Retrofit Integration Complexity:Existing trailer fleets require structural reinforcement to accommodate cryogenic tankage without compromising insulation performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refrigerated Transport Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Trucks, Refrigerated Vans, Refrigerated Trailers, Refrigerated Containers Vehicle Type: Light-duty Vehicles, Heavy-duty Vehicles, Medium-duty Vehicles, Specialized Vehicles Temperature Control: Active Cooling, Passive Cooling, Hybrid Cooling, Smart Temperature-Control Systems End User: Food & Beverage, Pharmaceuticals, Chemicals, Others |
| Companies Covered | DHL Supply Chain, NewCold Coöperatief U.A., Lineage Logistics, Constellation Cold Logistics Sarl, Americold Logistics, STEF Group, Girteka Logistics, DB Schenker, DFDS Logistics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refrigerated Transport Market Strategic Shifts & Innovations
Active cooling architecture is fragmenting as electrification mandates and pharmaceutical compliance requirements force parallel technology tracks. Fleet operators now confront simultaneous decisions on refrigerant chemistry, powertrain configuration, and monitoring system integration.
Cryogenic nitrogen cooling is decomposing the traditional vapor-compression monopoly in pharmaceutical last-mile operations. Specialist vaccine distributors in the Netherlands and Belgium are adopting liquid nitrogen evaporator systems to eliminate compressor vibration during transport. This technology is decomposing the historical trade-off between temperature stability and vehicle acquisition cost, enabling smaller hauliers to access pharmaceutical-grade capability without premium chassis investments.
The F-Gas Regulation's phasedown schedule is compressing refrigerant choice architecture for fleet operators. ECHA enforcement mechanisms now require documented refrigerant leakage rates below 3% annually for vehicles above 3.5 tonnes. German and French transport authorities are aligning national inspection protocols with these thresholds, accelerating adoption of CO2 transcritical systems in heavy-duty frozen freight segments.
Pharmaceutical buyers are consolidating vendor relationships around integrated cold-chain service providers. Large molecule biologics manufacturers in Switzerland and Denmark now specify continuous custody documentation from manufacturing site through patient delivery, displacing spot-market transport procurement. This concentration is most visible in Northern European oncology logistics networks, where single-source accountability has become a tender prerequisite.
Europe Refrigerated Transport Market Segmentation
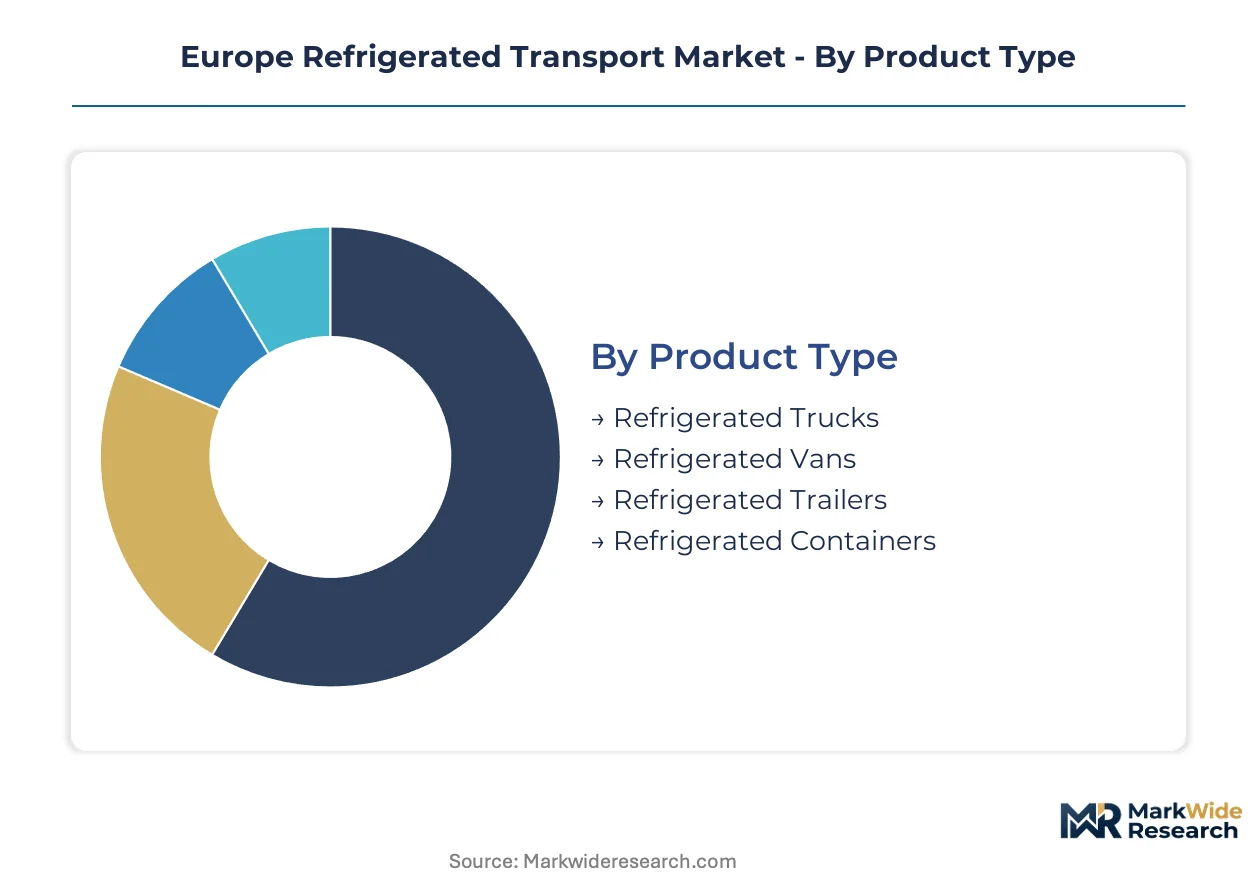
Refrigerated transport equipment selection cascades through distribution network design, with chassis configuration determining route economics and cooling architecture dictating regulatory compliance pathways. Fleet operators sequence procurement decisions across product type, vehicle class, and temperature control method to match cargo profiles against EU F-Gas and Euro VI constraints.
Product Type:
Channel distribution varies sharply by product category, with refrigerated trailers flowing through leasing networks while vans concentrate in direct manufacturer sales to foodservice operators.
- Refrigerated Trucks:Single-unit chassis with integrated insulated cargo bodies and roof-mounted refrigeration units serve medium-distance distribution from processing plants to regional distribution centers. German meat and dairy processors deploy these for daily multi-drop routes under ATP agreement compliance.
- Refrigerated Vans:Light commercial vehicles with compact cooling systems enable urban last-mile delivery where zero-emission zones constrain diesel auxiliary units. Dutch pharmaceutical couriers and Belgian meal-kit operators are electrifying these fleets fastest.
- Refrigerated Trailers:Detachable insulated semi-trailers with independent refrigeration power intercity frozen freight corridors. These dominate cross-border volume between Poland and Germany.
- Refrigerated Containers:ISO-standard intermodal units with clip-on gensets bridge maritime and rail legs of pharmaceutical import supply chains into Rotterdam and Hamburg.
Refrigerated trailers dominate installed base. Refrigerated vans are where expansion concentrates.
Vehicle Type:
Cost tier stratification separates premium chassis specifications for pharmaceutical GDP compliance from standard configurations for commodity food distribution.
- Light-duty Vehicles:Vehicles under 3.5 tonnes GVW with compact vapor-compression or cryogenic cooling serve pharmacy delivery and premium foodservice. ECHA leakage thresholds below 3% annually apply here, accelerating CO2 system adoption in Netherlands and Belgium.
- Heavy-duty Vehicles:Articulated tractors and rigid trucks above 12 tonnes GVW carry frozen freight volumes across Germany's dense food processing clusters. These face the steepest retrofit pressure under F-Gas phasedowns.
- Medium-duty Vehicles:Rigid trucks between 3.5 and 12 tonnes bridge urban distribution and regional haulage for prepared meal manufacturers.
- Specialized Vehicles:Custom chassis with multi-compartment temperature zones serve high-value biologics requiring simultaneous frozen and controlled ambient storage.
Heavy-duty vehicles anchor fleet investment. Light-duty vehicles are climbing the fastest.
Temperature Control:
Application requirements fragment technology selection, with pharmaceutical custody demanding continuous monitoring while frozen food tolerates simpler vapor-compression cycles.
- Active Cooling:Vapor-compression or cryogenic systems with powered refrigeration cycles maintain precise temperature setpoints across minus 25 to plus 15 Celsius range. These remain mandatory for EMA GDP compliance in oncology logistics.
- Passive Cooling:Insulated containers with phase-change materials or dry ice suit short-duration pharmaceutical samples and vaccine outreach programs in Eastern Europe.
- Hybrid Cooling:Systems combining electric compressor operation with cryogenic backup address zero-emission zone mandates while preserving range capability.
- Smart Temperature-Control Systems:IoT-enabled units with real-time monitoring, automated alerts, and blockchain documentation integration are gaining share fastest in Swiss and Danish biologics distribution.
Active cooling commands installed base. Smart temperature-control systems are gaining share fastest.
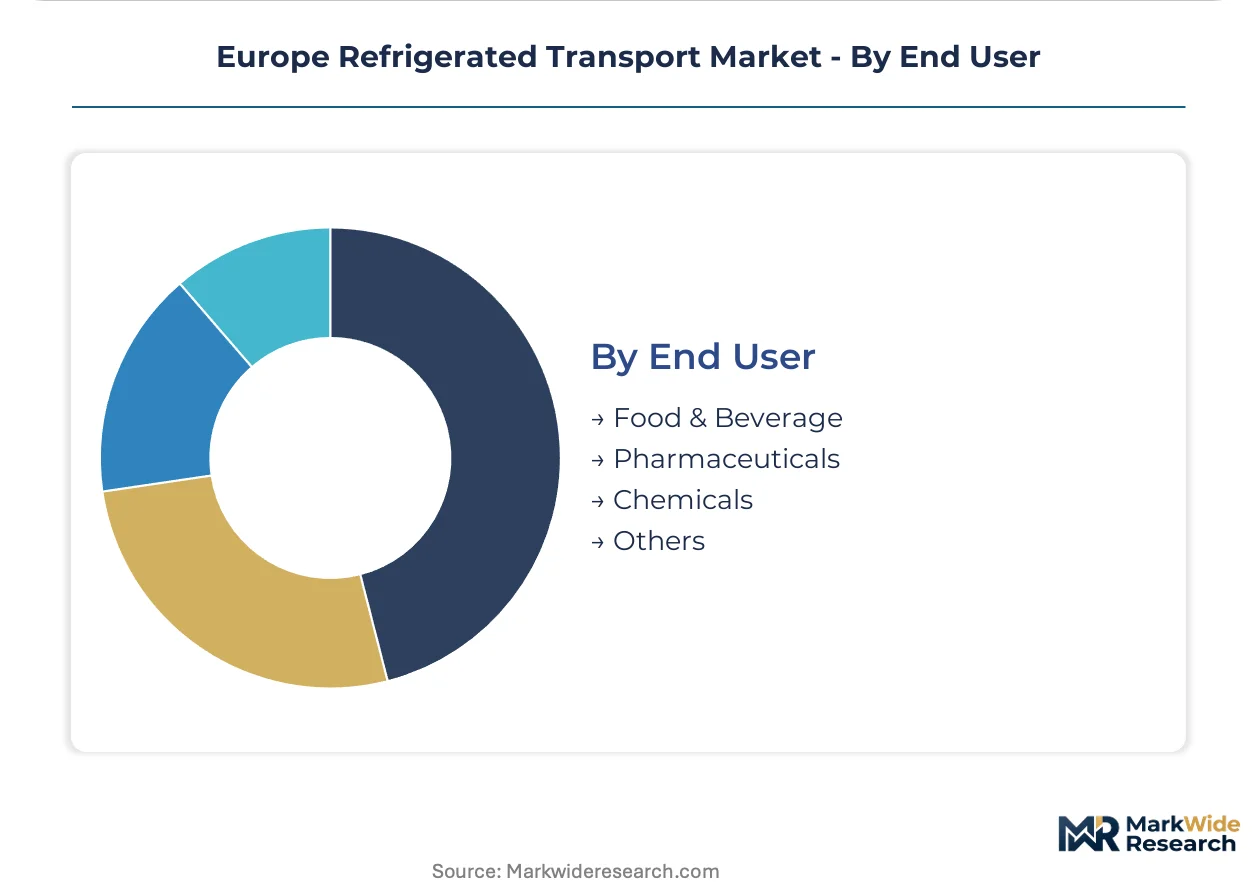
End User:
Customer type determines service level specifications, with pharmaceutical buyers consolidating around integrated providers while food processors fragment procurement across spot markets.
- Food & Beverage:Meat, dairy, prepared meals, and fresh produce generate the bulk of fleet demand across Germany, France, and Italy. Multi-temperature capability separates premium operators from commodity hauliers.
- Pharmaceuticals:Vaccines, insulin, biologics, and clinical trial materials require GDP-validated vehicles with continuous documentation. Northern European oncology networks now mandate single-source accountability.
- Chemicals:Temperature-sensitive industrial precursors and reagents demand ATP-certified transport with hazard classification compliance.
- Others:Floral products, precision agriculture inputs, and aerospace components occupy niche specification tiers.
Food and beverage anchors volume. Pharmaceuticals is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA enforcement of F-Gas Regulation phasedowns is compressing fleet replacement timelines across Germany's dense food processing corridors, while national transport authorities in France and the Netherlands accelerate zero-emission zone mandates that reshape urban delivery economics.
Germany
Meat and dairy processing clusters in Lower Saxony and Bavaria generate sustained demand for heavy-duty frozen freight capacity. KBA inspection protocols now align with ECHA leakage thresholds below 3% annually, forcing CO2 transcritical system adoption. The Frankfurt-Rhine-Main corridor anchors pharmaceutical GDP-compliant distribution networks for oncology logistics.
France
Specialized dairy and protein logistics dominate temperature-controlled distribution across the Île-de-France and Auvergne-Rhône-Alpes regions. ANSM guidelines on medicinal product distribution mandate continuous temperature documentation, elevating compliance costs for regional hauliers. Lyon-based biologics manufacturers are consolidating vendor relationships around single-source accountability providers.
Netherlands
Rotterdam's maritime import gateways drive refrigerated container demand for pharmaceutical supply chains originating in Asia. Dutch zero-emission zone mandates in Amsterdam and Utrecht are accelerating electric auxiliary power unit deployment in light-duty van fleets. Specialist vaccine distributors adopt cryogenic nitrogen cooling to eliminate compressor vibration during last-mile delivery.
Poland
Cross-border frozen freight volume between Poland and Germany is expanding as Western European processors source from Eastern European agricultural suppliers. Underpenetrated cold chain infrastructure in Warsaw and Krakow metropolitan areas presents first-mover advantages for temperature-controlled distribution investment. Polish hauliers face certification gaps against ATP agreement and GDP compliance standards.
Belgium
Brussels' pharmaceutical manufacturing density generates premium demand for multi-compartment vehicles serving biologics with simultaneous frozen and controlled ambient requirements. Belgian transport authorities align national inspection protocols with ECHA F-Gas enforcement, compressing refrigerant choice architecture for fleet operators. Antwerp's port logistics cluster integrates refrigerated container handling with captive rail connections to German industrial centers.
Europe Refrigerated Transport Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with pan-European network density separating premium operators from regional hauliers. Consolidation pressure is intensifying as simultaneous F-Gas retrofit costs and electrification capex strain mid-scale fleet balance sheets. Three archetypes dominate: integrated cold-chain service providers, automated high-bay cold storage operators with captive transport fleets, and specialized temperature-controlled food distributors. Competitive moves center on multi-temperature route consolidation and automated warehouse integration with transport assets.
Among integrated logistics providers, DHL Supply Chain and DB Schenker occupy positions defined by pan-European network scale, while STEF Group exemplifies the specialized food distribution archetype through concentrated dairy and protein logistics across France and Southern Europe. NewCold Coöperatief U.A. anchors the automated storage integration tier, representing the convergence of high-bay cold storage with captive fleet deployment.
| Leading Market Players |
|---|
| DHL Supply Chain |
| NewCold Coöperatief U.A. |
| Lineage Logistics |
| Constellation Cold Logistics Sarl |
| Americold Logistics |
| STEF Group |
| Girteka Logistics |
| DB Schenker |
| DFDS Logistics |
| Others |
Cost & Logistics Intelligence
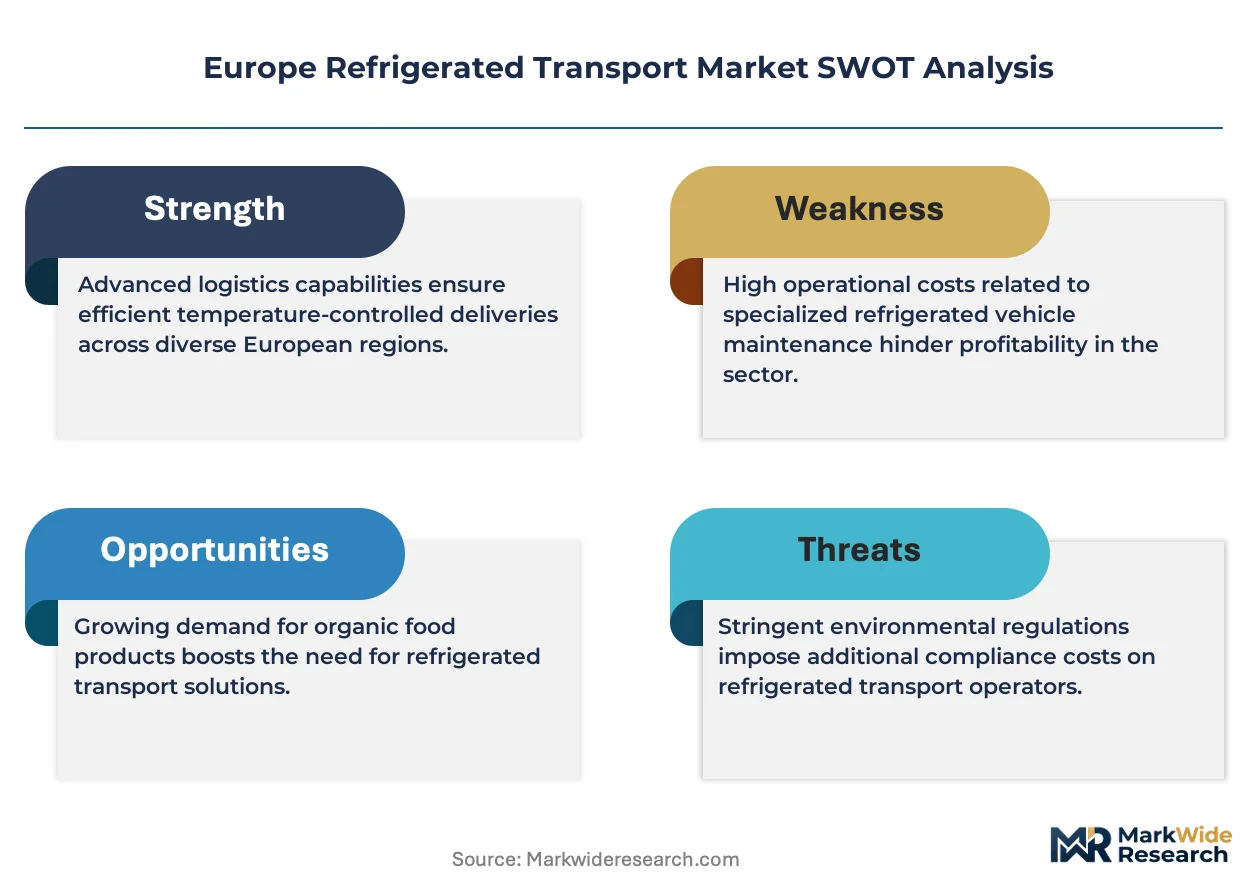
CO2 transcritical refrigeration systems displacing hydrofluorocarbon vapor-compression units are redrawing supply geography toward German and Dutch manufacturing clusters while compressing pricing economics for fleet operators facing simultaneous F-Gas retrofit deadlines and electrification mandates.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical GDP-compliant fleet procurement, with Swiss and Danish biologics manufacturers locking multi-year capacity agreements that embed temperature-documentation service bundles. Three-tier pricing structure across premium GDP-validated, standard ATP-certified, and economy commodity food tiers separates compliance-grade vehicles from basic insulated configurations. Cost compression in the economy tier is intensifying because Polish and Romanian hauliers are absorbing spot-market volatility to secure cross-border volume. Pharmaceutical buyers exhibit the lowest price sensitivity, while prepared meal distributors in Italy and Spain face margin pressure from diesel auxiliary unit operating bans.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound logistics costs for refrigerated container gensets and cryogenic nitrogen tankage flowing from Asian manufacturing hubs. Component supply concentrates in Germany, the Netherlands, and Italy, with vapor-compression compressors drawing from German automotive supplier networks and insulation panel production anchored in Italian industrial zones. Single-source vulnerability in cryogenic cooling system electronics creates exposure to semiconductor allocation constraints. Distribution runs through captive fleet operators integrated with automated high-bay cold storage, displacing traditional trailer leasing networks in Northern European pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated transport is shifting toward service-attach revenue models, with real-time temperature monitoring and blockchain documentation subscriptions expanding faster than chassis hardware sales as EMA GDP compliance mandates deepen recurring service dependencies.
For Market Incumbents: Consolidate around multi-temperature route density in Germany's food processing corridors and pharmaceutical distribution networks, acquiring mid-scale Polish and Romanian operators before ATP certification requirements harden competitive barriers. Backward integration into cryogenic cooling system maintenance capabilities defends margin position against specialist technology entrants. For New Entrants and Emerging Players: Lead with cryogenic nitrogen cooling solutions for Belgian and Dutch vaccine last-mile delivery, where compressor vibration sensitivity creates white-space opportunity outside incumbent vapor-compression supply relationships. Target underpenetrated Eastern European cold chain infrastructure with GDP compliance-as-a-service offerings that bundle vehicle provision with continuous documentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automated cold storage operators seeking transport fleet integration to complete vertical customer capture. Five-to-ten year viability hinges on electrification capex execution and F-Gas regulatory alignment. Monitor Dutch zero-emission zone enforcement velocity as inflection indicator for electric auxiliary power unit adoption timing.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical System Deployment | Aligns heavy-duty frozen freight fleets with ECHA leakage thresholds below 3% annually. |
| Pharmaceutical GDP Certification Investment | Unlocks long-term offtake contracts with Swiss and Danish biologics manufacturers. |
| Cryogenic Cooling Technology Licensing | Enables smaller hauliers to access pharmaceutical-grade capability without premium chassis. |
| Automated Warehouse Integration | Captures route consolidation efficiencies through captive fleet deployment with high-bay cold storage. |
| Real-Time Monitoring Platform Launch | Generates recurring compliance-as-a-service revenue from EMA continuous documentation mandates. |
Research Approach
Cross-validation between fleet operator procurement data and regulatory filing documentation anchors the qualitative findings, combining primary interviews with cold chain logistics directors, pharmaceutical distribution managers, and aftermarket service heads with secondary validation through ECHA enforcement records, ATP agreement certification databases, and Euro VI emission compliance filings. Bottom-up vehicle deployment counts triangulate against top-down market sizing from national transport authority registrations.
Sensitivity analysis across refrigerant chemistry adoption curves, zero-emission zone expansion timelines, and pharmaceutical custody documentation penetration informs the analytical framework over the projection horizon. Segmentation dimensions include product type, vehicle class, temperature control method, and end-use industry, with CAGRs derived from fleet replacement cycle modeling against regulatory deadline compression. Cryogenic cooling system cost curves and battery energy density improvement trajectories constitute key forecast inputs.
Forecasts assume regulatory continuity in ECHA F-Gas phasedowns and Dutch-German-Belgian zero-emission zone regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Europe Road Freight Transport Market