
 Global Shipbuilding Anti-Vibration Market | 2026-2036
Global Shipbuilding Anti-Vibration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shipbuilding Anti-Vibration Market Outlook
Multi-source procurement of elastomeric isolators is decoupling from the single-vendor legacy model that dominated naval programs. Trelleborg leverages its polymer compounding expertise to anchor European naval contracts. Parker LORD competes through active control integration for offshore platform projects. Hutchinson Paulstra specializes in tuned mass damper assemblies for luxury yacht builders seeking IMO compliance.
Shipbuilding anti-vibration encompasses engineered mounts, bushings, and damping systems manufactured from rubber-metal bonded assemblies, elastomeric composites, and tuned inertial devices designed to attenuate structural-borne and airborne vibration across propulsion, auxiliary, and hull systems. These components typically operate across temperature ranges from minus 40 to plus 100 degrees Celsius while maintaining isolation efficiencies above 80 percent in critical naval machinery installations. Rubber-based passive control solutions occupy the largest material-technology intersection due to proven durability in saltwater environments and lower installed cost relative to hybrid active-passive architectures. Composite tuned mass dampers represent the fastest-expanding segment as shipyards adopt lighter weight solutions for superyacht and high-speed ferry applications where center-of-gravity constraints limit conventional steel counterweights. Naval vessels command the deepest margin pools among application categories because of certification rigor, long program lifecycles, and restricted vendor qualification lists.
The International Maritime Organization's revised guidelines on underwater radiated noise, enforced through classification societies such as Lloyd's Register and DNV, are mandating stepped isolation performance for newbuild vessels above 400 gross tons. The EU Green Deal's extension to maritime transport via FuelEU Maritime is indirectly amplifying anti-vibration demand as dual-fuel engine installations introduce new torsional and combustion excitation signatures. Stakeholders must monitor classification society rule harmonization between IMO, ISO 6954 comfort criteria, and national naval specifications to anticipate qualification barriers that could reshape vendor competitiveness.
Market Dynamics
Dual-fuel engine retrofits across commercial fleets are forcing simultaneous redesign of isolation systems to address torsional excitation signatures that differ fundamentally from conventional diesel combustion profiles.
Growth Catalysts
- FuelEU Maritime:The EU's maritime decarbonization framework mandates alternative fuel adoption, requiring new isolation architectures for methanol and ammonia propulsion systems.
- Underwater radiated noise protocols:Classification society rules from Lloyd's Register and DNV are tightening isolation performance thresholds for vessels above 400 gross tons.
- Composite material advances:Carbon fiber tuned mass dampers are displacing steel counterweights in South Korean superyacht construction to meet center-of-gravity constraints.
Market Restraints
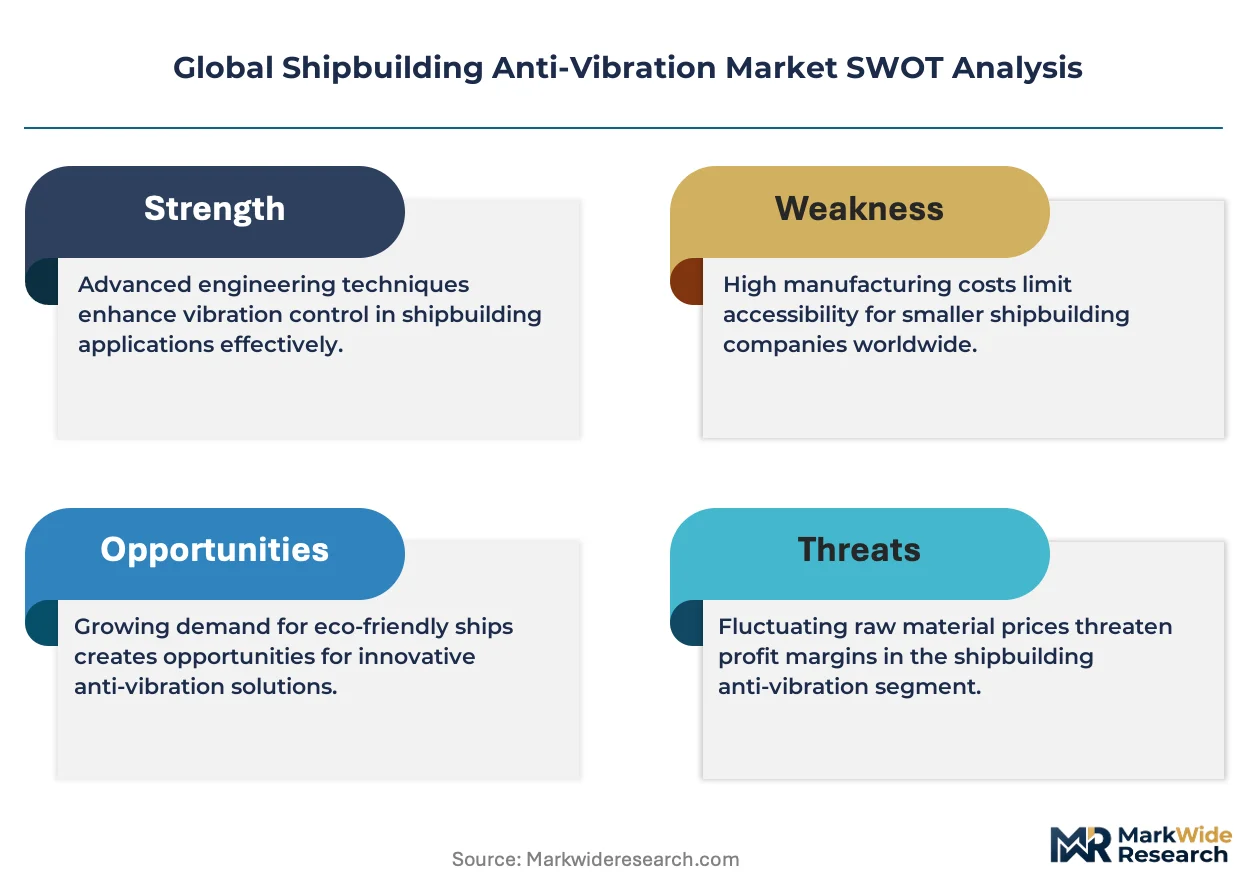
- Natural rubber price volatility:Elastomeric isolators depend on latex supply concentrated in Southeast Asian plantations exposed to climate disruption.
- Naval vendor list concentration:Restricted qualification regimes in defense procurement limit supplier entry to a handful of pre-certified polymer compounders.
- Active-passive hybrid cost barriers:Piezoelectric damping systems remain prohibitively expensive for commercial vessel retrofit budgets.
Strategic Opportunities
- Indian shipyard expansion:Cochin Shipyard and Mazagon Dock are modernizing facilities under the PLI scheme, creating first-mover openings for isolator suppliers.
- Autonomous vessel architectures:Unmanned surface vessels require vibration-hardened sensor suites, opening new specification channels.
- ISO 6954 comfort convergence:Harmonization between naval and commercial comfort criteria is enabling cross-certification efficiencies.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for saltwater-durable elastomers concentrates among retiring specialists at European compounders.
- Classification society divergence:Inconsistent test protocols between Lloyd's Register, DNV, and Bureau Veritas extend qualification timelines.
- Legacy steel damper integration:Retrofit projects face structural modification costs when replacing conventional tuned mass systems with composite alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shipbuilding Anti-Vibration Market |
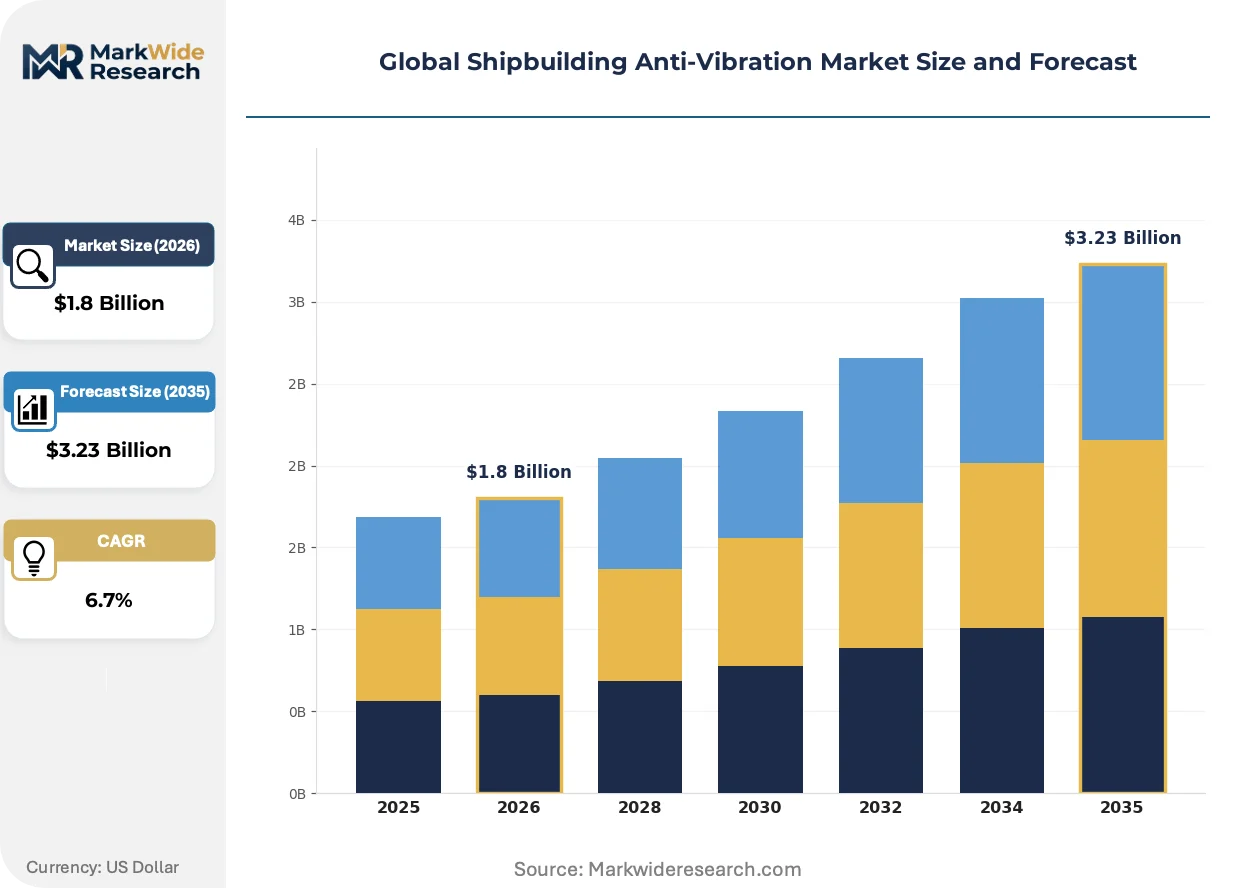
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, Metal, Composite, Foam Application: Naval Vessels, Commercial Ships, Offshore Platforms, Luxury Yachts End User: Shipbuilders, Repair Yards, OEMs, Government Agencies Technology: Passive Control, Active Control, Hybrid Systems, Tuned Mass Dampers |
| Companies Covered | Trelleborg, Parker LORD, Hutchinson Paulstra, GMT Rubber-Metal-Technic Ltd., Continental, Bridgestone Corporation, Sumitomo Riko Company Limited, ITT Inc., Fabreeka International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shipbuilding Anti-Vibration Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while elevating performance verification standards across naval and commercial segments.
Magnetorheological elastomers are rewriting isolation system responsiveness by enabling real-time stiffness modulation through magnetic field adjustment. Offshore platform operators in the North Sea are piloting these materials for variable-load machinery mounting. The technology is compressing the performance gap between passive rubber mounts and fully active control systems at intermediate cost points.
REACH substance restrictions on certain plasticizers are forcing reformulation of marine-grade elastomer compounds. European compounders are accelerating bio-based alternative development to maintain certification continuity. Naval programs in France and Germany are responding through accelerated qualification waivers for interim formulations.
Long-term service agreements are displacing component-only transactions as shipyards seek to outsource vibration performance risk. Classification society-certified performance guarantees now anchor contract structures for cruise line newbuilds. This pattern concentrates most visibly in German and Italian luxury yacht construction where IMO comfort ratings determine charter premiums.
Global Shipbuilding Anti-Vibration Market Segmentation
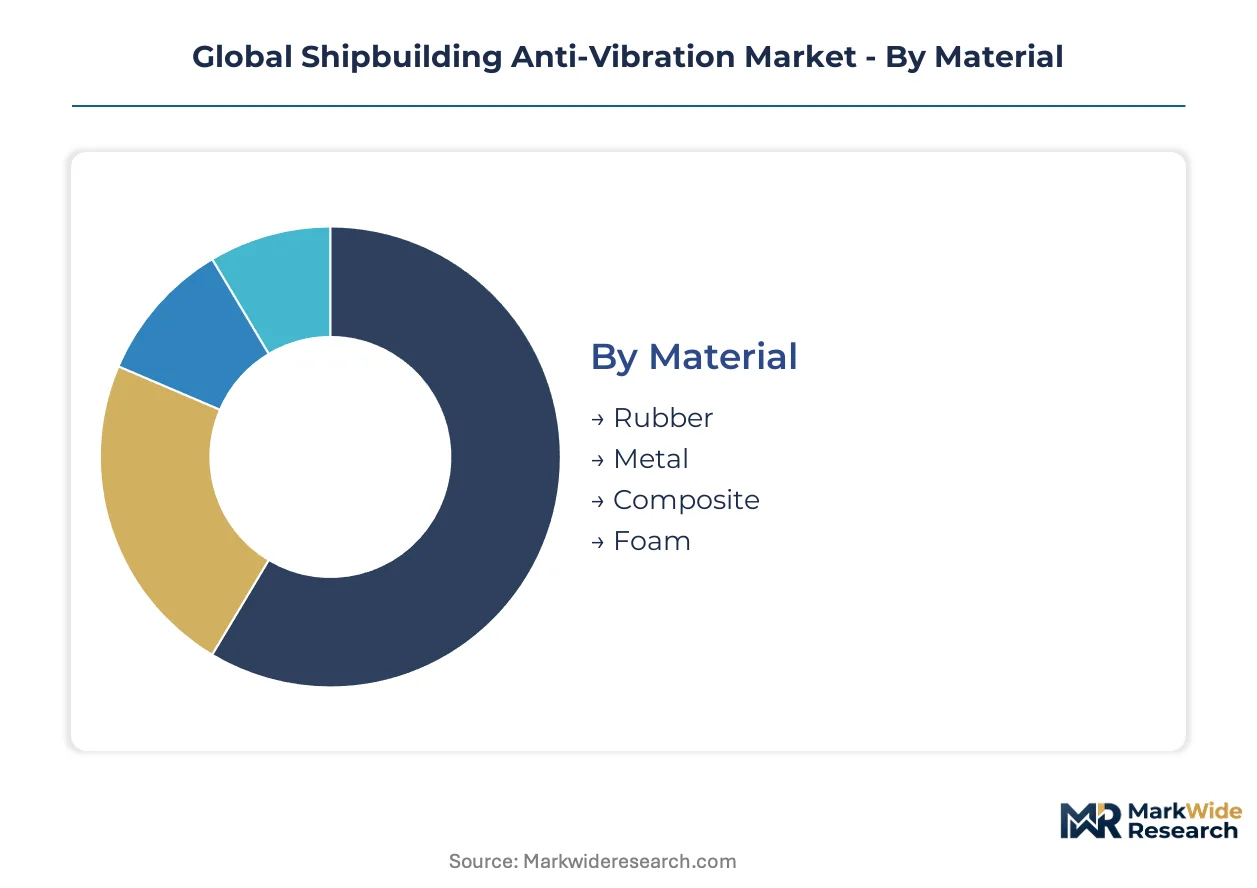
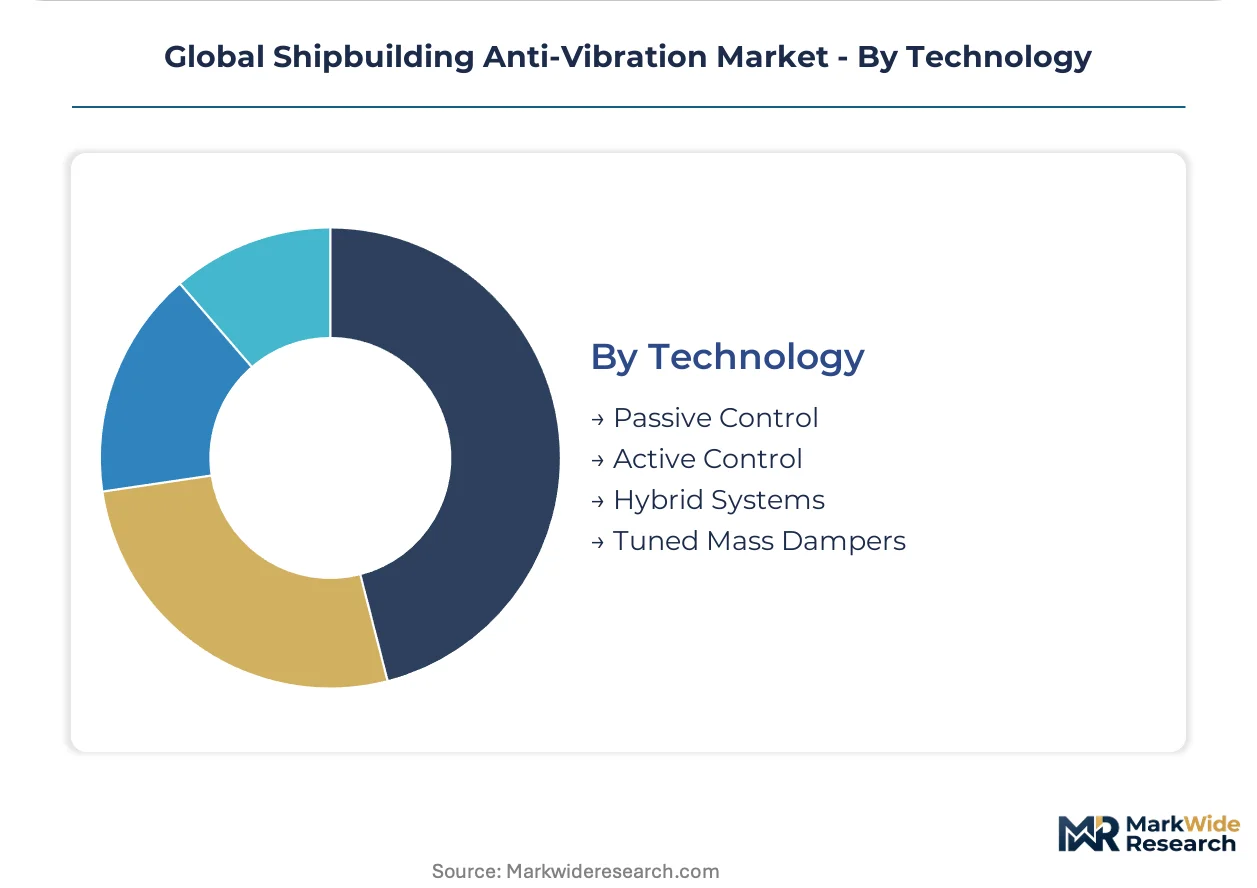
Segmentation in shipbuilding anti-vibration reveals how material selection and application requirements split procurement budgets across radically different performance tiers. Buyers prioritize saltwater durability in naval programs, weight reduction in superyachts, and retrofit compatibility in commercial fleets.
Material:
Cost tier drives material selection, with installed price per kilogram of isolation capacity varying by an order of magnitude across options.
- Rubber:Sulfur-vulcanized natural and synthetic elastomers dominate naval machinery mounts due to proven fatigue life exceeding 10 million cycles. South Korean shipyards specify nitrile-butadiene compounds for diesel engine installations under Lloyd's Register certification.
- Composite:Carbon fiber-reinforced polymer tuned mass dampers displace steel in German and Italian superyacht construction where center-of-gravity limits constrain conventional counterweights. IMO comfort ratings for charter vessels accelerate specification shifts.
- Metal:Steel and aluminum alloy isolators serve heavy propulsion systems in commercial bulk carriers where capital cost sensitivity outweighs weight penalties.
- Foam:Polyurethane acoustic foams address airborne noise in crew accommodation spaces aboard cruise ships operating under ISO 6954 comfort protocols.
Volume sits with rubber; growth tilts toward composite.
Application:
Application segmentation maps directly to margin structure, with certification rigor and program duration determining supplier profitability.
- Naval Vessels:Steel-hulled warships require MIL-SPEC elastomeric mounts operating across minus 40 to plus 100 degrees Celsius. French and German defense procurement offices maintain restricted vendor lists limiting competition to pre-qualified compounders.
- Commercial Ships:Container vessels and bulk carriers retrofit isolation systems during dual-fuel engine conversions. Classification society rules from DNV and Bureau Veritas mandate stepped performance for vessels above 400 gross tons.
- Offshore Platforms:North Sea oil and gas installations pilot magnetorheological elastomers for variable-load machinery mounting under Norwegian maritime authority oversight.
- Luxury Yachts:Superyacht builders in South Korea specify carbon fiber tuned mass dampers to meet underwater radiated noise protocols without compromising stability.
Naval programs capture the deepest margins; commercial retrofits expand the fastest.
End User:
Customer type determines contract structure, with risk allocation shifting between component sales and performance guarantees.
- Shipbuilders:Hyundai Heavy Industries and DSME in South Korea procure elastomeric isolators through multi-source agreements decoupled from single-vendor legacy models.
- Repair Yards:European retrofit specialists face structural modification costs when replacing steel dampers with composite alternatives in aging vessel fleets.
- OEMs:Engine manufacturers integrate isolation systems at assembly, specifying rubber-metal bonded mounts for methanol and ammonia propulsion architectures.
- Government Agencies:Naval procurement offices in France and Germany accelerate qualification waivers for REACH-compliant elastomer formulations.
Shipbuilders command procurement volume; repair yards drive specification churn.
Technology:
Technology maturity separates installed base from emerging specification channels.
- Passive Control:Rubber and elastomeric mounts occupy the largest installed base due to lower capital cost and zero power requirements. Saltwater durability concentrates demand with Southeast Asian latex supply chains.
- Tuned Mass Dampers:Inertial devices attenuate structural resonance in high-speed ferries and superyachts. Carbon fiber variants displace steel in East Asian newbuild yards.
- Active Control:Piezoelectric damping systems remain prohibitively expensive for commercial vessel retrofits despite superior performance in naval applications.
- Hybrid Systems:Magnetorheological elastomers enable real-time stiffness modulation, compressing the performance gap between passive mounts and active control at intermediate price points.
Passive control anchors installed volume; tuned mass dampers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian latex plantations anchor elastomer supply chains for naval and commercial isolator production. South Korean shipyards concentrate composite tuned mass damper demand as IMO underwater noise protocols tighten. European compounders face REACH-driven reformulation cycles while Indian yards modernize under production-linked incentives.
South Korea
Hyundai Heavy Industries and DSME drive elastomeric isolation procurement for naval and commercial newbuilds. Lloyd's Register certification requirements mandate stepped performance thresholds for vessels above 400 gross tons. The Busan-Ulsan industrial corridor hosts superyacht builders specifying carbon fiber dampers to meet center-of-gravity constraints.
Germany
Luxury yacht construction in German yards demands IMO-compliant vibration isolation for charter premium ratings. The EU Green Deal's FuelEU Maritime framework accelerates dual-fuel engine retrofits requiring redesigned isolation architectures. Bavaria and Lower Saxony host compounders developing bio-based elastomer alternatives under REACH substance restrictions.
China
MIIT standards on maritime equipment localization concentrate procurement with domestic rubber-metal bonded mount suppliers. Dual carbon goals pressure shipyards to adopt lighter composite damping solutions for fuel efficiency. The Yangtze River Delta shipbuilding cluster retrofits aging bulk carriers with classification society-certified isolation systems.
India
Cochin Shipyard and Mazagon Dock modernization under the PLI scheme creates first-mover openings for isolator suppliers. BIS certification alignment with ISO 6954 comfort criteria enables cross-certification efficiencies for export vessels. Gujarat and Tamil Nadu maritime clusters attract elastomer compounders seeking proximity to repair yard networks.
United States
Naval procurement offices maintain MIL-SPEC qualification regimes limiting vendor pools to pre-certified polymer compounders. EPA and OSHA oversight intersects with shipyard safety standards for vibration exposure in machinery spaces. The Gulf Coast repair yard corridor handles commercial fleet retrofits for dual-fuel engine isolation redesigns.
Global Shipbuilding Anti-Vibration Market Competitive Environment
Global majors compete with regional champions across certification depth and material specialization. The vendor base organizes around three tiers: European naval specialists with restricted qualification lists, Asian scale producers serving commercial newbuilds, and composite technology innovators targeting superyacht weight constraints. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships for classification society co-certification.
Within the European naval specialist tier, Trelleborg anchors polymer compounding expertise for restricted vendor list contracts. Parker LORD occupies a position bridging active control integration for offshore applications. Hutchinson Paulstra exemplifies tuned mass damper specialization for luxury yacht IMO compliance. These three represent distinct archetypes: compounder-integrated, control-technology hybrid, and application-specific assembly.
| Leading Market Players |
|---|
| Trelleborg |
| Parker LORD |
| Hutchinson Paulstra |
| GMT Rubber-Metal-Technic Ltd. |
| Continental |
| Bridgestone Corporation |
| Sumitomo Riko Company Limited |
| ITT Inc. |
| Fabreeka International |
| Others |
Value Chain & Pricing Dynamics
Natural rubber futures pricing on the Tokyo Commodity Exchange cascades through Southeast Asian latex supply chains into three distinct procurement tiers for shipbuilding anti-vibration components. Naval programs absorb premium-grade elastomer compounds through long-term offtake agreements, while commercial retrofit yards face spot-market volatility for standard rubber-metal bonded mounts.
Pricing Analysis
Warranty bundling separates naval contracts—where 15-year performance guarantees anchor pricing—from commercial retrofits sold component-only without service coverage. Three-tier pricing structure across MIL-SPEC certified, Lloyd's Register-compliant, and uncertified economy levels reflects certification depth as the primary price differentiation driver. Cost compression in the commercial tier is intensifying because South Korean shipyards are consolidating procurement volumes under multi-source agreements. Repair yards in India exhibit the highest price sensitivity due to structural modification costs for composite damper retrofits, while European superyacht builders prioritize weight-performance ratios over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam handle hub-and-spoke patterns for elastomeric isolator fulfillment to shipyards across South Korea, Germany, and China. Raw material sourcing draws from Thai and Indonesian latex plantations, German carbon fiber weavers, and Chinese steel forging operations. Single-source vulnerability concentrates in naval-grade nitrile-butadiene compounders where restricted vendor lists limit supplier pools. Distribution runs through classification society-certified logistics channels for IMO-compliant components, with direct mill-to-yard delivery for bulk naval contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shipbuilding anti-vibration sector sits in a material-transition phase as carbon fiber tuned mass dampers displace steel counterweights in superyacht and high-speed ferry applications. Magnetorheological elastomers are compressing the performance gap between passive mounts and active control systems.
For Market Incumbents: Anchor polymer compounding expertise through backward integration into Thai latex processing to secure raw material cost stability against climate-driven supply disruption. Deepen certification investment with Lloyd's Register and DNV for dual-fuel engine isolation architectures before REACH substance restrictions force compound reformulation. Lock in long-term service agreements with South Korean naval shipbuilders to outsource vibration performance risk and capture recurring revenue streams. For New Entrants and Emerging Players: Launch via repair yard partnerships in India's Gujarat and Tamil Nadu maritime clusters, where PLI scheme modernization is creating first-mover openings without restricted vendor list barriers. Target autonomous vessel architectures requiring vibration-hardened sensor suites, a specification channel absent entrenched competition. Pursue carbon fiber tuned mass damper supply to German and Italian superyacht builders seeking IMO comfort ratings for charter premium positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap elastomer compounders with active naval qualifications in France and Germany, where retiring polymer chemist expertise concentrates acquisition value. Long-term viability hinges on dual-fuel engine retrofit volumes across commercial fleets over a 5-10 year decarbonization window. Monitor classification society rule harmonization between IMO underwater noise protocols and ISO 6954 comfort criteria as the inflection signal for cross-certification efficiency plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latex Processing | Captive supply of Thai plantation output insulates against natural rubber price volatility. |
| Classification Society Co-Certification | Joint Lloyd's Register-DNV qualification accelerates market access for dual-fuel isolation systems. |
| Composite Material R&D Partnership | Carbon fiber damper development with South Korean superyacht builders captures IMO compliance premiums. |
| Long-Term Service Agreement Expansion | Performance-guarantee contracts with German cruise lines shift revenue from transactional to recurring. |
| Autonomous Vibration-Hardening Development | Sensor-suite isolation for unmanned surface vessels opens specification channels outside naval vendor lists. |
Study Parameters
Multi-period observation of elastomer pricing indices, shipyard order backlogs, and classification society rule amendments anchored the trend analysis, supplemented by interviews with naval procurement officers, shipyard technical directors, elastomer compounder R&D leads, and aftermarket service managers. Secondary validation drew from Lloyd's Register certification databases, DNV technical standards, IMO circulars on underwater radiated noise, and customs trade records for rubber-metal bonded mount shipments. Bottom-up vessel fleet analysis and top-down maritime equipment spending estimates were triangulated to cross-check market sizing.
Segment-weighting approaches distributed value across material types, application categories, and end-user contract structures throughout the projection horizon. The analytical framework modeled naval, commercial, offshore platform, and luxury yacht applications alongside technology tiers spanning passive, tuned mass, active, and hybrid control systems. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement timelines. Forecast inputs included shipyard capacity utilization rates in South Korea and India, plus dual-fuel engine retrofit penetration assumptions across European commercial fleets.
Natural rubber supply disruption, classification society rule divergence, and naval program budget reallocation are the dominant revision risks to forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Offshore Support Vessel Service Market