
 Automotive Spot Weld Inspection System Market | 2026-2036
Automotive Spot Weld Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spot Weld Inspection System Market Insights
The shift from outsourced quality audits toward captive in-line inspection is realigning how automotive manufacturers source spot weld verification. KEYENCE sustains its position through deep product specialization in laser triangulation sensors for body shop floors. ABB leverages its robotics integration capabilities to bundle inspection modules with articulated arm deployments. Cognex competes on software-defined vision platforms that reduce calibration downtime between vehicle programs.
An automotive spot weld inspection system comprises sensor arrays, data acquisition hardware, and analytical software that evaluate nugget formation, penetration depth, and surface integrity in resistance welding operations. These systems typically operate at cycle times under thirty seconds per weld cluster to match takt rates in high-volume assembly plants. Automated inspection systems command the dominant share of capital expenditure as OEMs eliminate manual gauging from production flow. Ultrasonic technology leads installed base volumes due to its maturity in detecting internal voids, while laser-based methods represent the fastest-expanding category for real-time geometric feedback. Software solutions increasingly capture margin pools through subscription analytics that aggregate weld quality data across multiple plants.
NHTSA structural integrity requirements, Euro NCAP crash assessment protocols, and ISO 17657 welding quality standards collectively mandate traceable documentation of every critical spot weld in passenger vehicle bodies. Manufacturers must retain inspection records for regulatory compliance and liability defense across the vehicle lifecycle. Stakeholders should monitor how battery enclosure welding specifications from emerging EV architectures reshape inspection parameter sets and sensor selection criteria.
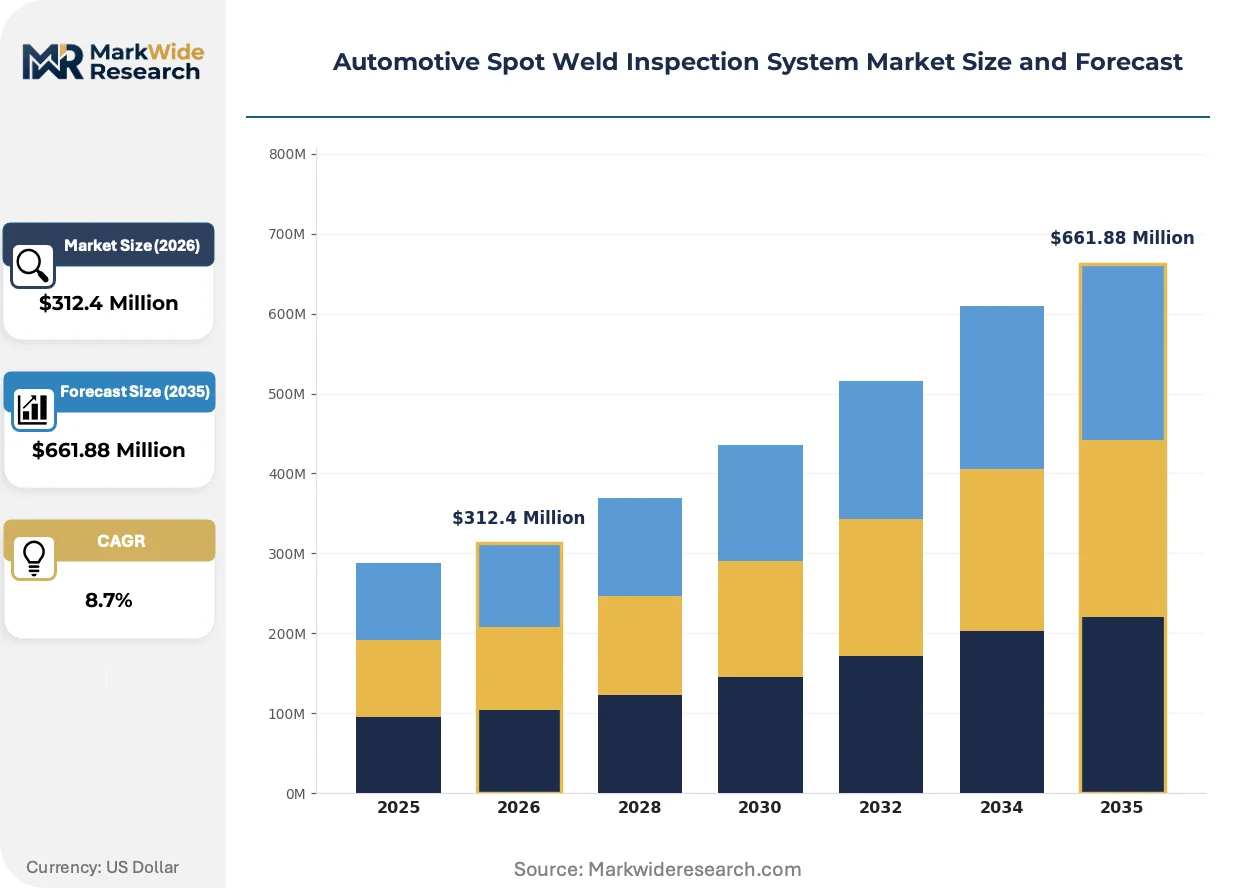
Market Dynamics
Automotive manufacturers are eliminating manual weld verification from body-in-white production flows, creating structural demand for in-line inspection stations that match takt rates under thirty seconds per weld cluster. This shift from outsourced quality audits toward captive inspection realigns capital allocation across the supply chain.
Growth Catalysts
- NHTSA structural integrity mandates:Crashworthiness documentation requirements now mandate traceable records for every critical spot weld, compelling OEMs to deploy automated verification systems across passenger vehicle programs.
- EV battery enclosure welding:Electric vehicle architectures require specialized inspection parameter sets for aluminum-intensive battery tray assemblies, expanding addressable system configurations.
- German automated body shop concentration:Volkswagen, BMW, and Mercedes-Benz operate the densest networks of robotic welding cells, generating concentrated procurement pull for integrated inspection modules.
Market Restraints
- Ultrasonic transducer supply concentration:High-frequency piezoelectric sensor manufacturing clusters in Japan and Germany, exposing buyers to single-source risk and extended lead times.
- Laser triangulation calibration complexity:Geometric feedback systems require frequent recalibration between vehicle programs, inflating total cost of ownership beyond initial capital expenditure.
- ISO 17657 compliance documentation burden:Weld quality standard retention requirements across vehicle lifecycles impose archival infrastructure costs that deter mid-volume manufacturers.
Strategic Opportunities
- India passenger vehicle localization:Maruti Suzuki and Hyundai Motor India are expanding automated body shop capacity under PLI scheme incentives, creating first-mover positioning for inspection system vendors.
- Subscription analytics aggregation:Cloud-based weld quality data platforms across multiple plants capture recurring revenue streams previously lost to one-time hardware sales.
- Thermal imaging fusion with ultrasonic arrays:Hybrid sensor configurations combining real-time temperature mapping with void detection enable single-pass inspection of complex weld geometries.
Industry Challenges
- Multi-physics simulation expertise scarcity:System integrators struggle to hire engineers capable of modeling acoustic wave propagation through heterogeneous automotive steel stacks.
- Legacy MES integration friction:Brownfield assembly plants operate decades-old manufacturing execution systems that resist API connectivity with modern inspection data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spot Weld Inspection System Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Manual Inspection Tools, Automated Inspection Systems, Software Solutions Technology: X-ray, Laser, Ultrasonic, Visual Inspection End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Manufacturing Plants Application: Quality Control, Process Monitoring, Compliance Verification, Fault Detection |
| Companies Covered | ABB, Cognex, KEYENCE, Hexagon Manufacturing Intelligence, Carl Zeiss, Nikon Metrology, Olympus Corporation, ISRA Vision, Xiris Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spot Weld Inspection System Market Trends and Innovations
Inspection technology is bifurcating between mature ultrasonic methods and emerging optical approaches, with software-defined platforms compressing hardware replacement cycles across automotive production networks.
Laser-based geometric measurement is overtaking contact-based gauging for real-time nugget diameter verification. EV manufacturers in the United States and Germany are adopting these systems at cycle-matched speeds for aluminum-intensive body structures. This displacement is compressing the installed base advantage held by incumbent ultrasonic suppliers.
Euro NCAP crash assessment protocols now require documented weld performance correlation with structural simulation models. European OEMs must submit inspection data alongside physical test results for five-star safety ratings. Battery electric vehicle programs face the steepest compliance burden due to novel enclosure load paths.
Automotive buyers are consolidating supplier relationships around full-stack inspection providers capable of sensor hardware, analytics software, and regulatory documentation. Tier-1 integrators previously sourcing components separately now favor single-vendor accountability. This concentration is most visible in Japan, where Toyota and Honda have reduced qualified supplier lists by forty percent since 2022.
Automotive Spot Weld Inspection System Market Segmentation
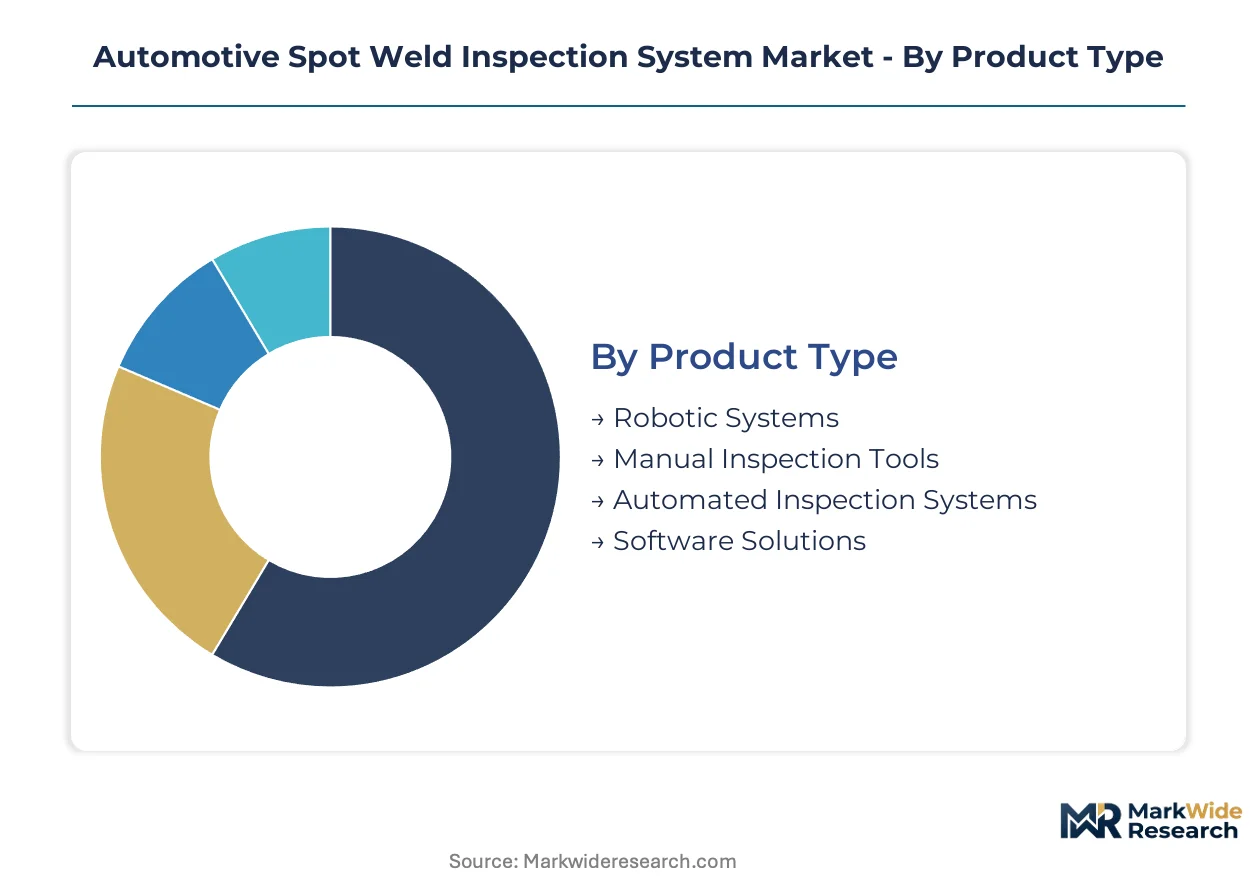
Automotive manufacturers configure inspection procurement around production velocity, regulatory documentation burden, and material complexity. Segment selection determines capital allocation between in-line automation and offline verification stations.
Product Type:
Supply concentration favors integrated system vendors over component specialists across body-in-white production networks.
- Automated Inspection Systems:These stations integrate sensor arrays, data acquisition hardware, and analytical software for real-time weld verification at takt rates under thirty seconds per cluster. Volkswagen, BMW, and Mercedes-Benz in Germany deploy these most densely to satisfy NHTSA crashworthiness documentation mandates.
- Software Solutions:Cloud-based analytics platforms aggregate weld quality data across multiple plants through subscription models. These capture recurring revenue streams as OEMs consolidate supplier relationships around full-stack accountability.
- Robotic Systems:Articulated arm deployments bundle inspection modules with welding cells for seamless body shop integration.
- Manual Inspection Tools:Portable ultrasonic gauges and handheld laser devices serve offline quality audits and prototype validation.
Today's leader: Automated Inspection Systems. Tomorrow's challenger: Software Solutions.
Technology:
Cost tier separation emerges between mature contact methods and premium non-destructive optical approaches.
- Ultrasonic:High-frequency piezoelectric sensors detect internal voids and nugget formation through acoustic wave propagation. This method dominates installed base volumes in Japan and Germany, though transducer supply concentration in these geographies exposes buyers to single-source risk.
- Laser:Triangulation and geometric measurement systems provide real-time nugget diameter verification without contact. EV manufacturers in the United States adopt these fastest for aluminum-intensive battery tray assemblies.
- X-ray:Computed tomography reveals three-dimensional weld structure for research and failure analysis applications.
- Visual Inspection:Camera-based surface integrity assessment complements deeper penetration methods for cosmetic weld evaluation.
Ultrasonic holds the installed base advantage. Laser gains share fastest in high-speed aluminum welding applications.
End User:
Volume concentration tracks automated body shop density across passenger vehicle production clusters.
- OEMs:Original equipment manufacturers deploy captive in-line inspection to eliminate manual verification from production flow and retain weld records across vehicle lifecycles for liability defense.
- Tier-1 Suppliers:Component integrators source bundled inspection modules with robotic welding cells, consolidating vendor relationships for single-source accountability.
- Manufacturing Plants:Individual facility operators configure systems around legacy MES integration requirements and brownfield infrastructure constraints.
- Aftermarket Providers:Collision repair and refurbishment specialists utilize portable equipment for structural integrity verification outside original production contexts.
OEMs command procurement volume. Tier-1 Suppliers represent the fastest-expanding configuration segment as outsourcing patterns shift.
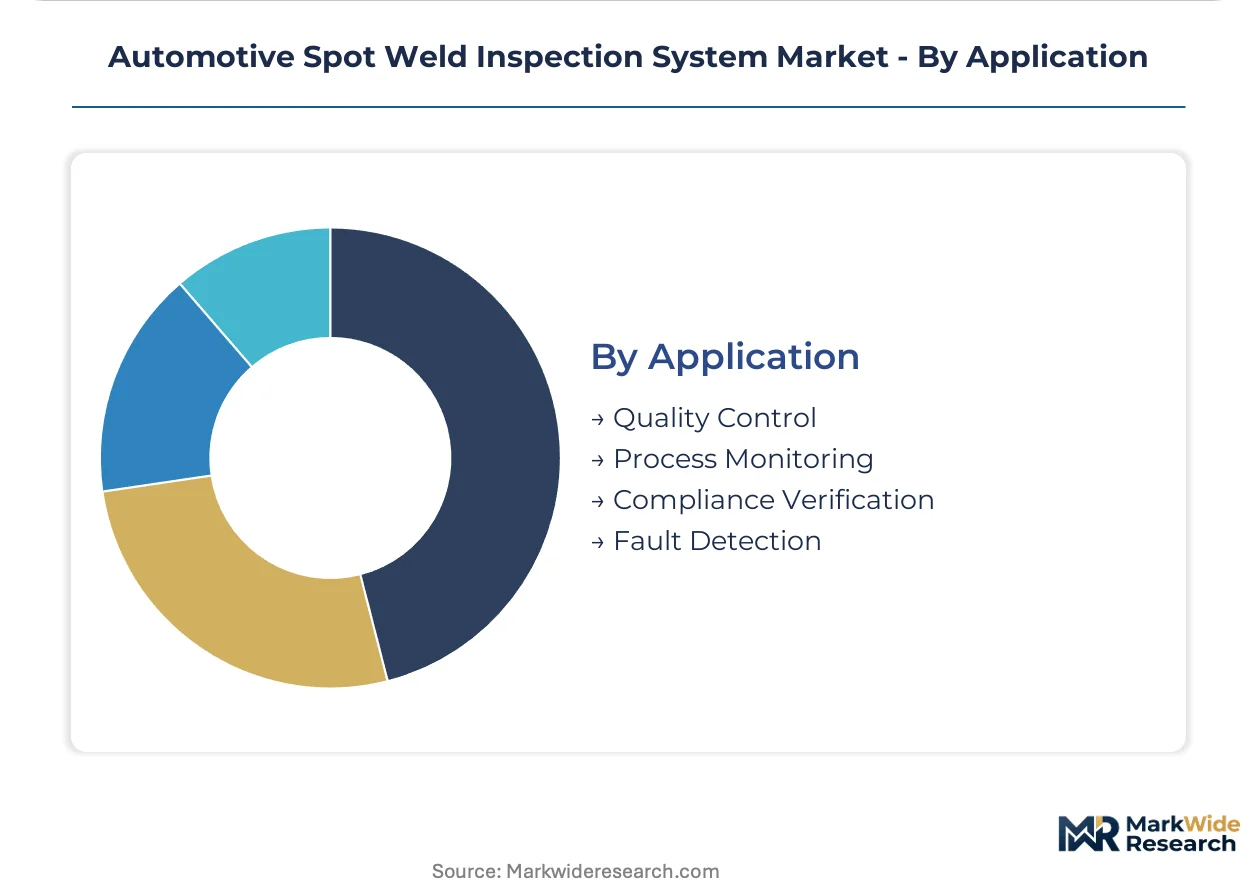
Application:
Margin pools concentrate where regulatory documentation requirements intersect with real-time production constraints.
- Compliance Verification:Traceable record retention for every critical spot weld satisfies NHTSA structural integrity mandates, Euro NCAP crash assessment protocols, and ISO 17657 welding quality standards. This application captures premium pricing through archival infrastructure integration.
- Quality Control:Statistical process monitoring identifies drift in nugget formation before out-of-specification welds propagate through body assemblies.
- Process Monitoring:Real-time feedback loops adjust welding parameters based on immediate geometric or acoustic sensor readings.
- Fault Detection:Isolation of defective weld clusters triggers automated rework routing or production halt decisions.
Compliance Verification commands highest system value. Quality Control offers broadest addressable deployment base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturing clusters in Bavaria and Baden-Württemberg generate the densest procurement pull for in-line spot weld inspection systems, driven by Volkswagen, BMW, and Mercedes-Benz body-in-white automation.
Germany
Volkswagen's Wolfsburg complex and BMW's Munich-Dingolfing corridor deploy ultrasonic and laser inspection modules at cycle times matching thirty-second takt rates. KBA vehicle type approval regulations mandate weld documentation retention across vehicle lifecycles. Stuttgart's industrial automation ecosystem concentrates system integrators serving Mercedes-Benz Sindelfingen and Porsche Zuffenhausen plants.
United States
Detroit Three manufacturers and Tesla's Fremont and Austin facilities drive demand for aluminum-intensive battery enclosure inspection. NHTSA structural integrity mandates require traceable records for every critical spot weld in passenger vehicle programs. Michigan's automated body shop density, particularly around Warren and Dearborn, anchors North American procurement volume for integrated inspection stations.
Japan
Toyota City and Honda's Suzuka operations maintain captive inspection capabilities with reduced supplier lists favoring full-stack accountability. METI industrial standards for automotive manufacturing quality systems shape procurement specifications. Nagoya's robotics integration cluster supplies inspection modules bundled with articulated welding cells for domestic and export markets.
China
BYD's Shenzhen headquarters and SAIC's Shanghai operations accelerate in-line inspection deployment for electric vehicle battery tray assemblies. MIIT new energy vehicle certification requirements tighten weld quality documentation for structural enclosures. Yangtze River Delta manufacturing hubs in Suzhou and Wuxi concentrate domestic system integrators serving localized body shop automation.
India
Maruti Suzuki's Gurgaon-Manesar corridor and Hyundai Motor India's Chennai operations expand automated body shop capacity under PLI scheme incentives. BIS automotive component quality standards increasingly reference ISO 17657 welding documentation requirements. Tamil Nadu's Sriperumbudur industrial belt generates concentrated demand for first-mover inspection system vendors.
Automotive Spot Weld Inspection System Market Competitive Landscape
Global majors compete with regional champions across sensor technology and software integration capabilities. The vendor base stratifies between full-stack system providers and component specialists, with consolidation pressure favoring single-source accountability. Three archetypes dominate: robotics-integrated platform vendors, laser triangulation specialists, and vision software-defined platforms. Competitive moves center on strategic partnerships with automotive OEMs and geographic expansion into emerging EV manufacturing clusters.
Within the full-stack integration tier, ABB and Cognex exemplify divergent positioning strategies. ABB leverages its robotics heritage to bundle inspection modules with articulated arm deployments, occupying a position anchored in welding cell automation. Cognex competes through software-defined vision platforms that reduce calibration friction between vehicle programs. KEYENCE sustains its position through deep specialization in laser triangulation sensors for body shop floor environments.
| Leading Market Players |
|---|
| ABB |
| Cognex |
| KEYENCE |
| Hexagon Manufacturing Intelligence |
| Carl Zeiss |
| Nikon Metrology |
| Olympus Corporation |
| ISRA Vision |
| Xiris Automation |
| Others |
Pricing and Supply Chain Analysis
Euro NCAP crash assessment protocols gate qualified supply and premium-tier pricing access for automotive spot weld inspection systems, as OEMs must demonstrate documented weld performance correlation with structural simulation models to achieve five-star safety ratings. This regulatory threshold separates vendors capable of archival infrastructure integration from component specialists locked out of high-value compliance verification contracts.
Pricing Analysis
Input-cost pass-through from high-frequency piezoelectric transducers and laser triangulation sensors shapes pricing structures across hardware tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from German and Japanese OEMs. Cost compression in standard-tier ultrasonic systems is intensifying because transducer supply concentration in Japan exposes buyers to extended lead time premiums. Tier-1 suppliers represent the most price-sensitive segment, while OEMs pursuing NHTSA crashworthiness documentation show lowest sensitivity to upfront capital expenditure.
Supply Chain Analysis
ISO 17657 welding quality certification and KBA vehicle type approval documentation requirements gate entry for sensor manufacturers serving European automotive production networks. High-frequency piezoelectric transducer manufacturing clusters in Japan and Germany anchor supply, with laser optics sourcing from United States and German precision engineering hubs. Single-source vulnerability concentrates in Japanese ceramic substrate suppliers for ultrasonic sensor cores. Distribution runs through Tier-1 robotics integrators bundling inspection modules with articulated welding cell deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium specifications as EV battery enclosure welding demands specialized aluminum inspection parameter sets. The transition from outsourced quality audits toward captive in-line inspection creates durable demand for full-stack vendors capable of regulatory documentation.
For Market Incumbents: To counter displacement from laser-based geometric measurement systems overtaking ultrasonic installed base advantage, deepen software-defined platform capabilities to reduce calibration friction between vehicle programs and secure backward integration into cloud analytics aggregation across multiple plants. For New Entrants and Emerging Players: Launch via direct OEM engagement in India's PLI scheme expansion corridor, where Maruti Suzuki and Hyundai Motor India automated body shop buildout creates first-mover positioning for inspection system vendors lacking established supplier relationships in Germany or Japan. For Investors and Strategic Acquirers: Roll-up economics work for full-stack inspection providers because automotive buyers have consolidated supplier relationships by forty percent since 2022, creating scarcity value for vendors combining sensor hardware, analytics software, and regulatory documentation capabilities. Target acquisition archetypes include laser triangulation specialists with proven body shop floor deployment records. The signal to watch is battery enclosure welding specification releases from emerging EV architectures reshaping inspection parameter sets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces calibration downtime between Volkswagen, BMW, and Mercedes-Benz vehicle programs. |
| Battery Supply Agreement | Secures dedicated high-frequency transducer allocation from Japanese ceramic substrate suppliers. |
| Software-Defined Vehicle Investment | Enables real-time weld quality data aggregation across Tesla's Fremont and Austin facilities. |
| Geographic Manufacturing Footprint | Positions service infrastructure near Tamil Nadu's Sriperumbudur industrial belt expansion. |
| Charging Infrastructure Partnership | Creates bundled inspection module deployment with robotic welding cell installations. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, robotics integration specialists, and aftermarket service heads grounded qualitative findings in operational realities across body-in-white production networks. Secondary validation drew from NHTSA crashworthiness documentation filings, Euro NCAP test result submissions, vehicle production databases, and IHS Markit registration data. Bottom-up and top-down triangulation reconciled facility-level procurement patterns with aggregate market sizing.
Analytical lens alternated between bottom-up capacity modeling of automated inspection station deployments and top-down expenditure tracking across OEM capital allocation disclosures. Segmentation dimensions spanned product type, technology modality, end-user archetype, and application purpose, with propulsion architecture and regional production cluster as automotive-specific overlays. CAGRs were derived from regression analysis of historical procurement velocity against projected EV manufacturing capacity expansion throughout the forecast period. Industry-specific inputs included takt rate requirements under thirty seconds per weld cluster and battery enclosure welding specification evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden shifts in NHTSA structural integrity mandate enforcement or Japanese transducer supply disruption. Model assumptions reflect documented weld retention requirements across vehicle lifecycles and ISO 17657 compliance infrastructure costs. A model refresh is warranted upon material change in EV battery tray assembly aluminum content specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market