
 Dock Fender Market | 2026-2036
Dock Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Dock Fender Market Outlook
Marine polymer engineering talent is rotating toward composite formulation roles as port operators specify higher-performance berthing solutions. Trelleborg Marine Systems leverages its integrated manufacturing footprint across Nordic and Asian facilities to control supply continuity for large-diameter fender projects. Yokohama Rubber anchors its position through captive rubber compounding capabilities that sustain margin pools in high-energy super cell segments. JIER Marine dominates the Chinese port retrofit channel through direct contracting relationships with state-owned terminal operators.
A dock fender is a marine cushioning device, typically constructed from rubber compounds, closed-cell foam, or steel-reinforced elastomeric assemblies, designed to absorb kinetic energy during vessel berthing and prevent structural damage to wharves and hulls. Manufacturing involves compression molding of natural or synthetic rubber blends, often with embedded steel plates or chain networks, to achieve specified reaction force and energy absorption curves under PIANC and ASTM testing protocols. Rubber-type fenders retain the largest installed base across commercial maritime terminals due to proven durability in cyclic loading environments. Foam-type fenders are gaining share in recreational and temporary installations where lighter weight and corrosion immunity offset higher unit costs. Port authorities represent the most concentrated end-user segment, with procurement decisions increasingly bundled into long-term terminal concession agreements that lock in fender replacement cycles.
PIANC guidelines govern fender system design and energy absorption calculations for international port projects, while ASTM F606 and ISO 17357 define material testing and performance certification thresholds that determine product eligibility for public tenders. In the United States, the Maritime Administration and Army Corps of Engineers incorporate these standards into federal port infrastructure grants, effectively filtering market access for uncertified suppliers. Stakeholders must monitor evolving vessel size classes and corresponding berthing energy requirements, as ultra-large container ships and LNG carriers force fender specification upgrades ahead of scheduled replacement cycles.
Market Dynamics
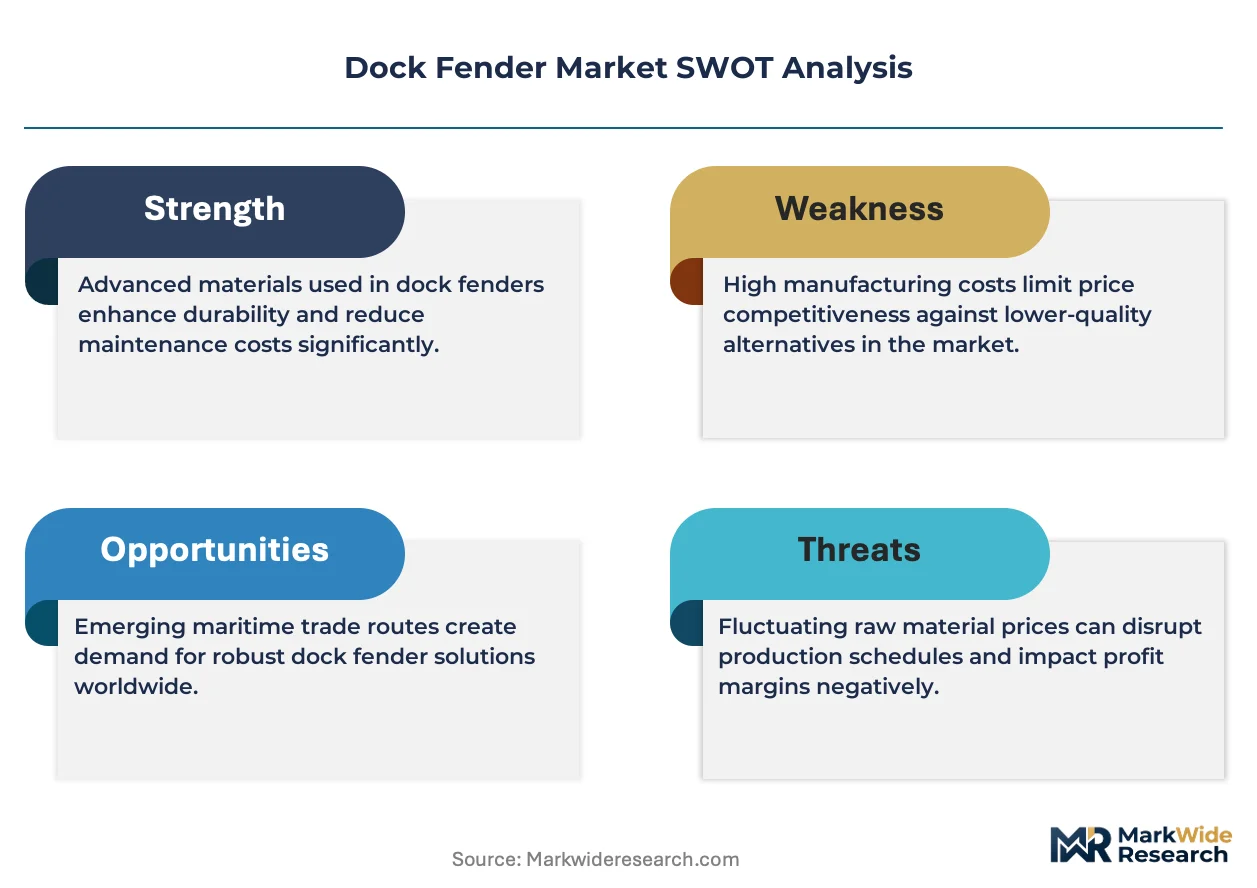
Ultra-large container vessels and LNG carriers are forcing premature fender replacement cycles as berthing energy calculations under PIANC guidelines now exceed installed capacity at legacy terminals. Port authorities face capital allocation pressure between berth expansion and fender upgrades.
Growth Catalysts
- Greenfield Port Investments:Vietnam and Indonesia are accelerating berth construction under state infrastructure programs. These projects specify high-performance composite fenders from initial design.
- PIANC Guideline Tightening:Revised vessel berthing energy standards are mandating higher absorption capacity. Terminal operators must retrofit existing installations to maintain certification.
- Marine Polymer Engineering Talent Migration:Composite formulation expertise is concentrating in Nordic and Asian manufacturing clusters. This skills concentration enables next-generation fender development.
Market Restraints
- Natural Rubber Price Volatility:Synthetic rubber substitutes face performance gaps in cyclic loading. Formulation engineers struggle to maintain reaction force curves when primary feedstock costs spike.
- Steel-Reinforced Assembly Concentration:Embedded plate fabrication depends on a narrow supplier base in East Asian foundries. Geographic concentration creates delivery risk for large-diameter projects.
- Closed-Cell Foam Substitution Ceiling:Foam-type fenders cannot achieve energy absorption parity with rubber in commercial maritime terminals. Unit cost premiums limit addressable market expansion.
Strategic Opportunities
- Vietnamese Port Authority Bundling:Long-term terminal concession agreements are incorporating fender replacement schedules. Direct contracting relationships lock in multi-cycle revenue streams.
- Composite-Rubber Hybrid Convergence:Steel-reinforced elastomeric assemblies are integrating polymer foam cores. This architecture delivers weight reduction without sacrificing energy absorption.
- US Maritime Administration Grant Alignment:Federal port infrastructure funding requires ASTM F606 certification. Qualified suppliers gain preferential access to public tender pipelines.
Industry Challenges
- PIANC-ASTM Certification Timeline Compression:Testing protocols for new vessel size classes require extended validation cycles. Product development schedules misalign with port authority procurement windows.
- Legacy Chain Network Integration:Retrofit projects must interface with existing mooring infrastructure. Installation complexity escalates when original specification documentation is incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dock Fender Market |
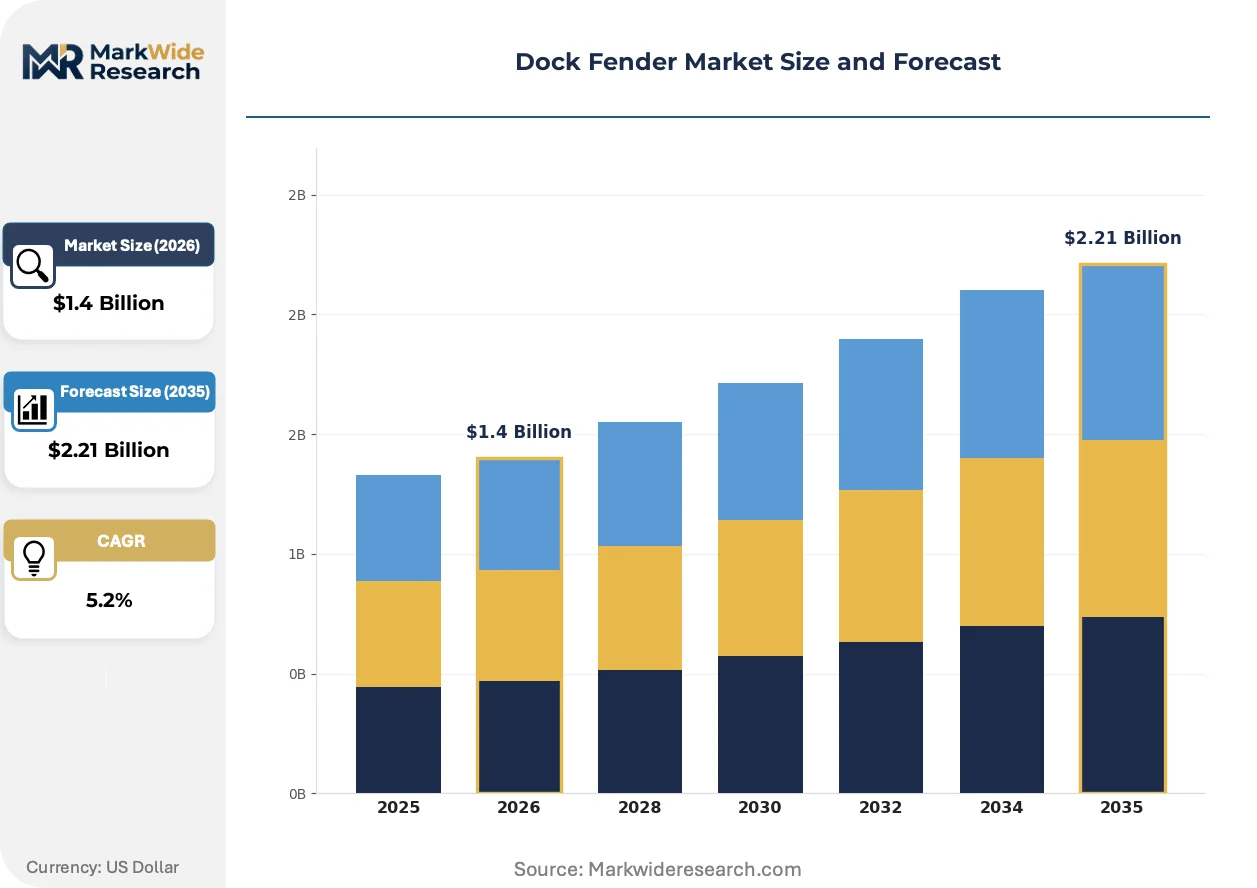
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Foam, Rubber, Steel, Plastic Application: Maritime, Industrial, Commercial, Recreational End User: Port Authorities, Shipping Companies, Boat Manufacturers, Marinas Installation: Permanent, Temporary, Adjustable, Fixed |
| Companies Covered | Trelleborg Marine Systems, Yokohama Rubber, Shibata Fender Team, Bridgestone, Sumitomo Rubber Industries, Fendercare Marine, Schuyler Companies, JIER Marine, Prosertek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dock Fender Market Strategic Shifts
Material science advances and procurement model evolution are compressing fender specification cycles while expanding performance boundaries. Three developments are restructuring competitive positioning.
Steel-reinforced elastomeric assemblies with embedded polymer foam cores are miniaturizing reaction force profiles without sacrificing energy absorption capacity. Port operators in Southeast Asia specify these hybrids for constrained berth geometries where conventional super cell fenders exceed spatial envelopes. The technology is miniaturizing installation footprints while maintaining PIANC-compliant performance curves.
REACH substance restrictions on certain rubber accelerators are forcing reformulation of traditional natural rubber compounds. European terminal operators now demand full material disclosure documentation upstream of tender submission. German and Dutch port authorities have integrated ECHA compliance verification into their technical evaluation matrices.
Terminal concession bundling is consolidating procurement authority under fewer decision-makers with longer time horizons. State-owned operators in Indonesia and Vietnam now negotiate decade-spanning fender service agreements that internalize replacement risk. This concentration is displacing spot-market purchasing and favoring suppliers with captive manufacturing footprints.
Dock Fender Market Segmentation
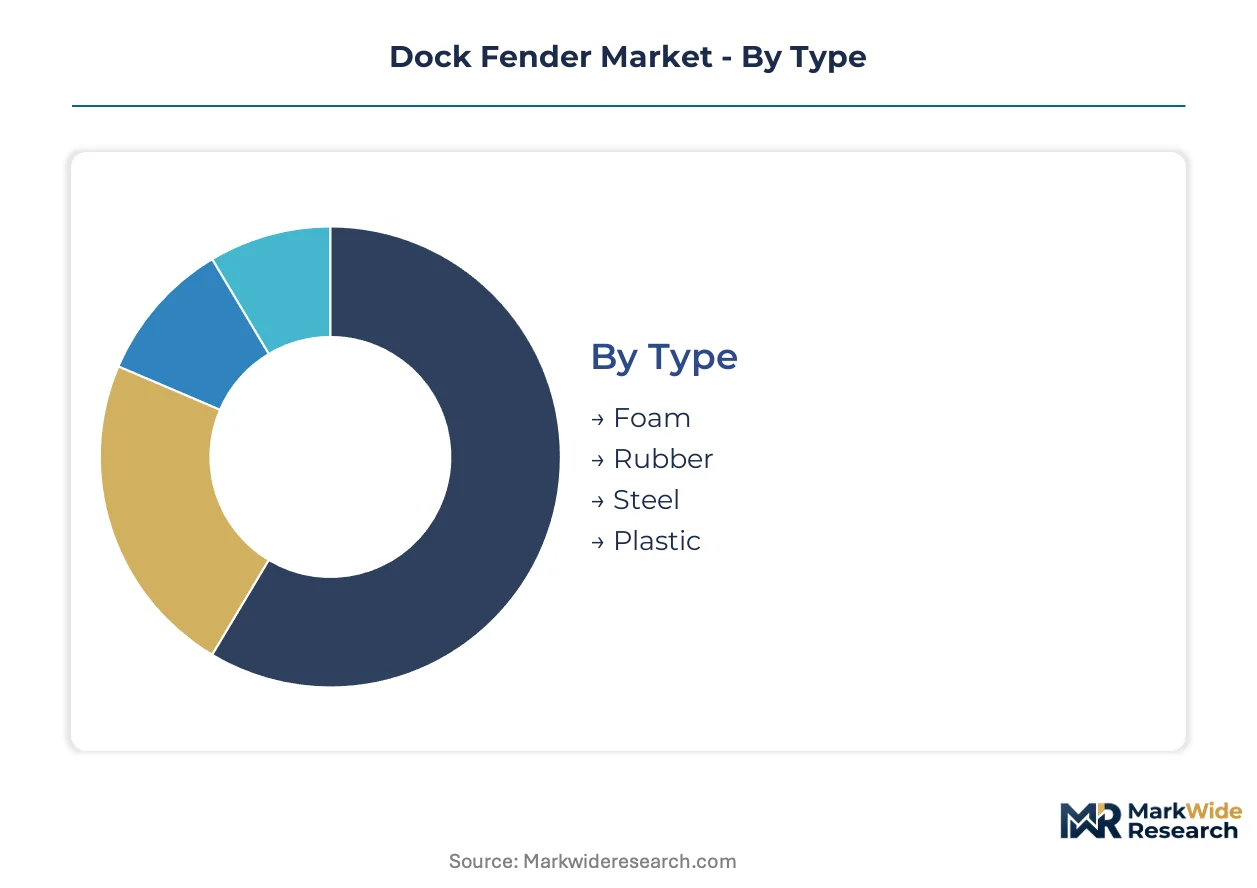
Dock fender procurement patterns diver sharply across type and application boundaries. Port authorities in Vietnam and Indonesia specify high-performance composites for greenfield berths, while legacy terminals in Europe prioritize retrofit compatibility over specification upgrades.
Type:
Rubber and foam formulations dominate export-led procurement from Nordic and Asian manufacturing clusters, while steel-reinforced variants concentrate in domestic heavy-industry applications.
- Rubber:Natural and synthetic rubber compounds undergo compression molding with embedded steel plates or chain networks to achieve PIANC-compliant reaction force curves. Vietnamese and Indonesian port authorities specify these for commercial maritime terminals where cyclic loading durability outweighs unit cost premiums.
- Foam:Closed-cell polymer cores deliver corrosion immunity and weight reduction for recreational installations and temporary berthing systems. Demand concentrates in European marinas and Southeast Asian yacht facilities where installation flexibility trumps energy absorption maximization.
- Steel:Steel-reinforced elastomeric assemblies integrate embedded plate fabrication from East Asian foundries for ultra-large vessel berthing energy absorption.
- Plastic:Thermoplastic formulations serve light-duty commercial applications with lower berthing energy requirements and constrained capital budgets.
Rubber holds the largest share; momentum sits with foam.
Application:
Procurement authority concentrates under port authorities in maritime applications, while industrial and commercial segments fragment across facility operators with shorter replacement horizons.
- Maritime:Container terminals, LNG facilities, and bulk cargo ports specify high-energy fender systems under PIANC guidelines. State-owned operators in Indonesia negotiate decade-spanning service agreements that internalize replacement risk and lock in supplier relationships.
- Industrial:Manufacturing facilities with private docks prioritize retrofit compatibility over performance upgrades. REACH substance restrictions on rubber accelerators force European industrial operators to demand full material disclosure documentation upstream of tender submission.
- Commercial:Mixed-use waterfront developments balance aesthetic constraints with functional berthing requirements.
- Recreational:Marinas and yacht clubs specify lighter-weight foam-type solutions where corrosion immunity offsets higher per-unit costs.
Maritime commands volume leadership; recreational applications are expanding most quickly.
End User:
Customer scale determines procurement sophistication, with port authorities bundling multi-cycle replacement schedules while boat manufacturers negotiate component supply agreements.
- Port Authorities:State-owned terminal operators in Vietnam and Indonesia consolidate procurement authority under long-term concession agreements. These entities specify composite-rubber hybrid architectures for constrained berth geometries where conventional super cell fenders exceed spatial envelopes.
- Shipping Companies:Container lines and LNG operators influence fender specification through vessel size class requirements that force premature replacement cycles at legacy terminals.
- Boat Manufacturers:OEM integration demands standardized fender dimensions for production line compatibility.
- Marinas:Private facility operators prioritize spot-market purchasing with shorter decision horizons.
Port authorities anchor demand concentration; shipping companies drive specification upgrades.
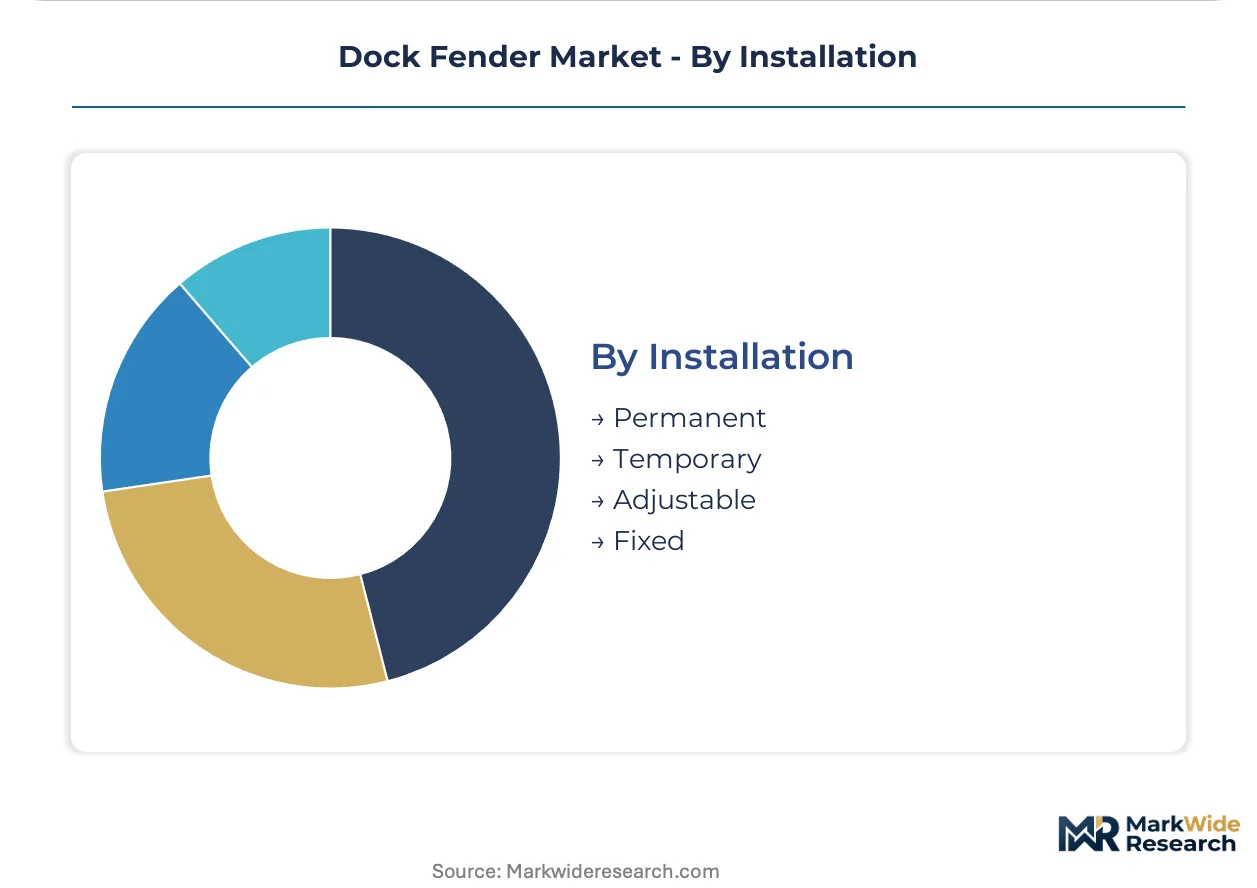
Installation:
Permanent and fixed installations dominate capital-intensive port infrastructure, while temporary and adjustable systems serve project-based and seasonal demand.
- Permanent:Embedded steel-reinforced assemblies with concrete anchoring systems serve commercial maritime terminals with 20-year design lives. Installation complexity escalates when original specification documentation is incomplete for retrofit projects.
- Fixed:Non-adjustable fender positioning suits standardized vessel fleets with predictable berthing geometry. US Maritime Administration grants require ASTM F606 certification for fixed installations in federally funded port infrastructure.
- Temporary:Modular foam-type systems deploy for construction phases and emergency berthing capacity.
- Adjustable:Position-variable fender arrays accommodate mixed vessel size classes at multi-purpose terminals.
Permanent installations retain the largest installed base; adjustable systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PIANC guidelines anchor procurement standards across maritime infrastructure, with regulatory enforcement varying by national port authority structure and federal grant requirements.
United States
Container terminal upgrades at Los Angeles and Long Beach drive demand for high-energy fender systems. The Maritime Administration and Army Corps of Engineers incorporate ASTM F606 certification into federal port infrastructure grants. Gulf Coast LNG export facilities in Texas and Louisiana specify steel-reinforced elastomeric assemblies for ultra-large carrier berthing.
China
State-owned terminal operators accelerate retrofit cycles at legacy ports along the Yangtze River Delta. GB standards and MIIT regulations govern domestic fender performance testing and material certification. Qingdao and Tianjin manufacturing clusters supply embedded steel plate fabrication for regional heavy-industry applications.
Germany
REACH substance restrictions on rubber accelerators force compound reformulation for European terminal operators. ECHA compliance verification is integrated into technical evaluation matrices at Hamburg and Bremerhaven port authorities. Industrial facilities in the Ruhr region prioritize retrofit compatibility over specification upgrades for private dock infrastructure.
Vietnam
Greenfield berth construction under state infrastructure programs specifies high-performance composite fenders from initial design. Long-term terminal concession agreements bundle multi-cycle replacement schedules under consolidated procurement authority. Hai Phong and Cai Mep-Thi Vai port clusters anchor Southeast Asian demand concentration.
Indonesia
State-owned terminal operators negotiate decade-spanning fender service agreements that internalize replacement risk. PIANC guideline tightening mandates higher absorption capacity for existing installations at Jakarta and Surabaya terminals. Tanjung Priok expansion projects specify composite-rubber hybrid architectures for constrained berth geometries.
Dock Fender Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting captive manufacturing footprints versus regional fabrication networks. The upper tier controls supply continuity through Nordic and Asian facilities, while mid-scale players compete on retrofit compatibility and spot-market responsiveness. Strategic archetypes divide between polymer compounders with rubber expertise and steel-reinforced assembly specialists with foundry relationships. Competitive moves center on direct contracting relationships with state-owned terminal operators and composite formulation partnerships with marine engineering consultancies.
Among integrated Nordic-Asian manufacturers, Trelleborg Marine Systems and Yokohama Rubber occupy positions reflecting compound expertise and captive rubber processing capabilities. JIER Marine represents the Chinese state-contracting archetype, anchoring relationships with domestic terminal operators. These three exemplify how geographic manufacturing footprints and procurement channel access determine tier placement.
| Leading Market Players |
|---|
| Trelleborg Marine Systems |
| Yokohama Rubber |
| Shibata Fender Team |
| Bridgestone |
| Sumitomo Rubber Industries |
| Fendercare Marine |
| Schuyler Companies |
| JIER Marine |
| Prosertek |
| Others |
Value Chain & Pricing Dynamics
Synthetic rubber substitution for natural rubber compounds is redrawing procurement geography as Vietnamese and Indonesian port authorities specify reformulated elastomers, simultaneously compressing margin pools for traditional compounders and elevating pricing power for integrated manufacturers with captive polymer engineering capabilities.
Pricing Analysis
Long-term terminal concession agreements dominate procurement structures, with decade-spanning service contracts bundling fender replacement cycles and internalizing supplier risk. Price differentiation separates ASTM F606-certified premium tiers from uncertified economy alternatives, with certification grade and volume scale as primary drivers. Pricing pressure intensifies in standard rubber segments as REACH-compliant compound reformulation elevates input costs. State-owned port authorities exhibit lowest price sensitivity due to concession-backed capital allocation, while private marinas negotiate spot-market terms with acute cost consciousness.
Supply Chain Analysis
Strategic stockpiling of natural rubber and steel plate inventories characterizes procurement behavior among integrated Nordic and Asian manufacturers buffering against feedstock volatility. Supply concentrates in China, Vietnam, and Germany, with embedded steel fabrication drawing from East Asian foundries and rubber compounding anchored in Southeast Asian processing clusters. Raw material dependencies center on natural rubber latex, synthetic polymer feedstocks, and high-tensile steel plate. Single-source vulnerability pervades steel-reinforced assembly networks. Distribution runs through direct contracting relationships with state-owned terminal operators, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dock fender market is entering a cyclical recovery phase as premature replacement cycles triggered by ultra-large vessel berthing energy requirements create sustained demand visibility across the analysis window.
For Market Incumbents: Shield market position by deepening backward integration into rubber compounding capabilities to offset natural rubber price volatility, while accelerating ASTM F606 and PIANC certification investments to filter tender access. Composite-rubber hybrid development represents the priority R&D lever against emerging polymer foam specialists.
For New Entrants and Emerging Players: Aftermarket service-layer gaps in legacy chain network integration and incomplete specification documentation recovery present white-space opportunities. Target European industrial retrofit segments where REACH compliance complexity disadvantages non-integrated suppliers. Pursue marine engineering consultancy partnerships as the primary go-to-market channel.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabrication networks lacking captive polymer formulation capabilities. Five-to-ten year viability hinges on concession bundling exposure in Vietnam and Indonesia. Monitor PIANC guideline revision timelines as the critical inflection signal for specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive supply of REACH-compliant compounds insulates margins from natural rubber volatility. |
| Composite-Rubber Hybrid Development | Polymer foam core integration enables weight reduction without sacrificing PIANC energy absorption. |
| Long-Term Concession Agreement Negotiation | Decade-spanning service contracts with Vietnamese and Indonesian port authorities lock in replacement cycles. |
| ASTM F606 Certification Investment | Qualified supplier status opens US Maritime Administration federal grant pipelines. |
| Marine Engineering Consultancy Partnership | Early-stage design influence secures specification preference in greenfield port projects. |
Study Parameters
Operator-level perspectives from port authority procurement directors, terminal concession managers, marine polymer engineers, and fender installation contractors anchored the qualitative base. Secondary validation drew from PIANC technical reports, ASTM F606 certification databases, customs trade records for rubber and steel inputs, and SEC filings of listed marine equipment manufacturers. Bottom-up demand modeling triangulated against top-down infrastructure investment forecasts.
Sensitivity analysis tested forecast robustness across natural rubber price scenarios, PIANC guideline implementation timelines, and vessel size class evolution assumptions. Segmentation dimensions spanned fender type, application, end-user category, and installation permanence, with regional regulatory cluster as an additional modeling layer. CAGRs derived from berth construction pipeline analysis and replacement cycle compression factors, incorporating ultra-large vessel berthing energy requirements as a demand accelerator.
Forecasts assume regulatory continuity in US Maritime Administration grant structures and EU REACH substance restrictions; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as vessel size class standards and Southeast Asian infrastructure investment commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market