
 Global Maritime Analytics Market | 2026-2036
Global Maritime Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Analytics Market Foresight
Real-time fuel optimization tier is redrawing competitive boundaries in maritime analytics. Wärtsilä leverages its engine manufacturing heritage to embed analytics directly into propulsion systems. Windward anchors its position through AI-driven vessel behavior intelligence for security and compliance screening.
Maritime analytics encompasses sensor fusion, satellite AIS tracking, and machine learning pipelines that process hydrodynamic, meteorological, and operational parameters to optimize vessel routing, fuel consumption, and port turnaround times. Fleet management applications currently dominate revenue as ship owners prioritize voyage efficiency and carbon intensity indicator compliance. Predictive maintenance segments within port operations are expanding fastest, driven by berth scheduling optimization and crane utilization analytics that reduce demurrage exposure.
The International Maritime Organization's Carbon Intensity Regulations, the EU MRV framework, and the US Coast Guard's cybersecurity directives are tightening data collection and reporting mandates across flag states. These standards force ship owners and port operators to adopt certified analytics platforms or face detention and trading restrictions. Stakeholders must evaluate whether their current data architecture can ingest multi-source telemetry while satisfying emerging audit requirements from classification societies and flag administrations.
Market Dynamics
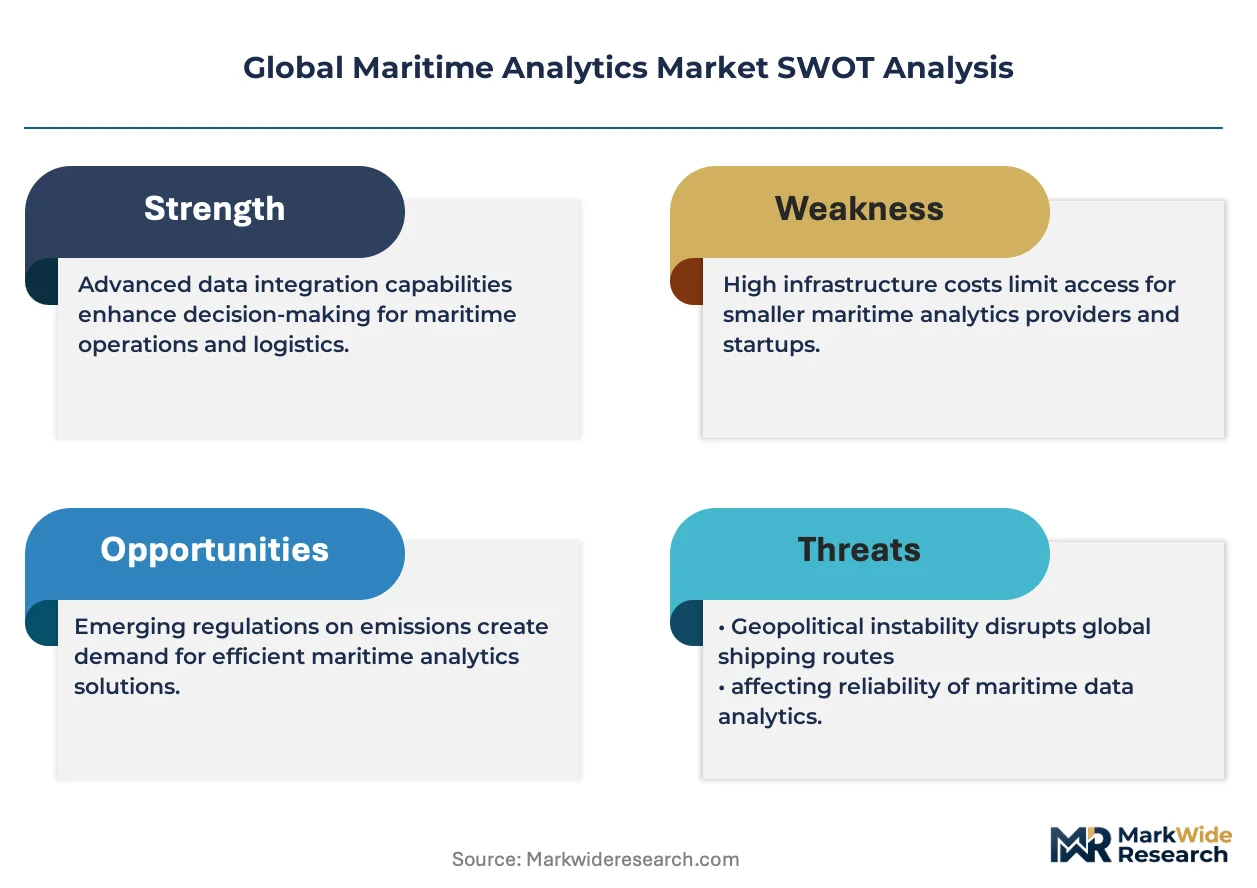
The International Maritime Organization's Carbon Intensity Regulations and EU MRV framework are compressing compliance timelines, forcing ship owners to deploy certified analytics platforms or face port detention and trading restrictions across flag states.
Growth Catalysts
- EU MRV Regulation:Mandatory emissions monitoring creates baseline demand for certified fuel consumption analytics across European-flagged vessels.
- Predictive maintenance:Port authorities in Singapore deploy berth scheduling optimization to reduce demurrage exposure and crane downtime.
- Sensor fusion:Integration of hydrodynamic, meteorological, and operational telemetry enables real-time voyage optimization for container fleets.
Market Restraints
- Data architecture costs:Retrofitting legacy vessels with multi-source telemetry ingestion systems requires substantial capital expenditure per hull.
- Classification society fragmentation:Divergent audit requirements across DNV, Lloyd's Register, and ABS create compliance complexity for multi-flag operators.
- Satellite AIS dependency:Vessel tracking accuracy degrades in high-latitude corridors where polar satellite coverage remains sparse.
Strategic Opportunities
- Norway's Kongsberg cluster:Maritime technology concentration around DNV headquarters and specialized engineering talent supports analytics R&D partnerships.
- Wind-assisted propulsion:Convergence of meteorological analytics with rigid sail systems creates new optimization algorithms for hybrid fleets.
- US Coast Guard cybersecurity directives:Mandated data protection standards generate demand for secure maritime analytics infrastructure in American waters.
Industry Challenges
- Maritime data science talent:Shortage of professionals combining naval architecture expertise with machine learning pipeline development constrains platform deployment velocity.
- ISO 19848 certification timelines:Extended validation periods for sensor data quality standards delay analytics platform commissioning on newbuild vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Analytics Market |
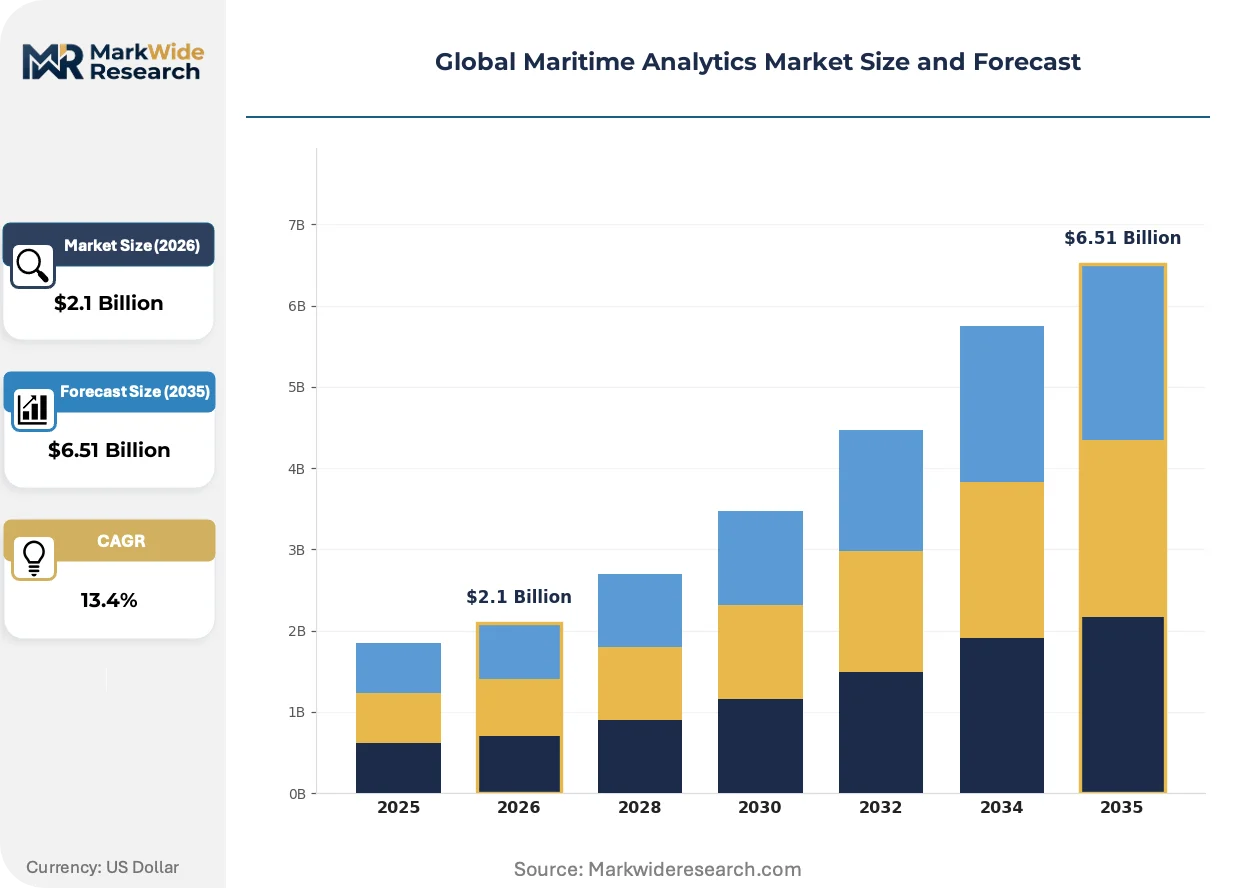
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Vessel Performance, Port Operations, Cargo Tracking, Weather Forecasting, Fuel Optimization, Maritime Security Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing, SaaS, Private Cloud Application: Fleet Management, Route Optimization, Predictive Maintenance, Regulatory Compliance, Environmental Monitoring, Incident Detection End User: Ship Owners, Port Authorities, Logistics Companies, Marine Surveyors, Insurance Providers, Coast Guard |
| Companies Covered | ABB, Wärtsilä, Windward, Spire Global, Kongsberg Gruppen, Kpler, MarineTraffic, Veson Nautical, DNV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Analytics Market Shifts & Advancements
Real-time fuel optimization tier is compressing competitive boundaries as engine manufacturers embed analytics directly into propulsion systems and AI-driven vessel behavior intelligence penetrates security screening workflows.
Digital twin technology for hull performance monitoring is bifurcating the fleet management segment. Container lines operating on Asia-Europe routes deploy high-fidelity hydrodynamic models to optimize trim and ballast configurations. The technology is bifurcating service contracts into premium real-time tiers versus standard scheduled maintenance offerings.
REACH regulation amendments tighten requirements for antifouling coating emissions tracking in European waters. Ship owners must now correlate hull performance data with coating chemistry disclosures in port state control inspections. Bulk carriers trading into Rotterdam and Hamburg face the steepest compliance documentation burdens.
Charterers now mandate continuous carbon intensity indicator disclosure as a contract precondition rather than annual reporting. Spot market fixtures in the Capesize segment increasingly specify real-time analytics access as a standard term. This pattern concentrates most visibly among Australian iron ore exporters and Chinese steel mill chartering desks.
Global Maritime Analytics Market Segmentation
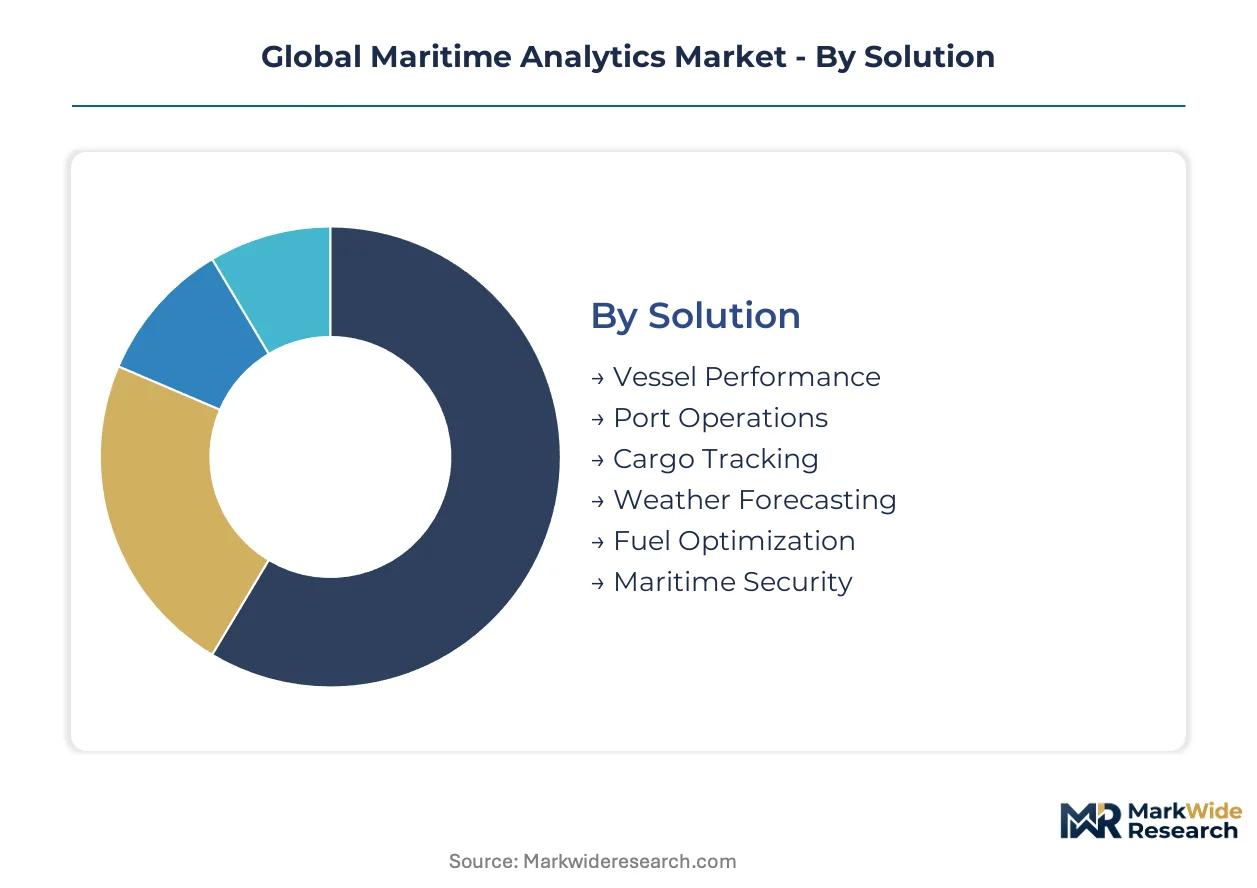
Maritime analytics segments reflect divergent margin structures across hardware-embedded solutions versus software-only platforms. Ship owners prioritize voyage efficiency applications while port authorities drive predictive maintenance adoption.
Solution:
Premium margins concentrate in fuel optimization and vessel performance modules where engine manufacturers embed proprietary algorithms directly into propulsion control systems.
- Fuel Optimization:Real-time consumption analytics integrate bunker delivery notes with engine telemetry and weather routing data. Container lines operating Asia-Europe trades deploy these systems to meet EU MRV compliance thresholds and charter party fuel clauses.
- Vessel Performance:Digital twin models process hydrodynamic sensor streams to optimize trim, ballast, and fouling management. Demand concentrates among Capesize bulk carriers facing carbon intensity indicator audits from classification societies.
- Port Operations:Berth scheduling algorithms reduce demurrage exposure for terminal operators.
- Cargo Tracking:Satellite AIS fusion with container sensor networks enables supply chain visibility.
- Weather Forecasting:Meteorological routing services integrate ensemble prediction models with vessel-specific seakeeping characteristics.
- Maritime Security:AI-driven vessel behavior screening flags anomalous navigation patterns for flag state authorities.
The dominant share belongs to Vessel Performance, while Fuel Optimization is closing the gap fastest.
Deployment:
Cost tiering separates enterprise-grade on-premises installations from volume-driven SaaS offerings targeting mid-size fleet operators.
- Cloud-Based:Multi-tenant architectures enable rapid scaling across dispersed fleet footprints without hull-mounted infrastructure investments. Norwegian maritime technology clusters favor these deployments for analytics R&D partnerships with DNV.
- Edge Computing:Local processing nodes aboard vessels handle latency-sensitive propulsion control loops when satellite connectivity degrades in polar corridors. Singapore port authorities deploy edge analytics for real-time crane optimization.
- On-Premises:Dedicated server installations satisfy cybersecurity mandates from the US Coast Guard for critical infrastructure protection.
- Hybrid:Split architectures process sensitive operational data locally while pushing aggregated benchmarks to cloud analytics engines.
- SaaS:Subscription pricing lowers barriers for smaller ship owners managing mixed-flag fleets.
- Private Cloud:Isolated infrastructure meets classification society audit requirements for data sovereignty.
Cloud-Based deployments hold the largest installed base, though Edge Computing is expanding most quickly as connectivity gaps persist in high-latitude shipping lanes.
Application:
Volume concentration tracks regulatory enforcement intensity, with compliance-driven segments commanding price premiums over operational efficiency tools.
- Regulatory Compliance:Automated reporting pipelines aggregate fuel consumption, voyage data, and emissions measurements for EU MRV and IMO Carbon Intensity Indicator submissions. Rotterdam and Hamburg port state control inspections now require correlated hull performance and coating chemistry documentation.
- Predictive Maintenance:Machine learning models forecast machinery degradation from vibration, oil analysis, and thermal sensor streams. Singapore terminal operators deploy these systems to minimize crane downtime and berth scheduling conflicts.
- Fleet Management:Integrated dashboards consolidate position tracking, maintenance schedules, and commercial performance across vessel portfolios.
- Route Optimization:Algorithms balance fuel consumption against schedule reliability using real-time current, wind, and congestion data.
- Environmental Monitoring:Systems track ballast water treatment performance and exhaust gas cleaning scrubber operations.
- Incident Detection:Automated alerts flag collisions, groundings, and piracy risks from AIS anomaly detection.
Regulatory Compliance captures the highest revenue share, while Predictive Maintenance shows the steepest expansion trajectory as port operators prioritize asset utilization.
End User:
Customer type determines procurement complexity, with integrated shipping groups consolidating analytics spend versus fragmented third-party service provider markets.
- Ship Owners:Technical managers negotiate analytics contracts as charter party fixtures increasingly mandate continuous carbon intensity disclosure rather than annual reporting. Australian iron ore exporters and Chinese steel mill chartering desks drive this specification pattern.
- Port Authorities:Terminal operators purchase berth optimization and cargo handling analytics to reduce vessel turnaround times and demurrage liabilities.
- Logistics Companies:Freight forwarders and NVOCCs deploy cargo tracking visibility platforms for shipper customers.
- Marine Surveyors:Classification society surveyors leverage analytics for remote condition monitoring and risk-based inspection scheduling.
- Insurance Providers:Underwriters incorporate vessel behavior scores into hull and machinery premium calculations.
- Coast Guard:Flag state authorities utilize security screening analytics for maritime domain awareness.
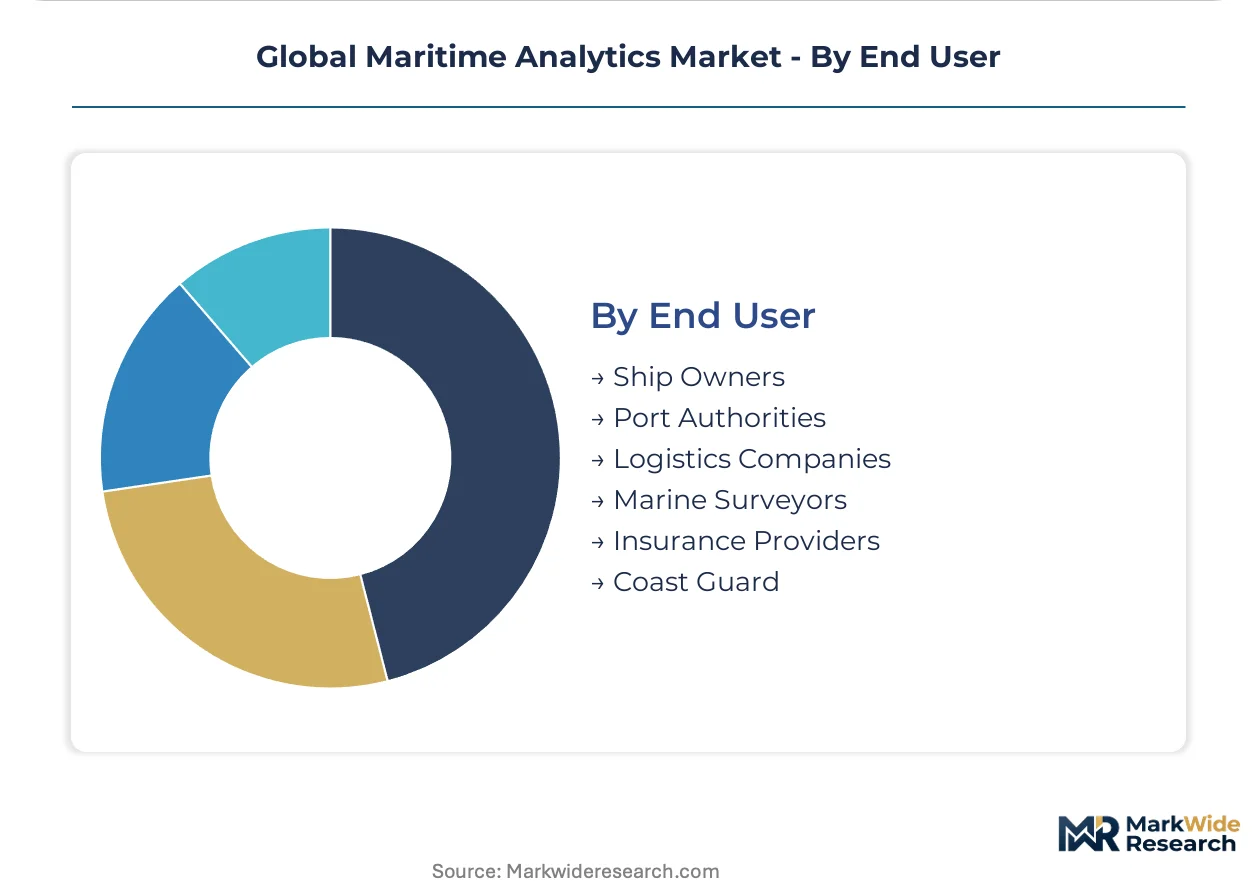
Ship Owners represent the largest addressable base, though Port Authorities are gaining share fastest as terminal automation investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity drives maritime analytics deployment unevenly across trading economies. Nations with high container throughput and stringent environmental enforcement invest earliest in vessel performance monitoring and port optimization systems.
Norway
Kongsberg Gruppen and DNV headquarters anchor a maritime technology cluster specializing in sensor fusion and classification society analytics. The Norwegian Maritime Authority enforces strict emissions documentation for vessels calling at Oslo and Bergen. Stavanger and Trondheim engineering centers supply machine learning talent for hydrodynamic modeling partnerships.
Singapore
The Maritime and Port Authority mandates predictive maintenance adoption for terminal operators managing the world's second-busiest container port. Berth scheduling optimization reduces demurrage exposure for shipping lines transshipping between Asia and Europe. Tuas Port automation investments accelerate edge computing deployments for real-time crane analytics.
Germany
Hamburg and Rotterdam port state control inspections enforce REACH regulation amendments for antifouling coating emissions tracking. German shipowners operating Capesize bulk carriers face steep compliance documentation burdens for EU MRV submissions. The Lloyd's Register and DNV presence in Hamburg creates concentrated demand for certified analytics platforms.
United States
The US Coast Guard cybersecurity directives mandate secure data protection standards for vessels operating in American waters. Port authorities in Los Angeles and Long Beach deploy cargo tracking analytics for supply chain visibility. Houston and New Orleans energy terminals utilize vessel behavior screening for maritime domain awareness.
China
Shanghai and Ningbo-Zhoushan port authorities process the world's highest container volumes, driving demand for fleet management dashboards and route optimization. The Ministry of Transport enforces emissions monitoring for domestic coastal fleets. Qingdao and Dalian shipyards integrate digital twin technology for hull performance monitoring in newbuild contracts.
Global Maritime Analytics Market Competitive Landscape
Listed leaders compete with private specialists across certification credibility and sensor integration depth. The vendor base spans engine manufacturers embedding proprietary algorithms, satellite data providers fusing AIS streams, and classification societies leveraging audit relationships. Three archetypes dominate: heritage engineering groups with propulsion control expertise, AI-native platforms specializing in vessel behavior intelligence, and maritime software incumbents with charter party workflow integration. Competitive moves concentrate on strategic partnerships between sensor hardware vendors and analytics platforms, plus geographic expansion into Singapore and Norway technology clusters.
Within the heritage engineering tier, ABB and Wärtsilä represent manufacturers embedding analytics directly into propulsion systems. Windward exemplifies the AI-native archetype through its positioning in vessel behavior screening for security applications. Kongsberg Gruppen anchors the Nordic cluster with its concentration near DNV headquarters.
| Leading Market Players |
|---|
| ABB |
| Wärtsilä |
| Windward |
| Spire Global |
| Kongsberg Gruppen |
| Kpler |
| MarineTraffic |
| Veson Nautical |
| DNV |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS architectures displacing on-premise legacy installations are simultaneously redrawing supply geography toward Norwegian maritime technology clusters and compressing pricing economics for hardware-embedded solutions. This substitution dynamic concentrates vendor margins in subscription tiers while eroding perpetual-license revenue pools for established engineering groups.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in maritime analytics procurement. Price differentiation hinges on ISO 19848 certification grade and after-sales service bundling with DNV or Lloyd's Register audit support. Cost compression in the economy tier is intensifying because Singapore port authorities are consolidating vendor relationships for berth optimization contracts. Charterers specifying continuous carbon intensity disclosure in Capesize fixtures exhibit the lowest price sensitivity, while mid-size bulk carriers operating mixed-flag fleets demonstrate acute sensitivity to subscription renewal rates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for sensor hardware destined for shipyard integration. Component supply concentrates in Norway, Singapore, and Germany, with Kongsberg Gruppen and DNV anchoring Nordic engineering talent pools. Raw material dependencies span marine-grade sensors, satellite AIS receivers, and edge-computing processors. Single-source vulnerability around polar satellite coverage creates tracking accuracy degradation risks for high-latitude routes. Distribution runs through maritime technology clusters that co-locate classification society offices with specialized engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime analytics is approaching a platform-economics inflection where interoperability between engine OEM telemetry and third-party optimization algorithms determines competitive survival. The convergence of Wärtsilä's embedded analytics with Windward's behavioral intelligence demonstrates this ecosystem shift.
For Market Incumbents: Secure certification pre-approval pathways with Lloyd's Register and DNV ahead of EU MRV enforcement tightening. Incumbent engine manufacturers must deepen backward integration into sensor hardware to defend against AI-native platforms eroding propulsion-control margins through API-based optimization layers. For New Entrants and Emerging Players: ISO 19848 fast-track certification unlocks port authority procurement channels in Singapore and Hamburg where predictive maintenance demand outstrips qualified vendor supply. White-space opportunities concentrate in wind-assisted propulsion optimization algorithms for hybrid fleets and cybersecurity-hardened analytics for US Coast Guard compliance. A channel partnership with classification societies offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed maritime software incumbents holding charter party workflow integration but lacking AI-native vessel behavior capabilities. Long-term viability favors platforms combining sensor fusion depth with regulatory audit relationships. The inflection signal to watch is charter party standard terms mandating real-time analytics access as a fixture precondition rather than optional add-on.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Partnership | DNV or Lloyd's Register alliances accelerate ISO 19848 certification timelines for new platform entrants. |
| Sensor Hardware Backward Integration | Captive marine-grade sensor production secures supply continuity for edge-computing deployments aboard vessels. |
| API-Based Optimization Layer | Open architecture enables third-party algorithm integration without displacing incumbent propulsion control systems. |
| Polar Coverage Satellite Agreement | Specialized AIS provider partnerships close tracking gaps for high-latitude container routes. |
| Cybersecurity Certification Program | US Coast Guard compliance infrastructure creates defensive moats in American port authority procurement. |
Research Methodology
Initial hypotheses were tested against primary input from fleet technical managers, port authority operations directors, classification society surveyors, and maritime software procurement leads and refined through secondary validation. Stakeholder interviews drew from container line superintendents, terminal automation engineers, and chartering desk analysts. Secondary sources encompassed Lloyd's Register and DNV classification filings, EU MRV emissions databases, Singapore Maritime and Port Authority automation disclosures, and customs records for marine sensor trade flows. Bottom-up vessel deployment estimates and top-down market sizing triangulated to convergence thresholds.
Variance decomposition across solution type, deployment architecture, application priority, and end-user procurement complexity shaped the analytical framework. Segmentation dimensions modeled include fuel optimization versus vessel performance modules, cloud-based versus edge-computing installations, regulatory compliance versus predictive maintenance applications, and ship owner versus port authority purchasing patterns. CAGRs derived from fitted growth curves calibrated against historical adoption rates for certified analytics platforms. Forecast inputs incorporated EU MRV enforcement intensity trajectories and charter party clause evolution in Capesize bulk carrier fixtures.
Underlying assumptions cover sustained EU MRV compliance timelines and stable satellite AIS coverage expansion, with deviation risk concentrated in classification society audit requirement fragmentation and maritime data science talent shortages. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Tugboat Operation Market