
 Maritime and Port Operations Emissions Transparency Platforms Market | 2026-2036
Maritime and Port Operations Emissions Transparency Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime and Port Operations Emissions Transparency Platforms Market Insights
The split between premium and commodity tiers is hardening in maritime emissions transparency. RightShip leverages its vessel vetting heritage to dominate carbon risk scoring for bulk charterers. ZeroNorth anchors its position through backward integration into voyage optimization and fuel analytics. CarbonChain differentiates by specializing in supply-chain-linked emissions accounting for cargo owners seeking Scope 3 granularity.
Maritime and port operations emissions transparency platforms are digital systems that aggregate, verify, and report greenhouse gas outputs from vessel operations, cargo handling, and terminal activities using standardized protocols like ISO 14064 and the IMO DCS framework. These platforms ingest Automatic Identification System feeds, IoT sensor networks, and satellite-derived atmospheric measurements to calculate carbon intensity per transport work or port call, then generate audit-ready disclosures for regulators, financiers, and cargo interests. Cloud-based deployments lead current uptake among mid-size fleet operators seeking lower capital barriers, while edge computing architectures are gaining traction among large container lines requiring real-time emissions optimization during voyage execution. Satellite monitoring and AIS data integration form the fastest-growing data layer as constellation providers expand maritime coverage and port authorities mandate automatic berth-to-berth tracking.
The European Maritime Safety Agency enforces EU MRV compliance deadlines that directly shape platform procurement cycles across EU-flagged and EU-calling fleets. The IMO Data Collection System and forthcoming Carbon Intensity Indicator ratings are forcing shipping companies to invest in verified emissions infrastructure or face operational restrictions and charter market exclusion. Stakeholders must monitor how the EU Emissions Trading System maritime inclusion rewrites cost structures and platform ROI calculations for trade lanes touching European ports.
Market Dynamics
The EU Emissions Trading System maritime inclusion is compressing platform procurement timelines as ship operators face carbon cost exposure on every European port call. This regulatory shock is forcing immediate investment in verified emissions infrastructure rather than gradual adoption curves.
Growth Catalysts
- EU MRV enforcement tightening:The European Maritime Safety Agency's verification deadlines are mandating digital emissions tracking for all EU-calling vessels, creating non-negotiable demand for audit-ready platforms.
- Container shipping lines:Major carriers are expanding platform procurement to satisfy charterer carbon disclosure requirements and avoid cargo owner defection to lower-carbon competitors.
- Rotterdam-Antwerp-Hamburg corridor concentration:European green finance rules are tightening fastest in this port cluster, concentrating platform deployment investment and creating reference implementations for adjacent markets.
Market Restraints
- Sensor hardware cost volatility:IoT device and satellite data feed pricing fluctuates with semiconductor supply constraints, squeezing platform provider margins and slowing small-fleet penetration.
- Data provider concentration:AIS and satellite atmospheric monitoring sources cluster among three constellation operators, creating single-point-of-failure risk for platform data layers.
- Legacy system integration friction:Existing vessel management software lacks standardized APIs, forcing expensive custom engineering for emissions data ingestion.
Strategic Opportunities
- IMO Carbon Intensity Indicator preparation:Shipping companies facing operational restrictions under forthcoming CII ratings need verified emissions infrastructure, creating a compliance-driven installation window ahead of enforcement.
- Scope 3 supply chain accounting:Cargo owners are demanding berth-to-berth emissions granularity for Scope 3 disclosures, opening platform extensions beyond vessel operators to cargo interest workflows.
- Edge computing convergence with voyage optimization:Real-time emissions optimization during voyage execution is attracting large container lines seeking fuel cost reduction alongside carbon compliance.
Industry Challenges
- Maritime data science talent scarcity:Platforms struggle to hire specialists capable of fusing AIS feeds, sensor networks, and satellite measurements into audit-grade carbon calculations.
- Certification timeline compression:ISO 14064 verification and IMO DCS framework accreditation processes lag behind regulatory deadlines, creating compliance gaps for early platform adopters.
- Multi-stakeholder data sovereignty disputes:Vessel owners, charterers, and cargo interests conflict over emissions data ownership and disclosure permissions, complicating platform architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime and Port Operations Emissions Transparency Platforms Market |
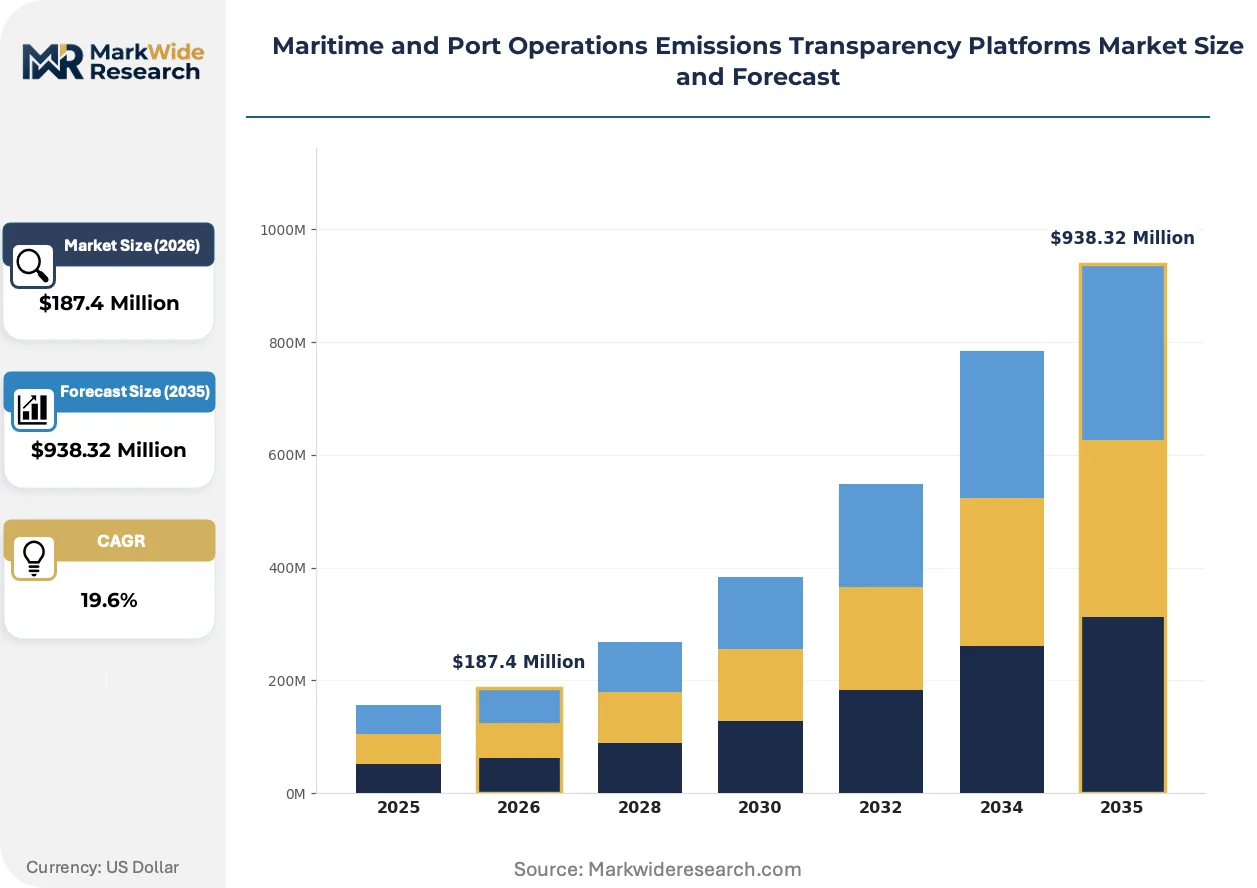
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $938.32 Million |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premise, Hybrid, Edge Computing Emission Source: Vessel Exhaust, Cargo Handling Equipment, Port Vehicles, Terminal Operations, Auxiliary Engines User Category: Fleet Operators, Port Authorities, Environmental Regulators, Shipping Companies, Logistics Providers Data Integration: Satellite Monitoring, IoT Sensors, AIS Data, Weather Analytics, Historical Records |
| Companies Covered | Wilhelmsen Port Services, OrbitMI, RightShip, PortXchange, Marine Digital, SeaIntelligence, CarbonChain, SeaRoutes, ZeroNorth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime and Port Operations Emissions Transparency Platforms Market Trends and Innovations
Emissions transparency technology is fragmenting into specialized layers as buyers reject monolithic platforms in favor of composable systems. This decomposition is enabling faster innovation cycles and sharper competitive differentiation among vendors.
Platform architecture is modularizing around discrete functional blocks—data ingestion, verification engines, and disclosure interfaces—allowing shipping lines to swap components without full system replacement. Mid-size fleet operators are adopting this approach fastest, mixing cloud-based verification from specialized providers with in-house voyage analytics. The structural consequence is compressing vendor lock-in and forcing platform providers to defend position through API interoperability rather than bundled feature depth.
The EU Green Deal's maritime extensions are rewriting cost structures for trade lanes touching European ports, with the EU ETS inclusion creating direct carbon price exposure for ship operators. This policy shock is redirecting platform investment toward real-time cost optimization features rather than retrospective reporting alone. Container lines with heavy Europe-Asia exposure are responding by prioritizing platforms with integrated EUA price forecasting and voyage re-routing algorithms.
Charterer vetting workflows are embedding emissions scoring as a primary selection criterion, displacing traditional safety and reliability metrics in cargo owner procurement decisions. Bulk commodity traders and retail supply chain managers are demanding platform-generated carbon intensity certificates before fixture confirmation. This shift is most visible in the dry bulk sector, where cargo owners with Science Based Targets initiative commitments are screening vessels based on verified CII-equivalent ratings.
Maritime and Port Operations Emissions Transparency Platforms Market Segmentation
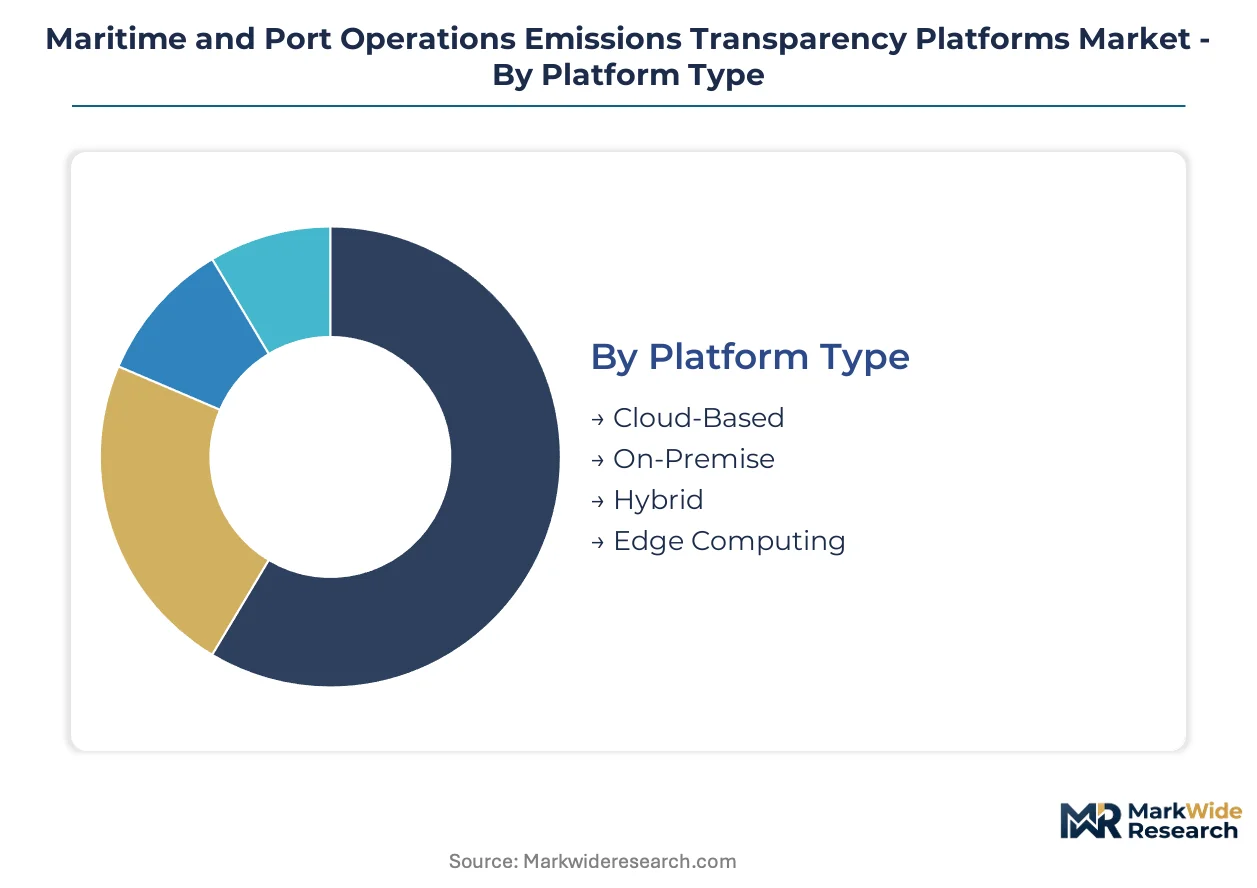
Segmentation in maritime emissions transparency platforms reveals how certification burdens, data sovereignty requirements, and operational scale reshape procurement patterns across vessel operators and port authorities. Buyers select platform architectures based on audit-grade verification needs and real-time optimization demands.
Platform Type:
Cloud-based deployments carry lighter ISO 14064 certification overhead for mid-size fleets, while edge computing architectures face stricter IMO DCS framework validation for real-time voyage optimization.
- Cloud-Based:Multi-tenant SaaS architectures with API-first data ingestion reduce capital barriers for mid-size fleet operators. Rotterdam-Antwerp-Hamburg corridor ports favor these deployments for rapid EU MRV compliance without on-site infrastructure. Demand concentrates among container lines with Europe-Asia exposure seeking lower upfront platform investment.
- Edge Computing:Distributed processing nodes aboard vessels enable real-time emissions optimization during voyage execution. Large container lines deploy these systems for fuel cost reduction alongside carbon compliance, requiring rigorous IMO DCS framework accreditation for audit-grade outputs.
- On-Premise:Dedicated server installations within port authority data centers satisfy data sovereignty mandates for sensitive vessel tracking information.
- Hybrid:Split architectures combine cloud-based reporting with edge-based voyage analytics to balance compliance and optimization needs.
Leading the category by volume: Cloud-Based. Expanding most quickly: Edge Computing.
Emission Source:
Cost tiers stratify sharply across emission sources, with vessel exhaust monitoring commanding premium platform pricing due to satellite data feed dependencies and complex fuel-type differentiation.
- Vessel Exhaust:Stack emissions monitoring integrates Automatic Identification System feeds with satellite-derived atmospheric measurements to calculate carbon intensity per transport work. Charterer vetting workflows embed these metrics as primary selection criteria, displacing traditional safety metrics in cargo owner procurement decisions.
- Terminal Operations:Shore-side power consumption and cargo crane electrification tracking require berth-to-berth granularity for Scope 3 supply chain disclosures. Cargo owners with Science Based Targets initiative commitments demand platform-generated certificates before fixture confirmation.
- Cargo Handling Equipment:Rubber-tired gantry crane and straddle carrier emissions tracking focuses on diesel-to-electric transition monitoring.
- Port Vehicles:Harbor craft and pilot boat fuel consumption analytics support port authority decarbonization mandates.
- Auxiliary Engines:At-berth generator and boiler emissions monitoring ensures compliance with port air quality regulations.
Dominating procurement spend: Vessel Exhaust. Gaining share fastest: Terminal Operations.
User Category:
Application maturity varies dramatically, with fleet operators deploying full-stack platforms while environmental regulators concentrate on verification engine procurement for audit oversight.
- Fleet Operators:Integrated platform deployments spanning data ingestion, verification engines, and disclosure interfaces dominate procurement among EU-flagged and EU-calling fleets facing EU ETS maritime inclusion cost exposure.
- Port Authorities:Automatic berth-to-berth tracking mandates drive investment in IoT sensor networks and satellite monitoring integration for emissions oversight within regulated port zones.
- Shipping Companies:IMO Carbon Intensity Indicator preparation creates compliance-driven installation windows for verified emissions infrastructure ahead of operational restriction enforcement.
- Environmental Regulators:Audit-grade platform procurement focuses on ISO 14064 verification engine access for third-party emissions validation.
- Logistics Providers:Multi-modal emissions tracking requirements drive demand for supply-chain-linked accounting extensions.
Representing the largest addressable base: Fleet Operators. Climbing fastest: Port Authorities.
Data Integration:
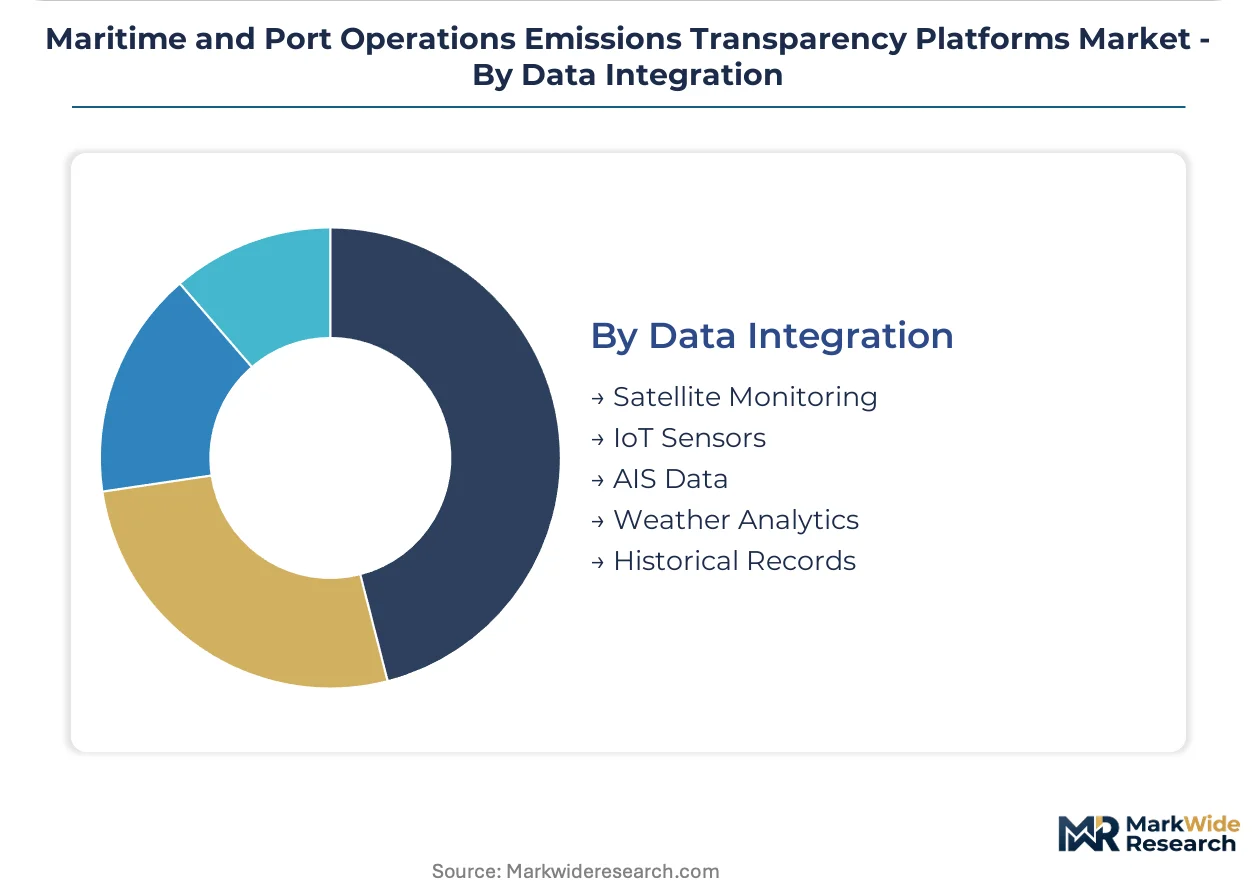
Supply concentration among three constellation operators creates single-point-of-failure risk for satellite-dependent platform architectures, reshaping buyer due diligence on data layer resilience.
- Satellite Monitoring:Constellation-derived atmospheric measurements and synthetic aperture radar tracking form the fastest-growing data layer as maritime coverage expands. Platform providers face margin pressure from semiconductor supply constraints affecting sensor hardware costs.
- AIS Data:Automatic Identification System feeds provide vessel position, speed, and draft information for transport work calculations. Three constellation operators dominate sourcing, creating concentration risk for platform data layers.
- IoT Sensors:Fuel flow meters, engine performance monitors, and exhaust gas analyzers deliver direct emissions measurement for audit-grade verification.
- Weather Analytics:Sea state and routing optimization data enables voyage re-routing algorithms for fuel cost reduction.
- Historical Records:Retroactive emissions baselining supports Science Based Targets initiative commitment verification for cargo owners.
Commanding the largest data spend: Satellite Monitoring. Steepest expansion trajectory: AIS Data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors platform deployment investment as the EU ETS maritime inclusion compresses procurement timelines for Europe-Asia trade lanes.
Germany
Hamburg's port authority mandates automatic berth-to-berth tracking for all container vessels, driving demand for satellite-AIS integration. The country's national maritime regulator enforces strict EU MRV verification deadlines. Platform providers concentrate engineering resources in the Hamburg metropolitan region to serve North Sea container traffic.
Netherlands
Amsterdam-based charterers embed emissions scoring as primary vetting criteria for dry bulk fixtures. The EU Green Deal's maritime extensions rewrite cost structures for Dutch-flagged operators. Rotterdam-Antwerp corridor ports deploy cloud-based verification systems as reference implementations for adjacent Baltic markets.
United Kingdom
London marine insurers demand audit-grade carbon intensity certificates for hull coverage renewals. The country's financial conduct authority aligns green finance rules with EU CSRD disclosure standards. Thames estuary terminals invest in IoT sensor networks for shore-side power consumption tracking.
Singapore
Maritime and Port Authority mandates digital emissions reporting for all bunker suppliers from 2025. The city-state's trade finance hub status attracts platform providers seeking Asia-Pacific headquarters. Tuas mega-port construction integrates edge computing architectures for real-time voyage optimization.
United States
California Air Resources Board enforces at-berth auxiliary engine emissions rules for Los Angeles-Long Beach container traffic. The EPA monitors vessel exhaust under federal clean air statutes. Pacific Northwest ports pilot satellite-derived atmospheric measurement integration for carbon intensity verification.
Maritime and Port Operations Emissions Transparency Platforms Market Competitive Landscape
Capital-heavy platform developers compete with asset-light verification specialists for maritime emissions transparency contracts. The vendor base stratifies around certification depth and data layer control. Three archetypes dominate: vessel vetting heritage players, voyage optimization integrators, and supply-chain accounting specialists. Consolidation pressure intensifies as charterers demand bundled carbon risk scoring with fixture workflows, forcing acquisition activity among mid-tier verification engine providers.
Within the supply-chain-linked accounting tier, CarbonChain exemplifies Scope 3 granularity specialization for cargo owners. RightShip occupies a position anchored in bulk charterer carbon risk scoring heritage. ZeroNorth represents backward integration convergence between voyage optimization and fuel analytics. These three companies illustrate how competitive differentiation hardens around distinct data layer advantages rather than generic platform breadth.
| Leading Market Players |
|---|
| Wilhelmsen Port Services |
| RightShip |
| PortXchange |
| Marine Digital |
| SeaIntelligence |
| CarbonChain |
| SeaRoutes |
| ZeroNorth |
Pricing and Supply Chain Analysis
Charterer carbon disclosure mandates are compressing procurement timelines for verified emissions infrastructure, forcing platform providers to absorb semiconductor cost volatility while maintaining audit-grade service tiers. This demand shock is reshaping how vendors structure pricing across certification levels and data source dependencies.
Pricing Analysis
Outcome-based pricing anchored to verified emissions reductions dominates contract structures, with platform fees scaling against carbon cost savings achieved through voyage optimization. Pricing stratifies across ISO 14064 certification tiers, with premium audit-ready platforms commanding multiples over basic reporting modules. Cost compression in the mid-market segment is intensifying because IoT sensor hardware prices fluctuate with semiconductor supply constraints. Small-fleet operators exhibit highest price sensitivity, while large container lines prioritize certification depth over per-seat costs.
Supply Chain Analysis
Satellite atmospheric measurement feeds rest on constellation operators concentrated in the United States, France, and Canada, creating concentrated dependency for platform data layers. AIS transponder hardware, exhaust gas analyzers, and fuel flow meters constitute critical component inputs. Single-source vulnerability in satellite data sourcing represents the dominant structural risk. Distribution runs through direct enterprise sales to fleet operators and port authorities, with systems integrators serving mid-size shipping companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU ETS maritime inclusion has transformed emissions transparency into a cost-of-compliance imperative, erecting regulatory moats that favor platform providers with pre-existing IMO DCS framework accreditation.
For Market Incumbents: Anticipate charterer demand for bundled carbon risk scoring with fixture workflows by deepening API interoperability with voyage optimization systems. Consolidation pressure from cargo owners seeking Science Based Targets initiative alignment favors acquisition of specialized verification engine providers. Backward integration into satellite data partnerships offers defensive control over margin-critical input costs. For New Entrants and Emerging Players: Dry bulk charterers with limited digital procurement infrastructure represent the most penetrable buyer archetype, as vetting workflows in this segment lag container shipping sophistication. Port authorities in secondary European corridors offer white-space deployment opportunities with lighter competitive intensity. A go-to-market angle emphasizing rapid EU MRV compliance without legacy system replacement addresses immediate procurement pain points. For Investors and Strategic Acquirers: The window for entry favors verification engine specialists with ISO 14064 accreditation depth over generic platform developers. Long-term viability hinges on data layer control and regulatory certification moats rather than feature breadth. Watch for EU Emissions Trading System allowance price volatility as the inflection indicator for platform ROI calculations and enterprise procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IMO DCS Framework Accreditation | Regulatory pre-qualification compresses sales cycles for EU-calling fleets facing ETS exposure. |
| Satellite Data Partnership | Direct constellation agreements reduce single-source vulnerability and stabilize input cost structures. |
| Edge Computing Architecture Deployment | Real-time voyage optimization attracts large container lines seeking fuel cost reduction alongside compliance. |
| Scope 3 Supply Chain Extension | Cargo owner workflows for Science Based Targets initiative disclosures open platform monetization beyond vessel operators. |
| API-First Platform Modularization | Composable system architectures reduce vendor lock-in and accelerate mid-size fleet adoption curves. |
Research Methodology
Document review covered EU MRV regulatory filings, IMO DCS framework technical guidelines, and port authority procurement records, complemented by interviews with fleet operations directors, maritime sustainability officers, port authority IT managers, and classification society verification specialists. Secondary sources included EMSA compliance databases, Lloyd's List intelligence reports, and customs data on sensor hardware trade flows. Bottom-up vessel fleet segmentation was cross-referenced against top-down market sizing from platform provider revenue disclosures.
Historical adoption curves for emissions monitoring technology were cross-referenced against panel input from procurement leads at container lines and bulk operators. Segmentation modeling spanned platform deployment architecture, emission source category, user type, and data integration method across the projection horizon. CAGRs were derived from regression analysis of regulatory enforcement timelines and charterer vetting workflow evolution. Forecast inputs incorporated EU ETS allowance price trajectories and satellite constellation coverage expansion schedules.
Revisions become necessary when regulatory enforcement deadlines shift, charterer carbon scoring methodologies change, or satellite data feed pricing experiences structural breaks. Forecasts reflect assumptions about continued EU MRV tightening and IMO CII rating enforcement without delay. A small set of named triggers—EU ETS maritime allowance price spikes, new port authority automatic tracking mandates, and consolidation among constellation operators—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Integrated Marine Automation System Market