
 Mooring Buoy Market | 2026-2036
Mooring Buoy Market Size, Share, and Industry Trends Forecast 2026-2036
Mooring Buoy Market Intelligence
The integration of real-time monitoring services, often sold as subscriptions, is rebalancing the value proposition from a one-time product sale to ongoing operational support. Trelleborg Marine Systems leverages its extensive material science expertise to offer durable, high-performance solutions for harsh environments. James Fisher and Sons plc specializes in integrated marine services, including buoy deployment and maintenance. Sealite differentiates with its focus on navigation aids and self-contained solar-powered lighting systems integrated into its buoy products.
A mooring buoy is a floating device anchored to the seabed, engineered to secure vessels and other marine structures. These buoys are constructed from materials like steel or polyethylene and are designed to withstand specific tensile loads and environmental conditions. Within applications, offshore platforms and ports and harbors constitute the largest segments due to high asset value and safety requirements. Foam-filled and synthetic mooring buoys are gaining share over traditional steel models, driven by lower maintenance needs and improved buoyancy characteristics.
Product design and testing are governed by standards from organizations like the International Organization for Standardization (ISO) and guidelines from national maritime authorities. Environmental regulations, such as those from the U.S. Environmental Protection Agency (EPA) concerning material leaching, also influence material selection and buoy coatings. The key decision for operators is balancing the higher initial cost of advanced synthetic and smart buoys against their long-term total cost of ownership benefits.
Market Dynamics
The primary force shaping the mooring buoy market is the re-evaluation of total cost of ownership. This calculation now prioritizes the lower maintenance of advanced synthetic materials over traditional steel's lower initial price.
Growth Catalysts
- Aquaculture Sector Growth:The expansion of fish and seaweed farming requires specialized mooring systems for large-scale farm grids, particularly in Southeast Asia.
- Port Infrastructure Investment:Modernization of ports and harbors in developing nations necessitates new mooring buoys to support increased vessel traffic and safety standards.
- Offshore Renewable Energy:Floating wind and solar platforms create a new application requiring high-performance mooring solutions engineered for harsh deepwater conditions.
Market Restraints
- High Capital Expenditure:The higher initial cost for advanced synthetic buoys versus steel is a primary adoption barrier for smaller operators.
- Material Degradation Concerns:Long-term performance uncertainty of HDPE from UV radiation and biofouling complicates lifecycle cost assessments.
- Logistical Complexity:Deployment in harsh environments requires specialized vessels and expertise, increasing total project costs for offshore operators.
Strategic Opportunities
- Data-as-a-Service Models:Offering subscription access to real-time data from smart buoys, such as tension monitoring, creates new recurring revenue.
- Environmental Monitoring Integration:Incorporating sensors for water quality or pollution detection meets demand from research institutes and regulatory bodies.
- Circular Economy Materials:Developing buoys from recycled polymers provides a competitive edge with customers adhering to sustainability mandates.
Industry Challenges
- System Integration Complexity:Ensuring smart buoy data compatibility with diverse port management software is a primary technical hurdle.
- Interoperability Gaps:A lack of universal standards for data formats hinders integration between different manufacturers' smart buoy systems.
- Specialized Talent Shortage:A deficit of technicians skilled in both marine engineering and data analytics impedes advanced system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mooring Buoy Market |
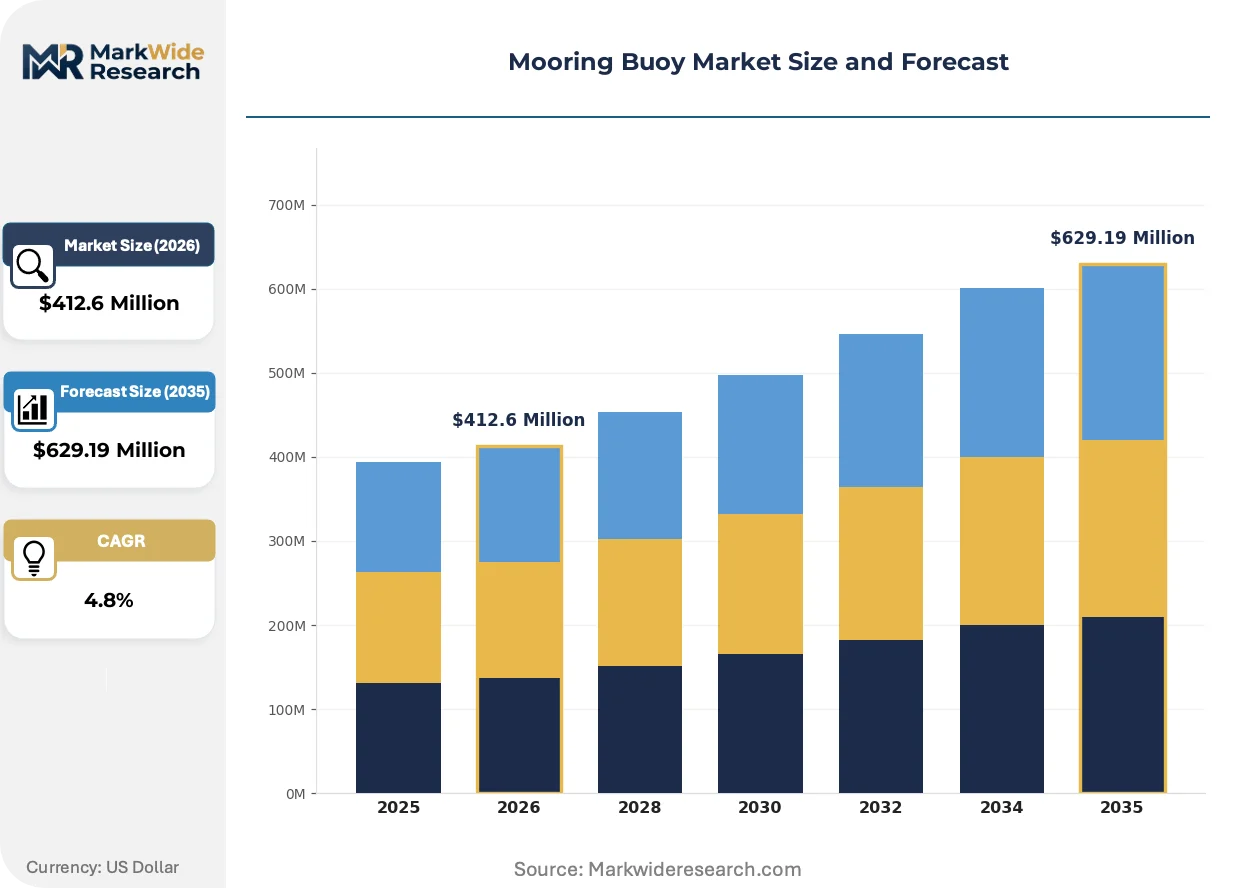
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Mooring Buoy, Synthetic Mooring Buoy, Pneumatic Mooring Buoy, Foam Filled Mooring Buoy Material: Polyethylene, Steel, Rubber, HDPE, Aluminum Application: Marine Transportation, Offshore Platforms, Ports and Harbors, Aquaculture, Coastal Monitoring End User: Shipping Companies, Offshore Service Providers, Port Authorities, Coastal Research Institutes |
| Companies Covered | Trelleborg Marine Systems, FBM Hudson, Sealite, James Fisher and Sons plc, Eval Marine, Steinsvik, Fendercare Marine, Poralu Marine, Colligo Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mooring Buoy Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of mooring buoys from passive anchors into active, data-generating nodes. This shift alters the product's value proposition from a one-time sale to ongoing operational support.
Integrated sensor packages with IoT connectivity provide real-time data on mooring line tension, buoy position, and weather. Offshore energy operators and major port authorities are primary adopters, seeking to improve safety. This technology is automating manual inspections and enabling predictive maintenance based on live performance data.
International standards from ISO for mooring equipment are being updated to include guidelines for synthetic materials. Concurrently, environmental rules from the U.S. EPA and Europe's ECHA scrutinize material leaching. This forces manufacturers to invest in verifiable material testing, especially for foam-filled buoys.
End-users are favoring service agreements that bundle the buoy with installation, maintenance, and data into a single operational expense. This "Mooring-as-a-Service" model disrupts the traditional capital sale, favoring suppliers with strong service capabilities. The model is gaining traction in Europe's offshore wind sector.
Mooring Buoy Market Segmentation
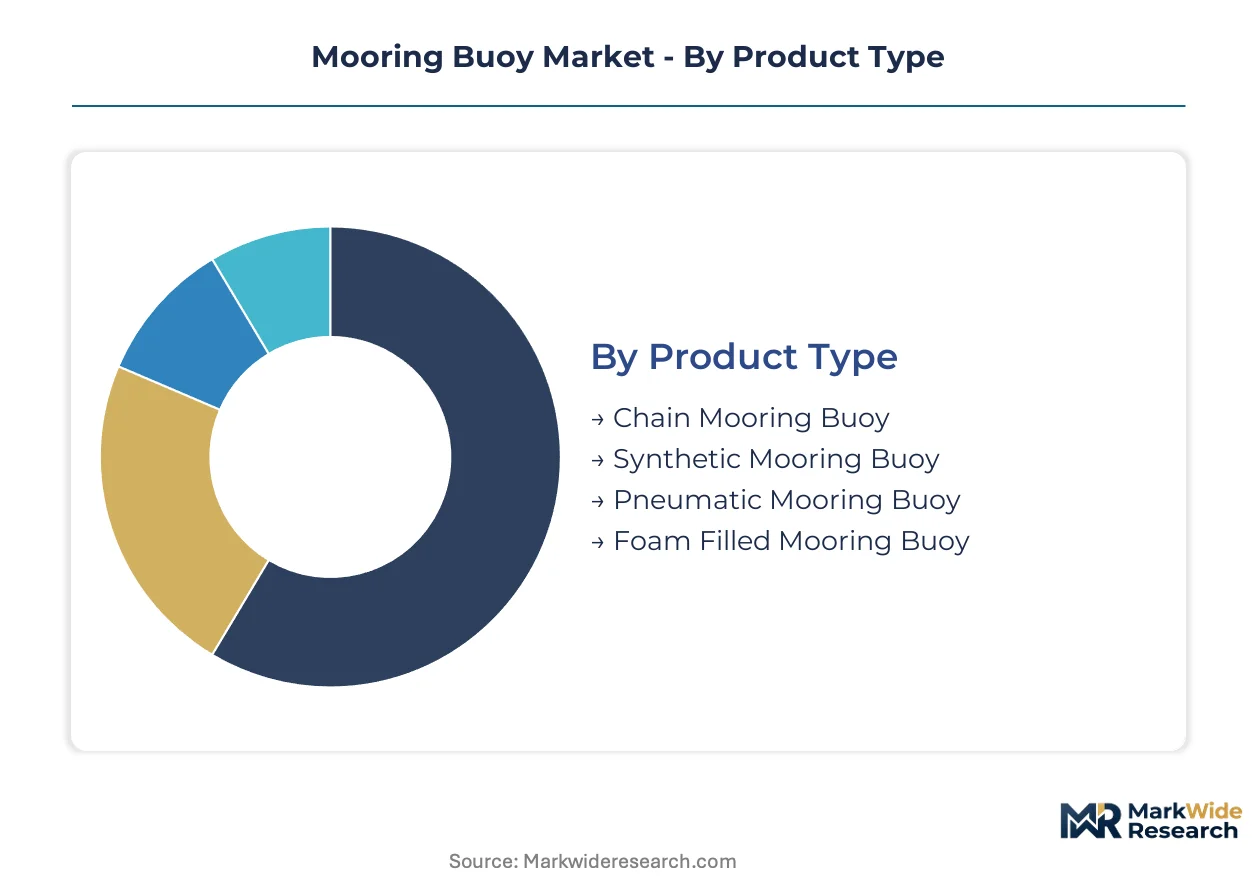
Segmentation analysis provides a critical framework for understanding the diverse demands and operational nuances within the mooring buoy market. This granular perspective allows manufacturers and service providers to tailor product development, refine market strategies, and identify high-growth opportunities across various end-use sectors.
Product Type:
Product type segmentation highlights how design and material choices influence the regulatory approvals required, such as those from national maritime authorities for navigation aids or ISO standards for structural integrity.
- Synthetic Mooring Buoy:These buoys utilize advanced polymers for lighter weight and improved durability, offering superior resistance to corrosion and biofouling. Demand concentrates in offshore renewable energy projects, where their reduced maintenance requirements offset higher initial costs.
- Foam Filled Mooring Buoy:Consisting of an inner foam core encased in a robust outer shell, these buoys offer exceptional buoyancy and puncture resistance, making them virtually unsinkable. Port authorities and offshore platforms favor them for critical applications due to their inherent safety features.
- Chain Mooring Buoy:Traditional buoys relying on heavy chain for anchoring, primarily used in established port and harbor operations for vessel securing.
- Pneumatic Mooring Buoy:Inflatable buoys providing high buoyancy and shock absorption, often deployed for temporary mooring or ship-to-ship transfers.
Chain Mooring Buoy sits at the top of the volume ranking, with Foam Filled Mooring Buoy climbing the fastest.
Material:
Material segmentation reveals distinct cost structures and performance characteristics, ranging from economical traditional options to premium advanced composites.
- HDPE:High-Density Polyethylene offers excellent impact resistance, UV stability, and reduced biofouling, significantly extending product lifecycle. Southeast Asian nations prioritize HDPE buoys for new port developments due to their long-term cost benefits.
- Steel:Robust and cost-effective for high-tensile load applications, steel remains a primary material for large-scale mooring systems. Offshore platforms often specify steel buoys for their proven strength and durability in harsh conditions.
- Polyethylene:A versatile polymer providing good buoyancy and corrosion resistance, suitable for a range of general-purpose mooring applications.
- Rubber:Used for fender buoys and shock-absorbing elements, rubber offers elasticity and protection against impact.
- Aluminum:Lightweight and corrosion-resistant, aluminum is chosen for specialized applications requiring portability or reduced structural load.
Demand for Steel is driven by its cost-effectiveness, while HDPE sees growth due to its advanced properties.
Application:
Application segmentation illustrates how diverse operational requirements dictate specific buoy designs and performance criteria.
- Offshore Platforms:Mooring buoys for offshore platforms must withstand extreme weather conditions and maintain precise station-keeping for critical infrastructure. Operators require high-performance solutions with real-time monitoring to ensure safety and operational continuity.
- Ports and Harbors:These applications demand robust buoys for vessel guidance, berthing, and navigational aids within busy waterways. Modernization projects in developing nations, particularly in Southeast Asia, drive new demand for these systems.
- Aquaculture:Specialized mooring systems secure large-scale fish and seaweed farms, particularly in coastal regions and protected waters.
- Marine Transportation:Buoys support various aspects of marine transport, including channel marking, temporary anchorage, and emergency response.
- Coastal Monitoring:Integration of environmental sensors into buoys supports research institutes and regulatory bodies for water quality and climate data collection.
The largest segment remains Ports and Harbors, with Aquaculture exhibiting significant expansion.
End User:
End user segmentation highlights the varied procurement patterns and service expectations across different operational entities.
- Port Authorities:These entities manage port infrastructure and navigation, requiring durable, compliant buoys for safe vessel movement and berthing. Their procurement often includes maintenance contracts and smart buoy integration for operational efficiency.
- Offshore Service Providers:Companies supporting offshore energy and exploration rely on high-performance mooring buoys for platform stability and operational safety. They prioritize solutions that offer reliability and advanced monitoring capabilities in deepwater environments.
- Shipping Companies:These operators utilize mooring buoys for vessel anchorage, cargo transfer, and temporary berthing in various maritime locations.
- Coastal Research Institutes:Research bodies deploy buoys equipped with sensors for environmental data collection and scientific studies in marine ecosystems.
Operational safety drives demand from Offshore Service Providers, while environmental mandates influence Coastal Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States focuses on advanced monitoring for offshore energy, Indonesia prioritizes port modernization and aquaculture expansion. The United Kingdom drives demand for sophisticated mooring in offshore wind, contrasting with China's rapid port infrastructure and extensive aquaculture needs. Vietnam also sees significant expansion in its aquaculture sector and port developments.
United States
Offshore energy platforms and coastal monitoring initiatives drive significant demand for advanced mooring buoys. U.S. EPA regulations concerning material leaching influence the selection of environmentally compliant buoy materials. The Gulf Coast region, particularly around Houston, harbors substantial demand for robust mooring solutions supporting oil and gas operations.
Indonesia
Extensive port development projects and a rapidly expanding aquaculture sector necessitate new mooring buoy installations. National maritime authorities implement rigorous safety standards for new port infrastructure and vessel management. Major port cities like Jakarta and Surabaya drive significant procurement for increased vessel traffic management systems.
United Kingdom
Offshore wind farm expansion and marine research initiatives generate demand for high-performance and smart mooring solutions. ECHA guidelines on chemical substances affect buoy material composition and manufacturing processes. The North Sea region sees substantial investment in high-performance mooring for renewable energy installations and associated infrastructure.
China
Rapid port infrastructure growth and large-scale aquaculture projects are primary demand drivers for mooring buoys. MIIT policies support domestic manufacturing and technological upgrades for advanced marine equipment. Coastal provinces such as Guangdong and Zhejiang are hubs for both port expansion and extensive fish farming operations.
Vietnam
Expanding aquaculture operations and new port and harbor developments create consistent demand for specialized mooring systems. The country's national maritime authority enforces standards for safe navigation and coastal protection. Key coastal areas like Da Nang and Hai Phong require specialized mooring for growing fishing fleets and commercial shipping.
Mooring Buoy Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting a moderately fragmented market. Solution providers concentrate on high-performance materials or integrated marine services. Navigation aid specialists also carve out distinct positions. Companies pursue strategic partnerships to offer comprehensive solutions and diversify portfolios with advanced monitoring technologies.
Specialists in integrated marine services, James Fisher and Sons plc, exemplify the trend towards comprehensive operational support. Trelleborg Marine Systems occupies a position defined by material science expertise, delivering durable, high-performance solutions for demanding environments. Sealite represents an archetype focused on navigation aids, integrating self-contained solar-powered lighting systems directly into its buoy products. These players highlight the industry's shift from simple product sales to value-added services and technological differentiation.
| Leading Market Players |
|---|
| Trelleborg Marine Systems |
| FBM Hudson |
| Sealite |
| James Fisher and Sons plc |
| Eval Marine |
| Steinsvik |
| Fendercare Marine |
| Poralu Marine |
| Colligo Marine |
| Others |
Cost & Logistics Intelligence
Specialized technician expertise in marine engineering and data analytics in Europe's offshore wind sector drives higher pricing for smart buoy service agreements. This labor-cost differential contributes to distinct pricing tiers for advanced operational support.
Pricing Analysis
Capacity additions in Southeast Asian HDPE manufacturing are reshaping price floors for general-purpose buoys. The market operates on a hybrid model combining per-unit transactional sales for traditional buoys with subscription-based services for smart systems. Price differentiation stems from material science expertise and integrated real-time monitoring capabilities. Pricing pressure stems from competition with traditional steel models. Smaller operators are highly price-sensitive, while offshore energy operators exhibit lower sensitivity for advanced solutions.
Supply Chain Analysis
HDPE and steel raw material supply relies on major chemical producers in China and Southeast Asian nations. The mooring buoy supply chain draws heavily from specialized component manufacturers for integrated sensor packages. Single-source vulnerability for critical electronic components presents a structural risk. Distribution runs through a mix of branded specialists offering comprehensive marine services and contract manufacturers for standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mooring buoy market functions as a stable compounder, driven by consistent infrastructure investment in port modernization and offshore energy projects. This foundational demand ensures predictable, long-term growth across various applications.
For Market Incumbents: To counter material degradation concerns and interoperability gaps, incumbents must deepen R&D into advanced polymer formulations and actively participate in developing open data standards for smart buoys. Investing in ISO certification for synthetic materials reinforces product lifecycle claims. Strategic partnerships with software providers can integrate smart buoy data seamlessly into diverse port management systems.
For New Entrants and Emerging Players: Launch via specialized service agreements targeting the rapidly expanding aquaculture sector in Southeast Asian nations. Focus on developing buoys from recycled polymers to align with sustainability mandates, offering a competitive edge. Integrate environmental monitoring sensors to attract research institutes and regulatory bodies, tapping into a niche demand for water quality data.
For Investors and Strategic Acquirers: Offshore service providers are the most active acquirers in this space, seeking to expand integrated offerings. The market presents long-term viability due to the shift towards lower total cost of ownership for advanced synthetic and smart buoys. Prioritize acquisition targets with strong service capabilities and proprietary real-time monitoring technologies. Increased adoption of the "Mooring-as-a-Service" model serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D Investment | Enhances product lifecycle and reduces maintenance for offshore energy operators. |
| "Mooring-as-a-Service" Expansion | Transforms revenue models from one-time sales to recurring operational support for port authorities. |
| Environmental Sensor Integration | Meets demand from coastal research institutes for water quality and climate data. |
| Strategic Alliances for Data Integration | Addresses system integration complexity with diverse port management software. |
| Specialized Technician Training Programs | Mitigates the talent shortage in marine engineering and data analytics. |
Research Approach
Direct dialogue with port authorities, offshore service providers, aquaculture farm managers, and material scientists informed primary insights. This qualitative data was validated against secondary sources including ISO standards, U.S. EPA regulations, and national maritime authority reports. A rigorous process of bottom-up data collection and top-down market sizing ensured comprehensive analysis.
The quantitative model produced detailed volume and value projections across the analysis window. Segmentation dimensions included product type, material, application, end-user, and buoy load capacity. Compound annual growth rates were derived from historical trends and projected growth catalysts. Forecast inputs integrated global port development plans and offshore renewable energy project pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen geopolitical disruptions. Forecasts reflect specific assumptions regarding material science breakthroughs and evolving environmental regulations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Integrated Marine Automation System Market