
 Saudi Arabia Offshore Support Vessel (OSV) Market | 2026-2036
Saudi Arabia Offshore Support Vessel (OSV) Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Offshore Support Vessel (OSV) Market Analysis
Buyer concentration among Saudi Aramco and its tier-one contractors is realigning procurement toward long-term charter agreements with performance-linked terms. Maersk AS leverages its integrated logistics platform to anchor multi-year contracts across Saudi offshore fields. Zamil Offshore competes through localized maintenance capabilities and proximity to Jubail port infrastructure. Tidewater Inc. specializes in high-specification anchor handling tug supply vessels for deepwater operations.
Offshore support vessels are purpose-built marine craft typically ranging from 50 to 120 meters in length, equipped with dynamic positioning systems and deck cargo capacities exceeding 1,000 tonnes, designed to transport personnel, supplies, and equipment to offshore oil and gas installations. Platform supply vessels dominate vessel type deployment due to their versatility in dry and liquid cargo transfer to fixed platforms. Anchor handling tug supply units command premium charter rates given their critical role in mobile offshore drilling unit positioning. Contract-based deployment models are gaining preference over spot chartering as operators seek cost predictability across multi-year field development cycles.
SFDA maritime safety standards and the Saudi Maritime Code govern vessel certification, crew qualifications, and environmental compliance for operations in Saudi territorial waters. The General Authority of Ports (Mawani) regulates port access and berth allocation, directly influencing fleet utilization rates and operational scheduling. Stakeholders must monitor regulatory alignment between Saudi standards and International Maritime Organization conventions as the Kingdom expands local content requirements for offshore fleet procurement.
Market Dynamics
Long-term charter agreements with performance-linked terms are consolidating procurement power among Saudi Aramco and its tier-one contractors, compressing spot market liquidity and forcing fleet operators to absorb utilization risk.
Growth Catalysts
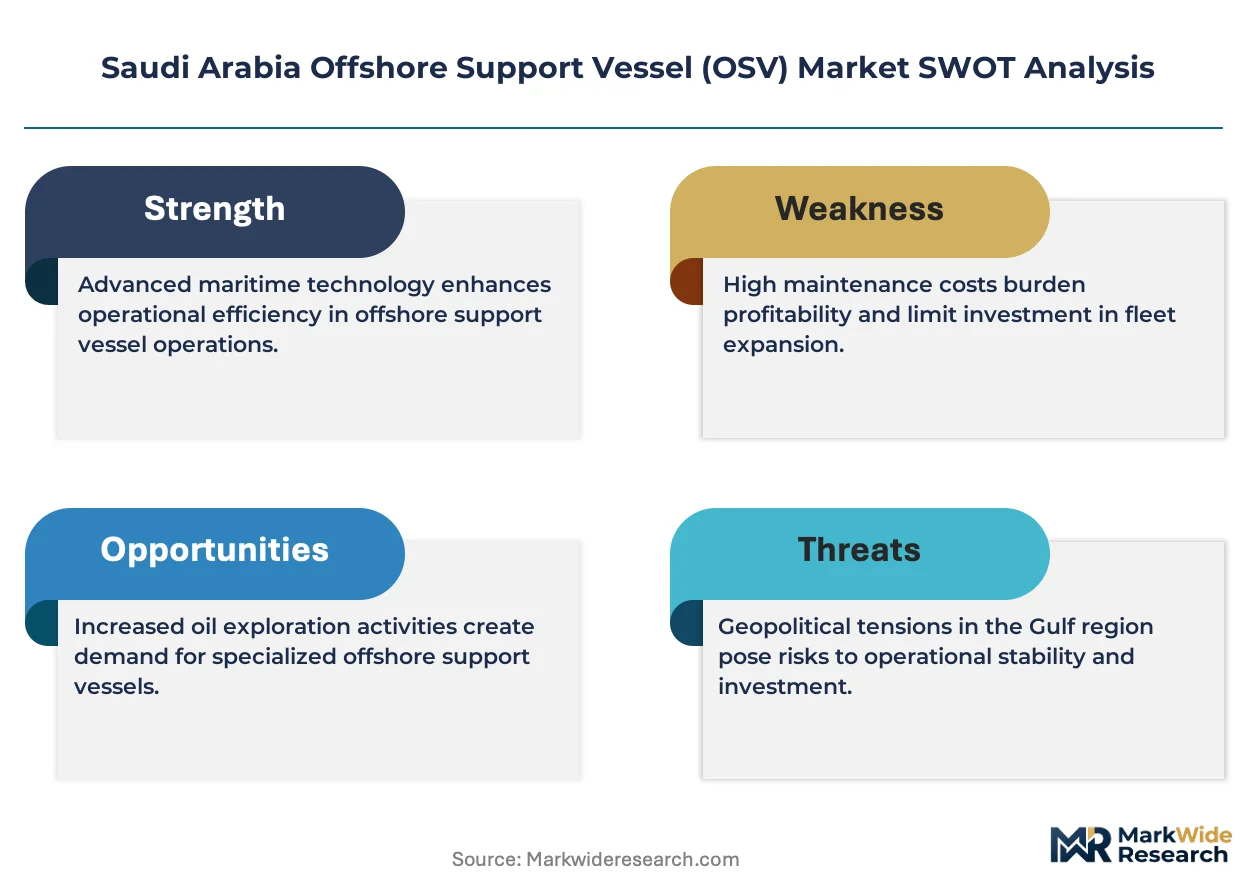
- SFDA Maritime Safety Protocols:Tightened vessel certification requirements under amended Saudi Maritime Code standards are accelerating fleet modernization cycles and creating replacement demand for compliant assets.
- Ras Tanura Cluster Expansion:Concentrated offshore oilfield development around Saudi Arabia's eastern energy corridor is generating sustained demand for platform supply vessels and anchor handling capabilities.
- Dynamic Positioning System Adoption:Advanced DP-2 and DP-3 class vessels are displacing legacy equipment in deepwater operations, requiring operators to upgrade technical specifications.
Market Restraints
- Steel Plate Input Volatility:Hull construction material costs fluctuate with commodity markets, squeezing newbuild margins for domestic shipyards serving the offshore fleet.
- Jubail Port Infrastructure Concentration:Heavy reliance on single-hub maintenance and berthing capacity creates operational bottlenecks during peak demand periods.
- Crew Qualification Scarcity:SFDA-mandated certification timelines extend officer deployment lead times, constraining available vessel operating hours.
Strategic Opportunities
- Red Sea Field Development:Unexploited offshore blocks along Saudi Arabia's western coastline offer greenfield charter potential as exploration activity expands beyond Arabian Gulf concentrations.
- Hybrid Propulsion Convergence:Battery-diesel hybrid systems combined with shore power connectivity enable emission reduction compliance while maintaining operational range.
- Local Content Mandates:Saudi Vision 2030 procurement preferences for in-country value creation incentivize joint ventures between international operators and domestic maintenance providers.
Industry Challenges
- Marine Engineer Skill Gap:Specialized training for high-specification vessel systems lags fleet expansion, forcing operators to recruit from international labor pools.
- SFDA Certification Timelines:Extended approval processes for modified vessel configurations delay redeployment and compress effective charter windows.
- Legacy Fleet Integration:Retrofitting older platform supply vessels with emissions control equipment creates technical compatibility conflicts with existing deck layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Offshore Support Vessel (OSV) Market |
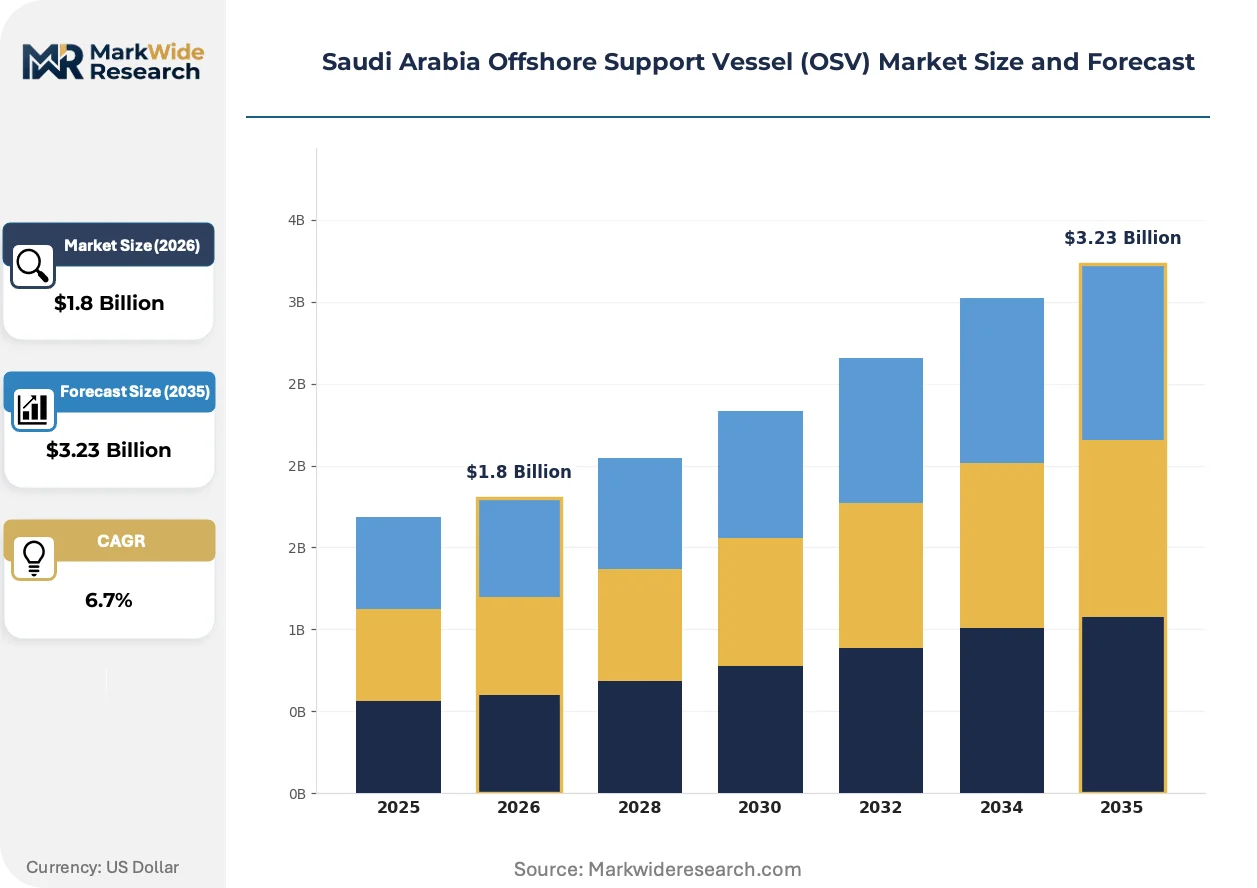
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Platform Supply Vessel, Anchor Handling Tug Supply, Multipurpose Support Vessel, Security Vessel Service Type: Logistics Support, Crew Transportation, Cargo Handling, Maintenance Services End User: Energy Companies, Marine Contractors, Government Agencies, Research Institutions Deployment Model: Charter, Owning, Leasing, Contract-based |
| Companies Covered | Bumi Armada, Maersk AS, Zamil Offshore, Baltic Marine Services LLC, Bourbon Corporation SA, SEACOR Marine, VM Marine, International Maritime Industries, Tidewater Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Offshore Support Vessel (OSV) Market Emerging Trajectories
Hybrid propulsion architectures and digital fleet management systems are actively displacing conventional diesel-mechanical designs across Saudi Arabia's offshore support fleet, driven by charterer emission reduction mandates and operational cost optimization priorities.
Battery-hybrid powertrains with shore charging capability are electrifying vessel auxiliary loads and harbor maneuvering operations. Saudi Aramco's tier-one contractors are specifying hybrid-ready specifications in new charter tenders issued since 2024. This electrification is compressing payback periods for capital-intensive propulsion upgrades and disqualifying pure diesel assets from premium contract pools.
SFDA amendments to the Saudi Maritime Code are mandating enhanced environmental compliance documentation and real-time emissions monitoring for all vessels operating in territorial waters. Shipowners must now install certified exhaust gas cleaning systems and submit quarterly performance reports to Mawani port authorities. Platform supply vessels with fixed-route deployment patterns face the tightest compliance timelines, accelerating retrofit investments ahead of enforcement deadlines.
Charter contracting is consolidating around multi-year performance agreements with embedded availability guarantees and fuel efficiency clauses. Spot market activity is retreating to short-notice emergency mobilizations and unplanned maintenance coverage. This behavioral shift is most pronounced in the Ras Tanura-Jubail corridor, where Saudi Aramco's integrated project timelines demand predictable vessel supply across five-year development cycles.
Saudi Arabia Offshore Support Vessel (OSV) Market Segmentation
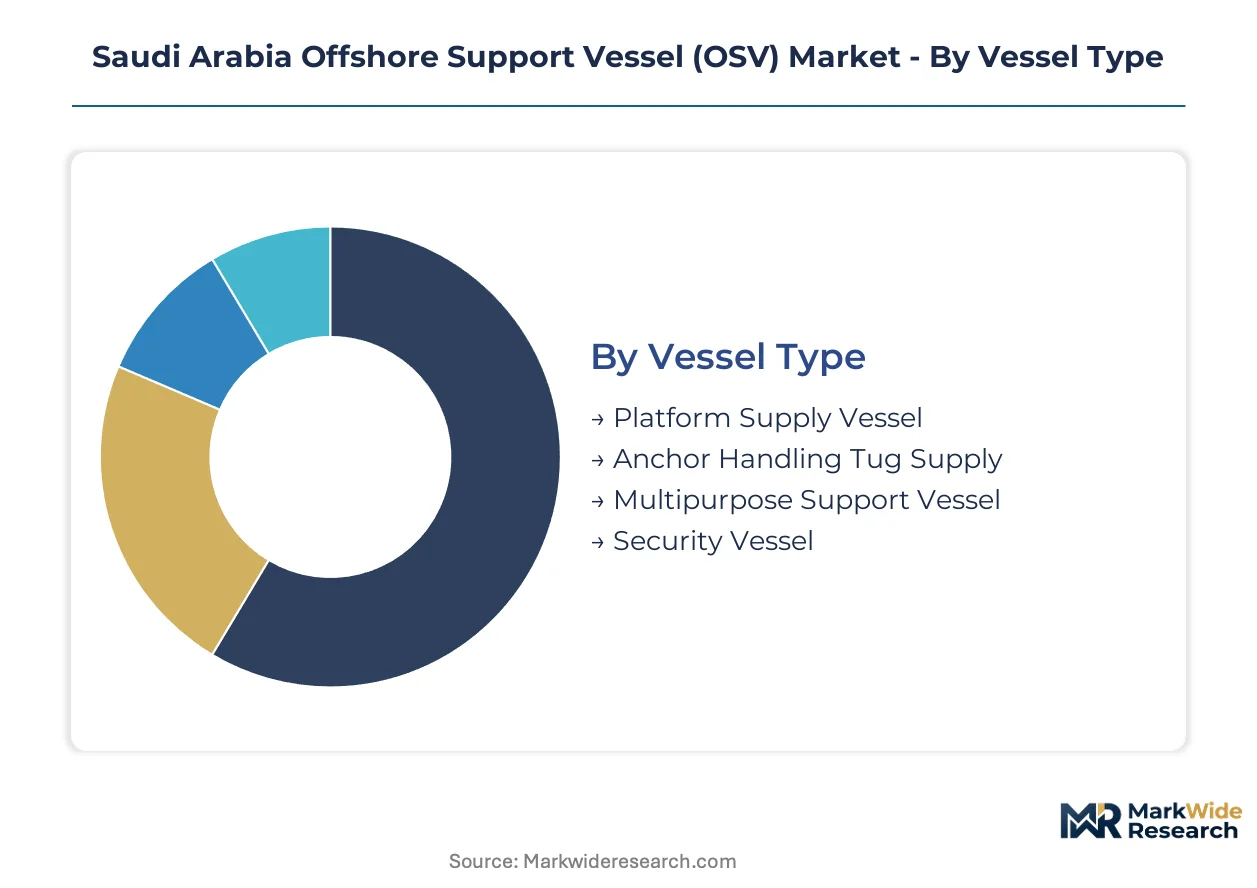
Offshore support vessel procurement in Saudi Arabia follows distinct technical and commercial axes. Charter specifications diverge sharply across vessel capabilities, service bundles, and contracting structures.
Vessel Type:
Propulsion specifications and dynamic positioning capabilities define competitive positioning across hull configurations.
- Platform Supply Vessel:These 70-90 meter hulls with 1,000+ tonne deck cargo capacity handle dry bulk, liquid mud, and methanol transfers to fixed Arabian Gulf platforms. Demand concentrates around Ras Tanura cluster developments where Saudi Aramco maintains continuous supply requirements.
- Anchor Handling Tug Supply:DP-2 and DP-3 equipped units exceeding 15,000 BHP bollard pull command premium day-rates for mobile offshore drilling unit positioning. Deepwater field developments in Saudi Arabia's eastern offshore blocks are absorbing high-specification tonnage fastest.
- Multipurpose Support Vessel:Hybrid-configured hulls combining ROV deployment, subsea construction support, and light intervention capabilities serve marginal field tiebacks.
- Security Vessel:Fast patrol craft with armed escort certification protect critical energy infrastructure against maritime threats.
Mature deployment sits with Platform Supply Vessel configurations. Newer deployment is concentrated in Anchor Handling Tug Supply units with enhanced dynamic positioning.
Service Type:
Operational intensity and crew specialization requirements segment service value chains.
- Logistics Support:Integrated supply chain coordination spanning warehousing at Jubail port, just-in-time vessel loading, and offshore platform inventory management. Saudi Aramco's tier-one contractors are consolidating procurement around single-source logistics providers.
- Crew Transportation:Helicopter alternative services using motion-compensated gangway systems for 150+ passenger transfers to remote wellhead platforms. SFDA safety protocols mandate enhanced stability criteria for personnel transport.
- Cargo Handling:Crane operations and subsea equipment deployment requiring certified offshore lifting competence.
- Maintenance Services:On-vessel repair capabilities and technician transport for platform topside interventions.
Volume concentration follows Logistics Support contracts. Margin expansion is concentrating in Crew Transportation as SFDA tightens safety specifications.
End User:
Procurement scale and technical specification authority vary sharply across charterer categories.
- Energy Companies:Saudi Aramco dominates charter demand with multi-year performance agreements embedding availability guarantees and fuel efficiency clauses. Long-term contract structures compress spot market liquidity across the eastern province.
- Marine Contractors:Subsea installation specialists and drilling service companies require flexible vessel access for campaign-based deployment.
- Government Agencies:Ministry of Energy and Mawani port authority vessels serve regulatory enforcement and maritime security functions.
- Research Institutions:Oceanographic survey and environmental monitoring operations utilize lightly equipped support hulls.
Contract maturity sits with Energy Companies. Procurement innovation is concentrating in Marine Contractors seeking hybrid-ready vessel specifications.
Deployment Model:
Capital commitment intensity and operational control rights determine contracting structure selection.
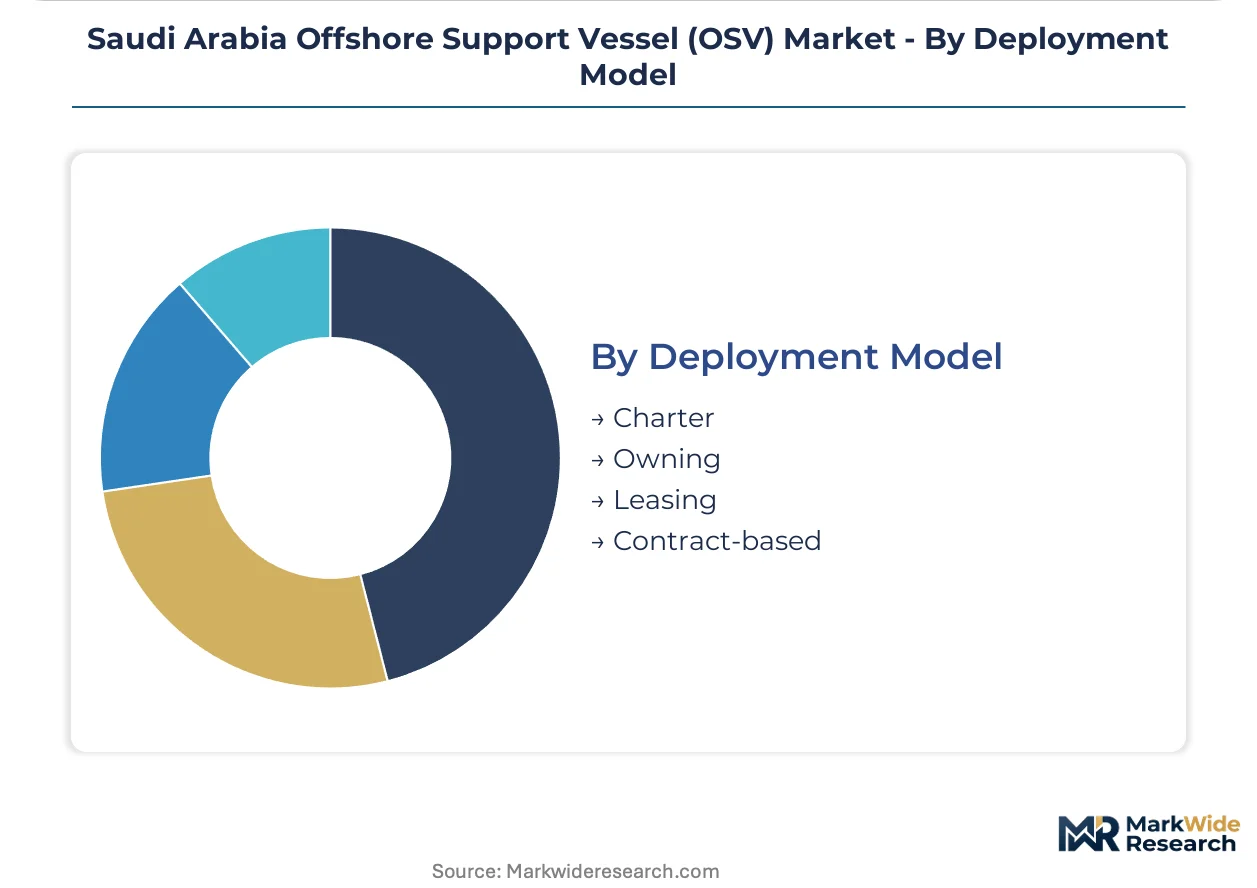
- Charter:Time-charter and bareboat arrangements transfer operational liability to vessel owners while preserving charterer route flexibility. Saudi Aramco's integrated project timelines favor five-year charter terms with embedded extension options.
- Owning:Captive fleet ownership eliminates third-party margin stacking for operators with predictable demand profiles.
- Leasing:Sale-and-leaseback structures release capital from vessel assets while preserving operational access.
- Contract-based:Project-specific agreements with availability-linked payment terms align vessel supply with field development milestones.
Risk transfer sits with Charter arrangements. Capital efficiency gains are concentrating in Contract-based structures with performance-linked pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Aramco's integrated project timelines concentrate charter demand along the eastern energy corridor, with vessel procurement patterns tracking field development cycles across multiple coastal clusters. SFDA maritime safety protocols and Mawani port authority regulations shape operational requirements throughout Saudi territorial waters.
Eastern Province
Ras Tanura and Jubail Industrial City anchor the heaviest OSV deployment, with platform supply vessels handling continuous cargo transfers to offshore platforms. SFDA certification requirements govern vessel eligibility for operations in these waters. The Jubail port infrastructure cluster serves as the primary maintenance hub, creating operational bottlenecks during peak demand periods.
Riyadh
Administrative and procurement functions for offshore fleet management concentrate in the capital, with Saudi Aramco headquarters directing charter contracting strategy. The Saudi Maritime Code amendments flow through central government channels headquartered here. Riyadh-based logistics coordinators manage supply chain integration between onshore warehousing and offshore vessel loading.
Western Region
Red Sea offshore blocks remain underexploited, presenting greenfield charter potential as exploration activity expands beyond Arabian Gulf concentrations. Mawani port authority regulations apply equally to western coastline operations. Yanbu port infrastructure offers alternative berthing capacity for vessels serving emerging western field developments.
NEOM Northwest
NEOM's industrial and energy projects are generating specialized vessel requirements for construction support and logistics coordination. Local content mandates under Saudi Vision 2030 incentivize joint ventures between international operators and domestic providers in this zone. The northwest coastline is attracting preliminary survey and site preparation vessel activity ahead of major infrastructure deployment.
Saudi Arabia Offshore Support Vessel (OSV) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid-ready specifications and local content partnerships. The vendor base clusters around three distinct maturity levels: integrated logistics platforms with multi-year charter capacity, localized maintenance specialists with port-proximity advantages, and high-specification vessel operators serving deepwater niches. Two strategic archetypes dominate: scale-driven charter aggregators and technical specialists commanding premium day-rates. Competitive positioning hinges on SFDA certification compliance speed and Mawani port relationship depth.
Within the integrated logistics tier, Maersk AS anchors multi-year contract portfolios across Saudi offshore fields. Zamil Offshore exemplifies the localization archetype through proximity to Jubail port infrastructure. Tidewater Inc. occupies the high-specification niche for anchor handling tug supply operations. These three operators represent distinct competitive vectors: scale aggregation, geographic embedding, and technical specialization.
| Leading Market Players |
|---|
| Bumi Armada |
| Maersk AS |
| Zamil Offshore |
| Baltic Marine Services LLC |
| Bourbon Corporation SA |
| SEACOR Marine |
| VM Marine |
| International Maritime Industries |
| Tidewater Inc. |
| Others |
Supply Flow & Price Mechanics
SFDA emissions compliance mandates gate both qualified vessel supply and premium-tier pricing access, compressing charter differentials between hybrid-ready assets and legacy tonnage while concentrating procurement leverage among Saudi Aramco and its tier-one contractors. Steel plate input volatility and Jubail port infrastructure bottlenecks amplify cost pass-through pressures across the eastern province fleet.
Pricing Analysis
Volume concentration in platform supply vessels trades at compressed margins against premium day-rates commanded by DP-3 anchor handling tug supply units serving deepwater Arabian Gulf blocks. Three-tier pricing structure across high-specification hybrid, DP-2 compliant, and legacy diesel vessels tracks SFDA certification grade and bollard pull capacity. Pricing pressure stems from steel plate commodity swings squeezing newbuild economics at domestic shipyards. National oil company procurement teams exhibit lowest price sensitivity given performance-linked contract structures, while marine contractors face acute margin compression on spot charter exposure.
Supply Chain Analysis
Direct-to-charterer contracting channels handle Saudi Aramco's integrated project demand, bypassing spot market intermediaries. Hull construction draws from South Korean and Chinese shipyard capacity, with marine engine packages sourced from Germany and Japan. Supply chain risk centers on single-source dependency for dynamic positioning system integration from European specialists. Distribution runs through Mawani-regulated port infrastructure with Jubail anchoring maintenance and berthing logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over shore-based maintenance infrastructure and hybrid propulsion technology supply determines long-term charter viability.
For Market Incumbents: Hedge utilization risk through captive maintenance facility investments at Yanbu and Ras Tanura, reducing reliance on Jubail port concentration. Secure multi-year steel plate offtake agreements with Korean mills to buffer commodity volatility. Defend against emerging hybrid specialists by accelerating DP-3 fleet certification ahead of SFDA enforcement timelines.
For New Entrants and Emerging Players: Battery-hybrid propulsion architecture offers the clearest technology-first wedge against legacy fleet operators. Target undercontracted Red Sea exploration support where Saudi Aramco has yet to lock five-year charter terms. Pursue joint venture structures with Zamil Group affiliates to satisfy local content mandates under Vision 2030 procurement preferences.
For Investors and Strategic Acquirers: SFDA certification backlog clearance rates are the leading indicator that vessel availability constraints will ease or tighten across the eastern province. Five-to-ten year viability favors operators with integrated logistics platforms and Mawani port relationship depth. Monitor hybrid propulsion retrofit order books at International Maritime Industries as the signal for fleet modernization capex inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | SFDA emissions deadlines disqualify pure diesel assets from Saudi Aramco tender pools. |
| Jubail Maintenance Facility Expansion | Port-proximate repair capacity reduces vessel downtime during peak charter demand. |
| Red Sea Field Development Charter | Greenfield western coastline blocks offer first-mover positioning ahead of Arabian Gulf saturation. |
| Local Content Joint Venture | Vision 2030 procurement preferences favor Saudi-partnered operators in NEOM zone. |
| DP-3 Certification Acceleration | Advanced dynamic positioning unlocks premium day-rates for deepwater drilling unit positioning. |
Methodological Framework
Independent corroboration across charter contract registries, Mawani port authority utilization filings, and SFDA certification databases underwrites the qualitative findings in this study. Primary interviews with Saudi Aramco procurement officers, offshore vessel fleet managers, Jubail shipyard operations directors, and marine engineering consultants combined with secondary validation from Lloyd's List intelligence, Clarksons Research vessel databases, and Saudi Maritime Code amendment records. Bottom-up charter rate aggregation and top-down fleet capacity modeling triangulate market size estimates.
Rate-of-change decomposition across vessel type, propulsion specification, and deployment model segments structures the analytical framework throughout the projection horizon. CAGRs derive from charter day-rate trajectory modeling and fleet replacement cycle analysis. Modeled inputs include SFDA regulatory compliance timelines, Saudi Aramco field development capex schedules, and hybrid propulsion technology cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel plate commodity spikes or extended SFDA certification delays. Forecasts reflect assumptions regarding Saudi Aramco production targets and Vision 2030 local content enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Europe Maritime Information Market