
 Asia-Pacific Maritime Satellite Communication Market | 2026-2036
Asia-Pacific Maritime Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Maritime Satellite Communication Market Outlook
IMO GMDSS certification is rotating vendor eligibility across the Asia-Pacific Maritime Satellite Communication landscape, filtering participants by distress-alerting and satellite redundancy qualifications. Thales Group leverages its military-grade encryption heritage to anchor naval force contracts across the region. Intelsat SA sustains geographic dominance through its EpicNG high-throughput satellite fleet positioned over Pacific and Indian Ocean coverage zones. The SKY Perfect JSAT Group competes via dedicated Ku-Band capacity serving Japanese commercial shipping lanes.
Asia-Pacific maritime satellite communication encompasses ship-to-shore data transmission via geostationary and low-earth-orbit constellations, typically operating in Ku-Band (12-18 GHz) and L-Band (1-2 GHz) frequencies with dish diameters ranging from 60 cm to 2.4 meters for stabilized maritime VSAT terminals. This infrastructure enables real-time fleet tracking, engine telemetry, crew welfare connectivity, and regulatory distress signaling across dispersed oceanic routes. VSAT product configurations command the dominant revenue share due to their bandwidth scalability for container shipping operators, while Ku-Band adoption is accelerating fastest among fishing industry fleets seeking affordable broadband alternatives to legacy Inmarsat services. Data services within the service type dimension capture concentrated margin pools as vessel operators prioritize IoT sensor backhaul and predictive maintenance analytics over basic voice connectivity.
TRAI in India enforces satellite service licensing frameworks that condition foreign operator market access through mandatory local gateway infrastructure and spectrum coordination protocols. Japan's METI coordinates maritime digitalization subsidies that directly stimulate VSAT procurement for domestic shipping consortia transitioning to autonomous navigation support systems. Australia's TGA maritime safety directives intersect with the IMO framework to mandate satellite communication redundancy for vessels operating in the Great Barrier Reef restricted zones. Stakeholders must monitor evolving national spectrum allocation auctions and coastal state data sovereignty requirements that will reshape terminal deployment economics and service provider licensing structures.
Market Dynamics
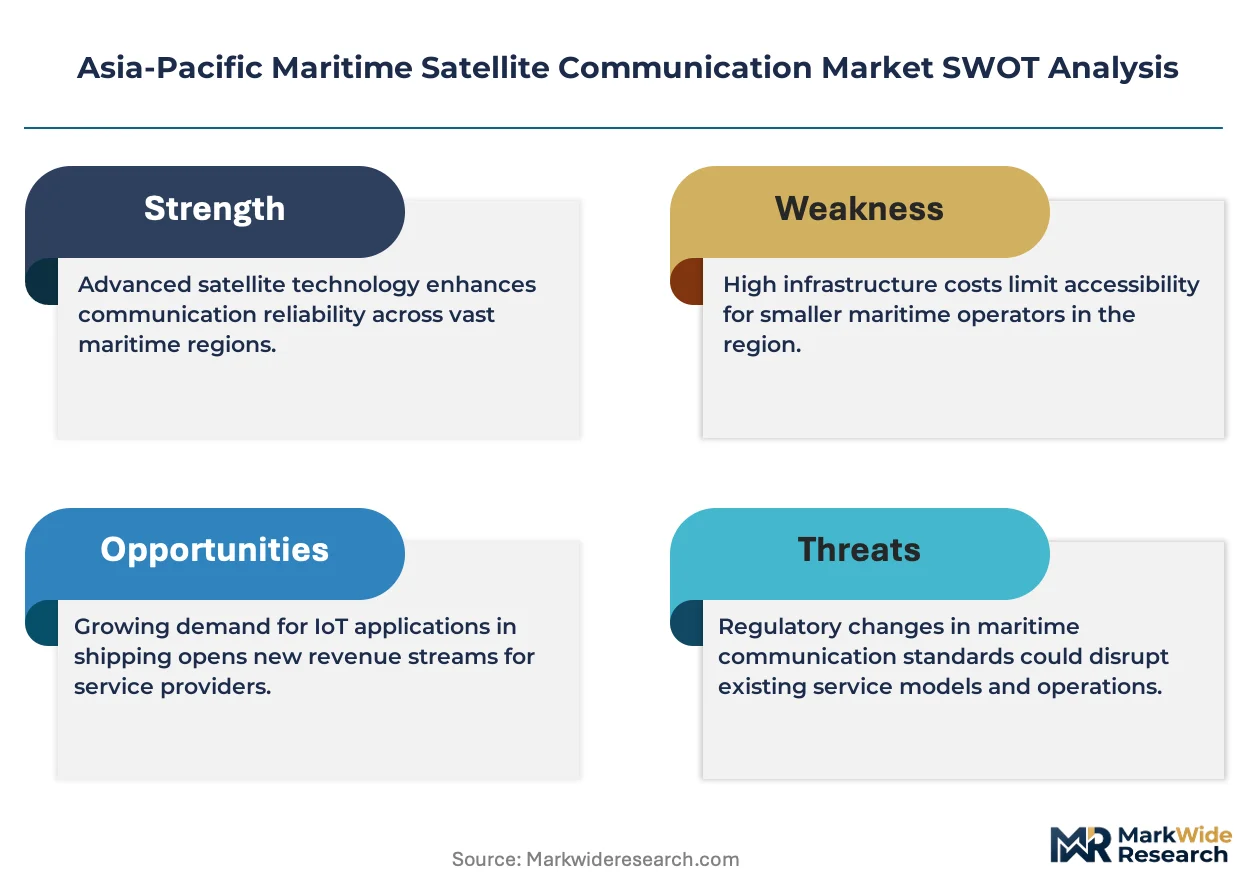
The International Maritime Organization's updated GMDSS framework is compressing certification timelines and mandating satellite redundancy across Asia-Pacific commercial fleets, forcing terminal refresh cycles and vendor requalification.
Growth Catalysts
- Indonesia's Archipelagic Shipping Lanes:Port digitization programs and fleet modernization initiatives across the archipelago are expanding bandwidth procurement for container and bulk carriers operating through the Malacca Strait corridors.
- METI Maritime Digitalization Subsidies:Japan's Ministry of Economy, Trade and Industry coordinates direct VSAT procurement support for domestic shipping consortia transitioning to autonomous navigation support systems.
- Ku-Band Frequency Adoption:Fishing industry fleets across Southeast Asian waters are accelerating migration from legacy Inmarsat L-Band services to Ku-Band VSAT terminals for affordable broadband connectivity.
Market Restraints
- TRAI Licensing Friction:India's Telecom Regulatory Authority mandates local gateway infrastructure and spectrum coordination protocols that condition foreign operator market access, elevating compliance costs for international service providers.
- Terminal Hardware Concentration:Stabilized maritime VSAT antenna production concentrates among specialized precision manufacturers in East Asian industrial clusters, creating supply vulnerability for 60 cm to 2.4 meter dish configurations.
- LEO Constellation Substitution Threat:Emerging low-earth-orbit broadband constellations are threatening to displace geostationary satellite services for certain vessel classes, compressing long-term contract visibility for traditional operators.
Strategic Opportunities
- Predictive Maintenance Analytics:IoT sensor backhaul services for engine telemetry and hull monitoring represent underpenetrated margin pools as vessel operators prioritize data services over basic voice connectivity.
- Australia's Great Barrier Reef Zones:TGA maritime safety directives intersecting with IMO frameworks mandate satellite communication redundancy for vessels operating in restricted environmental zones, creating compliance-driven demand concentration.
- 5G-Satellite Convergence:Integration of terrestrial 5G coastal coverage with satellite backhaul is enabling seamless ship-to-shore handoff architectures for vessels operating within 50 nautical miles of shore infrastructure.
Industry Challenges
- Maritime Cybersecurity Certification:IMO 2021 cybersecurity guidelines for shipboard systems are extending compliance timelines for satellite terminal firmware updates and encryption protocol validation across aging fleet installations.
- Crew Welfare Bandwidth Scaling:Container shipping operators face execution complexity in balancing commercial IoT data prioritization against escalating crew connectivity expectations for streaming and real-time communication services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Maritime Satellite Communication Market |
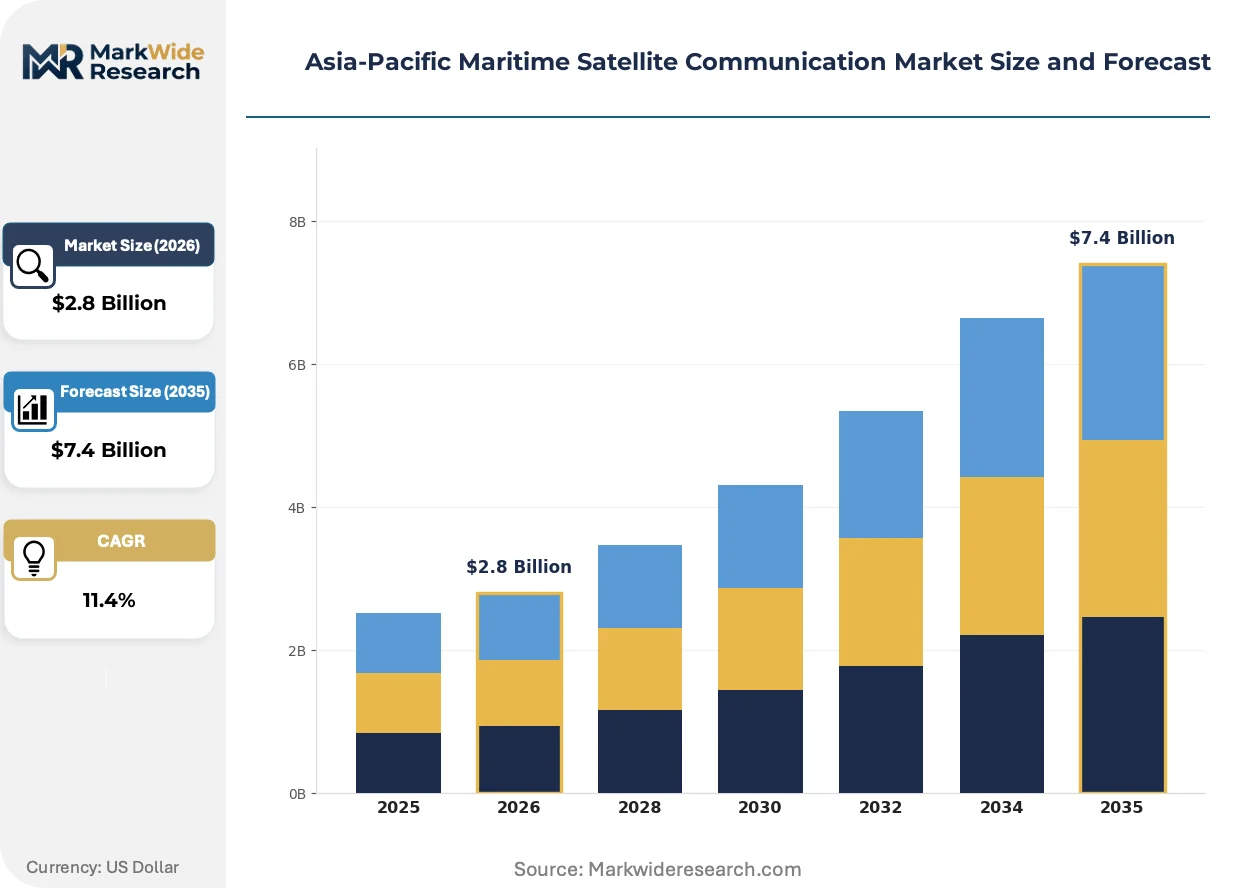
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VSAT, Inmarsat, Iridium, Ku-Band Service Type: Bandwidth Services, Data Services, Voice Services, Video Services Deployment: Onboard, Shore-based, Hybrid, Point-to-Point End User: Commercial Shipping, Naval Forces, Fishing Industry, Cruise Operators |
| Companies Covered | Thaicom PCL, Intelsat SA, Inmarsat Group Ltd, Speedcast International Limited, Asia Satellite Telecommunications Holdings Ltd, Network Innovation Inc., Thales Group, The SKY Perfect JSAT Group, Thuraya Telecommunications Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Maritime Satellite Communication Market Strategic Shifts
Terminal architecture is fragmenting as stabilized VSAT systems encounter competition from flat-panel electronically steered arrays, while regulatory mandates compress replacement cycles and vessel operators renegotiate service tier structures.
Geostationary high-throughput satellite capacity is decomposing the traditional hub-and-spoke maritime connectivity model. Container shipping operators with dispersed Pacific and Indian Ocean routes are adopting multi-orbit service architectures that blend GEO throughput with LEO latency performance. This technology is decomposing vendor lock-in patterns that previously anchored decade-long service contracts to single satellite operators.
Australia's TGA has aligned with IMO GMDSS updates to mandate redundant satellite communication pathways for vessels transiting the Great Barrier Reef Marine Park. The industrial consequence is accelerated dual-terminal installations aboard bulk carriers and cruise operators serving Queensland ports. Japanese and Korean shipyards are now specifying redundant Ku-Band and L-Band configurations as standard for newbuild vessels destined for Australian coastal routes.
Charter-party agreements are increasingly unbundling connectivity services from vessel hire rates, forcing shipowners to assume direct satellite service procurement responsibility. Maritime service aggregators in Singapore and Hong Kong are displacing traditional Inmarsat distribution channels with flexible bandwidth-on-demand contracts. This pattern is most visible among Southeast Asian tanker fleets operating under spot-market charter arrangements where connectivity cost transparency has become a competitive tender requirement.
Asia-Pacific Maritime Satellite Communication Market Segmentation
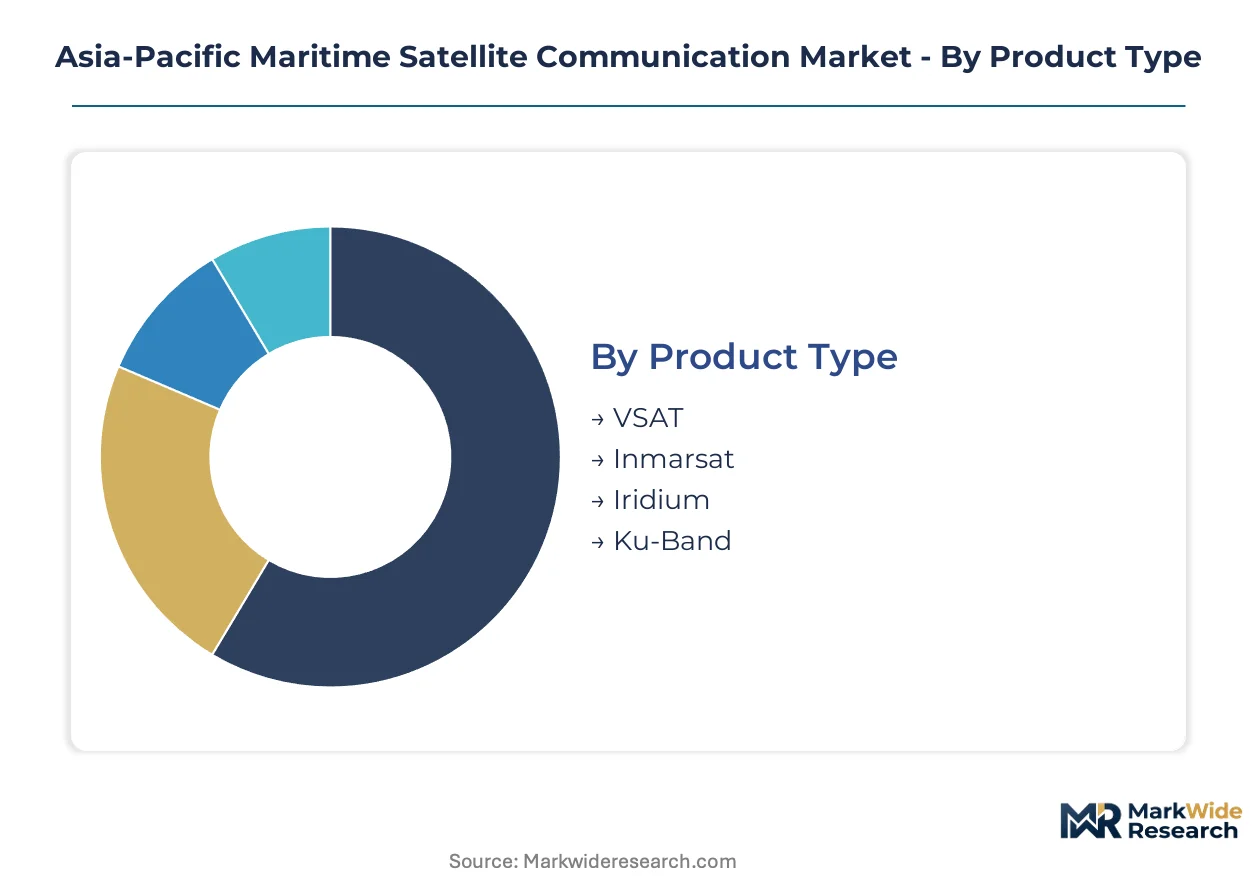
Asia-Pacific maritime satellite communication procurement patterns diverge sharply between archipelagic domestic routes and transoceanic export corridors. Vessel operators segment hardware and service investments by operational geography, with coastal state regulations conditioning terminal specifications and bandwidth commitments across fleet categories.
Product Type:
Domestic archipelagic fleets in Indonesia and the Philippines anchor demand for compact, affordable terminals, while export-oriented container operators across Northeast Asian corridors prioritize high-throughput systems for oceanic routes.
- VSAT:Stabilized maritime terminals with dish diameters from 60 cm to 2.4 meters deliver scalable Ku-Band and L-Band connectivity for real-time fleet tracking and engine telemetry. Container shipping operators across Singapore and Hong Kong procurement channels concentrate demand here, driven by IoT sensor backhaul requirements and crew welfare bandwidth scaling.
- Ku-Band:Frequencies operating between 12-18 GHz provide cost-efficient broadband alternatives to legacy satellite services for mid-size vessel operators. Fishing fleets across Southeast Asian waters are accelerating migration to these terminals, drawn by affordable pricing relative to Inmarsat L-Band subscriptions and improving coverage from high-throughput satellite constellations.
- Inmarsat:L-Band services maintain regulatory compliance utility for distress signaling and GMDSS certification across Asia-Pacific commercial fleets.
- Iridium:Low-earth-orbit constellation access delivers pole-to-pole coverage for vessels operating in high-latitude Pacific routes beyond geostationary reach.
VSAT holds the largest share; momentum sits with Ku-Band adoption among price-sensitive fleet segments.
Service Type:
Margin concentration follows data intensity, with predictive analytics and video applications commanding premium pricing over basic connectivity tiers.
- Data Services:IoT sensor backhaul for hull monitoring, engine performance analytics, and cargo condition tracking commands concentrated margin pools. Vessel operators across Japanese shipping consortia prioritize these services over voice connectivity, with METI maritime digitalization subsidies directly stimulating procurement for autonomous navigation support systems.
- Bandwidth Services:Committed information rate contracts and pooled megabit-per-second allocations form the commercial foundation for fleet-wide connectivity management. Singapore-based maritime service aggregators are displacing traditional distribution channels with flexible bandwidth-on-demand contracts for Southeast Asian tanker fleets operating under spot-market charter arrangements.
- Voice Services:Regulatory-mandated distress alerting and routine ship-to-shore communication remain essential but low-margin service components.
- Video Services:Crew welfare streaming and remote technical support applications are expanding fastest among cruise operators and bulk carriers with extended voyage durations.
Data Services generates the highest margins; Video Services is climbing the fastest as crew connectivity expectations escalate.
Deployment:
Terminal architecture selection reflects vessel mobility patterns, with stationary infrastructure dominating port-adjacent operations and stabilized systems governing mobile maritime applications.
- Onboard:Stabilized VSAT terminals and flat-panel electronically steered arrays installed directly aboard vessels enable continuous connectivity across oceanic routes. Japanese and Korean shipyards now specify redundant Ku-Band and L-Band configurations as standard for newbuild vessels destined for Australian coastal routes under TGA maritime safety directives.
- Hybrid:Architectures blending geostationary throughput with low-earth-orbit latency performance are decomposing vendor lock-in patterns among container operators with dispersed Pacific and Indian Ocean routes. These configurations enable seamless handoff between satellite layers as vessels traverse coverage boundaries.
- Shore-based:Coastal gateway stations and port communication infrastructure support vessel traffic management and cargo logistics coordination.
- Point-to-Point:Dedicated satellite links between specific vessel-shore pairs serve specialized naval and offshore energy applications requiring isolated communication pathways.
Onboard deployment dominates vessel connectivity; Hybrid architectures are gaining share fastest as multi-orbit service models mature.
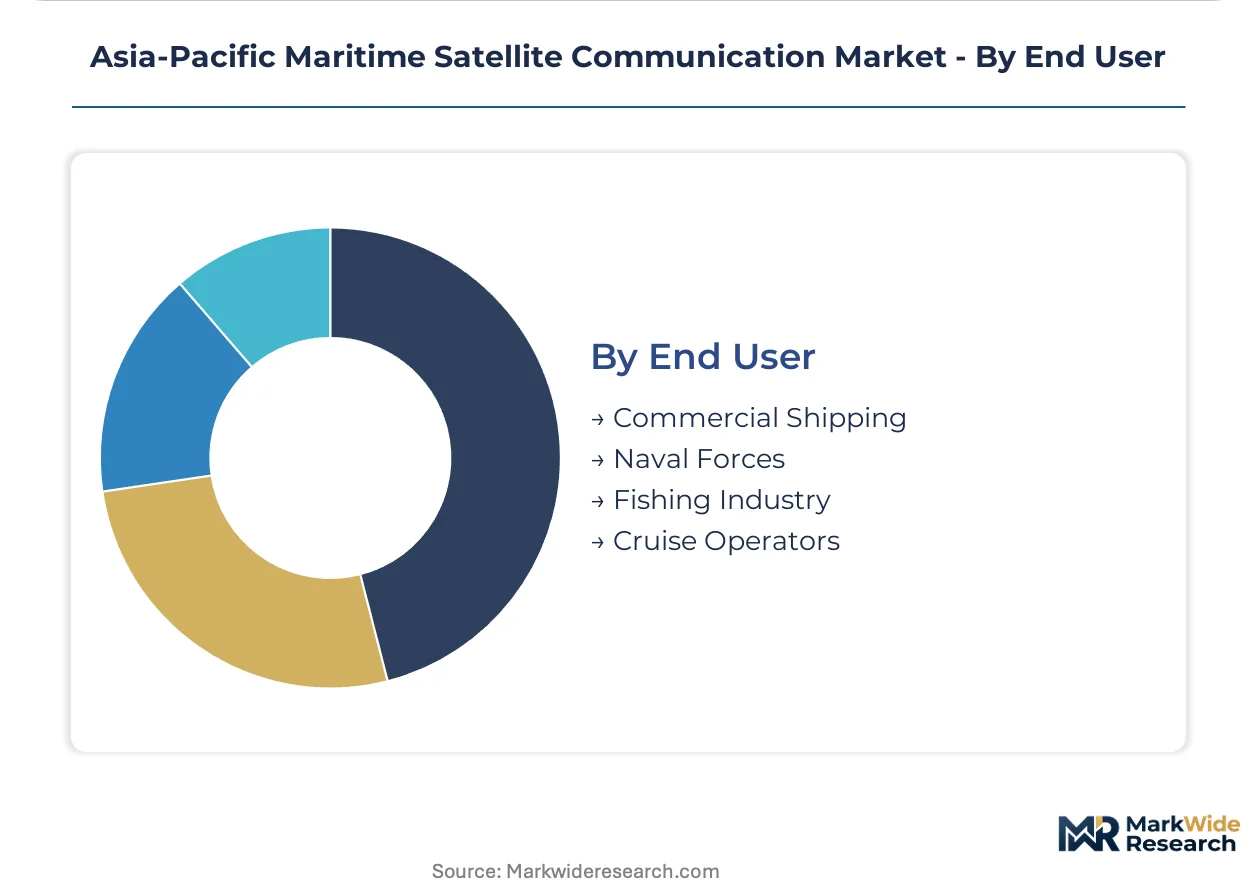
End User:
Fleet modernization timelines and regulatory compliance obligations create divergent procurement rhythms across vessel operator categories.
- Commercial Shipping:Container and bulk carrier operators across Southeast Asian trade corridors drive VSAT volume procurement, with Indonesia's port digitization programs expanding bandwidth procurement for vessels transiting Malacca Strait corridors. Charter-party agreement unbundling is forcing shipowners to assume direct satellite service procurement responsibility.
- Naval Forces:Military-grade encryption requirements and sovereign communication security protocols anchor specialized demand for hardened terminal systems. Thales Group leverages its encryption heritage to secure regional naval force contracts across Asia-Pacific waters.
- Fishing Industry:Price-sensitive fleet operators across Southeast Asian waters are accelerating migration from legacy Inmarsat services to Ku-Band VSAT terminals for affordable broadband connectivity and catch documentation compliance.
- Cruise Operators:Passenger connectivity expectations and Australia Great Barrier Reef zone transit requirements mandate redundant satellite communication pathways aboard vessels serving Queensland ports.
Commercial Shipping holds the largest share; the Fishing Industry represents the steepest expansion trajectory as affordability barriers erode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government maritime digitalization subsidies and port modernization programs are conditioning satellite communication procurement across Asia-Pacific coastal states. National regulators enforce spectrum licensing frameworks and safety compliance mandates that shape terminal deployment economics.
Indonesia
Archipelagic shipping lanes through the Malacca Strait drive concentrated VSAT demand for container and bulk carriers. Port digitization programs expand bandwidth procurement for fleet modernization. Jakarta and Surabaya anchor maritime service aggregator activity for domestic shipping consortia.
Japan
METI coordinates direct VSAT procurement subsidies for shipping operators transitioning to autonomous navigation support systems. Maritime digitalization policies stimulate Ku-Band terminal adoption among commercial fleets. Yokohama and Nagoya industrial clusters concentrate shipyard newbuild specifications with redundant satellite configurations.
Australia
TGA maritime safety directives mandate satellite communication redundancy for vessels transiting Great Barrier Reef restricted zones. Compliance-driven demand accelerates dual-terminal installations aboard bulk carriers and cruise operators. Queensland ports anchor procurement concentration for reef-zone transit requirements.
India
TRAI licensing frameworks condition foreign operator market access through mandatory local gateway infrastructure and spectrum coordination protocols. Commercial shipping fleets face elevated compliance costs for terminal refresh cycles. Mumbai and Chennai industrial corridors concentrate maritime service provider licensing negotiations.
Singapore
Maritime service aggregators displace traditional distribution channels with flexible bandwidth-on-demand contracts for tanker fleets operating under spot-market charter arrangements. Connectivity cost transparency has become a competitive tender requirement. The city-state's port authority anchors regional procurement channel restructuring.
Asia-Pacific Maritime Satellite Communication Market Competitive Environment
Player mix skews toward satellite operators and specialized maritime service aggregators with geostationary capacity and VSAT terminal distribution capabilities. The competitive structure concentrates around three strategic archetypes: high-throughput satellite fleet operators, military-grade encryption specialists, and regional bandwidth aggregators. Capacity expansion and strategic partnerships dominate competitive moves as vendors position for multi-orbit service architectures.
Within the satellite operator tier, Intelsat SA and The SKY Perfect JSAT Group represent contrasting geographic anchoring strategies. Thales Group occupies a position exemplifying the military-grade encryption specialist archetype. These three entities illustrate how heritage capabilities and orbital positioning shape competitive differentiation across naval force contracts and commercial shipping procurement channels.
| Leading Market Players |
|---|
| Thaicom PCL |
| Intelsat SA |
| Inmarsat Group Ltd |
| Speedcast International Limited |
| Asia Satellite Telecommunications Holdings Ltd |
| Network Innovation Inc. |
| Thales Group |
| The SKY Perfect JSAT Group |
| Thuraya Telecommunications Company |
| Others |
Value Chain & Pricing Dynamics
Ku-Band terminal substitution for legacy Inmarsat L-Band services is redrawing procurement economics across Southeast Asian fishing fleets, compressing hardware margins while expanding service-attach revenue pools for bandwidth aggregators in Singapore and Hong Kong.
Pricing Analysis
Certification level under IMO GMDSS and TGA frameworks creates the primary spread between premium and standard service tiers. The dominant pricing structure runs through subscription-based bandwidth contracts with committed information rate floors. Price differentiation rests on satellite redundancy configuration and cybersecurity protocol validation, with dual-terminal vessels commanding premium positioning. Pricing pressure stems from LEO constellation entrants compressing long-term contract visibility for geostationary operators. Fishing industry fleets exhibit highest price sensitivity, while naval forces and cruise operators demonstrate lowest sensitivity due to sovereign security mandates and passenger experience requirements.
Supply Chain Analysis
Just-in-time terminal procurement dominates vessel newbuild programs, though strategic stockpiling of stabilized antenna components is emerging among Japanese and Korean shipyards facing supply vulnerability. Geographic supply concentrates in South Korea, Japan, and Taiwan for precision-manufactured VSAT terminals with dish diameters from 60 cm to 2.4 meters. Raw material dependencies center on gallium nitride semiconductors, carbon fiber composite substrates, and precision servo motors. Single-source vulnerability in East Asian industrial clusters for stabilized antenna production creates structural risk. Distribution runs through maritime service aggregators in Singapore and Hong Kong displacing traditional Inmarsat channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware commoditization is accelerating service-attach economics, with predictive maintenance analytics and bandwidth-on-demand contracts expanding faster than terminal sales across Asia-Pacific maritime procurement channels.
For Market Incumbents: Consolidate around multi-orbit service architectures that blend geostationary throughput with LEO latency performance, insulating against constellation substitution threats. Deepen vertical integration into terminal firmware and encryption protocol layers to capture IMO 2021 cybersecurity compliance spending. Anchor capacity positions through strategic partnerships with Japanese and Korean shipyards specifying redundant configurations for Australian reef-zone transit. For New Entrants and Emerging Players: Differentiate on flat-panel electronically steered array technology to bypass stabilized VSAT supply bottlenecks concentrated in East Asian manufacturing clusters. Target Indonesia's archipelagic domestic shipping consortia with affordable Ku-Band terminals and flexible bandwidth contracts unbundled from charter-party agreements. Pursue direct procurement relationships with fishing industry fleets accelerating migration from legacy Inmarsat services. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors bandwidth aggregators with software-defined service orchestration capabilities over pure satellite operators. Long-term viability hinges on recurring revenue density from IoT sensor backhaul and crew welfare connectivity scaling faster than hardware depreciation cycles. Acquisition targets should demonstrate established relationships with METI subsidy programs or TGA compliance certification pathways. The signal to watch is charter-party agreement restructuring that forces shipowners to assume direct satellite procurement responsibility.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Service Architecture | Blends GEO throughput with LEO latency for container operators across Pacific and Indian Ocean routes. |
| Cybersecurity Certification Investment | Captures IMO 2021 compliance spending for terminal firmware updates and encryption validation. |
| Bandwidth-on-Demand Platform | Displaces traditional distribution channels for Southeast Asian tanker fleets under spot-market arrangements. |
| Flat-Panel Terminal Development | Bypasses supply vulnerability in stabilized VSAT manufacturing concentrated in East Asian clusters. |
| Predictive Maintenance Analytics Bundle | Captures margin pools from engine telemetry and hull monitoring prioritized over basic voice connectivity. |
Study Parameters
Desk research of satellite operator capacity disclosures, regulatory filings with IMO and national maritime authorities, and vessel fleet databases preceded structured interviews with maritime service aggregators, shipyard procurement directors, and terminal manufacturers. Primary fieldwork captured deployment economics and contract restructuring patterns across Singapore, Hong Kong, and Tokyo procurement channels. Secondary validation drew from customs trade data, port authority digitization program announcements, and spectrum allocation records. Bottom-up terminal shipment analysis triangulated against top-down bandwidth demand modeling.
Variance decomposition across product type, service tier, deployment architecture, and end-user category shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include terminal specification, bandwidth commitment structure, vessel mobility pattern, and operator fleet category. CAGRs were derived from elasticity-adjusted demand curves incorporating METI subsidy program trajectories and TGA compliance mandate timelines. Industry-specific forecast inputs encompassed charter-party agreement unbundling velocity and LEO constellation coverage expansion assumptions.
Material uncertainties — LEO substitution pace, national spectrum auction outcomes, and coastal state data sovereignty enforcement — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory compliance timeline adherence and terminal refresh cycle acceleration. Revision becomes warranted when LEO constellation commercial service deployment crosses threshold coverage density for Pacific and Indian Ocean shipping corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Global Maritime Market