
 Global Connected Ship Market | 2026-2036
Global Connected Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Ship Market Intelligence
The growing emphasis on offshore support vessels and specialized tankers is repositioning the market away from a sole focus on traditional bulk carriers. This shift creates new requirements for high-bandwidth connectivity and onboard data processing. Wartsila Oyj leverages its integrated solutions portfolio to address these complex operational needs. Kongsberg Gruppen differentiates through its advanced sensor and autonomous navigation systems, while Northrop Grumman Corporation extends its defense-grade communication technologies into the commercial maritime sector.
A connected ship integrates onboard operational systems with shore-side management platforms through a persistent digital link. These systems utilize high-throughput satellite communication (SATCOM) to transmit real-time data on vessel performance, location, and health. While SATCOM represents the core technology segment, its application in predictive Maintenance Alerts is growing faster than mature uses like basic Fleet Monitoring. The ability to collect and analyze this data is central for end users such as shipping companies and port authorities.
Regulatory frameworks from the International Maritime Organization (IMO), such as SOLAS conventions, mandate certain communication and safety systems onboard vessels. Concurrently, equipment must comply with radio frequency standards set by bodies like the US Federal Communications Commission (FCC) and European CE marking requirements. These rules create a baseline for technology adoption. Vessel operators must now weigh the operational benefits of enhanced connectivity against the escalating cybersecurity threats targeting maritime assets.
Market Dynamics
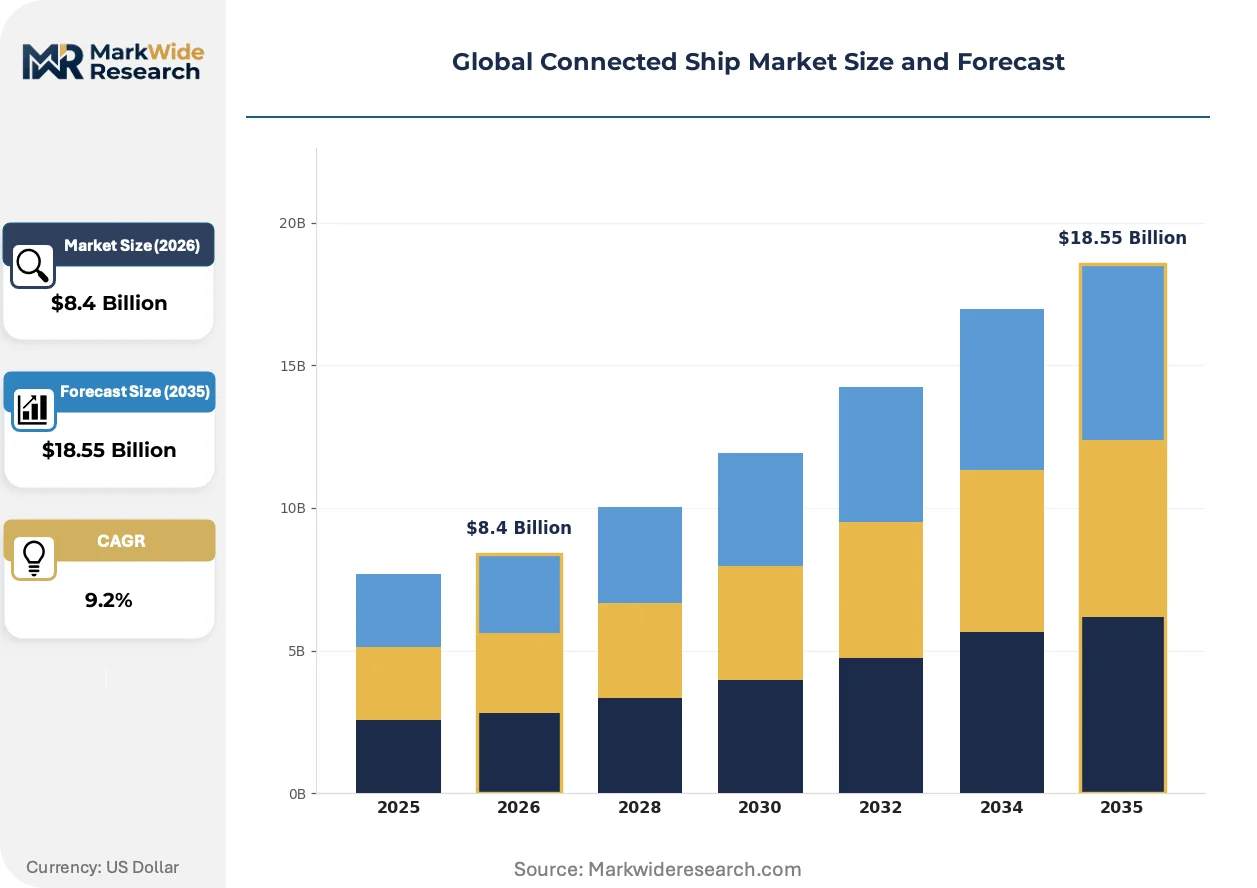
The convergence of high-throughput satellite communication with onboard operational technology is the central force shaping the connected ship market. This integration enables real-time data streams, compelling shipping companies to adopt digital fleet management for enhanced operational efficiency and safety compliance.
Growth Catalysts
- Regulatory Mandates:IMO's cyber risk guidelines and SOLAS conventions compel operators to adopt certified secure communication systems, establishing a baseline for market adoption.
- SATCOM Advancement:The deployment of LEO satellite constellations lowers connectivity costs, making data-intensive applications like remote diagnostics viable for more vessel types.
- Specialized Fleet Demand:The operational needs of offshore support vessels for constant, high-bandwidth monitoring pull adoption beyond traditional container and bulk carrier segments.
Market Restraints
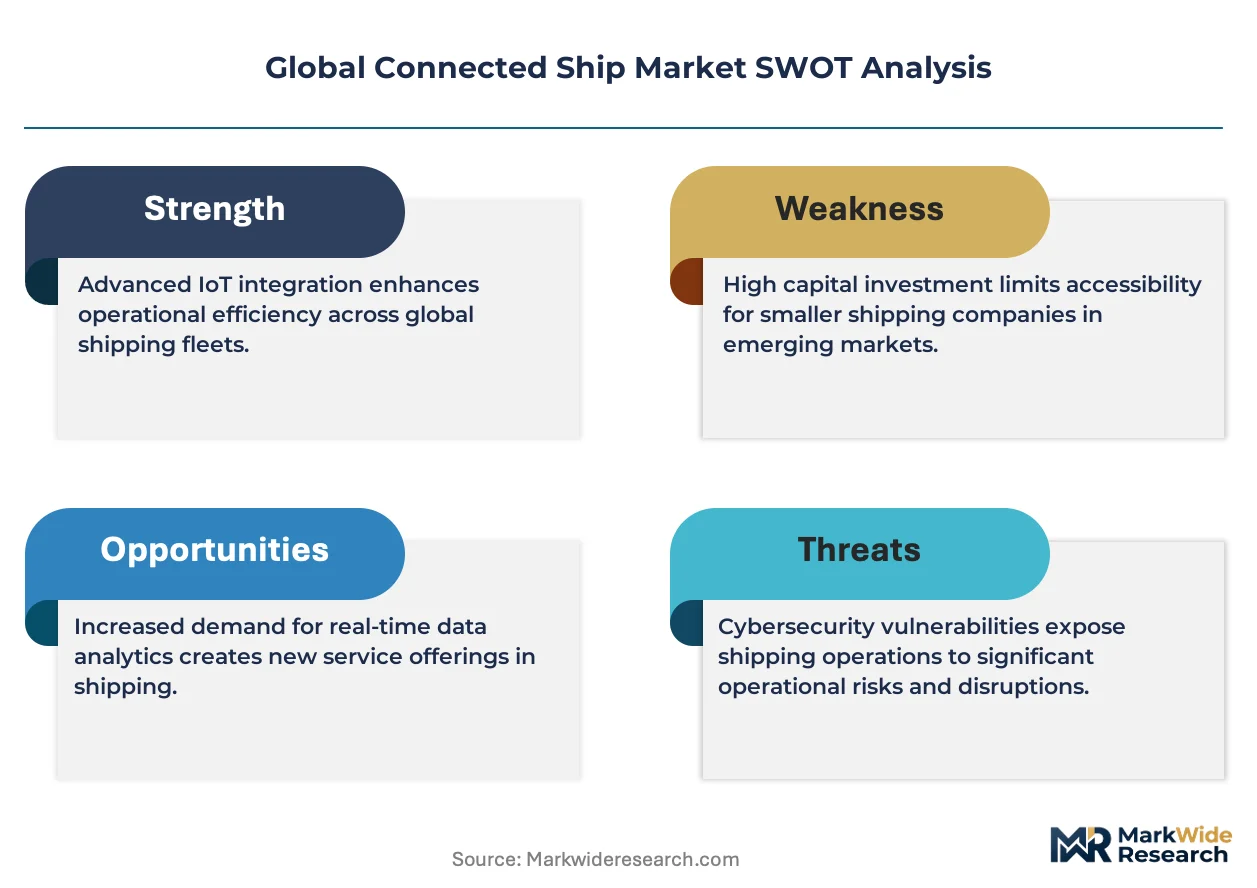
- High Capital Outlay:The upfront cost for SATCOM terminals and recurring data subscription fees present a major financial barrier for smaller fleet operators.
- System Interoperability:A lack of data format standardization across equipment from different vendors creates integration complexity, hindering the deployment of unified platforms.
- Escalating Cyber Risk:Increased vessel connectivity exposes critical operational technology to cyberattacks, forcing investment in costly security measures and specialized personnel training.
Strategic Opportunities
- Decarbonization Analytics:Developing AI platforms to optimize routes and engine performance helps owners meet IMO 2030 and 2050 emissions targets.
- Underserved Vessel Segments:Tailored, cost-effective connectivity solutions for smaller vessels like fishing fleets and coastal carriers represent a significant growth area.
- Onboard Edge Computing:Integrating edge computing with IoT sensors enables local data processing, reducing satellite transmission costs and improving response times.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel with hybrid skills in maritime operations, IT networking, and cybersecurity complicates the management of advanced onboard systems.
- Legacy System Integration:Integrating modern digital platforms with existing analog operational technology on older vessels presents significant technical and financial hurdles for fleet modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Ship Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Container Vessels, Bulk Carriers, Tankers, Passenger Ships, Offshore Support Vessels Technology: SATCOM, VHF Radio, AIS, Radar Systems, GNSS Application: Fleet Monitoring, Cargo Tracking, Navigation Assistance, Maintenance Alerts, Safety Management End User: Shipping Companies, Port Authorities, Shipbuilders, Maritime Software Providers, Logistics Operators |
| Companies Covered | Wartsila Oyj, Schneider Electric, Kongsberg Gruppen, Emerson Electric Co., ABB Ltd., Northrop Grumman Corporation, General Electric Company, Rockwell Automation Inc., Marlink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Ship Market Strategic Shifts & Innovations
The market is shifting from providing basic vessel connectivity to delivering integrated operational intelligence platforms. This evolution prioritizes the application of data for measurable outcomes in efficiency, safety, and compliance, transforming ships into mobile data centers.
Digital twin technology creates a dynamic virtual replica of a vessel, continuously updated with data from onboard sensors and operational systems. Major container lines and operators of specialized tankers are adopting this for performance simulation and predictive health monitoring. This technology is unifying disparate data from navigation, propulsion, and cargo systems into a single, interactive model for shore-side management.
Forthcoming European Union regulations, specifically the Cyber Resilience Act (CRA), will introduce mandatory cybersecurity standards for maritime communication hardware. This legislation shifts security responsibility onto manufacturers, requiring them to implement secure-by-design principles. SATCOM terminal and IoT device suppliers targeting the EU market must therefore overhaul their development and compliance verification processes.
Vessel operators increasingly adopt "Connectivity-as-a-Service" (CaaS) models, moving away from separate hardware and airtime procurement. This subscription-based approach bundles equipment, installation, and multi-band satellite airtime into a single operational expense, disrupting traditional reseller channels. The shift is most visible among mid-sized fleets in Europe and North America seeking predictable costs and simplified vendor management.
Global Connected Ship Market Segmentation
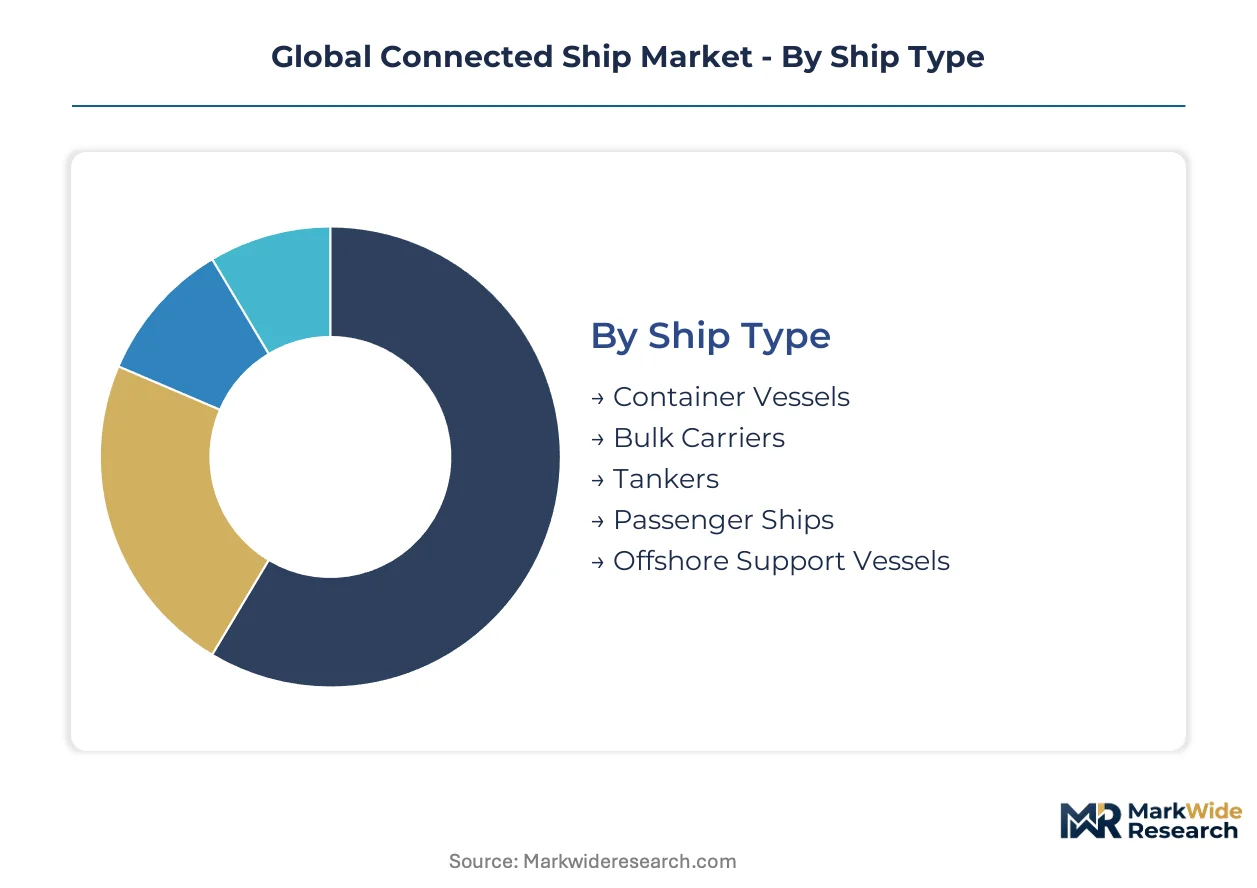
The Global Connected Ship Market is segmented to provide a granular understanding of the diverse technological and operational demands across the maritime industry. This segmentation highlights distinct investment patterns and adoption drivers, enabling targeted solution development for various stakeholders.
Ship Type:
The capital intensity associated with vessel acquisition and outfitting significantly influences connected ship technology deployment across different ship types.
- Container Vessels:These large commercial ships transport standardized cargo containers, forming the backbone of global trade. Demand for real-time cargo tracking and optimized route planning is particularly high among major shipping lines operating these vessels.
- Offshore Support Vessels:Specialized vessels, including platform supply vessels and anchor handling tugs, serve the offshore oil and gas industry. Their operational complexity and remote locations necessitate constant, high-bandwidth monitoring for safety and efficiency, driving advanced connectivity adoption.
- Bulk Carriers:These ships transport unpackaged dry bulk cargo such as grain, coal, and iron ore. Connectivity solutions for bulk carriers primarily focus on basic fleet monitoring and navigation.
- Tankers:Designed to carry liquid cargo, including crude oil, chemicals, and liquefied natural gas. Tankers require robust communication for safety protocols and environmental compliance.
- Passenger Ships:This category includes cruise ships and ferries, demanding high-capacity connectivity for passenger services alongside operational needs.
Most installed capacity flows through Container Vessels. Expansion is steepest in Offshore Support Vessels.
Technology:
The underlying technological infrastructure for connected ships varies significantly based on required data throughput, latency, and operational environment.
- SATCOM:Satellite communication systems provide pervasive, high-bandwidth connectivity essential for real-time data transmission across vast ocean expanses. These systems form the core digital link between vessels and shore-side management platforms.
- GNSS:Global Navigation Satellite Systems, including GPS and GLONASS, offer precise positioning data critical for navigation, route optimization, and location tracking. GNSS integration ensures accurate operational intelligence.
- VHF Radio:Very High Frequency radio systems provide short-range communication for line-of-sight interactions between vessels and coastal stations. These systems are fundamental for safety and local operational coordination.
- AIS:Automatic Identification System transponders broadcast vessel information, enhancing collision avoidance and maritime domain awareness. AIS data is crucial for traffic management and security.
- Radar Systems:Radar technology detects other vessels, landmasses, and weather patterns, providing essential navigational safety information. Modern radar integrates with digital platforms for enhanced situational awareness.
The foundational layer of connectivity is provided by SATCOM. GNSS drives precision applications across the fleet.
Application:
Connected ship applications are developed to address specific operational challenges, ranging from routine monitoring to predictive maintenance and critical safety functions.
- Maintenance Alerts:These applications use sensor data and analytics to provide proactive notifications about equipment health and potential failures. Predictive maintenance significantly reduces unplanned downtime and operational costs for fleet operators.
- Fleet Monitoring:Centralized systems track vessel location, speed, fuel consumption, and other key performance indicators in real time. This application enables shore-side teams to optimize operational efficiency and ensure adherence to schedules.
- Cargo Tracking:Digital solutions provide real-time visibility into the status and location of cargo containers or bulk goods. This enhances supply chain transparency and improves logistics planning for shipping companies.
- Navigation Assistance:Advanced systems integrate GNSS, electronic charts, and weather data to provide optimized routing and enhanced situational awareness. These tools reduce fuel consumption and improve safety at sea.
- Safety Management:Applications focus on emergency response, crew welfare, and regulatory compliance for safety standards. Connectivity supports remote diagnostics and timely intervention during critical incidents.
Efficiency gains are primarily realized through Fleet Monitoring. Emerging capabilities in Maintenance Alerts offer significant future value.
End User:
The connected ship market serves a diverse array of end-users, each with unique requirements and motivations for adopting digital maritime solutions.
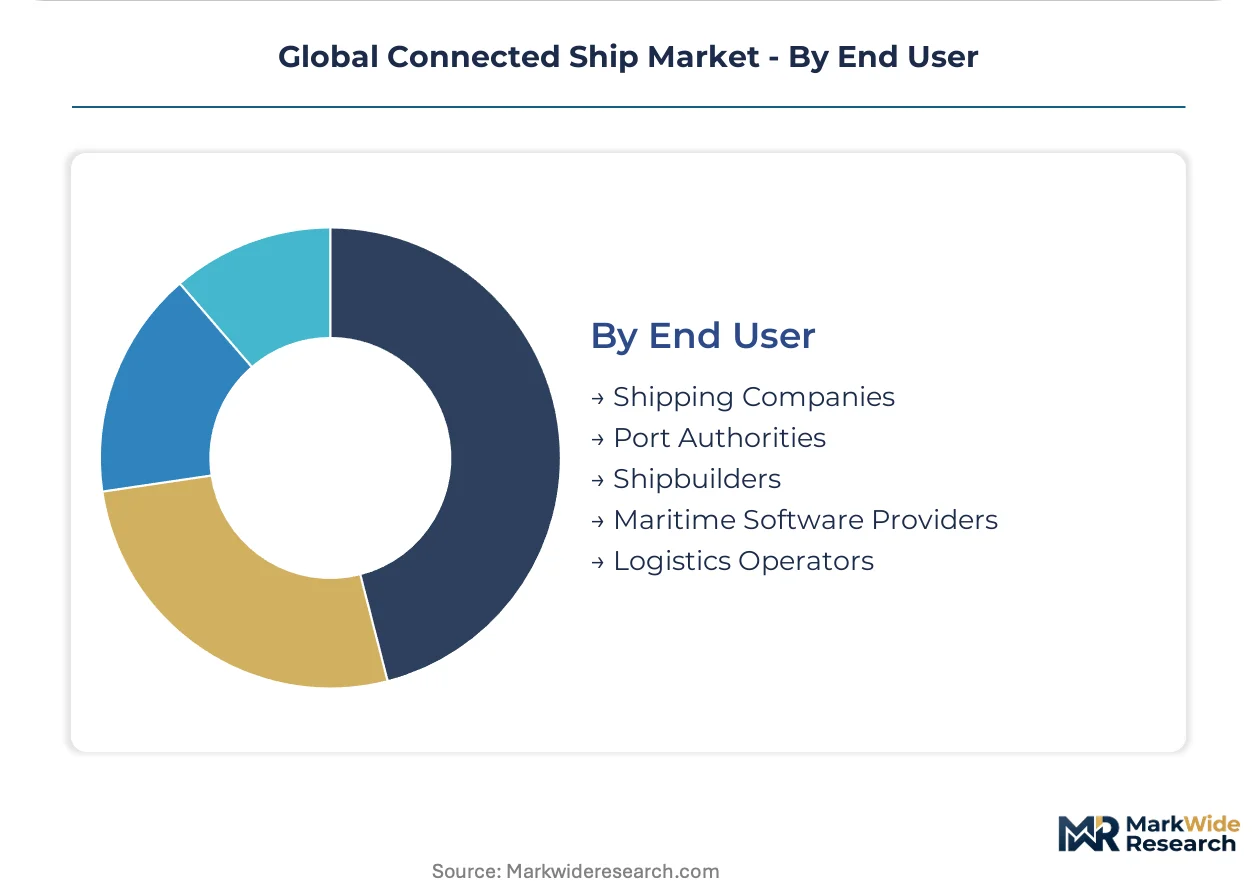
- Shipping Companies:These entities operate commercial vessels and are primary adopters of connected solutions for operational efficiency, cost reduction, and regulatory compliance. Their investment drives much of the market's growth.
- Port Authorities:Responsible for managing port operations, traffic, and security, port authorities leverage connected ship data for efficient vessel turnaround and resource allocation. They integrate with vessel systems for seamless logistics.
- Logistics Operators:Companies involved in the movement and storage of goods utilize connected ship data to optimize multimodal transport chains. This enhances transparency and predictability in global supply networks.
- Shipbuilders:Incorporating connected technologies during vessel construction to offer integrated digital platforms from the outset. Shipbuilders embed future-proofed communication and data infrastructure.
- Maritime Software Providers:These companies develop and supply the analytical tools and management platforms that process connected ship data. They enable the actionable insights derived from raw vessel information.
The primary investment in connected ship solutions originates from Shipping Companies. Collaboration with Logistics Operators is becoming increasingly vital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore, a pivotal maritime hub, drives advanced connected ship technology adoption. Its strategic location and emphasis on digital transformation initiatives compel significant investment in real-time data solutions. This region's commitment to maritime innovation influences global market trends.
Singapore
Demand for real-time cargo tracking and optimized route planning for container vessels remains high in Singapore. The Maritime and Port Authority of Singapore (MPA) actively promotes smart port technologies and digital platforms. The Port of Singapore, a global transshipment hub, continuously integrates advanced connectivity for enhanced logistics.
Netherlands
Offshore support vessels operating from the Netherlands require constant, high-bandwidth monitoring for complex operations. European CE marking requirements ensure communication hardware compliance within the region. The Port of Rotterdam spearheads initiatives for autonomous shipping and digital port management.
United States
Demand for precise positioning data and robust safety management systems is strong across the US maritime sector. The US Federal Communications Commission (FCC) sets stringent radio frequency standards for marine communication equipment. The Gulf Coast region, with its offshore energy industry, integrates advanced SATCOM for operational intelligence.
China
China's vast shipping fleet and port operations necessitate optimized route planning and efficient cargo tracking solutions. The Ministry of Industry and Information Technology (MIIT) guides the development of secure maritime communication infrastructure. Major ports like Shanghai and Ningbo-Zhoushan are at the forefront of digitalizing logistics.
Global Connected Ship Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies expand their offerings to meet the complex and evolving demands of the maritime sector. The market structure exhibits characteristics of both consolidation among established industrial players and fragmentation among specialized technology providers. Strategic archetypes include integrated solution providers, niche technology developers focusing on specific vessel needs, and defense contractors extending their communication capabilities. Technological differentiation and strategic partnerships represent dominant competitive moves within this dynamic environment.
Large industrial conglomerates and defense contractors anchor significant portions of the connected ship market. Wartsila Oyj, a Finnish corporation, exemplifies an integrated solutions provider, offering a broad portfolio across vessel systems and operational platforms. Kongsberg Gruppen, a Norwegian technology group, occupies a position as a specialist in advanced sensor and autonomous navigation systems for various maritime applications. Northrop Grumman Corporation, a US-based aerospace and defense technology company, represents the extension of defense-grade communication into commercial maritime applications, leveraging its robust heritage.
| Leading Market Players |
|---|
| Wartsila Oyj |
| Schneider Electric |
| Kongsberg Gruppen |
| Emerson Electric Co. |
| ABB Ltd. |
| Northrop Grumman Corporation |
| General Electric Company |
| Rockwell Automation Inc. |
| Marlink |
| Others |
Cost & Logistics Intelligence
The connected ship market shows a clear divergence between high-end, integrated solutions and basic connectivity offerings. This split influences both subscription pricing models and the complexity of hardware and service supply chains.
Pricing Analysis
Input cost pass-through for satellite bandwidth significantly impacts connected ship service pricing. Connectivity-as-a-Service (CaaS) models dominate, with premium-mid-economy pricing differentiation driven by service level agreements and data security certifications. Pricing pressure stems from increased competition among SATCOM providers and the deployment of LEO constellations. Smaller fleet operators are most price-sensitive, while major shipping companies prioritize reliability and advanced features.
Supply Chain Analysis
Regional distribution centers in maritime hubs like Singapore and Rotterdam manage hardware logistics for connected ship components. Key SATCOM hardware manufacturing concentrates in the United States and Europe, drawing from specialized semiconductors and high-frequency communication modules. Single-source vulnerability for specific satellite modem chipsets presents a structural risk. Installation and maintenance services typically run through a network of certified local partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion characterizes the connected ship market, primarily driven by the shift towards high-value data analytics and predictive maintenance services. This premium-tier evolution enables providers to capture greater value beyond basic connectivity offerings.
For Market Incumbents: Extend integrated solution portfolios to encompass advanced cybersecurity services, countering escalating cyber threats. Incumbents must invest in robust R&D for AI-driven operational intelligence platforms, leveraging existing client relationships. This strategy defends against specialized software providers entering the value chain. Wartsila Oyj can enhance its integrated solutions.
For New Entrants and Emerging Players: Launch cost-effective connectivity solutions via regional maritime equipment distributors, targeting underserved vessel segments like fishing fleets. New entrants can focus on specialized applications such as real-time emissions monitoring for coastal carriers. This approach exploits market fragmentation among smaller operators. A go-to-market angle involves bundling basic SATCOM with essential IoT sensors.
For Investors and Strategic Acquirers: Consolidation pressure builds where smaller, specialized software providers lack capital for global scaling and compliance. Long-term viability (5-10 year window) favors providers offering comprehensive, secure, integrated operational platforms. Acquisition targets include niche edge computing firms or specialized AI analytics developers. The signal to watch is increasing adoption of Connectivity-as-a-Service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Decarbonization Platforms | Optimizes fuel consumption for container vessels, directly addressing IMO 2030 emissions targets. |
| Expand Secure Edge Computing Solutions | Reduces satellite transmission costs for offshore support vessels while enhancing local data processing. |
| Pursue Global Cyber Resilience Act Compliance | Ensures communication hardware meets stringent EU regulations, critical for European market access. |
| Form Connectivity-as-a-Service Partnerships | Simplifies procurement for shipping companies, driving broader adoption among mid-sized fleets. |
| Integrate Digital Twin Technology | Provides dynamic virtual vessel replicas, improving predictive maintenance for specialized tankers. |
Research Approach
Bottom-up shipping company operational modeling reconciled against top-down SATCOM provider capacity tracking forms the analytical core. This study combined primary interviews with industry stakeholders and secondary validation from diverse sources. Primary insights came from maritime IT directors, port authority officials, vessel operators, and SATCOM solution architects. Secondary data included IMO conventions, FCC filings, and industry reports.
Historical trendline analysis informed the projection of market growth across the analysis window. The segmentation dimensions modeled included ship type, technology, application, and end-user, alongside regional maritime activity. Compound annual growth rates were derived from a multi-variant regression model incorporating technological advancements and regulatory impacts. Key forecast inputs included vessel build rates and SATCOM bandwidth cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory shifts or unforeseen geopolitical events impacting maritime trade. Forecasts reflect assumptions regarding technological adoption curves and global economic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global Maritime Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Europe Inland Water Freight Transport Market