
 Drill Ships Market | 2026-2036
Drill Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Ships Market Analytics
The EU Green Deal is hardening emissions benchmarks for offshore drilling contractors serving European oil majors. Transocean Ltd. leverages its ultra-deepwater fleet scale to secure long-term charters with integrated operators. Seadrill Limited anchors its competitiveness through harsh-environment rig specialization in the North Sea and Norwegian sectors. Samsung Heavy Industries dominates newbuild construction for high-specification drill ships with advanced dynamic positioning systems.
A drill ship is a self-propelled monohull vessel equipped with a moonpool-centered drilling derrick, dynamic positioning thrusters maintaining station within meter-scale accuracy, and subsea blowout preventer stacks enabling operations at water depths exceeding 3,000 meters. Its primary purpose is exploratory and development drilling in deepwater and ultra-deepwater provinces inaccessible to fixed platforms or jack-up rigs. Ultra-Deepwater Drill Ships command the premium charter rate tier due to scarcity of seventh-generation assets capable of 12,000-foot water depths. Oil Exploration applications absorb the majority of contracted rig years, while Natural Gas Extraction is gaining share as pre-salt and Lower Tertiary plays mature. Offshore Deployment configurations generate substantially all revenue, with High Seas operations representing the fastest-growing operational envelope.
The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce structural and operational standards for foreign-flagged drill ships in American waters, while the International Maritime Organization's Carbon Intensity Index is reshaping fleet efficiency requirements globally. Brazil's national petroleum regulator mandates local content thresholds that influence equipment sourcing and shipyard selection for pre-salt field development. Stakeholders must weigh charter duration commitments against technology obsolescence risk as dual-fuel and hybrid propulsion architectures enter commercial deployment.
Market Dynamics
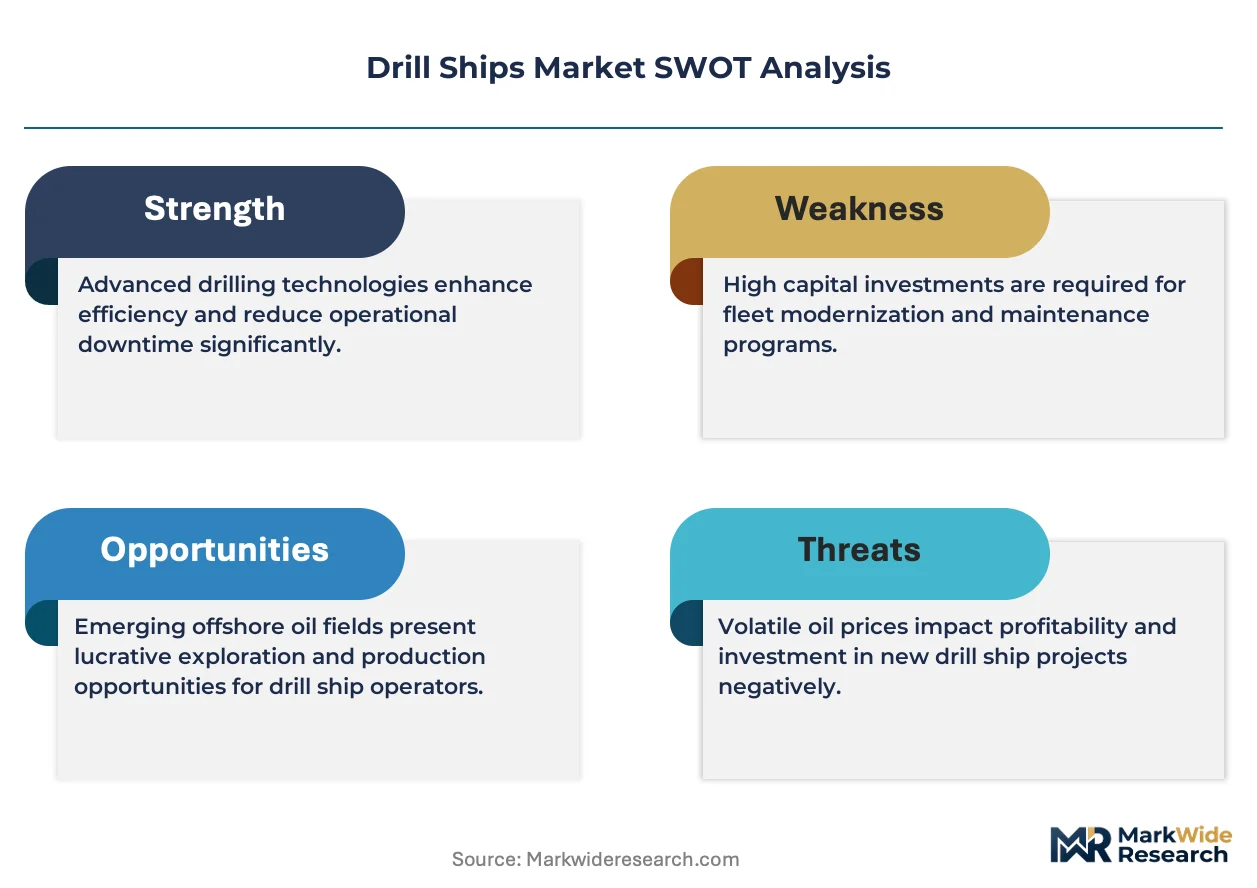
Seventh-generation drill ship specifications are forcing fleet obsolescence across the contractor base as charterers demand dual-fuel capability and 20,000 psi well control systems for pre-salt development.
Growth Catalysts
- Brazil's Pre-Salt Local Content Mandates:The national petroleum regulator requires minimum domestic equipment sourcing, redirecting shipyard contracts toward South Korean and Singaporean yards with established Brazilian partnerships.
- EU Green Deal Methane Rules:Tightening offshore equipment standards are accelerating replacement of legacy blowout preventer stacks with sealed systems that reduce fugitive emissions during deepwater operations.
- Lower Tertiary Play Maturation:Ultra-deepwater provinces in the Gulf of Mexico and West Africa are absorbing contracted rig years as exploration shifts from appraisal to full-field development.
Market Restraints
- High-Specification Steel Alloy Costs:Specialized grades for moonpool reinforcement and derrick structures face price volatility tied to nickel and molybdenum supply concentration in Indonesian and Russian mining operations.
- Dynamic Positioning System Supplier Concentration:A handful of European and Japanese marine automation specialists control thruster control software, creating single-source risk for newbuild programs.
- IMO Carbon Intensity Index Compliance:Existing diesel-electric architectures face operational penalties or retrofit requirements that compress residual asset values for mid-generation vessels.
Strategic Opportunities
- Hybrid Propulsion Retrofit Programs:Battery-hybrid energy storage integration offers fuel consumption reductions that extend economic life of sixth-generation assets in mid-cycle markets.
- Arctic Harsh-Environment Specialization:Ice-class drill ship demand from Norwegian and Russian frontier basins remains underserved relative to temperate-water fleet capacity.
- Digital Twin Charter Models:Real-time structural monitoring and predictive maintenance subscriptions are creating recurring revenue streams separate from day-rate contracting.
Industry Challenges
- Subsea BOP Stack Maintenance Certification:Factory acceptance testing and recertification timelines for 20,000 psi ram configurations extend mobilization windows and compress effective operating days.
- Dual-Fuel Engineering Talent Scarcity:LNG bunkering system design and cryogenic handling expertise resides within a narrow contractor pool concentrated in South Korean ship engineering consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Ships Market |
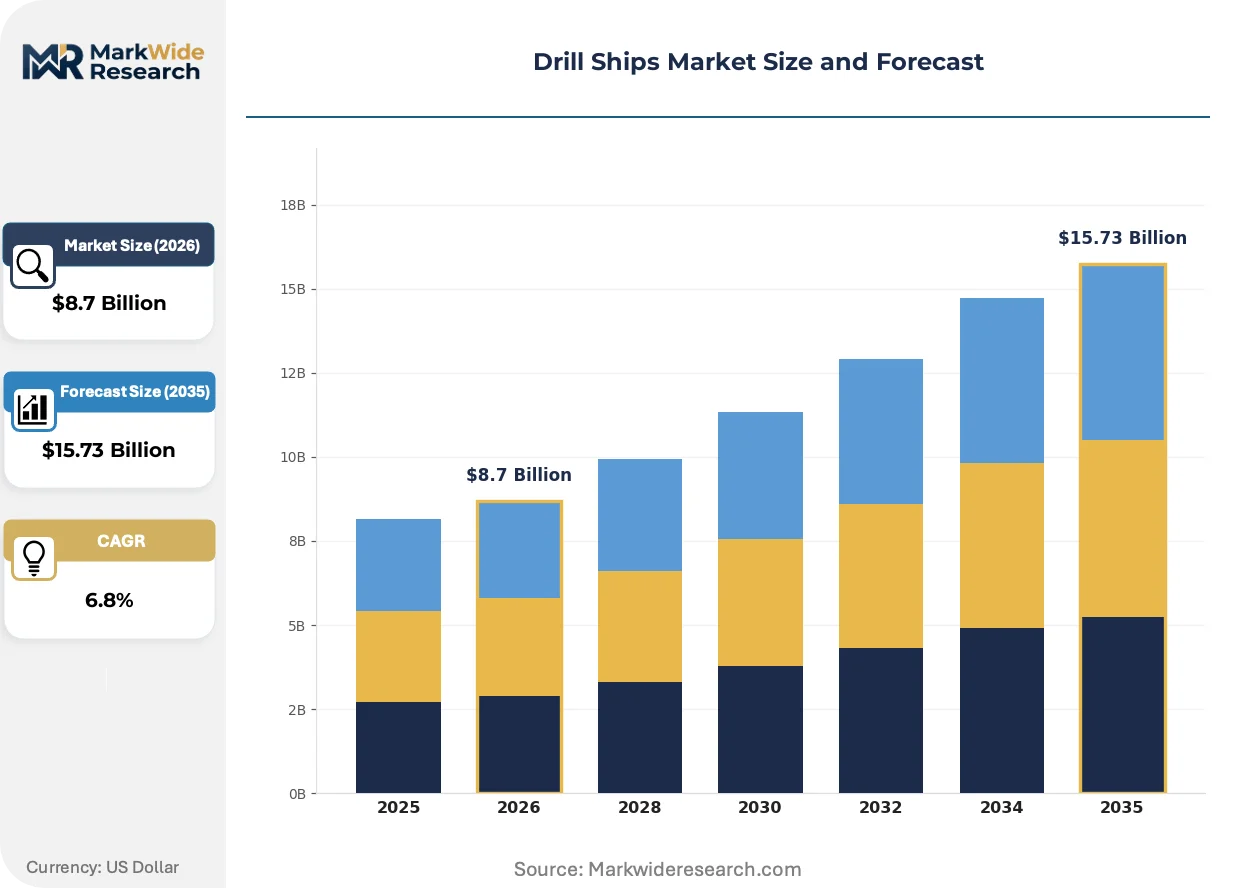
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deepwater Drill Ships, Ultra-Deepwater Drill Ships, Semi-Submersible Drill Ships, Tender Assist Drill Ships Application: Oil Exploration, Natural Gas Extraction, Scientific Research, Offshore Construction End User: Oil & Gas Companies, Government Agencies, Research Institutions, Offshore Service Operators Deployment: Onshore, Offshore, Nearshore, High Seas |
| Companies Covered | Transocean Ltd., Seadrill Limited, Valaris plc, Noble Corporation plc, Diamond Offshore Drilling, Saipem SpA, China Oilfield Services Ltd., Maersk Drilling, Samsung Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Ships Market Evolving Landscape
Automation architectures and alternative propulsion systems are restructuring capital deployment patterns among drilling contractors and integrated operators.
Subsea wellhead connector systems are modularizing around standardized interface geometries that reduce custom engineering for each field development. Integrated operators in Brazil and West Africa are specifying these interfaces in charter tenders to compress mobilization timelines. This standardization is modularizing supplier ecosystems around interchangeable component families rather than bespoke wellhead stacks.
The EU Green Deal's methane emissions monitoring mandates are requiring continuous leak detection instrumentation on all offshore drilling equipment serving European majors. Contractors must install infrared camera networks and sealed BOP designs that eliminate atmospheric venting during connection operations. Ultra-deepwater segments face the steepest compliance costs due to higher-pressure well control complexity.
Charter contracting is compressing toward shorter-duration, well-specific assignments rather than multi-year field development programs. Independent operators in the Gulf of Mexico are driving this shift, substituting spot-market availability for committed fleet positions. This rotation is most visible in US waters where regulatory clarity from the Bureau of Safety and Environmental Enforcement supports rapid permit-to-spud timelines.
Drill Ships Market Segmentation
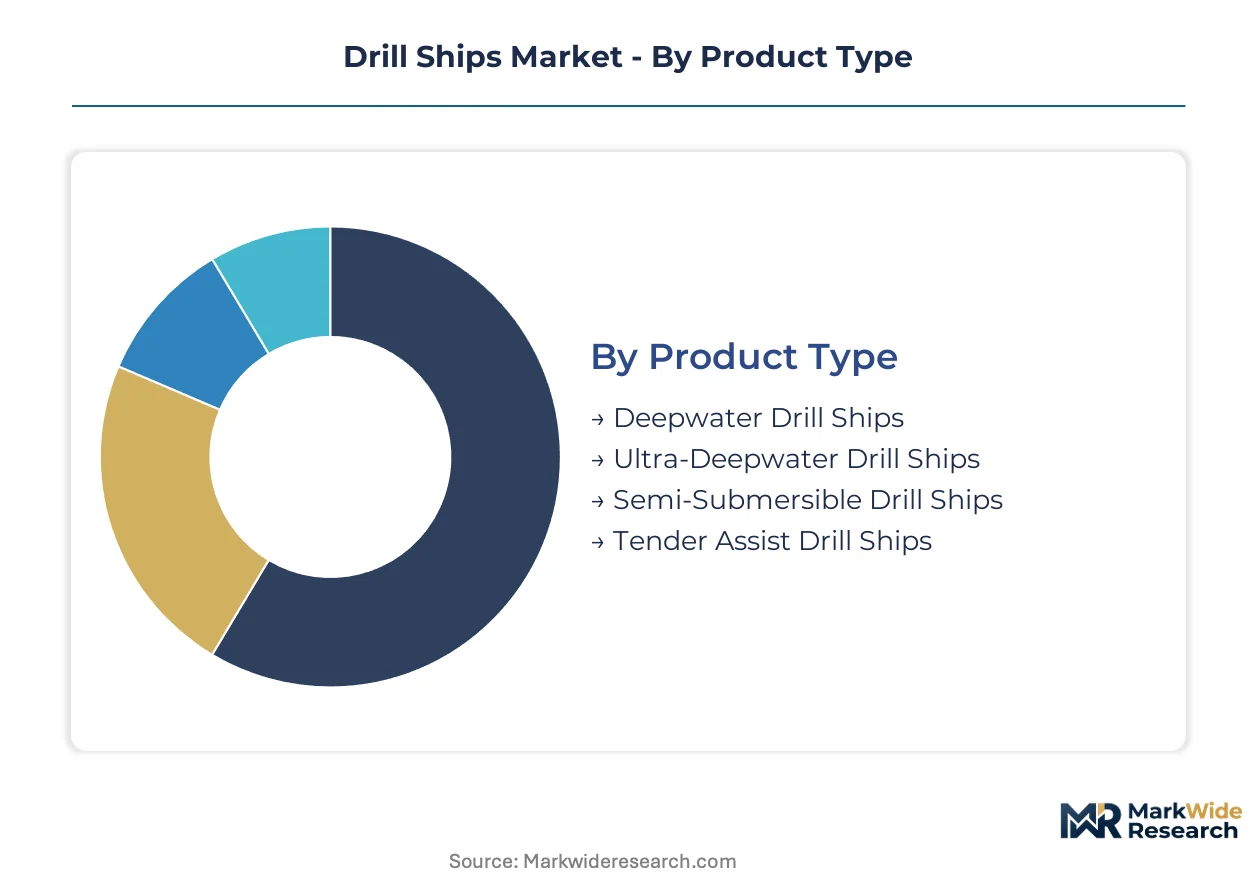
Segmentation in the drill ships market reflects divergent capital intensity, technical specifications, and charter duration preferences across operator archetypes. Contractor fleet positioning and integrated operator procurement strategies concentrate differently across each dimension, shaping build-to-spec programs and secondhand transaction liquidity.
Product Type:
Charter rate tiers and water depth capability separate buyers with pre-salt development mandates from those serving mature basin workover programs.
- Ultra-Deepwater Drill Ships:Seventh-generation assets equipped with 20,000 psi well control systems and dual-fuel propulsion command premium day rates for pre-salt development in Brazil's Santos Basin. Demand concentrates with integrated operators holding 10-year field development commitments requiring 12,000-foot water depth capability.
- Deepwater Drill Ships:Sixth-generation units with 10,000-foot ratings and conventional diesel-electric architecture serve Gulf of Mexico and West African exploration programs. Charter contracting favors shorter-duration well tests as independent operators substitute spot-market availability for committed fleet positions.
- Semi-Submersible Drill Ships:Twin-hull designs offer superior motion characteristics for harsh-environment North Sea and Norwegian sectors.
- Tender Assist Drill Ships:Platform-supported configurations reduce capital outlay for shallow-water development drilling in Southeast Asian mature basins.
Volume sits with Deepwater Drill Ships; growth tilts toward Ultra-Deepwater Drill Ships.
Application:
Reserve replacement economics and carbon intensity benchmarks reshape allocation of contracted rig years across hydrocarbon types and non-extraction services.
- Oil Exploration:Wildcat and appraisal drilling in frontier basins absorbs the majority of ultra-deepwater fleet capacity, with Lower Tertiary plays in the Gulf of Mexico and West Africa transitioning from exploration to full-field development. EU Green Deal methane rules are tightening equipment specifications for European major charters.
- Natural Gas Extraction:Pre-salt gas cap development and Lower Tertiary gas-condensate discoveries are gaining contracted rig share as fields mature. Brazil's national petroleum regulator mandates local content thresholds that influence equipment sourcing for gas development programs.
- Scientific Research:Academic and governmental ocean drilling programs utilize modified drill ships for sediment core retrieval and subseafloor observatory installation.
- Offshore Construction:Pipelay and subsea infrastructure installation applications repurpose idle drilling assets in secondary equipment markets.
Revenue concentrates in Oil Exploration; Natural Gas Extraction is expanding most quickly.
End User:
Balance sheet capacity and charter duration risk tolerance stratify the customer base across integrated majors, national oil companies, and speculative independents.
- Oil & Gas Companies:Supermajors and national oil companies drive newbuild demand with 5-10 year charter commitments for pre-salt and ultra-deepwater development. Integrated operators in Brazil and West Africa are specifying standardized subsea wellhead interfaces to compress mobilization timelines.
- Offshore Service Operators:Contract drilling specialists with fleet ownership models compete on day-rate positioning and operational efficiency in spot-market segments.
- Government Agencies:State-backed exploration programs in frontier jurisdictions utilize sovereign-chartered assets for resource assessment drilling.
- Research Institutions:International ocean drilling programs operate dedicated scientific vessels with modified derrick configurations for core retrieval missions.
Contracted years cluster with Oil & Gas Companies; Research Institutions show the steepest expansion trajectory for specialized vessel modifications.
Deployment:
Regulatory jurisdiction and environmental operating envelope determine thruster specification, ice-class notation, and dynamic positioning redundancy requirements.
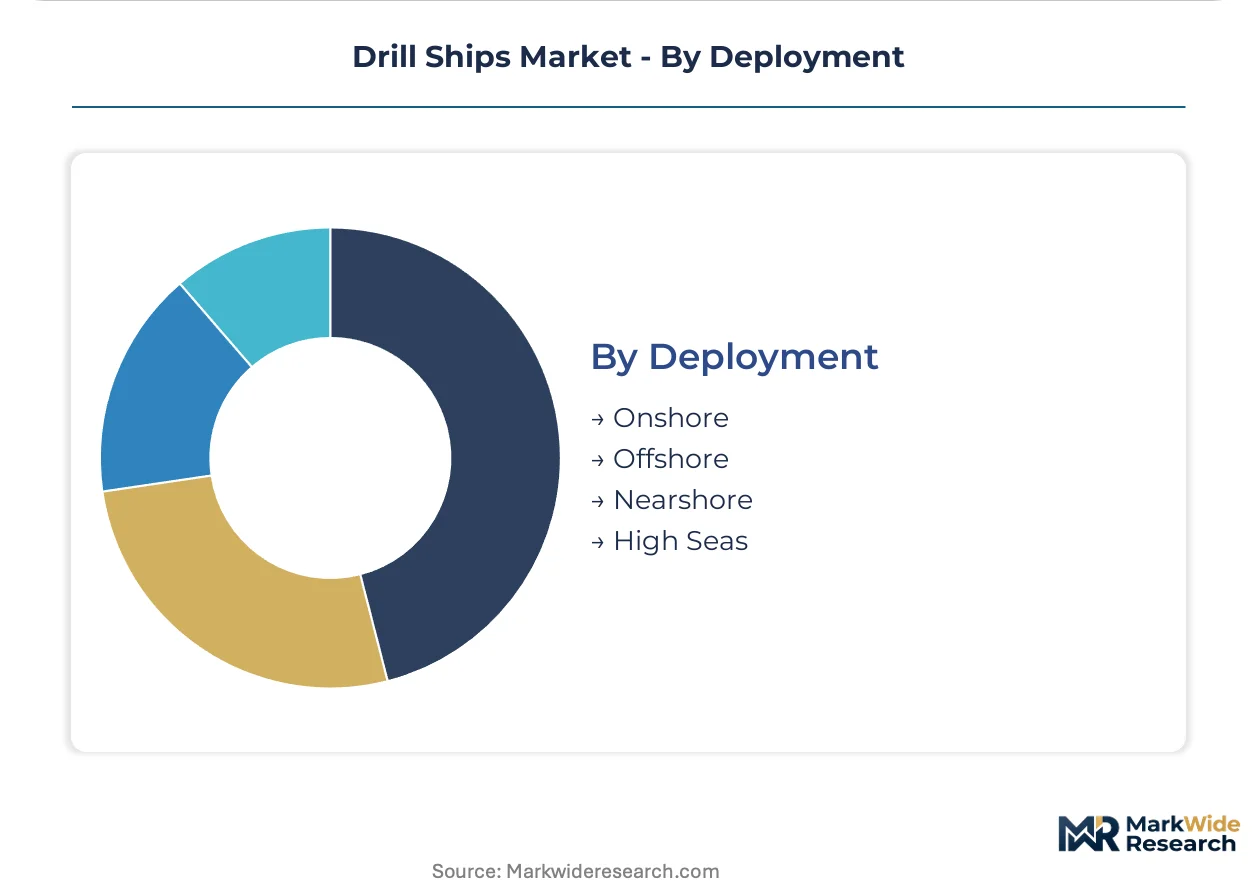
- Offshore:Continental shelf and slope drilling in 500-3,000 meter water depths generates the preponderance of fleet revenue, with Brazil's pre-salt local content mandates redirecting shipyard contracts toward South Korean and Singaporean yards with established Brazilian partnerships.
- High Seas:Ultra-deepwater operations beyond 3,000 meters in frontier basins command premium charter tiers due to scarcity of seventh-generation assets.
- Nearshore:Shallow-water shelf drilling utilizes tender-assisted configurations for platform-supported development programs.
- Onshore:Shipyard commissioning, repair, and cold-stacking status represents non-revenue deployment for fleet rationalization periods.
Operating days accumulate in Offshore deployment; High Seas operations are climbing the fastest as frontier basins mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's energy corridor concentrates the headquarters of drill ship charterers and fleet operators serving ultra-deepwater provinces across the Atlantic margin.
Brazil
Pre-salt development in the Santos Basin absorbs the majority of seventh-generation newbuild capacity. ANP local content mandates redirect equipment sourcing toward South Korean shipyards with established Brazilian partnerships. Rio de Janeiro anchors the offshore services cluster where Petrobras coordinates integrated development programs.
United States
Lower Tertiary play maturation in the Gulf of Mexico sustains demand for dual-fuel capable assets. The Bureau of Safety and Environmental Enforcement enforces structural standards that compress permit-to-spud timelines. Houston hosts the contractor headquarters managing spot-market chartering for independent operators.
Norway
Harsh-environment specialization in the Norwegian Sea and Barents Sea drives ice-class specification requirements. Petroleum Safety Authority regulations mandate redundant dynamic positioning systems for frontier basin operations. Stavanger concentrates engineering consultancies designing Arctic-capable thruster configurations.
South Korea
Newbuild construction for high-specification drill ships dominates yard capacity at Samsung Heavy Industries and Hyundai Heavy Industries. MFDS maritime safety standards align with IMO Carbon Intensity Index compliance trajectories. Ulsan and Geoje shipbuilding clusters integrate battery-hybrid propulsion architectures into seventh-generation designs.
United Kingdom
North Sea decommissioning and remaining field development sustain mid-generation asset utilization. HSE offshore safety regulations influence blowout preventer recertification standards adopted by international contractors. Aberdeen maintains the subsea engineering cluster supporting BOP stack maintenance programs.
Drill Ships Market Competitive Landscape
Premium-margin players sit above commodity-margin players across water depth capability and dual-fuel specification tiers. The contractor base concentrates around fleet-scale specialists, harsh-environment niche operators, and integrated oilfield service conglomerates. Three archetypes dominate: ultra-deepwater pure-plays commanding long-term charters, diversified drilling contractors balancing spot-market exposure, and shipyard-affiliated lessors controlling newbuild pipelines. Competitive dynamics revolve around charter duration commitments against technology obsolescence risk, and strategic partnerships with national oil companies securing pre-salt development mandates.
Among Switzerland-based fleet operators, Transocean Ltd. exemplifies the ultra-deepwater pure-play archetype through its concentration of seventh-generation assets. Seadrill Limited, operating from London, occupies a position within the diversified contractor tier balancing harsh-environment North Sea exposure with ultra-deepwater capability. China Oilfield Services Ltd. represents the national oil company-affiliated structure, anchoring the state-backed competitive vector serving domestic and international pre-salt programs.
| Leading Market Players |
|---|
| Transocean Ltd. |
| Seadrill Limited |
| Valaris plc |
| Noble Corporation plc |
| Diamond Offshore Drilling |
| Saipem SpA |
| China Oilfield Services Ltd. |
| Maersk Drilling |
| Samsung Heavy Industries |
| Others |
Value Network & Pricing Analysis
Cryogenic handling specialists concentrated in South Korean engineering consultancies command wage premiums that widen spreads between dual-fuel capable seventh-generation assets and conventional diesel-electric sixth-generation units. Labor-cost differentials for LNG bunkering system expertise translate directly into charter rate tiering as operators pass through certification-driven crew premiums.
Pricing Analysis
Day-rate benchmarking anchored to operational uptime and well control reliability dominates contract structures for ultra-deepwater assets. Three-tier pricing structure across premium, standard, and economy levels separates seventh-generation dual-fuel drill ships from sixth-generation conventional units and mid-generation cold-stacked alternatives. Price differentiation rests on IMO Carbon Intensity Index compliance status and 20,000 psi BOP certification tier. Pricing pressure stems from shorter-duration well-specific chartering compressing effective revenue days. Independent operators in Gulf of Mexico waters exhibit highest price sensitivity; integrated majors holding pre-salt development mandates show lowest.
Supply Chain Analysis
ABS and DNV classification society qualifications gate entry for moonpool steel suppliers and dynamic positioning system integrators. Manufacturing gravity centers on South Korea, Singapore, and China for hull construction and topside integration. Raw material dependencies include nickel-molybdenum alloy grades for high-pressure well control components, advanced marine automation software from European and Japanese specialists, and subsea BOP ram configurations from concentrated OEM channels. Single-source vulnerability runs through thruster control software licensors. Distribution runs through shipyard-direct contracting with integrated operators and contractor fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal methane rules erect capital barriers that moat compliant seventh-generation fleets against legacy asset competition.
For Market Incumbents: Acquire sixth-generation assets with hybrid retrofit potential to extend economic life against newbuild competition. Consolidate positions in Brazilian pre-salt chartering through ANP local content partnerships with South Korean yards. Defensive priority centers on dual-fuel engineering talent capture from narrow South Korean consultancy pools.
For New Entrants and Emerging Players: Arctic-capable independent operators remain underserved relative to ice-class fleet capacity. Target Norwegian and Russian frontier basin operators seeking harsh-environment specialization absent from temperate-water contractor portfolios. White-space entry favors battery-hybrid retrofit services for mid-generation assets in North Sea and UK decommissioning markets. Go-to-market leverage rests on digital twin predictive maintenance subscriptions creating recurring revenue separate from day-rate exposure.
For Investors and Strategic Acquirers: Re-rating potential sits with diversified contractors holding sixth-generation fleets and hybrid retrofit capabilities given IMO Carbon Intensity Index compliance trajectories. Long-term viability over a multi-year horizon favors asset-light digital service layers over steel-heavy newbuild exposure. Acquisition focus targets engineering consultancies with cryogenic LNG system design expertise. Signal to monitor: ANP local content threshold adjustments redirecting shipyard contract flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Retrofit | Extends sixth-generation asset competitiveness under IMO Carbon Intensity Index compliance requirements. |
| ANP Local Content Partnership | Secures Brazilian pre-salt charter access through South Korean shipyard alliance structures. |
| Digital Twin Service Layer | Creates recurring predictive maintenance revenue separate from volatile day-rate contracting exposure. |
| Arctic Ice-Class Certification | Captures underserved Norwegian Sea and Barents Sea frontier basin demand. |
| Cryogenic Engineering Talent Acquisition | Locks scarce LNG bunkering system design capability from concentrated South Korean consultancy base. |
Research Methodology
Regulatory filings from ANP, US Bureau of Safety and Environmental Enforcement, and IMO Marine Environment Protection Committee formed the secondary backbone for compliance trajectory mapping. Primary interviews with offshore drilling contractors, integrated operator procurement leads, shipyard program managers, and subsea equipment OEMs validated charter contracting patterns and newbuild specification trends. Customs and trade data, SEC 10-K fleet disclosures, and shipyard orderbook databases supplied volume and value anchors. Bottom-up rig-by-rig capacity modeling triangulated against top-down operator capital expenditure surveys.
Bottom-up segmentation by water depth capability, propulsion architecture, and regional deployment configuration anchored the analytical framework across the projection horizon. Modeled dimensions included product type tier, application split between oil exploration and gas extraction, end-user balance sheet capacity, and operational envelope from nearshore through high seas. CAGRs were derived from rig supply-demand balance projections and day-rate elasticity assumptions. Industry-specific forecast inputs incorporated ANP local content mandate enforcement timelines and EU Green Deal equipment standard phase-in schedules.
Revisions become necessary when ANP local content thresholds shift, EU methane monitoring mandates accelerate, or dual-fuel propulsion technology costs experience step-change reduction. Forecasts reflect assumptions about charter duration preferences, shipyard delivery schedules, and frontier basin exploration permit timelines. A model refresh is warranted upon material change in IMO Carbon Intensity Index penalty structures or Brazilian pre-salt field development commitment flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Plate Market