
 Global PE Films Market | 2026-2036
Global PE Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global PE Films Market Foresight
Market Context
Southeast Asia is reconfiguring regional supply dynamics through new blown film extrusion complexes in Vietnam and Thailand. Amcor PLC leverages vertical integration across resin sourcing and converter networks to sustain margin stability. Berry Global Group anchors North American flexible packaging demand through scale manufacturing of high-performance barrier grades. Sigma Plastics Group competes on specialized industrial liner formulations for chemical containment applications.
Technical Definition and Segment Structure
PE films are thermoplastic polymer sheets manufactured from ethylene-derived resins, typically ranging from 12 microns to 250 microns in gauge, produced via cast, blown, or co-extrusion processes to deliver moisture barriers, chemical resistance, and sealability for packaging and protective applications. Linear low-density PE dominates volume production due to its puncture resistance and down-gauging compatibility in stretch wrap and heavy-duty sack applications. Blown films command premium positioning in agricultural mulch and construction vapor barrier segments where thickness uniformity and directional strength properties determine performance. Co-extruded films capture expanding share in food packaging as processors specify oxygen barrier layers for extended shelf-life requirements.
Regulatory Framework and Outlook
REACH registration requirements in Europe, FDA food contact substance notifications in the United States, and China's GB standards for plastic packaging govern material composition, migration limits, and recyclability claims across major demand centers. ECHA restrictions on intentionally added microplastics and California's SB 54 extended producer responsibility framework are reshaping formulation roadmaps toward certified recycled content and design-for-recycling architectures. Stakeholders must monitor evolving Extended Producer Responsibility schemes and polymer-specific recycling targets to align capacity investments with compliance-ready product portfolios.
Market Dynamics
Mono-material recyclable film architectures are compressing multi-layer barrier structures as EU Green Deal compliance deadlines force converters to redesign packaging formats without sacrificing shelf-life performance.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' 2030 recyclability targets compel food brands to specify certified mono-material PE grades, pulling investment toward compatible extrusion and sealing technologies.
- Blown film capacity expansion:Vietnam and Thailand are adding blown film lines to serve regional agrochemical and construction membrane demand, shifting supply gravity within Southeast Asia.
- Bio-based ethylene feedstocks:Sugar cane-derived and waste-to-ethylene routes are achieving scale parity in select Brazilian and Indian supply contracts, enabling carbon footprint claims for export-sensitive consumer goods.
Market Restraints
- Crude-linked resin volatility:Naphtha and ethane feedstock costs swing with Brent crude movements, compressing converter margins during inventory valuation cycles.
- Chinese domestic capacity overhang:State-supported petrochemical complexes in Zhejiang and Shandong provinces are adding LLDPE film-grade output faster than regional demand absorption.
- Oxygen barrier limitations:Unmodified PE films require metallization or coating to match EVOH or PA barrier performance in modified-atmosphere meat packaging.
Strategic Opportunities
- India organized retail penetration:Reliance Retail and DMart expansion into tier-2 cities is creating first-time demand for pre-packaged produce films with printed branding surfaces.
- California SB 54 EPR frameworks:Extended producer responsibility rules are mandating post-consumer recycled content thresholds, advantaging converters with early mechanical recycling partnerships.
- Digital printing convergence:HP Indigo and EFI inkjet presses are enabling short-run customized film graphics without cylinder costs, collapsing minimum order quantities for regional food brands.
Industry Challenges
- Migration testing bottlenecks:FDA food contact substance notifications and EFSA evaluations for novel co-extruded structures face 18-24 month review timelines, delaying commercial launches.
- Mechanical recycling feedstock quality:Collection infrastructure gaps produce contaminated post-consumer PE streams that fail food-grade pellet specifications, limiting closed-loop claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PE Films Market |
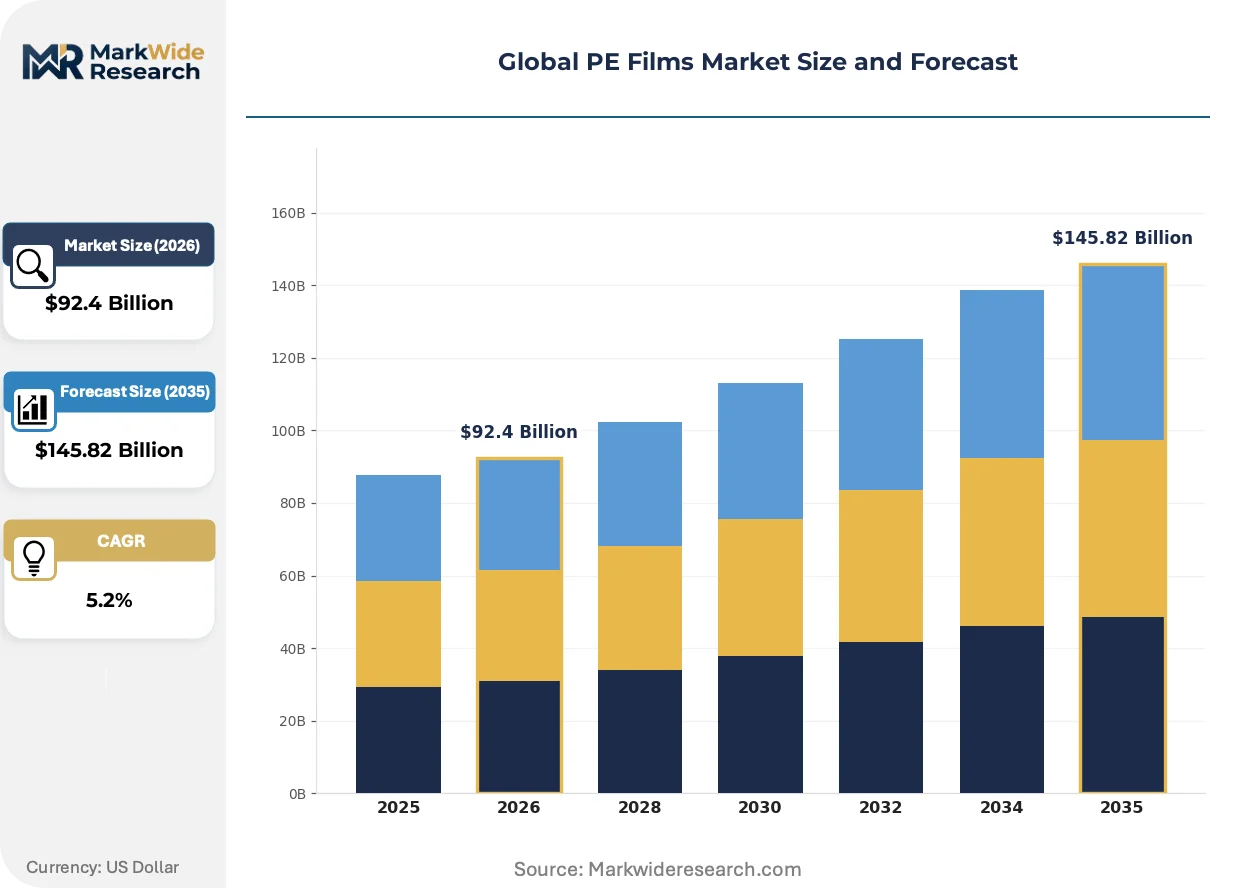
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $145.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density PE, High-Density PE, Linear Low-Density PE, Medium-Density PE, Cross-Linked PE Application: Packaging, Agriculture Mulch Films, Construction Vapor Barriers, Industrial Liners, Consumer Goods Wrapping End User Industry: Food & Beverage Manufacturers, Agricultural Producers, Building Contractors, Industrial Fabricators, Consumer Goods Producers Form: Cast Films, Blown Films, Tubular Films, Co-extruded Films, Laminated Films |
| Companies Covered | Avient, Sigma Plastics Group, Amcor PLC, Inteplast Group, Novolex Holdings, Berry Global Group, Winpak, Reynolds Consumer Products, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PE Films Market Shifts & Advancements
Digital process control and materials informatics are compressing development cycles for film formulations that must simultaneously satisfy barrier, seal, and recyclability specifications.
Machine learning-driven rheology modeling is virtualizing the traditional trial-and-error approach to multi-layer co-extrusion die design. European barrier film specialists are deploying these tools to predict melt flow distribution across spiral mandrel geometries before physical prototyping. The technology is virtualizing months of tooling iteration into simulation cycles, accelerating time-to-market for oxygen-scavenging film structures.
REACH restrictions on intentionally added microplastics are forcing reformulation of anti-block and slip additives in agricultural mulch films. ECHA's 2023-2027 restriction roadmap targets conventional masterbatch chemistries used in soil-contact applications. Agricultural film converters in Spain and Italy are responding with bio-based additive packages and accelerated biodegradation certification pathways.
Brand-led specification of mass-balance certified recycled content is displacing virgin resin in premium personal care packaging. Unilever and Procter & Gamble procurement teams are inserting ISCC PLUS chain-of-custody requirements into flexible packaging tenders. This specification shift is most visible in Western European cosmetics and home care segments where shelf-facing sustainability claims command retail placement premiums.
Global PE Films Market Segmentation
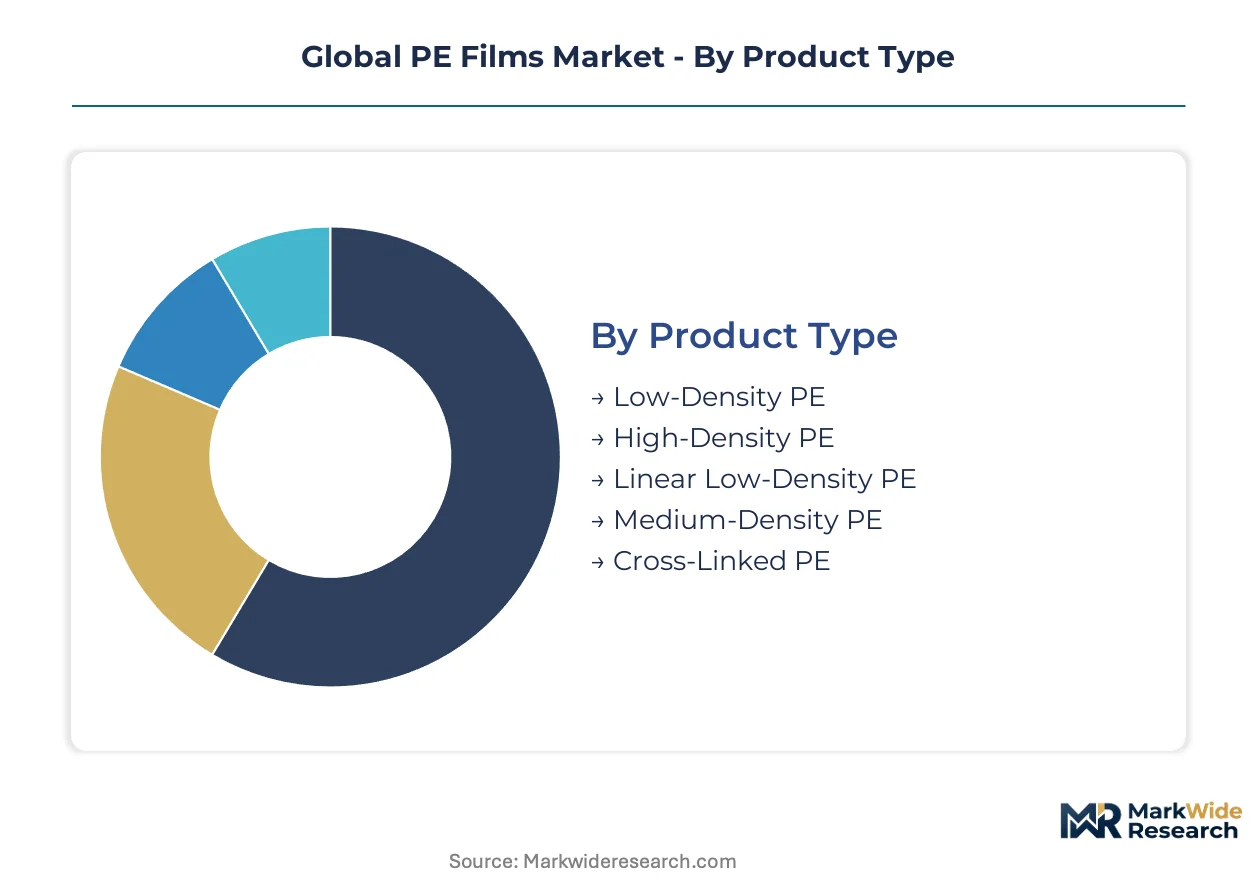
PE film specifications diverge sharply across resin chemistry, conversion method, and end-use performance requirements. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Mature commodity grades dominate tonnage, while specialty modified resins capture expanding specification-driven demand.
- Low-Density PE:Branched polymer structure delivers optical clarity and softness for bread bags and garment covers. Clarity requirements in French retail packaging sustain demand despite down-gauging pressure from linear low-density alternatives.
- Linear Low-Density PE:Linear backbone with short-chain branching provides puncture resistance and stretch recovery. Heavy-duty sack applications in Brazilian agribusiness and Indian fertilizer packaging absorb the majority of global LLDPE film-grade output.
- High-Density PE:Crystalline structure yields stiffness and moisture barrier for retail carry bags and industrial drum liners.
- Medium-Density PE:Intermediate density balances toughness and processability for shrink hoods and collation films.
- Cross-Linked PE:Covalent bonding through peroxide or irradiation creates heat-resistant films for cable insulation and medical sterilization pouches.
Linear Low-Density PE retains volume leadership; Cross-Linked PE holds the steepest expansion curve.
Application:
Application mix tracks directly to construction cycles, agricultural planting seasons, and consumer packaged goods procurement patterns.
- Packaging:Flexible primary and secondary formats span food contact, industrial, and retail segments. Mono-material recyclable specifications under EU Green Deal timelines are forcing rapid redesign of multi-layer barrier structures.
- Agriculture Mulch Films:Soil-contact films regulate temperature, suppress weeds, and reduce irrigation demand. Italian and Spanish growers face ECHA restrictions on conventional additive masterbatches, accelerating bio-based formulation shifts.
- Construction Vapor Barriers:Moisture-blocking membranes protect building envelopes from condensation damage.
- Industrial Liners:Chemical containment and bulk material handling films serve drum, IBC, and tank applications.
- Consumer Goods Wrapping:Printed and clear films protect textiles, electronics, and household products through distribution.
Packaging commands absolute tonnage; Agriculture Mulch Films is climbing the fastest amid climate adaptation investments.
End User Industry:
Customer concentration varies from fragmented agricultural operations to consolidated multinational food manufacturers with centralized procurement.
- Food & Beverage Manufacturers:Brand owners specify barrier performance, seal integrity, and recyclability credentials. Mass-balance certified recycled content requirements from Unilever and Procter & Gamble procurement teams are reshaping supplier qualification criteria.
- Agricultural Producers:Seasonal purchasing patterns and price sensitivity characterize demand for mulch, greenhouse, and silage films. Brazilian sugar cane operations and Indian horticulture clusters represent distinct specification profiles.
- Building Contractors:Project-based demand for vapor barriers and underslab membranes tracks residential and commercial construction permits.
- Industrial Fabricators:Drum, pail, and intermediate bulk container manufacturers specify liner films for chemical and food-grade containment.
- Consumer Goods Producers:Personal care and home care brands drive premiumization through printed films with sustainability claims.
Food & Beverage Manufacturers retain volume leadership; Agricultural Producers holds the steepest expansion curve.
Form:
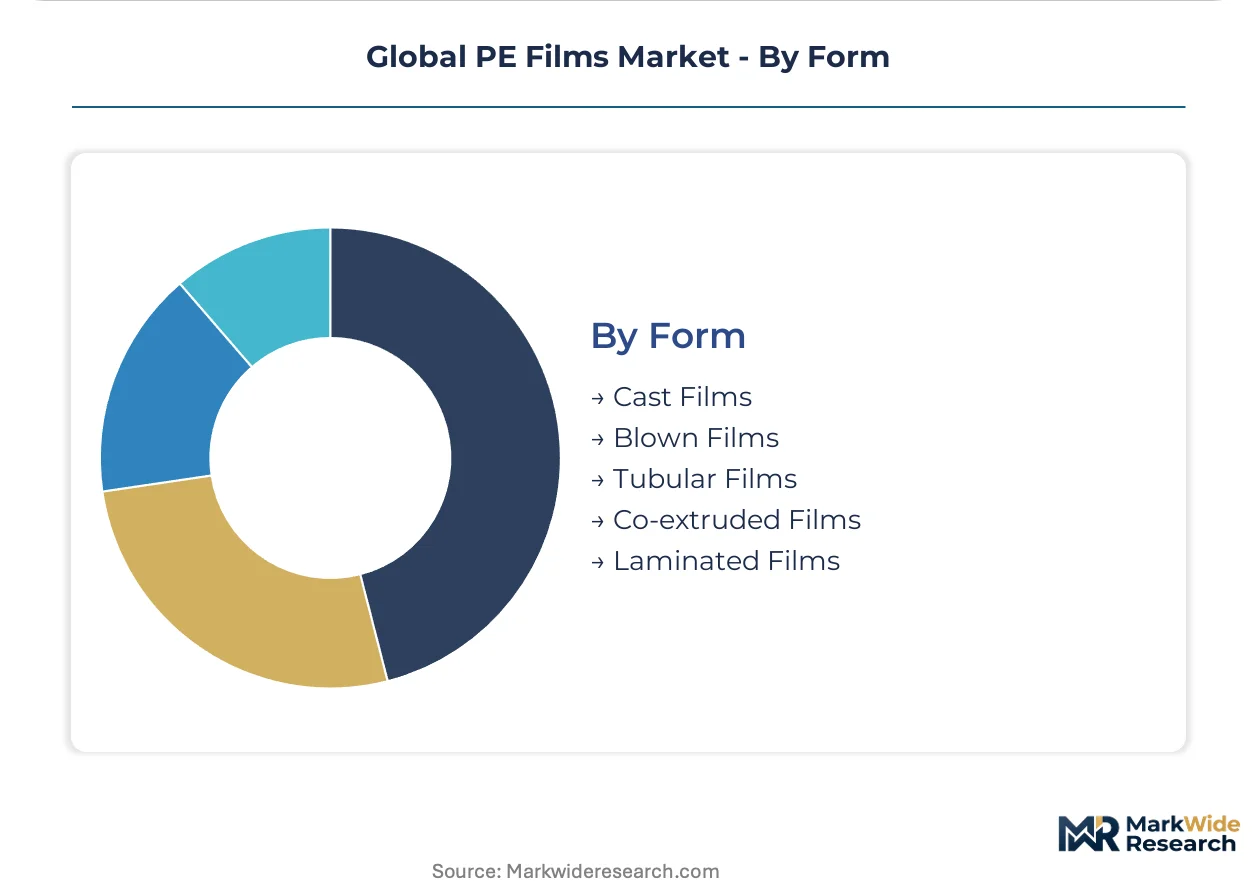
Conversion technology determines thickness uniformity, optical properties, and barrier performance ceilings.
- Blown Films:Tubular bubble extrusion creates balanced biaxial orientation and toughness for agricultural and construction applications. Vietnamese and Thai converters are adding capacity to serve regional agrochemical and building membrane demand.
- Co-extruded Films:Multi-layer die technology combines dissimilar resins for oxygen barrier and sealant functionality. Machine learning-driven rheology modeling is compressing development cycles for oxygen-scavenging structures in European barrier film operations.
- Cast Films:Chill roll extrusion delivers gauge precision and optical clarity for lamination and printing substrates.
- Tubular Films:Seamless cylindrical formats serve bag-making and form-fill-seal operations with reduced conversion steps.
- Laminated Films:Adhesive or extrusion bonding of multiple webs creates high-performance barrier structures, though recyclability challenges mount under EPR frameworks.
Blown Films retains volume leadership; Co-extruded Films holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European resin distribution for film-grade polyethylene, while Shanghai's Yangshan deep-water port anchors Asia-Pacific feedstock import flows.
China
Zhejiang and Shandong provinces host state-backed petrochemical complexes adding LLDPE film-grade capacity faster than regional absorption rates. GB standards for plastic packaging recyclability claims govern domestic converter qualification. Ningbo-Zhoushan port cluster serves both export-oriented flexible packaging and internal agricultural film demand.
United States
Gulf Coast ethane crackers supply cost-advantaged feedstock for domestic blown film operations serving food and industrial packaging. FDA food contact substance notifications govern migration limits for co-extruded structures. Chicago and Dallas-Fort Worth converter clusters process resin into printed retail and agricultural mulch films.
Germany
Ruhr industrial corridor converters specialize in high-barrier co-extruded films for modified-atmosphere meat packaging. REACH registration requirements and ECHA microplastic restrictions force additive reformulation in agricultural applications. Hamburg port infrastructure enables bio-based ethylene feedstock imports for mass-balance certified production.
India
Reliance Retail and DMart expansion into tier-2 cities generates first-time demand for branded pre-packaged produce films. BIS standards and FSSAI regulations govern food-contact migration limits and recyclability labeling. Gujarat petrochemical belt supplies LLDPE resin to Mumbai-Pune converter clusters serving western agricultural markets.
Brazil
São Paulo state converters leverage sugar cane-derived bio-ethylene for carbon footprint-sensitive export packaging. ANVISA regulates food-contact substance safety for flexible primary packaging. Santos port complex handles both resin imports and finished film exports to Mercosur agricultural markets.
Global PE Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and masterbatch supply. The vendor base stratifies across multinational converters with captive extrusion networks, regional blown film specialists, and niche industrial liner formulators. Three archetypes dominate: vertically integrated packaging platforms, scale-driven commodity converters, and specialized barrier film developers. Competitive moves concentrate on mechanical recycling partnerships for post-consumer feedstock security and digital printing technology licensing for short-run customization.
Among North American packaging platforms, Amcor PLC and Berry Global Group exemplify scale-driven converter archetypes with integrated resin sourcing and extrusion networks. Sigma Plastics Group occupies a specialized position in industrial liner formulations, representing the niche technical-grade segment where chemical containment specifications command pricing premiums. These three anchors illustrate the market's structural divergence between commodity volume plays and specification-driven specialty positioning.
| Leading Market Players |
|---|
| Avient |
| Sigma Plastics Group |
| Amcor PLC |
| Inteplast Group |
| Novolex Holdings |
| Berry Global Group |
| Winpak |
| Reynolds Consumer Products |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
Gulf Coast ethane crackers and Zhejiang petrochemical complexes anchor resin supply, concentrating margin capture upstream while converters downstream compete on specification premiums and recycling certification tiers.
Pricing Analysis
EU Green Deal packaging mandates dictate the pricing tier structure across the Global PE Films Market. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS mass-balance certified grades from conventional recycled-content films and virgin resin commodity tiers. Price differentiation hinges on certification level and volume scale, with food-grade mechanical recycling pellets commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from Chinese domestic capacity overhang as state-backed LLDPE film-grade output expands faster than regional absorption. Agricultural producers in Brazil and India exhibit highest price sensitivity due to seasonal purchasing patterns, while personal care brands in Western Europe demonstrate lowest sensitivity as sustainability claims command retail placement premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for resin sourcing and finished film trade. Geographic supply concentration centers on China, the United States, and Germany, with blown film capacity expanding in Vietnam and Thailand to serve regional agrochemical demand. Raw material dependencies draw from naphtha, ethane, and bio-based ethylene feedstocks, with sugar cane-derived routes achieving scale parity in select Brazilian contracts. Single-source vulnerability persists in specialty additive masterbatches subject to ECHA microplastic restrictions. Distribution runs through Rotterdam-Antwerp pipeline corridors for European resin distribution and Shanghai's Yangshan port for Asia-Pacific feedstock flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global PE Films Market operates as a defensive-moat arena where regulatory entrenchment around REACH compliance and FDA food contact notifications creates substantial switching costs for qualified suppliers.
For Market Incumbents: Harden barrier film capabilities through machine learning-driven rheology modeling investments that compress co-extrusion development cycles. Secure mechanical recycling partnerships for post-consumer feedstock security before California SB 54 EPR thresholds tighten. Defend against emerging digital printing specialists by licensing short-run customization technology to regional converters.
For New Entrants and Emerging Players: Build out bio-based additive formulation capabilities targeting Italian and Spanish agricultural mulch film markets facing ECHA restriction deadlines. India's tier-2 city organized retail expansion represents the most penetrable geography for first-time branded produce film demand. Lead with digital printing convergence partnerships that collapse minimum order quantities for regional food brands.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized barrier film developers with oxygen-scavenging expertise and mass-balance certification capabilities. Long-term viability hinges on mechanical recycling feedstock security and design-for-recycling architecture patents. Watch for inflection signals in EU Green Deal compliance deadline acceleration or California EPR recycled-content threshold increases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive LLDPE supply from Gulf Coast crackers insulates Amcor and Berry Global from naphtha volatility. |
| Mechanical Recycling Partnership | Early alliances with post-consumer collection infrastructure secure food-grade pellet supply for California SB 54 compliance. |
| Digital Printing Technology Licensing | HP Indigo press partnerships enable Sigma Plastics Group to serve short-run industrial liner customization demand. |
| Bio-Based Additive Certification | ECHA-compliant masterbatch formulations open Italian and Spanish agricultural mulch film procurement channels. |
| Mass-Balance Chain-of-Custody | ISCC PLUS certification qualifies suppliers for Unilever and Procter & Gamble premium personal care packaging tenders. |
Research Methodology
Initial hypotheses were tested against primary input from blown film plant managers, flexible packaging procurement leads at food manufacturers, masterbatch R&D directors, and agricultural film distributors, then refined through secondary validation against customs and trade data, SEC 10-K filings, European Plastics Association reports, and FDA food contact substance notification databases. Bottom-up capacity assessments across Zhejiang, Shandong, and Gulf Coast petrochemical complexes were triangulated with top-down demand modeling from food and beverage, agriculture, and construction end-use segments.
Demand-supply balance dynamics across resin grade tiers, conversion technology types, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included resin chemistry, film form, application category, and end-user industry concentration. CAGRs were derived through regression analysis of historical capacity expansion rates against regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated EU Green Deal recyclability target enforcement schedules and California SB 54 extended producer responsibility phase-in patterns.
Stress conditions across crude-linked resin volatility, Chinese domestic capacity absorption rates, and ECHA additive restriction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and mechanical recycling feedstock quality improvement trajectories. Material shifts in EU Green Deal deadline acceleration or FDA food contact substance notification review timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
North America Solar Control Window Films Market