
 Polymer Microspheres Market | 2026-2036
Polymer Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Microspheres Market Outlook
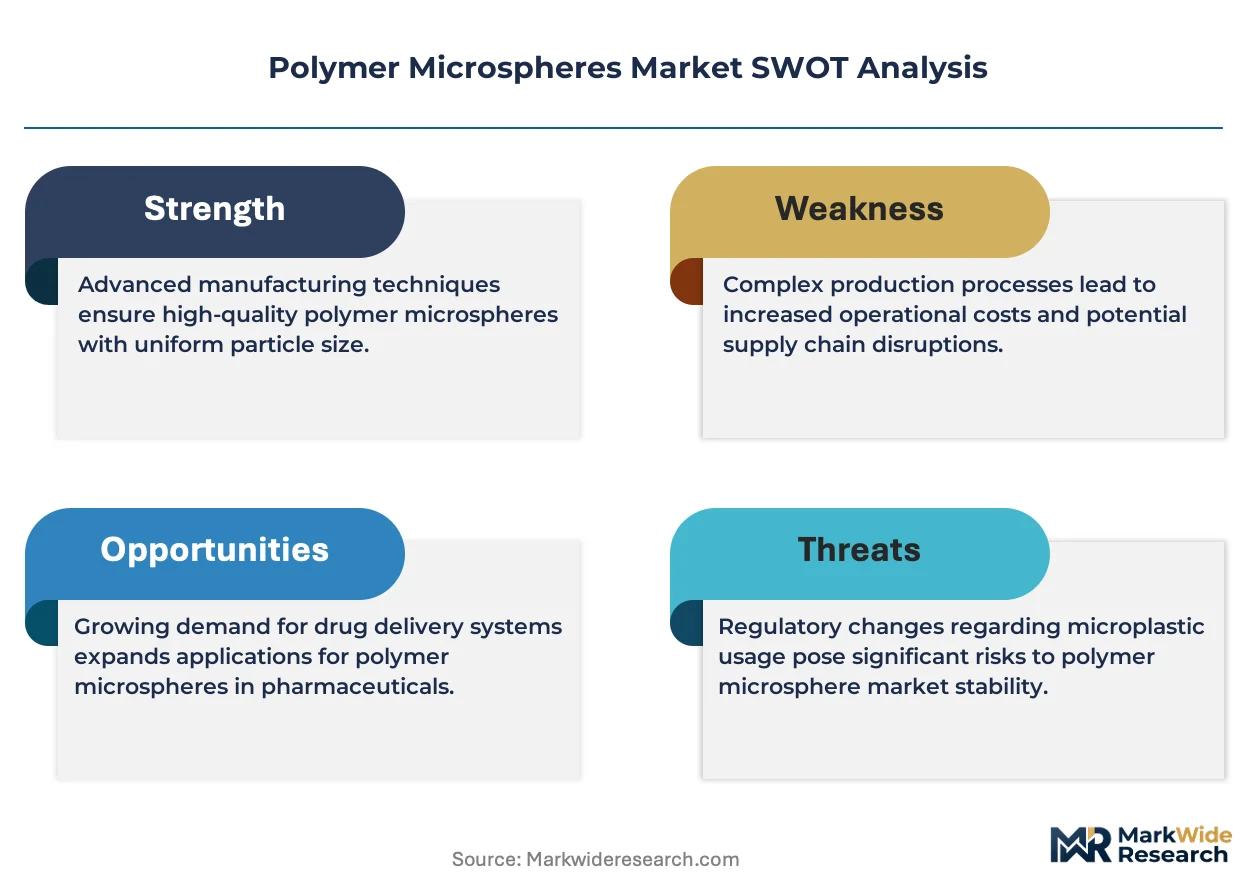
REACH compliance is consolidating the European supplier base by raising the cost-of-entry for uncertified polymer microsphere producers. Evonik Industries AG leverages its backward integration into specialty methacrylate monomers to sustain margin control across medical-grade microsphere lines. 3M Company anchors North American supply through its dominance in precision-controlled particle size distribution for diagnostic applications. Merck KGaA competes on pharmaceutical-grade cGMP manufacturing scale, while Nouryon differentiates via surface-functionalized microspheres for water treatment chemistry.
Polymer microspheres are spherical particles typically ranging from one micron to one millimeter in diameter, composed of synthetic polymers such as polystyrene, polymethyl methacrylate, or polyethylene, manufactured through emulsion or suspension polymerization to achieve uniform size distribution and controlled porosity for applications requiring precise payload delivery, optical properties, or mechanical spacers. Drug delivery systems command the deepest margin pools due to FDA-validated excipient requirements and long qualification cycles that lock in supplier relationships. Diagnostic applications represent the fastest-growing product type, fueled by lateral flow assay and multiplexed immunoassay expansion. Cosmetic formulations remain mature, with spray-drying technology enabling cost-efficient production of hollow microspheres for tactile enhancement in skincare.
FDA excipient guidelines and EPA water quality standards jointly shape product purity thresholds and environmental release protocols for polymer microsphere manufacturers serving pharmaceutical and environmental end users. ISO 10993 biocompatibility testing and EU MDR device regulations further segment the addressable market between commodity and validated-grade supply tiers. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA on particulate drug carrier standards to anticipate qualification pathway changes that could reshape competitive positioning.
Market Dynamics
Regulatory bifurcation between FDA-validated excipient grades and commodity polymer microspheres is compressing supplier margins at the lower tier while entrenching incumbents with cGMP infrastructure. REACH and RoHS compliance costs in Europe are accelerating consolidation among uncertified producers.
Growth Catalysts
- Controlled-release drug delivery:Pharmaceutical formulators are embedding polymer microspheres into long-acting injectables to achieve zero-order release kinetics. FDA excipient validation creates multi-year supplier lock-in.
- REACH RoHS purity mandates:European chemical safety frameworks are elevating residual monomer thresholds. Certified producers capture displaced volume from decommissioned regional suppliers.
- Diagnostic multiplexing:Lateral flow assay manufacturers are scaling fluorescent microsphere procurement to support point-of-care testing expansion.
Market Restraints
- Specialty methacrylate feedstock concentration:Backward-integrated monomer producers control 70% of medical-grade resin supply. Price volatility transmits directly to microsphere cost structures.
- ISO 10993 biocompatibility timelines:Cytotoxicity and sensitization testing cycles extend 18-24 months. Small producers lack capital to sustain qualification gaps.
- Silica nanoparticle substitution:Inorganic carriers are displacing polymer microspheres in certain cosmetic and coating applications where optical clarity is secondary.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are importing validated microsphere excipients for domestic generic injectable programs.
- Surface-functionalized water treatment chemistry:Nouryon's ion-exchange microsphere architecture opens municipal and industrial wastewater remediation contracts.
- EU MDR device regulation:Stricter particulate contamination standards for implantable devices are forcing device makers toward pre-qualified microsphere suppliers.
Industry Challenges
- cGMP cleanroom capex intensity:ISO Class 7 manufacturing suites require $15-25 million per production line. Regional players lack balance sheet capacity.
- Particle size distribution validation:Laser diffraction and Coulter counter method disputes between suppliers and pharmaceutical buyers delay batch releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Microspheres Market |
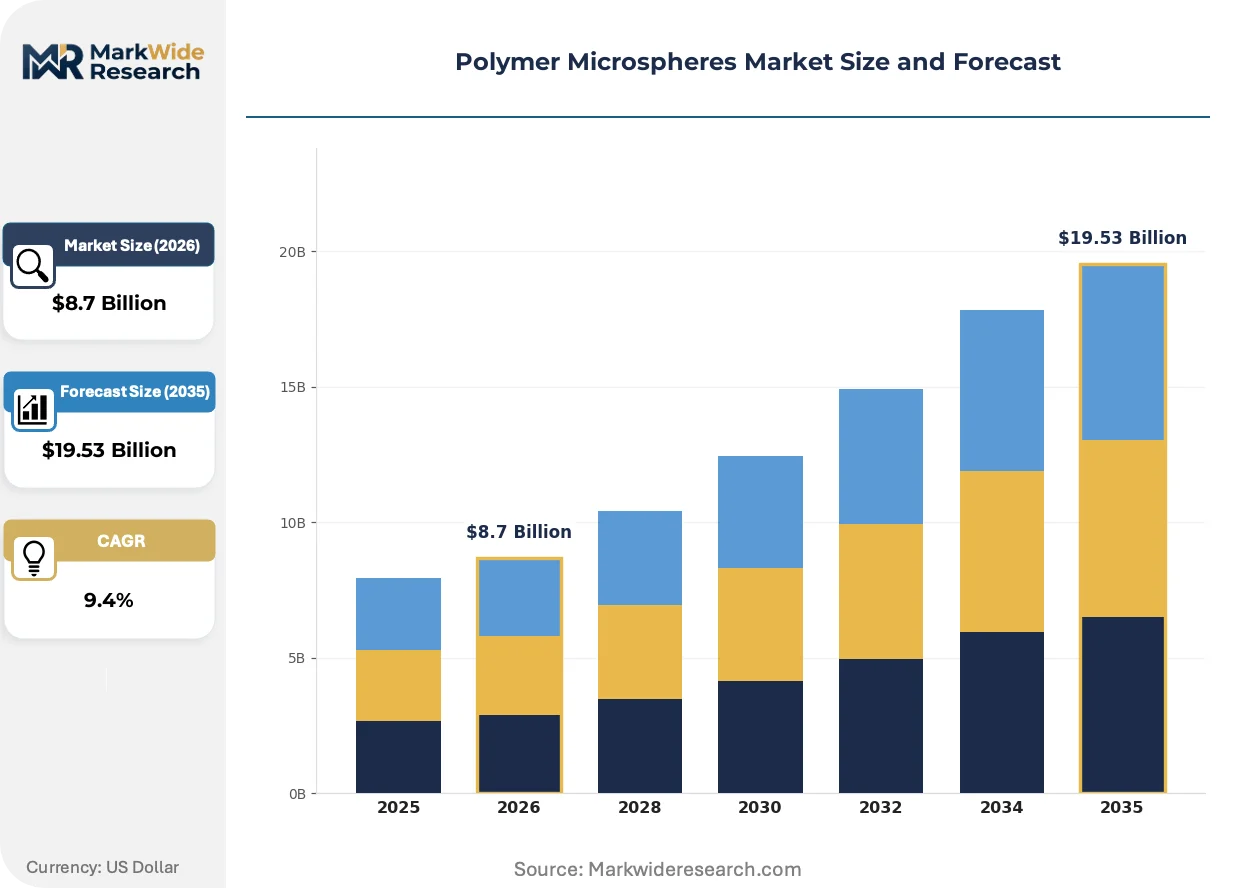
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Microsphere Coatings, Drug Delivery Systems, Diagnostic Applications, Bioimaging Solutions Application: Cosmetic Formulations, Medical Devices, Laboratory Research, Water Treatment End User: Pharmaceutical Companies, Academic Institutions, Healthcare Providers, Environmental Agencies Technology: Emulsion Polymerization, Suspension Polymerization, Solvent Evaporation, Spray-Drying |
| Companies Covered | 3M Company, Nouryon, Polysciences Inc., Sekisui Chemical, Cospheric LLC, Merck KGaA, Evonik Industries AG, Chase Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Microspheres Market Strategic Shifts
Microsphere architecture is fragmenting into application-specific platforms rather than converging on universal formulations. Suppliers are engineering surface chemistries and porosity profiles for discrete end-use requirements.
Multilayer core-shell microspheres are modularizing payload delivery across incompatible active pharmaceutical ingredients. Formulators at major pharmaceutical houses are adopting these structures for combination therapies with divergent release profiles. The technology is modularizing supplier relationships into co-development partnerships rather than transactional procurement.
EMA particulate drug carrier guidance harmonization with FDA standards is compressing dual-qualification burdens for European suppliers. Manufacturers previously maintaining separate validation dossiers are converging on unified testing protocols. Drug delivery system suppliers with existing FDA master files are capturing accelerated EMA approval timelines.
Diagnostic buyers are consolidating microsphere procurement through dedicated distributor channels rather than direct manufacturer relationships. Lateral flow assay producers in the United States are outsourcing inventory management and technical support to specialized life science distributors. This channel shift concentrates pricing leverage with distributors possessing regional regulatory expertise.
Polymer Microspheres Market Segmentation
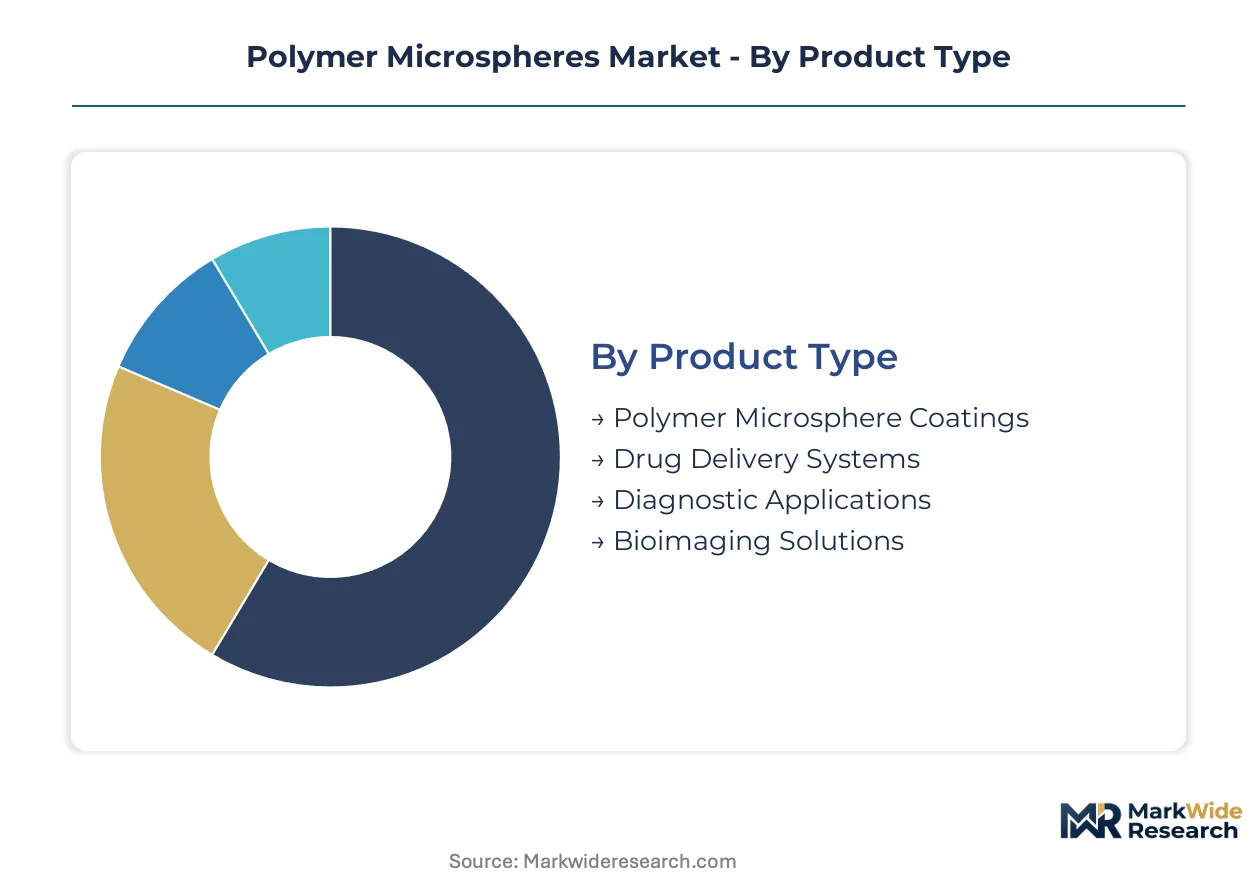
Polymer microsphere buyers segment procurement by validation tier rather than commodity grade. FDA-validated excipient lines command price premiums of 40-60% above industrial-grade equivalents, creating distinct competitive battlegrounds across each category.
Product Type:
FDA excipient validation and ISO 10993 biocompatibility certification split this category into pharmaceutical-grade and industrial-grade supply tiers. Drug delivery systems and diagnostic applications require cGMP manufacturing infrastructure; coatings and bioimaging tolerate broader quality tolerances.
- Drug Delivery Systems:Polylactic-co-glycolic acid and polymethyl methacrylate microspheres enable zero-order release kinetics for long-acting injectables. Pharmaceutical formulators in the United States concentrate procurement with suppliers holding active FDA master files, locking in multi-year supply agreements through qualification cycle barriers.
- Diagnostic Applications:Fluorescent and magnetic microspheres with sub-micron size precision support lateral flow immunoassay and multiplexed molecular diagnostics. Point-of-care testing expansion in Germany and the United States is accelerating procurement volumes for surface-carboxylated and streptavidin-coated variants.
- Polymer Microsphere Coatings:Industrial-grade polystyrene and polyethylene microspheres serve anti-slip and optical diffusion applications where medical certification is unnecessary.
- Bioimaging Solutions:Contrast-agent-loaded microspheres for ultrasound and MRI enhancement require radiolabeling compatibility and batch-to-batch consistency.
Drug delivery systems sit at the top of the volume ranking, with diagnostic applications climbing the fastest.
Application:
End-use concentration varies by margin pool depth and regulatory burden intensity. Medical devices and laboratory research command validated-grade premiums; cosmetic and water treatment applications compete on unit economics.
- Medical Devices:Implantable stent coatings, tissue scaffolds, and hemostatic agents require ISO 10993 cytotoxicity and sensitization clearance. EU MDR device regulations are forcing European manufacturers toward pre-qualified microsphere suppliers with established biological safety dossiers.
- Laboratory Research:Cell separation, flow cytometry calibration, and particle size standards consume high-volume, lower-margin microsphere lots. Academic procurement concentrates through distributor channels rather than direct manufacturer relationships.
- Cosmetic Formulations:Hollow microspheres from spray-dried polymethyl methacrylate provide tactile enhancement and optical blurring in skincare products.
- Water Treatment:Surface-functionalized ion-exchange microspheres target heavy metal capture and phosphate remediation in municipal wastewater facilities.
Medical devices capture the deepest margin pools, while water treatment expands most quickly on environmental compliance spending.
End User:
Procurement authority concentrates with organizations possessing in-house formulation capabilities and regulatory affairs infrastructure. Pharmaceutical companies and healthcare providers drive validated-grade demand; academic and environmental buyers prioritize cost efficiency.
- Pharmaceutical Companies:Controlled-release formulation groups at major drug manufacturers specify microsphere porosity, surface chemistry, and residual monomer thresholds during supplier qualification. cGMP audit requirements limit their vendor base to producers with dedicated medical-grade production suites.
- Healthcare Providers:Hospital system purchasing departments procure diagnostic microspheres for in-house laboratory operations, consolidating orders through group purchasing organizations.
- Academic Institutions:Research universities in Massachusetts and California represent high-volume, price-sensitive demand for unvalidated research-grade microspheres.
- Environmental Agencies:Municipal water authorities in the Netherlands and Singapore pilot ion-exchange microsphere deployments for emerging contaminant removal.
Pharmaceutical companies dominate absolute spending, with environmental agencies gaining share fastest on remediation infrastructure investment.
Technology:
Manufacturing process selection determines particle size distribution precision, surface functionality control, and scalable throughput. Emulsion and suspension polymerization dominate medical-grade production; spray-drying serves cost-sensitive industrial volumes.
- Emulsion Polymerization:Aqueous-phase synthesis yields sub-micron microspheres with narrow polydispersity indices below 0.05. Diagnostic microsphere specifications for lateral flow assays demand this precision, concentrating production among suppliers with continuous-flow reactor expertise.
- Suspension Polymerization:Bead-forming in aqueous suspensions produces 50-500 micron microspheres for drug delivery and bioimaging. Scale-up economics favor this route for pharmaceutical excipient batches exceeding 100 kilograms.
- Solvent Evaporation:Double-emulsion techniques encapsulate hydrophilic active pharmaceutical ingredients within hydrophobic polymer matrices.
- Spray-Drying:Atomization and thermal processing create hollow microspheres for cosmetic and lightweight filler applications at lowest unit cost.
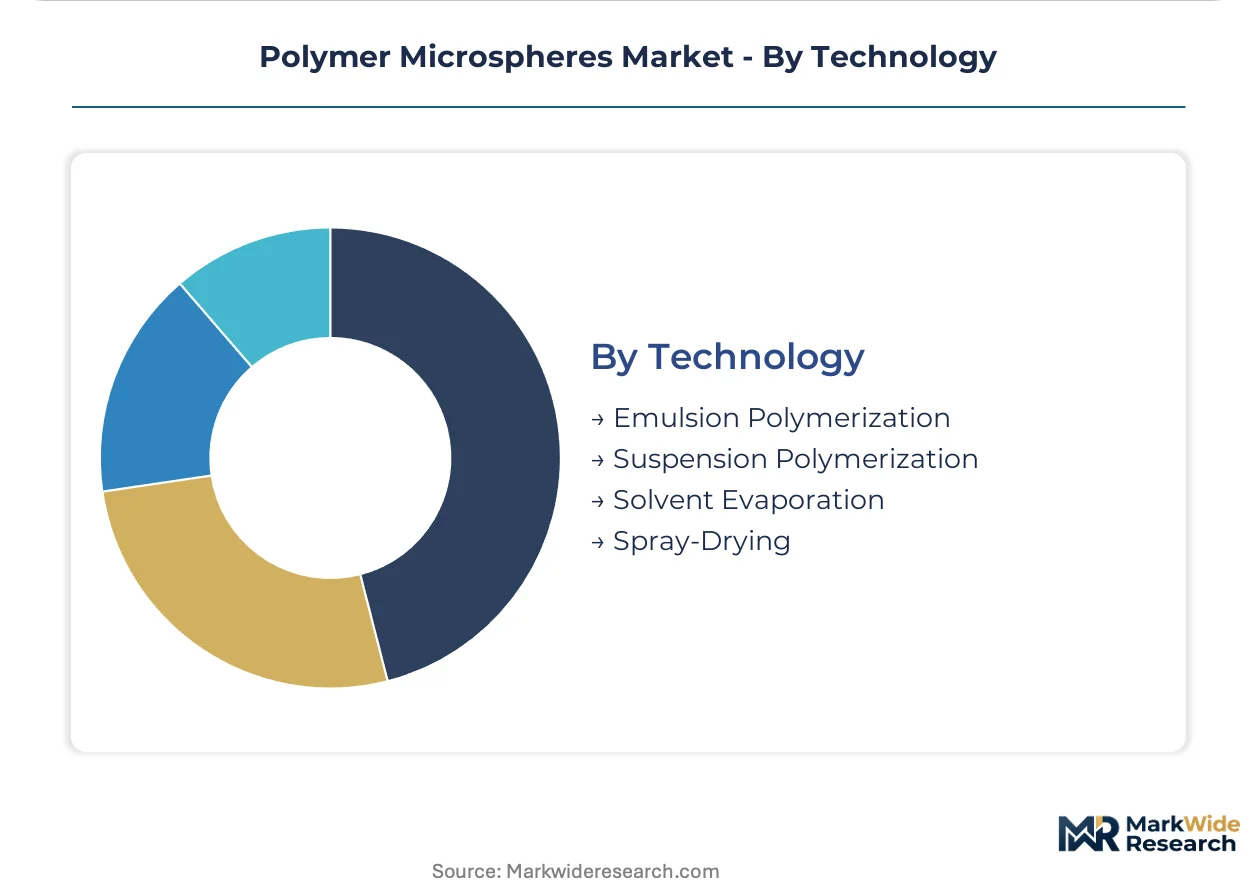
Suspension polymerization leads production volumes, with emulsion polymerization expanding most quickly on diagnostic precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and polymer scientists concentrate in pharmaceutical and diagnostic clusters across five countries, anchoring regional demand patterns for validated-grade microspheres.
United States
Long-acting injectable programs at Boston and San Francisco biotech clusters drive pharmaceutical-grade procurement. FDA master file requirements for excipient suppliers lock in multi-year vendor relationships through qualification barriers. The Research Triangle Park corridor in North Carolina houses diagnostic manufacturers scaling fluorescent microsphere volumes for point-of-care testing expansion.
Germany
REACH residual monomer thresholds and EU MDR device regulations are decommissioning uncertified regional suppliers. EMA harmonization with FDA particulate carrier standards accelerates dual-qualification timelines for exporters. The Rhine-Main industrial corridor around Frankfurt sustains specialty chemical production infrastructure for medical-grade methacrylate monomer supply.
China
Domestic CDMO capacity in Suzhou and Shanghai is importing validated microsphere excipients for generic injectable development. NMPA alignment with FDA cGMP inspection protocols opens pathways for foreign supplier registration. The Yangtze River Delta concentration of biopharma manufacturing clusters represents the fastest-growing procurement geography in Asia-Pacific.
India
Hyderabad and Bangalore contract development organizations are qualifying imported polymer microspheres for controlled-release formulation programs. CDSCO import licensing requirements for pharmaceutical excipients favor suppliers with established biological safety dossiers. The Gujarat pharmaceutical manufacturing belt is expanding fill-finish capacity for long-acting injectable exports to regulated markets.
Japan
PMDA quality agreements for particulate drug carriers mandate batch-to-batch consistency documentation from foreign suppliers. METI funding for domestic pharmaceutical manufacturing reshoring supports local microsphere synthesis capability investment. The Kansai corridor around Osaka maintains precision chemical processing expertise for sub-micron particle size distribution control.
Polymer Microspheres Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered validation grades. The supplier base concentrates at the FDA-validated excipient tier where cGMP infrastructure requirements filter out regional entrants. Three archetypes dominate: backward-integrated monomer producers, distributor-channel specialists, and precision-size diagnostic suppliers. Competitive moves center on qualification dossier expansion and co-development partnerships with pharmaceutical formulators.
Within the diversified chemical conglomerate tier, 3M Company and Evonik Industries AG exemplify scale-driven positioning through captive raw material control. Merck KGaA represents the pharmaceutical-grade manufacturing archetype with cGMP infrastructure at scale. These three companies anchor the premium tier where FDA master file holdings create multi-year supplier lock-in with major drug manufacturers.
| Leading Market Players |
|---|
| 3M Company |
| Nouryon |
| Polysciences Inc. |
| Sekisui Chemical |
| Cospheric LLC |
| Merck KGaA |
| Evonik Industries AG |
| Chase Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into specialty methacrylate monomers anchors both supply security and margin control for medical-grade polymer microsphere producers serving FDA-validated excipient markets. This upstream captive production insulates incumbents from feedstock volatility while locking in multi-year pricing power through qualification cycle barriers that prevent buyer switching.
Pricing Analysis
Technical service bundling separates pharmaceutical-grade procurement from commodity transactions, with FDA master file holders commanding substantial premiums over industrial-grade alternatives. Three-tier pricing structure across validated excipient, ISO-certified research, and unvalidated industrial levels reflects certification investment recovery and biocompatibility testing documentation costs. Cost compression in the commodity tier intensifies because REACH and RoHS compliance investments have decommissioned smaller European suppliers. Academic institutions exhibit the highest price sensitivity, while pharmaceutical formulators prioritize batch consistency and regulatory dossier completeness over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty monomer producers who control upstream resin supply for medical-grade microsphere synthesis. Manufacturing draws from methacrylate monomers, suspension polymerization initiators, and surface-functionalization reagents as critical inputs. Regulatory restriction risk emerges from divergent FDA and EMA particulate carrier guidance timelines that delay dual-qualification for exporters. Distribution runs through specialized life science distributors possessing regional regulatory expertise rather than direct manufacturer channels for diagnostic applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as diagnostic multiplexing and long-acting injectable demand shift procurement toward validated-grade specifications with extended supplier lock-in cycles.
For Market Incumbents: Extend qualification dossier coverage across EMA-FDA harmonized standards to capture accelerated approval timelines for dual-registered suppliers. Deepen backward integration into surface-functionalization chemistry to defend against silica nanoparticle substitution in cosmetic and coating segments. Prioritize co-development partnerships with pharmaceutical formulators engineering multilayer core-shell architectures for combination therapy delivery. For New Entrants and Emerging Players: Surface-functionalized ion-exchange microspheres for municipal wastewater remediation present the most penetrable white-space target, with environmental agencies in the Netherlands and Singapore piloting deployments. Spray-dried hollow microsphere production for skincare applications offers lower regulatory barriers and faster revenue generation than pharmaceutical-grade qualification. Pursue CDMO partnerships in Hyderabad and Bangalore as a go-to-market angle for generic injectable program qualification. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with life science regulatory expertise because diagnostic buyers are consolidating procurement through specialized channels rather than direct manufacturer relationships. The five-to-ten year viability window favors platform consolidation plays over single-product bets. Watch EMA-FDA guidance harmonization progress as the inflection signal for accelerated European supplier rationalization and premium-tier volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive methacrylate supply insulates margin control from feedstock volatility for medical-grade lines. |
| FDA Master File Expansion | Active dossiers create multi-year supplier lock-in with pharmaceutical formulators through qualification barriers. |
| Surface Functionalization R&D Investment | Ion-exchange and streptavidin coatings open water treatment and diagnostic multiplexing contract opportunities. |
| cGMP Cleanroom Capacity Addition | ISO Class 7 manufacturing suites filter out regional competitors lacking balance sheet capacity for qualification. |
| Distributor Channel Partnership | Regional regulatory expertise concentrates pricing leverage with specialized life science inventory managers. |
Study Parameters
Multiple input streams — primary interviews with pharmaceutical formulation scientists, diagnostic procurement managers, and polymer manufacturing executives, alongside secondary validation through FDA master file databases, EMA regulatory submissions, and specialty chemical trade data — were reconciled to construct segment-level demand estimates. Bottom-up volume modeling from individual production facility capacities and top-down cross-checks against end-use consumption patterns ensured analytical robustness across the projection horizon.
Segmentation dimensions modeled include validation grade tier, application type, manufacturing technology, and regional regulatory cluster throughout the forecast period. CAGRs were derived from weighted average growth contributions across these segments, with pharmaceutical excipient demand and diagnostic multiplexing expansion serving as primary volume drivers. Supply-side constraints from REACH compliance costs and cGMP infrastructure requirements were incorporated as dampening factors on capacity expansion timelines.
The model holds under sustained regulatory divergence between FDA and EMA standards; deviation toward accelerated harmonization would shift competitive advantage toward existing dual-qualified suppliers with converged testing protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Basic Methacrylate Copolymer Market