
 Dura Substitute Market | 2026-2036
Dura Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Dura Substitute Market Analysis
Modular graft configurations with integrated anti-adhesion barriers is pivoting buyer choice toward premium product tiers. DePuy Synthes leverages its orthopedic-surgical portfolio to sustain channel dominance in hospital purchasing networks. W. L. Gore & Associates anchors its position through proprietary expanded polytetrafluoroethylene technology leadership. Medtronic competes across multiple material platforms, extending its neurosurgical reach through broad regulatory clearances.
A dura substitute is a biocompatible implant engineered to replicate the mechanical and barrier functions of native dura mater, typically manufactured from synthetic polymers such as expanded polytetrafluoroethylene or absorbable collagen matrices with thickness specifications ranging from 0.1 to 0.6 millimeters, serving to prevent cerebrospinal fluid leakage and reduce post-surgical adhesions following craniotomy or spinal procedures. Thermoplastic formulations currently dominate procedural volume due to favorable handling characteristics and established surgeon familiarity, while biodegradable segments attract accelerated development investment as absorption profiles align with reduced long-term complication rates. Composite material grades command concentrated margin pools where multi-layer constructions address both immediate sealing and delayed tissue integration requirements.
The FDA's Class III premarket approval pathway and ISO 10993 biocompatibility testing standards govern commercial entry, elevating capital requirements for new entrants while reinforcing incumbent quality systems. The EU Medical Device Regulation's enhanced clinical evidence demands reshape post-market surveillance obligations for European market access. Stakeholders must monitor evolving reimbursement determinations from Medicare and commercial payers as synthetic grafts displace autograft protocols in cost-accountable care environments.
Market Dynamics
Neurosurgical departments are consolidating purchasing authority through integrated delivery networks, compressing vendor selection cycles and elevating procurement sophistication around biocompatibility documentation and total cost-of-ownership metrics.
Growth Catalysts
- Class III PMA Pathway Maturation:The FDA's streamlined premarket approval processes for well-characterized synthetic polymers reduce time-to-market for incremental product iterations, accelerating manufacturer R&D cadence.
- Aging Craniotomy Volume:United States Medicare beneficiary expansion drives procedural growth in dural repair indications, particularly among patients requiring anticoagulant management where synthetic grafts reduce reoperation risk.
- Expanded Polytetrafluoroethylene Platform Extension:Proprietary ePTFE manufacturing scale-up enables cost-competitive supply of multi-thickness product portfolios addressing both cranial and spinal surgical applications.
Market Restraints
- Collagen Raw Material Volatility:Bovine and porcine tissue sourcing constraints create input cost unpredictability for absorbable matrix manufacturers, compressing margin stability.
- Single-Source Polymer Supply:Medical-grade fluoropolymer resin production concentrates among three specialty chemical suppliers, exposing graft manufacturers to allocation risk during semiconductor industry demand spikes.
- Autograft Protocol Persistence:Pericranial flap harvesting retains preference in certain academic medical centers due to zero material cost and established reimbursement coding, limiting synthetic penetration in cost-sensitive environments.
Strategic Opportunities
- Japan PMDA Accelerated Review:The Sakigake designation pathway for regenerative medicine products offers reduced clinical data requirements for novel biodegradable dura substitutes, enabling earlier market entry versus standard PMA timelines.
- Ambulatory Surgery Center Expansion:CMS procedural code expansion for select craniotomy categories in ASC settings creates demand for simplified, off-the-shelf graft configurations with reduced OR preparation time.
- Anti-Adhesion Barrier Integration:Converging hyaluronic acid coating technologies with synthetic dura substrates addresses unmet need in posterior fossa surgery where arachnoid scarring drives reoperation rates.
Industry Challenges
- Neurosurgical Device Sales Force Sizing:Specialized clinical specialist recruitment lags procedural volume growth, constraining new product conversion rates in community hospital settings.
- ISO 10993-18 Chemical Characterization Burden:Updated biocompatibility testing standards require extensive extractables and leachables profiling, extending certification timelines and elevating third-party laboratory costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dura Substitute Market |
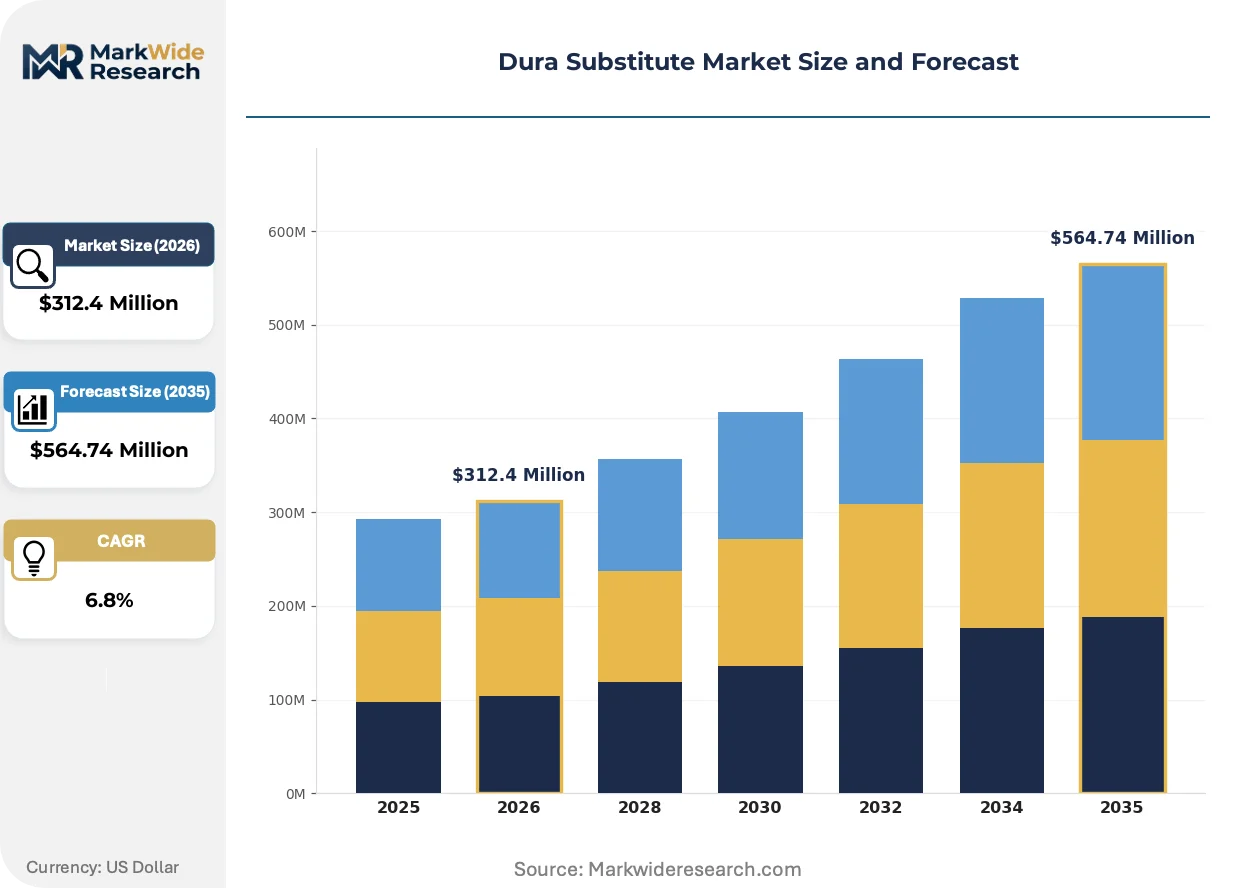
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermoset, Biodegradable, Composite Application: Automotive Parts, Consumer Goods, Medical Devices, Industrial Equipment End User: Manufacturers, Construction Firms, Healthcare Providers, Retailers Material Grade: Engineering Grade, High-Performance Grade, Standard Grade, Custom Grade |
| Companies Covered | DePuy Synthes, W. L. Gore & Associates, Inc., Medtronic, Acera Surgical, Inc., Baxter International, Stryker Corporation, B. Braun SE, Gunze Limited, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dura Substitute Market Emerging Trajectories
Product architecture is bifurcating between permanent synthetic barriers and resorbable tissue scaffolds, with hybrid constructs emerging to bridge immediate sealing requirements and long-term tissue integration outcomes.
Absorbable collagen matrices are decentralizing procurement authority from centralized hospital purchasing committees toward individual surgeon preference cards. Academic medical centers in the United States are piloting surgeon-directed graft selection protocols based on case-specific absorption profile requirements. This shift is compressing vendor consolidation benefits and elevating product differentiation around handling characteristics.
The EU Medical Device Regulation's enhanced clinical evidence requirements are reshaping post-market surveillance obligations for European market access. Manufacturers must now maintain active implant registries and periodic safety update reports beyond initial CE marking. Synthetic dura substitute portfolios with legacy predicate device approvals face disproportionate compliance burden versus novel submissions with prospective clinical data packages.
Hospital value analysis committees are consolidating vendor contracts around single-source agreements with performance guarantees. Integrated delivery networks in Texas and Florida are replacing multi-manufacturer purchasing with exclusive preferred supplier arrangements tied to utilization compliance metrics. This concentration is visible most acutely in systems with employed neurosurgical staff models where standardization incentives align with supply chain cost reduction targets.
Dura Substitute Market Segmentation
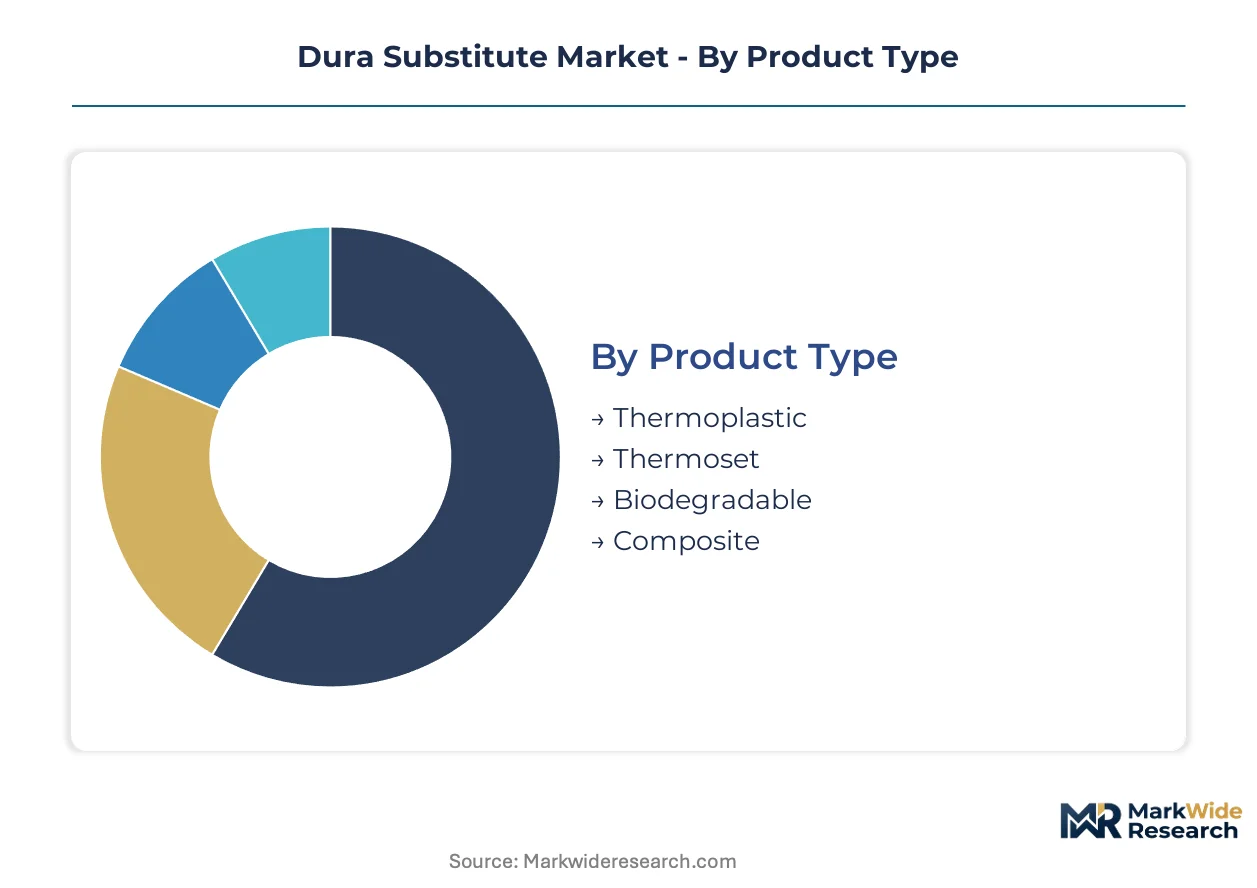
Dura substitute procurement splits across material permanence, procedural setting, and regulatory burden. Each segmentation axis reveals distinct margin structures and certification pathways that shape vendor positioning.
Product Type:
Thermoplastic and thermoset formulations carry FDA Class III PMA requirements, while biodegradable variants face additional ISO 10993-18 chemical characterization burdens. Composite constructs trigger the most extensive premarket review cycles due to multi-material interaction uncertainties.
- Thermoplastic:Expanded polytetrafluoroethylene and similar polymers dominate current procedural volume. United States hospital systems favor established handling characteristics in craniotomy settings where surgeon familiarity reduces operative time.
- Thermoset:Cross-linked silicone substrates offer dimensional stability under thermal sterilization. Academic medical centers in Germany and Japan are piloting these for complex posterior fossa reconstructions requiring precise contouring.
- Biodegradable:Absorbable collagen matrices with 6-12 month resorption profiles align with reduced long-term adhesion risk in spinal dural repair.
- Composite:Multi-layer constructions combining synthetic barriers with resorbable scaffolds command premium positioning where immediate sealing and delayed tissue integration both prove critical.
Leading the category by volume: Thermoplastic. Growing fastest: Biodegradable.
Application:
Medical device applications concentrate reimbursement authority and quality documentation requirements. Automotive and industrial segments operate under lighter regulatory frameworks but face commoditization pressure from regional polymer suppliers.
- Medical Devices:Craniotomy and spinal dural repair applications drive value concentration. United States Medicare reimbursement codes for synthetic grafts in neurosurgical procedures support procedural volume expansion in hospital outpatient departments.
- Automotive Parts:Sealing applications in electric vehicle battery enclosures utilize fluoropolymer films with thickness specifications overlapping medical-grade production. German automotive suppliers are qualifying dual-use manufacturing lines to absorb medical demand fluctuations.
- Consumer Goods:Premium outdoor apparel membranes leverage ePTFE breathability properties with reduced biocompatibility testing overhead.
- Industrial Equipment:Chemical processing seals and filtration membranes compete primarily on cost-per-unit-area metrics against conventional elastomers.
Dominant by revenue: Medical Devices. Expanding most quickly: Automotive Parts.
End User:
Healthcare providers maintain the most stringent vendor qualification protocols, requiring active implant registries and periodic safety update reports under EU MDR. Construction and retail channels prioritize logistics reliability over technical documentation depth.
- Healthcare Providers:Integrated delivery networks in Texas and Florida are consolidating purchasing around single-source agreements with utilization compliance guarantees. Employed neurosurgical staff models create standardization incentives that compress vendor counts.
- Manufacturers:Medical device OEMs source raw fluoropolymer films for in-house graft fabrication, competing with finished graft suppliers on total cost of ownership.
- Construction Firms:Geosynthetic barrier applications in tunnel waterproofing utilize lower-specification polymer grades with minimal regulatory documentation.
- Retailers:Direct-to-consumer medical supply distribution remains limited by sterile handling requirements and prescription status constraints.
Largest procurement volume: Healthcare Providers. Steepest expansion trajectory: Manufacturers.
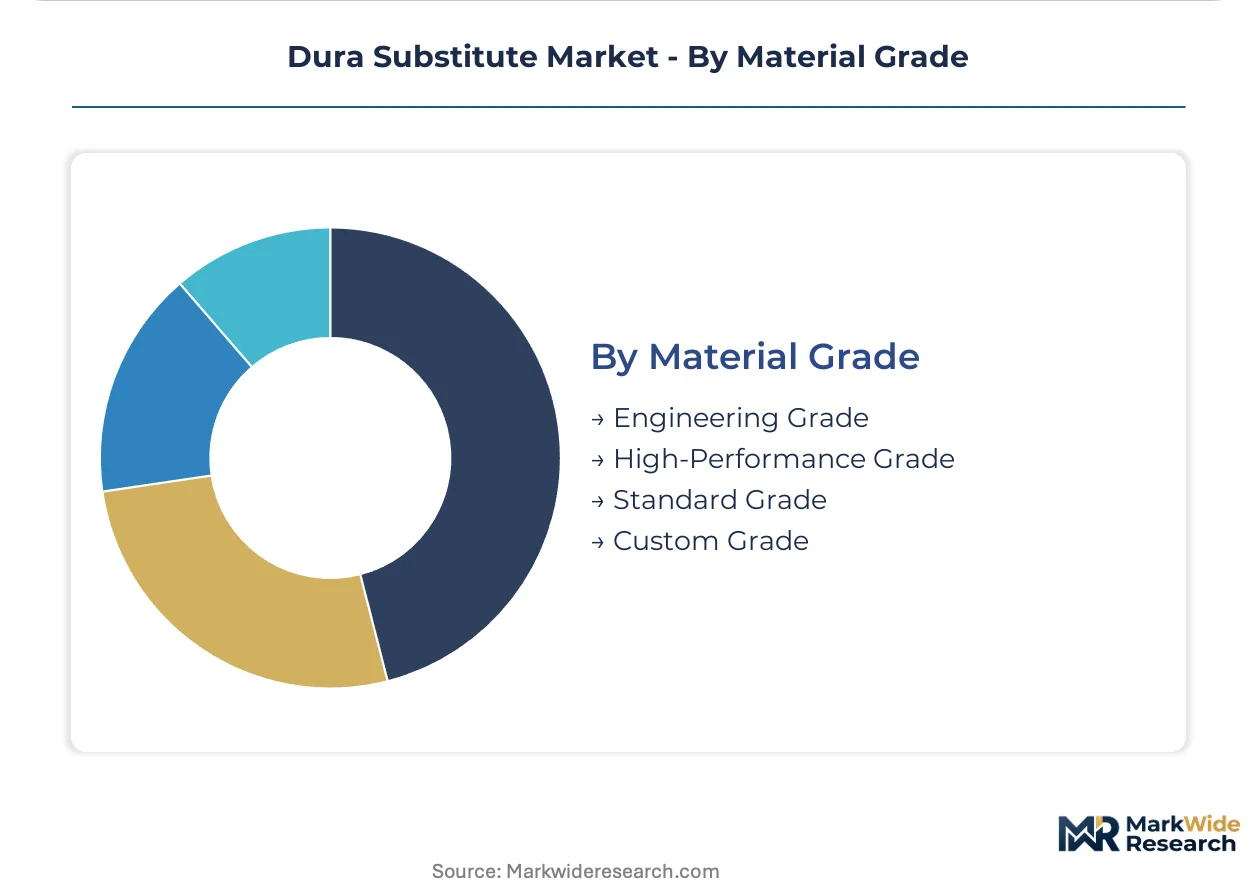
Material Grade:
Engineering and high-performance grades concentrate among three specialty chemical suppliers, exposing graft manufacturers to allocation risk. Standard and custom grades fragment across regional compounders with shorter lead times but inconsistent lot-to-lot variability control.
- Engineering Grade:Medical-grade fluoropolymer resins with documented biocompatibility profiles support Class III device submissions. Japanese PMDA and FDA both require resin-level traceability for PMA approvals.
- High-Performance Grade:Ultra-pure formulations with sub-ppm extractable limits serve pediatric neurosurgery and repeat-implant scenarios where immunogenicity risk tolerance approaches zero.
- Standard Grade:Industrial-specification polymers with broader molecular weight distributions compete on unit cost in research and veterinary applications.
- Custom Grade:Patient-specific thickness and porosity modifications for complex cranial base reconstructions require small-batch production with extended quality release timelines.
Highest revenue concentration: Engineering Grade. Gaining share fastest: High-Performance Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of medical-grade fluoropolymer resins concentrates among specialty chemical suppliers in Germany, Japan, and the United States, while procedural consumption clusters in aging healthcare systems with established neurosurgical infrastructure.
United States
Medicare beneficiary expansion and employed neurosurgical staff models in integrated delivery networks drive synthetic graft procurement. FDA Class III PMA pathway maturation accelerates incremental product iterations for well-characterized polymers. Texas and Florida hospital systems consolidate purchasing around single-source agreements with utilization compliance guarantees.
Germany
Academic medical centers pilot thermoset silicone substrates for complex posterior fossa reconstructions requiring precise contouring. EU Medical Device Regulation's enhanced clinical evidence demands reshape post-market surveillance obligations for CE-marked portfolios. The Baden-Württemberg medical technology corridor hosts fluoropolymer processing clusters serving dual automotive-medical production lines.
Japan
Aging demographics and expanding neurosurgical departments in hospital systems elevate procedural volume for dural repair indications. PMDA's Sakigake designation pathway for regenerative medicine products offers reduced clinical data requirements for novel biodegradable substitutes. The Kanto region's precision polymer industry supplies medical-grade resin with documented biocompatibility profiles.
China
Rising craniotomy volume in tier-one hospital systems creates demand for cost-competitive synthetic graft alternatives to autograft protocols. NMPA medical device registration requirements for Class III implants elevate capital barriers for domestic entrants. The Yangtze River Delta concentration of polymer compounders serves both medical device OEMs and finished graft suppliers.
Switzerland
Swissmedic's stringent quality system requirements reinforce incumbent manufacturer positioning in high-performance grade segments. Pediatric neurosurgery applications demand ultra-pure formulations with sub-ppm extractable limits. The Basel biopharmaceutical corridor extends into medical polymer characterization and implant testing services.
Dura Substitute Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material platforms and regulatory jurisdictions. The vendor base stratifies into three tiers: multinational medical device conglomerates with broad neurosurgical portfolios, mid-cap polymer technology specialists with proprietary manufacturing platforms, and regional fabricators serving cost-sensitive procurement environments. Dominant competitive moves include backward integration into medical-grade fluoropolymer resin supply and exclusive preferred supplier arrangements with integrated delivery networks.
Among diversified medical technology conglomerates, DePuy Synthes and Medtronic exemplify scale-driven archetypes competing across multiple material platforms with extensive regulatory clearances. W. L. Gore & Associates, Inc. occupies a specialist position anchored by proprietary expanded polytetrafluoroethylene technology leadership. These three entities represent contrasting strategic postures: broad portfolio diversification versus focused polymer platform dominance.
| Leading Market Players |
|---|
| DePuy Synthes |
| W. L. Gore & Associates, Inc. |
| Medtronic |
| Acera Surgical, Inc. |
| Baxter International |
| Stryker Corporation |
| B. Braun SE |
| Gunze Limited |
| Integra LifeSciences |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in Texas and Florida concentrate purchasing authority through single-source agreements, anchoring contract-based long-term offtake pricing with utilization compliance guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA Class III PMA holders commanding premium positioning.
Pricing Analysis
Margin tightening in standard-grade thermoplastic segments reflects bovine collagen raw material volatility and fluoropolymer resin allocation pressure. Price differentiation hinges on ISO 10993-18 chemical characterization completeness and surgeon-directed preference card status. Cost-down pressure on economy-tier fabricators accelerates because autograft protocols retain zero-material-cost positioning in academic medical centers. Hospital value analysis committees exhibit highest price sensitivity, while pediatric neurosurgery applications demonstrate least elasticity due to immunogenicity risk tolerance thresholds.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for medical-grade fluoropolymer resins. Manufacturing draws from specialty chemical suppliers in Baden-Württemberg, the Kanto region, and the US Gulf Coast, with bovine collagen matrices sourcing from controlled herd operations. Single-source polymer vulnerability exposes graft manufacturers to semiconductor industry demand spikes. Distribution runs through hospital system central warehouses and GPO-contracted channels with sterile handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dura substitute market sits in a technology-transition phase as biodegradable collagen matrices displace permanent synthetic barriers in posterior fossa and spinal applications.
For Market Incumbents: Deploy backward integration into medical-grade fluoropolymer resin supply to secure allocation priority during semiconductor demand spikes. Consolidate channel control through exclusive preferred supplier arrangements with integrated delivery networks employing neurosurgical staff. Counter emerging biodegradable specialists by accelerating hybrid construct R&D through proprietary ePTFE platform extensions. For New Entrants and Emerging Players: Launch via ambulatory surgery center direct distribution targeting simplified off-the-shelf graft configurations with reduced OR preparation time. White-space exists in Japan's Sakigake-designated biodegradable segments and Texas-Florida IDN secondary sourcing positions. Penetrate through surgeon-directed preference card protocols at academic medical centers piloting case-specific absorption profile selection. For Investors and Strategic Acquirers: The window for entry favors mid-cap polymer technology specialists with proprietary manufacturing platforms and active FDA PMA predicates. Long-term viability rests on CE marking transition completion under EU MDR enhanced clinical evidence requirements. Monitor PMDA Sakigake approval velocity as inflection indicator for biodegradable segment tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Pathway Advancement | Streamlined premarket approval for well-characterized synthetic polymers accelerates DePuy Synthes and Medtronic iteration cycles. |
| EU MDR CE Marking Transition | Enhanced clinical evidence demands reshape post-market surveillance obligations for W. L. Gore's European portfolios. |
| Hospital System Partnership | Exclusive preferred supplier arrangements with Texas and Florida IDNs compress vendor counts and lock in utilization compliance. |
| Backward Integration into Resin | Captive supply of medical-grade fluoropolymer reduces allocation risk exposure during semiconductor demand spikes. |
| Reimbursement Strategy | Medicare code expansion for ASC craniotomy settings creates demand pull for simplified graft configurations. |
Methodological Framework
Document review covered FDA 510(k) and PMA filings, EU MDR technical documentation, and hospital procurement database extracts, complemented by interviews with neurosurgical department heads, GPO contracts managers, biomedical engineers, and fluoropolymer resin procurement leads. Secondary sources included CMS Medicare reimbursement schedules, ISO 10993 biocompatibility standards, and specialty chemical trade flow data. Bottom-up procedural volume modeling and top-down manufacturer revenue triangulation validated segment splits.
Cross-reference of historical adoption curves against surgeon panel input shaped absorption profile penetration assumptions across the projection horizon. Segmentation dimensions modeled include material permanence, procedural setting, regulatory burden tier, and end-user purchasing authority concentration. CAGRs derived from logistic diffusion curves applied to Medicare beneficiary expansion trajectories and neurosurgical department infrastructure deployment patterns.
Regulatory timeline delays, raw material sourcing disruptions, and reimbursement code revision decisions are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Halloysite Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Alginate Films Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Global PE Films Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Europe Textile Films Market