
 Global Graphic Film Market | 2026-2036
Global Graphic Film Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphic Film Market Foresight
Southeast Asia is reconfiguring capacity as Thailand and Vietnam add calendered film lines to serve export-oriented converters. Avery Dennison Corporation leverages integrated adhesive chemistry to sustain margin control across cast and calendered grades. 3M anchors North American supply through proprietary multi-layer casting technology that dominates fleet wrap specifications. ORAFOL Europe GmbH competes on optical clarity standards for reflective traffic and safety applications.
Graphic film denotes pressure-sensitive or heat-activated polymer substrates, typically 50-200 microns in caliper, engineered for surface adhesion, print receptivity, and environmental durability across indoor and outdoor exposures. Cast film production involves liquid resin pouring onto polished belts, yielding dimensional stability for complex curves; calendered film extrudes through heated rollers, delivering cost efficiency for flat signage. Vehicle wraps command premium value pools due to conformability requirements, while advertising signage remains the volume anchor. UV inkjet technology displaces solvent systems as environmental regulations tighten, with latex inkjet gaining share in retail and interior applications where low-VOC operation matters.
EPA standards govern volatile organic compound emissions from solvent-based inkjet operations in the United States, while REACH restricts phthalate plasticizers and heavy metal pigments across European supply chains. ISO 9001 and ISO 14001 certifications function as baseline qualifiers for converter qualification programs at major fleet operators and retail chains. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will reshape sourcing geography and technology migration timelines.
Market Dynamics
Fleet operators in Germany, the United States, and Japan are consolidating procurement specifications around conformable cast films, forcing converters to certify against ISO 9001 and ISO 14001 while absorbing REACH and EPA compliance costs into long-term supply agreements.
Growth Catalysts
- Vehicle Wrap Specifications:Fleet branding mandates from logistics operators in Germany and the United States are pulling premium cast film volumes as conformability requirements intensify for complex vehicle geometries.
- UV Inkjet Conversion:Print houses across Japan and South Korea are retiring solvent systems under tightening volatile organic compound frameworks, expanding addressable demand for compatible film surfaces.
- Thailand Calendering Expansion:Export-oriented converters are adding capacity to serve Australian and Middle Eastern signage markets, lowering landed costs for standard-grade applications.
Market Restraints
- Petrochemical Input Volatility:Polyvinyl chloride and polyethylene terephthalate resin prices fluctuate with naphtha cracking margins, compressing converter gross margins on fixed-price annual contracts.
- Adhesive Chemistry Concentration:Proprietary solvent acrylic formulations remain concentrated among three integrated suppliers in Germany and the United States, creating qualification bottlenecks for new market entrants.
- Reflective Film Technical Ceiling:Microprismatic retroreflective layers face durability limitations in high-humidity climates, restricting penetration in Southeast Asian infrastructure projects.
Strategic Opportunities
- Indian Fleet Digitization:E-commerce logistics operators are adopting vehicle wraps for last-mile brand visibility, creating first-mover advantage for converters establishing local slitting and distribution.
- Latex Inkjet Compatibility:Water-based ink systems are gaining share in retail interior applications, rewarding film suppliers with optimized topcoat chemistry for aqueous receptivity.
- EU Green Deal Procurement Mandates:Public sector signage tenders are incorporating recycled content thresholds, advantaging suppliers with certified post-industrial film loops.
Industry Challenges
- Color-Matching Skill Scarcity:Fleet operators demand spot-color consistency across multi-year refresh cycles, yet trained color technicians are concentrated in legacy print regions.
- Multi-Site Certification Burden:ISO 14001 audits across converter networks in Vietnam and Thailand extend qualification timelines for multinational fleet accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphic Film Market |
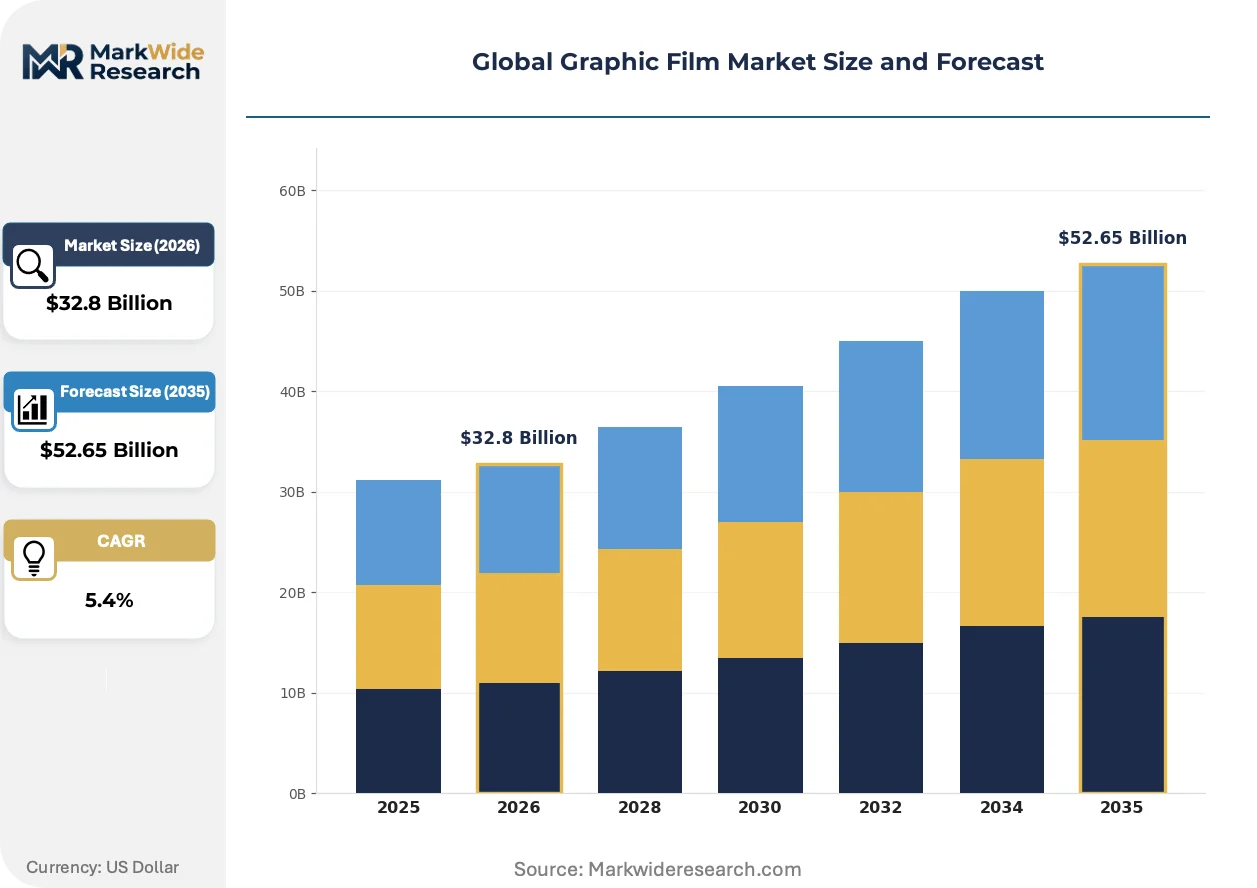
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Film, Calendered Film, Polymeric Film, Metallic Film, Others Application: Advertising Signage, Vehicle Wraps, Architectural Decoration, Promotional Displays, Interior Design Technology: Solvent-Based Inkjet, UV Inkjet, Latex Inkjet, Screen Printing, Thermal Transfer End User Industry: Advertising Agencies, Vehicle Wrap Specialists, Interior Decorators, Exhibition Organizers, Retail Marketers |
| Companies Covered | 3M, Avery Dennison Corporation, DuPont de Nemours, ORAFOL Europe GmbH, HEXIS S.A., Arlon Graphics, CCL Industries, Dunmore, Achilles USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphic Film Market Shifts & Advancements
Print technology and substrate chemistry are converging to eliminate solvent-based workflows while regulatory pressure accelerates compliance-driven specification consolidation among large fleet operators.
Cast film production is migrating from batch-oriented belt casting to continuous multi-layer coextrusion systems that reduce gauge variation below two microns. Fleet wrap specialists in Germany and the United States are specifying these tighter tolerances for complex curvature applications. The technology is migrating from premium automotive segments toward mid-volume commercial van fleets as equipment amortization spreads across broader production runs.
REACH restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of adhesive backings and colored topcoats across European supply chains. Converter qualification programs now require third-party certification of chemical content before purchase order release. Traffic safety applications in Germany and France face the steepest compliance ramps as retroreflective specifications tighten.
Specification consolidation among logistics operators is compressing supplier rosters to three approved film sources per geography. Large fleet buyers in the United States and Germany are unbundling installation from material supply, forcing converters to compete on film performance warranties rather than turnkey service bundles. This pattern is most visible in North American over-the-road trucking, where carrier mergers have concentrated purchasing power.
Global Graphic Film Market Segmentation
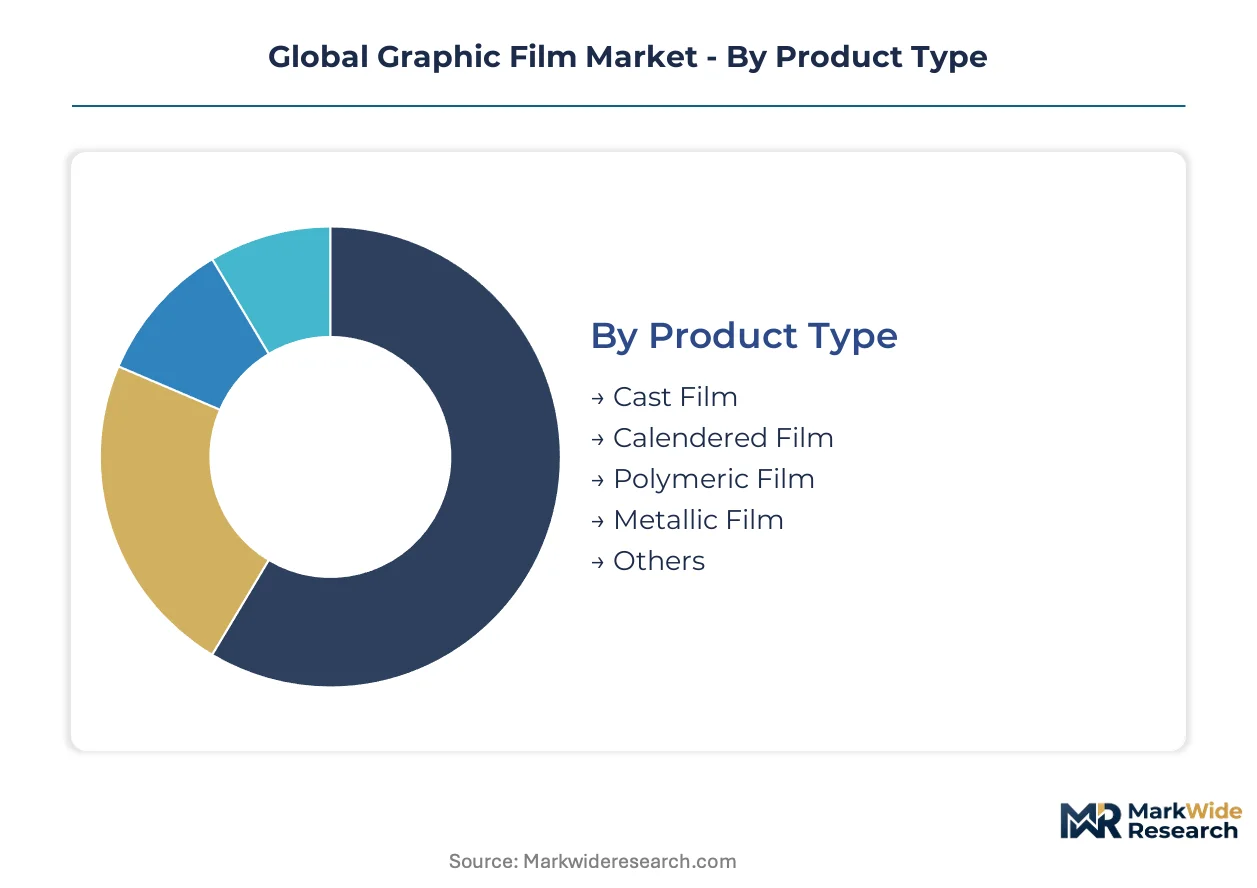
Graphic film segmentation reflects divergent production economics and specification intensity across substrates, applications, and print technologies. Fleet operators and retail chains source through distinct procurement channels with incompatible qualification requirements. Understanding segment boundaries clarifies where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Cast film commands the longest production cycle and highest capital intensity, while calendered lines turn inventory fastest through continuous extrusion economics.
- Cast Film:Liquid resin pours onto polished casting belts, yielding dimensional stability below two microns gauge variation. Fleet wrap specialists in Germany and the United States specify these tolerances for complex vehicle geometries where conformability failures trigger warranty claims.
- Calendered Film:Heated roller extrusion delivers cost efficiency for flat signage applications. Thailand and Vietnam are adding capacity to serve Australian and Middle Eastern export markets, compressing lead times for standard-grade procurement.
- Polymeric Film:Flexible PVC and PET substrates balance durability with print receptivity. REACH compliance costs in Europe are forcing reformulation of plasticizer content across adhesive backings.
- Metallic Film:Vacuum-deposited aluminum layers create reflective decorative effects. Premium automotive badging and retail point-of-sale applications concentrate demand in Japan and Germany.
- Others:Specialty substrates include holographic diffractive films and retroreflective microprismatic layers. Traffic safety specifications in France and Germany impose stringent optical clarity standards.
Calendered film anchors the volume base while cast film gains share at the steepest rate as fleet branding specifications tighten.
Application:
Application segmentation separates cyclical advertising spend from durable fleet assets with multi-year amortization schedules.
- Vehicle Wraps:Full and partial fleet graphics require conformable cast films rated for seven-year outdoor durability. Logistics operators in the United States and Germany are consolidating procurement around three approved film sources per geography.
- Advertising Signage:Billboards, transit shelters, and building wraps consume calendered film at scale. Thai converters are capturing Middle Eastern tender volumes through landed cost advantages.
- Architectural Decoration:Window films and surface laminates serve commercial retrofit and new construction. EU Green Deal procurement mandates are incorporating recycled content thresholds for public sector tenders.
- Promotional Displays:Short-run retail campaigns favor rapid-turn digital print compatibility. Japanese and South Korean print houses are retiring solvent systems under tightening VOC frameworks.
- Interior Design:Wall coverings and decorative laminates demand low-VOC operation. Latex inkjet systems are expanding addressable demand for aqueous-receptive topcoats.
Advertising signage generates the highest absolute volumes while vehicle wraps command the steepest premium expansion.
Technology:
Print technology segmentation tracks regulatory displacement of solvent systems and the chemistry requirements each successor imposes on film surfaces.
- UV Inkjet:Curable inks eliminate VOC emissions while enabling direct-to-substrate adhesion on untreated films. Japanese print houses are converting under METI-aligned environmental guidelines.
- Latex Inkjet:Water-based systems penetrate retail interiors where low-VOC operation is mandatory. Film suppliers with optimized aqueous topcoat chemistry capture specification preference.
- Solvent-Based Inkjet:Legacy systems face EPA emission limits in the United States and equivalent state-level restrictions. Market share concentrates in regions with lagging enforcement infrastructure.
- Screen Printing:Thick ink deposits suit outdoor durability requirements for traffic safety and fleet graphics. German and French retroreflective specifications favor this method for optical density control.
- Thermal Transfer:Ribbon-based systems serve variable-data labeling and short-run personalization. Barcode and asset-tracking applications drive demand in logistics and healthcare.
Solvent-based inkjet retains installed base dominance while UV inkjet climbs the fastest as regulatory deadlines approach.
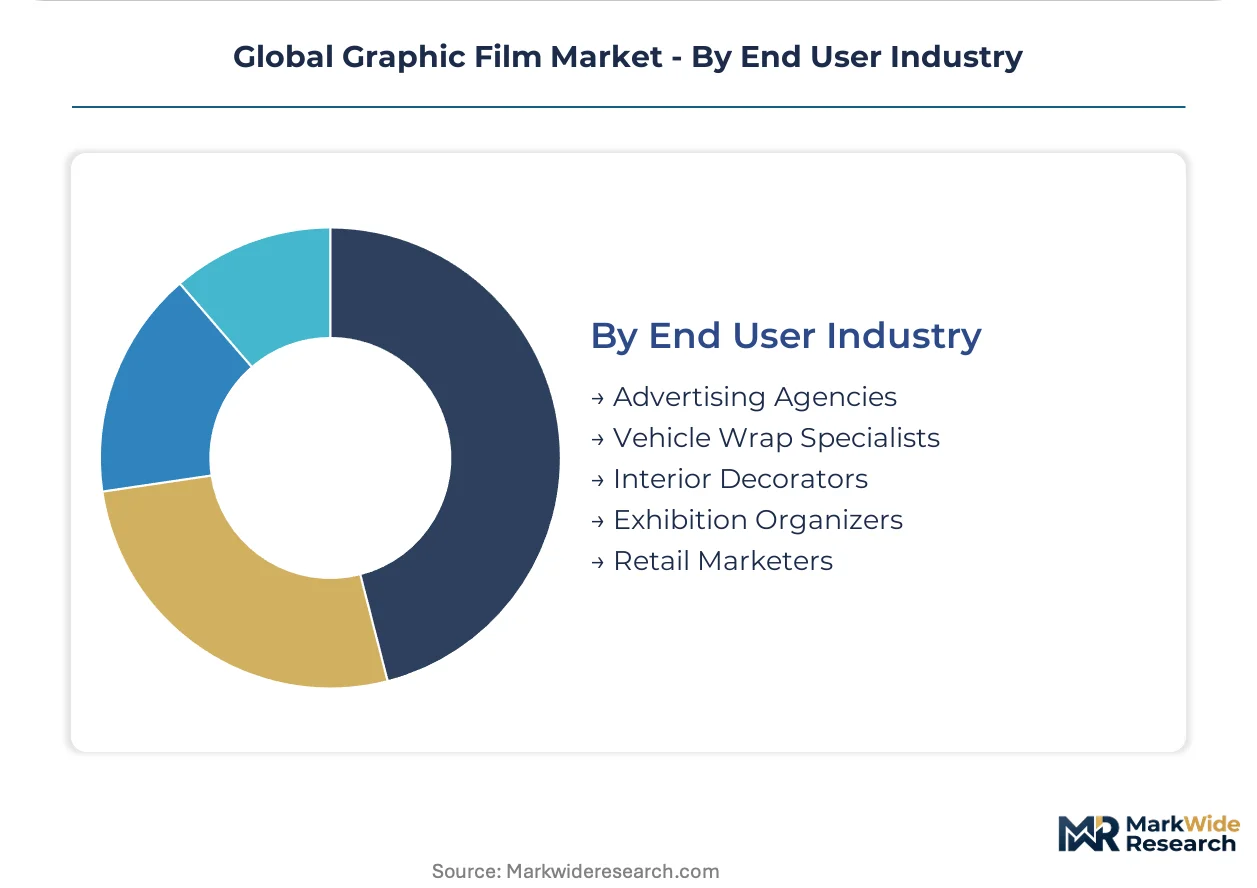
End User Industry:
End user segmentation distinguishes specification authority between brand owners, installation contractors, and procurement intermediaries.
- Vehicle Wrap Specialists:Certified installers qualify against ISO 9001 and ISO 14001 while absorbing REACH and EPA compliance costs into long-term supply agreements with fleet operators.
- Advertising Agencies:Creative houses specify film grade based on campaign duration and environmental exposure. Short-turn retail cycles favor calendered film with digital print compatibility.
- Interior Decorators:Commercial and residential designers prioritize low-emission materials for enclosed spaces. Latex-compatible films with aqueous topcoats capture specification preference.
- Exhibition Organizers:Trade show and event graphics demand rapid production with intermediate durability. Rental and reuse cycles favor cost-optimized calendered substrates.
- Retail Marketers:In-store graphics and point-of-sale materials require color consistency across seasonal refresh cycles. Color-matching skill scarcity concentrates procurement with legacy print region converters.
Advertising agencies anchor the volume base while vehicle wrap specialists expand fastest as fleet digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA standards in the United States are tightening volatile organic compound emissions from solvent-based inkjet operations, forcing fleet operators and print houses to consolidate procurement around compliant film suppliers with integrated adhesive chemistry capabilities.
United States
Fleet branding mandates from logistics operators are pulling premium cast film volumes as conformability requirements intensify for complex vehicle geometries. EPA emission limits on solvent-based inkjet operations are accelerating UV inkjet conversion across print houses. ORAFOL Europe GmbH anchors supply relationships with major over-the-road trucking carriers consolidating purchasing power through carrier mergers.
Germany
Logistics operators are consolidating procurement specifications around conformable cast films with multi-year durability warranties. REACH restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of adhesive backings across European supply chains. The converter cluster anchored by ORAFOL Europe GmbH serves premium automotive wrap applications with certified chemical content documentation.
Japan
Print houses are retiring solvent systems under METI-aligned environmental guidelines, expanding addressable demand for UV-compatible film surfaces. METI frameworks govern volatile organic compound emissions from industrial printing operations. Fleet operators in the Kanto region are specifying cast films for commercial van graphics with seven-year outdoor durability ratings.
Thailand
Export-oriented converters are adding calendered film lines to serve Australian and Middle Eastern signage markets, lowering landed costs for standard-grade applications. The country's national environmental regulator is aligning industrial emission standards with ASEAN harmonized frameworks. Bangkok-based slitting operations are capturing tender volumes from Middle Eastern infrastructure projects.
India
E-commerce logistics operators are adopting vehicle wraps for last-mile brand visibility, creating first-mover advantage for converters establishing local slitting and distribution. The Bureau of Indian Standards is developing certification protocols for pressure-sensitive adhesive films used in commercial vehicle applications. Maharashtra-based converters are qualifying against ISO 9001 and ISO 14001 standards for multinational fleet accounts.
Global Graphic Film Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around integrated adhesive chemistry specialists, multi-layer casting technology holders, and regional calendering operators serving price-sensitive signage markets. Three strategic archetypes dominate: proprietary formulation owners, continuous coextrusion equipment operators, and export-oriented calendering specialists. Competitive moves center on capacity expansion in Southeast Asia and strategic partnerships for recycled content certification under EU Green Deal procurement mandates.
Among integrated adhesive chemistry specialists, Avery Dennison Corporation and 3M exemplify the capability-concentrated tier with proprietary formulation control across cast and calendered grades. ORAFOL Europe GmbH occupies a position within the optical clarity specialist segment serving reflective traffic and safety applications. These three entities represent the dominant competitive anchors as fleet operators consolidate approved supplier rosters to three film sources per geography.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison Corporation |
| DuPont de Nemours |
| ORAFOL Europe GmbH |
| HEXIS S.A. |
| Arlon Graphics |
| CCL Industries |
| Dunmore |
| Achilles USA |
| Others |
Supply & Pricing Matrix
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the graphic film value chain, compressing converter gross margins on fixed-price annual contracts while forcing geographic sourcing shifts toward calendering capacity expansion in Southeast Asia.
Pricing Analysis
German cast film commands premium positioning against Thai calendered grades, with three-tier pricing structure across premium, standard, and economy levels separating fleet wrap specifications from commodity signage. Price differentiation hinges on ISO 14001 certification tier and volume scale commitments, with annual contract structures absorbing REACH compliance costs. Cost compression in standard-grade calendered film is intensifying because Thai capacity additions are lowering landed costs for Australian and Middle Eastern buyers. Advertising agencies exhibit highest price sensitivity, while vehicle wrap specialists prioritize conformability warranties over unit economics.
Supply Chain Analysis
Export-control restrictions on proprietary multi-layer casting technology limit equipment flows to qualified integrators in Germany and the United States, concentrating advanced capacity among incumbent technology holders. Geographic supply concentration centers on Germany, Thailand, and the United States, with raw material dependencies drawing from naphtha-derived PVC resin, PET feedstocks, and solvent acrylic adhesive formulations. Single-source vulnerability in proprietary adhesive chemistry creates qualification bottlenecks for new market entrants. Distribution runs through certified converter networks that unbundle installation from material supply for multinational fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where specification consolidation among logistics operators is collapsing approved supplier rosters, creating interoperability barriers for non-certified film sources.
For Market Incumbents: Entrench proprietary adhesive chemistry advantages by deepening backward integration into solvent acrylic formulation production and expanding continuous coextrusion capacity in Germany to serve tightening fleet wrap tolerances. Lock in long-term supply agreements with consolidating logistics operators before qualification windows close to emerging calendering specialists. For New Entrants and Emerging Players: Indian e-commerce logistics penetration represents the most penetrable white-space target, where Bureau of Indian Standards certification protocols are still developing and local slitting infrastructure remains undersupplied. Establish ISO 9001-qualified distribution partnerships with Maharashtra-based converters to capture first-mover advantage in vehicle wrap adoption for last-mile brand visibility campaigns. For Investors and Strategic Acquirers: EU Green Deal procurement mandates reshape the acquisition landscape by advantaging suppliers with certified post-industrial film loops and aqueous topcoat chemistry for latex inkjet compatibility. Target mid-cap specialists with integrated adhesive capabilities and existing converter network relationships rather than pure-play calendering operators exposed to Thai capacity oversupply. Watch for REACH enforcement escalation against phthalate plasticizers as the signal indicating accelerated reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Proprietary solvent acrylic control insulates margin pressure from petrochemical volatility and qualification bottlenecks. |
| Continuous Coextrusion Capacity Expansion | German equipment deployment captures fleet wrap specification tightening below two-micron gauge variation thresholds. |
| Recycled Content Certification Investment | EU Green Deal compliance unlocks public sector signage tender access with mandated post-industrial film loops. |
| Thai Calendering Footprint Addition | Export-oriented capacity captures Australian and Middle Eastern standard-grade procurement through landed cost advantages. |
| Latex Inkjet Topcoat Development | Aqueous receptivity chemistry captures retail interior specifications as METI-aligned guidelines displace solvent systems. |
Research Methodology
Desk research of trade flow databases, customs records, and SEC filings preceded structured interviews with fleet procurement directors, converter plant managers, adhesive chemistry R&D leads, and print house operations heads. Primary fieldwork across Germany, the United States, Thailand, and India validated secondary indicators of capacity expansion and certification program evolution. Bottom-up volume estimates from slitting operation throughput triangulated against top-down petrochemical feedstock consumption patterns.
Assumptions held REACH and EPA regulatory trajectories within announced enforcement timelines while varying petrochemical input cost scenarios across the projection horizon. Segmentation modeling captured cast versus calendered grade tier, application durability requirements, print technology compatibility, and end-user procurement channel. CAGRs derived from elasticity-adjusted demand curves incorporating fleet digitization rates and UV inkjet conversion timelines. Industry-specific inputs included naphtha cracking margin volatility indices and logistics operator merger-driven purchasing power concentration.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Thai calendering specialists or accelerated adhesive chemistry licensing would shift outcomes. Material shifts in EU Green Deal recycled content mandate thresholds or REACH enforcement escalation against phthalate plasticizers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Hornbeam Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Absorbent Booms and Socks Market