
 Charge Generation Materials (CGM) Market | 2026-2036
Charge Generation Materials (CGM) Market Size, Share, and Industry Trends Forecast 2026-2036
Charge Generation Materials (CGM) Market Insights
Photodetector demand is shifting toward high-sensitivity organic photoconductor formulations as lidar and optical sensing deployments multiply. Merck KGaA leverages its liquid crystal materials heritage to anchor European supply chains for specialty CGM precursors. Sumitomo Chemical sustains Japanese domestic production through captive azo pigment chemistry. Idemitsu Kosan competes in vapor-deposited small-molecule layers for imaging drum applications.
Charge generation materials are functional compounds that convert photonic energy into electrical charge carriers, typically comprising azo pigments, phthalocyanine derivatives, or perylene diimides engineered with ionization potentials between 5.0 and 5.8 eV for efficient hole injection. Their primary industrial purpose centers on electrophotographic imaging drums, organic photovoltaic active layers, and photodetector heterojunctions where quantum efficiency exceeds external circuit thresholds. Organic photoconductors dominate volume consumption in legacy laser printer drums where decades of formulation refinement have compressed margins. Nanomaterials represent the fastest-expanding structural category as quantum-dot-enhanced photodetectors penetrate automotive lidar and near-infrared sensing modules. Film form factors capture the majority of value given roll-to-roll coating compatibility with existing display and solar cell fabrication lines.
EPA oversight under the Toxic Substances Control Act governs new CGM substance notifications in the United States, while REACH registration mandates in Europe impose full toxicity dossiers on azo pigment imports. Japan's METI administers Chemical Substances Control Law classifications that restrict perfluorinated photoconductor additives. Stakeholders must monitor evolving substance restriction lists that could disqualify legacy phthalocyanine chemistries from consumer electronics supply chains.
Market Dynamics
Photodetector manufacturers are consolidating procurement around azo pigment and phthalocyanine suppliers capable of delivering REACH-compliant purity grades, compressing the vendor base for legacy organic photoconductors while opening volume contracts for nanomaterial-enhanced formulations.
Growth Catalysts
- Automotive lidar deployment:Tier-1 suppliers are qualifying quantum-dot-enhanced charge generation layers for near-infrared sensing modules, creating specification pull-through from Detroit to Stuttgart.
- EPA notification pathways:Streamlined TSCA review processes for pre-manufacture notifications are accelerating new CGM substance introductions into US electrophotographic supply chains.
- Japan's precision electronics corridor:Concentrated demand from imaging drum fabricators in Kanagawa and Osaka prefectures sustains captive azo chemistry production at scale.
Market Restraints
- Copper phthalocyanine feedstock volatility:Pigment precursor costs fluctuate with copper cathode pricing, squeezing margin stability for drum coating operations.
- East Asian supply concentration:Vapor-deposited small-molecule layer production clusters in Japan and South Korea, exposing buyers to geographic disruption risk.
- Perfluorinated additive restrictions:METI classifications under Japan's Chemical Substances Control Law are disqualifying legacy photoconductor formulations from consumer electronics certification.
Strategic Opportunities
- India's domestic electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating first-mover openings for CGM precursor suppliers establishing local blending capacity.
- Organic photovoltaic integration:Roll-to-roll coating lines for building-integrated photovoltaics represent an emerging application channel with distinct formulation requirements.
- EU Green Deal chemistry mandates:REACH authorization pathways for biodegradable photoconductor alternatives are creating regulatory tailwinds for bio-based azo pigment research.
Industry Challenges
- Thin-film deposition expertise scarcity:Vapor-phase processing of small-molecule charge generation layers requires specialized equipment operators absent from standard chemical engineering pipelines.
- Multi-jurisdictional dossier preparation:Simultaneous REACH registration, EPA notification, and METI filing timelines strain regulatory affairs capacity at mid-scale pigment houses.
- Legacy printer drum compatibility:New CGM formulations must demonstrate drop-in replacement performance against decades-refined organic photoconductor specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charge Generation Materials (CGM) Market |
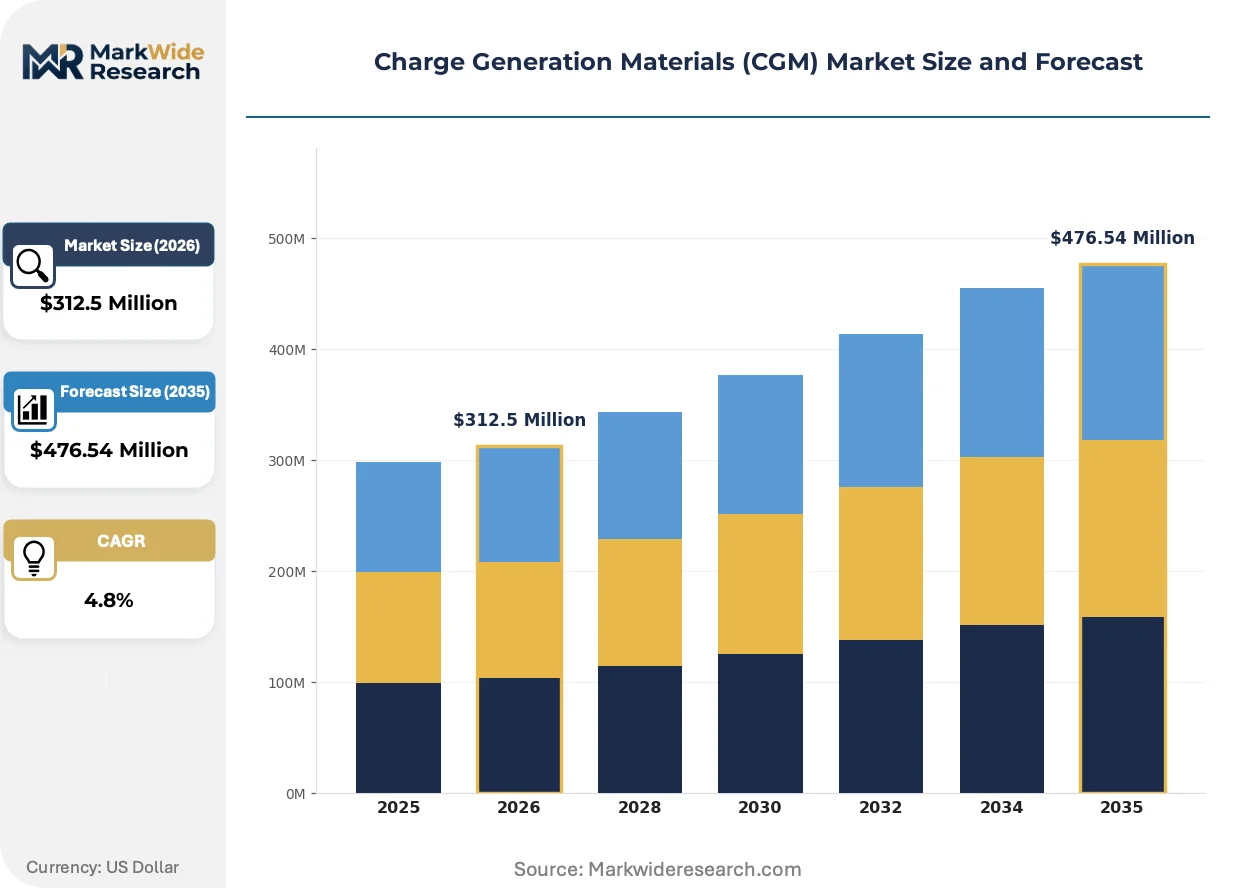
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Organic Photoconductors, Inorganic Photoconductors, Nanomaterials, Biomaterials Application: Consumer Electronics, Solar Cells, Photodetectors, Imaging Systems End User: Manufacturers, Research Institutions, Commercial Enterprises, Government Agencies Form Factor: Films, Powders, Coatings, Composites |
| Companies Covered | Merck KGaA, Sumitomo Chemical, Idemitsu Kosan, BASF, Eastman Kodak, DuPont, Hewlett-Packard, Canon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charge Generation Materials (CGM) Market Trends and Innovations
Formulation science is converging with deposition process control as manufacturers seek to bridge the performance gap between solution-processed and vapor-deposited charge generation architectures.
Hybrid organic-inorganic nanocomposite charge generation layers are unifying the quantum efficiency advantages of quantum dots with the manufacturing scalability of solution coating. Automotive lidar module suppliers in Germany and Japan are accelerating qualification timelines for these formulations. The technology is unifying previously separate supplier ecosystems—specialty chemical houses and nanomaterials startups—into integrated coating partnerships.
REACH authorization timelines for azo pigment intermediates are compressing the window for legacy chemistry reliance in European electrophotographic supply chains. ECHA's evolving substance restriction lists are forcing drum manufacturers to validate alternative charge generation precursors before 2026 regulatory deadlines. German imaging equipment producers are responding by dual-sourcing phthalocyanine and perylene diimide formulations to maintain CE marking compliance.
Specification-driven vendor consolidation is concentrating procurement decisions at fewer buyer entities with dedicated materials science teams. Long-tail distributors serving regional printer refurbishment shops are losing share to direct mill relationships with Tokyo and Seoul-based drum fabricators. This concentration is most visible in Japan's Kansai region, where precision electronics manufacturers have consolidated 80% of domestic organic photoconductor purchasing under three procurement consortia.
Charge Generation Materials (CGM) Market Segmentation
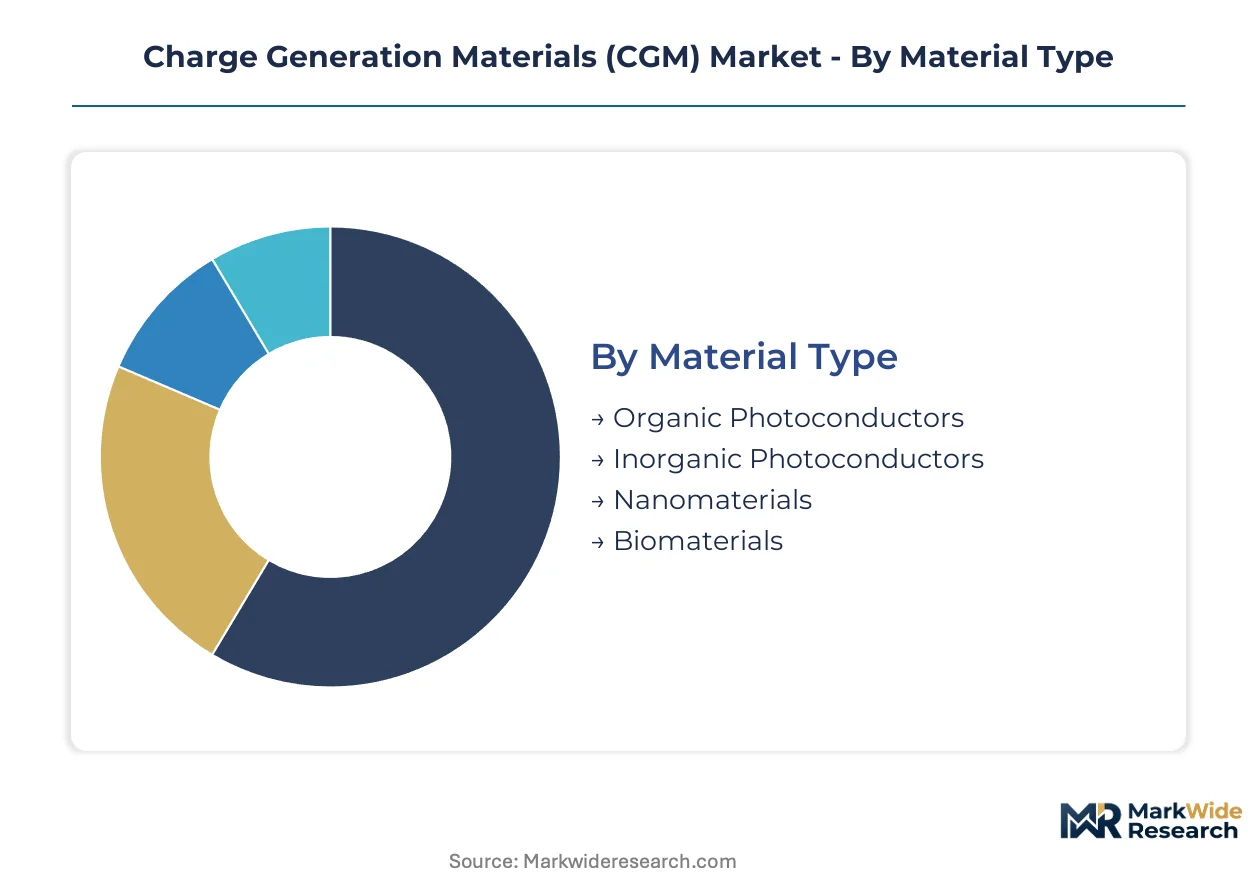
Segmentation in charge generation materials reflects divergent regulatory pathways and manufacturing scale requirements. Material chemistry dictates certification burdens, while form factor determines coating equipment compatibility and end-use accessibility.
Material Type:
REACH registration intensity varies sharply across this category, with azo pigment derivatives facing full toxicity dossier requirements under ECHA mandates while nanomaterial formulations trigger novel substance notifications in multiple jurisdictions.
- Organic Photoconductors:Azo pigments and phthalocyanine derivatives engineered with ionization potentials between 5.0 and 5.8 eV dominate legacy electrophotographic drum manufacturing. Procurement concentrates in Japan's Kanagawa and Osaka prefectures where imaging equipment fabricators sustain captive azo chemistry production at scale.
- Nanomaterials:Quantum-dot-enhanced formulations and hybrid organic-inorganic nanocomposites enable near-infrared quantum efficiency for automotive lidar modules. Demand is accelerating fastest in Germany and Japan as Tier-1 suppliers qualify these layers for sensing applications.
- Inorganic Photoconductors:Selenium-based and silicon-based architectures serve specialized high-voltage imaging applications requiring thermal stability beyond organic limits.
- Biomaterials:Emerging bio-based azo pigment alternatives seek REACH authorization pathways under EU Green Deal chemistry mandates.
Organic photoconductors sit at the top of the volume ranking, with nanomaterials climbing the fastest.
Application:
Application segmentation tracks directly to deposition process maturity and roll-to-roll coating line availability.
- Imaging Systems:Electrophotographic drums for laser printers represent the most mature application channel with decades of formulation refinement compressing margins. Manufacturing clusters in East Asia sustain organic photoconductor volume consumption through established coating partnerships.
- Photodetectors:Lidar and optical sensing deployments are multiplying specification requirements for high-sensitivity organic photoconductor formulations. German and Japanese automotive module suppliers are consolidating procurement around REACH-compliant purity grades.
- Solar Cells:Organic photovoltaic active layers and building-integrated photovoltaics demand distinct formulation requirements for roll-to-roll compatibility.
- Consumer Electronics:METI classifications under Japan's Chemical Substances Control Law restrict perfluorinated photoconductor additives in this channel.
Imaging systems generate the highest absolute volume, while photodetectors show the steepest expansion trajectory.
End User:
End user type determines order scale, technical service intensity, and regulatory documentation requirements.
- Manufacturers:Imaging drum fabricators and photodetector module producers purchase at commercial scale with dedicated materials science teams managing direct mill relationships. Three procurement consortia in Japan's Kansai region now consolidate 80% of domestic organic photoconductor purchasing.
- Research Institutions:Universities and national laboratories drive formulation innovation for next-generation nanocomposite architectures.
- Commercial Enterprises:Regional printer refurbishment shops are losing procurement share to concentrated buyer entities.
- Government Agencies:Defense and space applications specify custom purity grades with extended qualification timelines.
Manufacturers command the largest order volumes, with research institutions expanding fastest as quantum-dot formulation programs multiply.
Form Factor:
Form factor selection constrains equipment capital requirements and coating line retrofit compatibility.
- Films:Roll-to-roll coated layers capture the majority of value given compatibility with existing display and solar cell fabrication infrastructure. Film deposition expertise scarcity limits supplier entry.
- Coatings:Solution-processed formulations bridge performance gaps for manufacturers lacking vapor-phase equipment.
- Powders:Dry pigment precursors serve drum manufacturers with in-house dispersion capabilities.
- Composites:Hybrid structural formats integrate charge generation and transport functions in single-layer architectures.
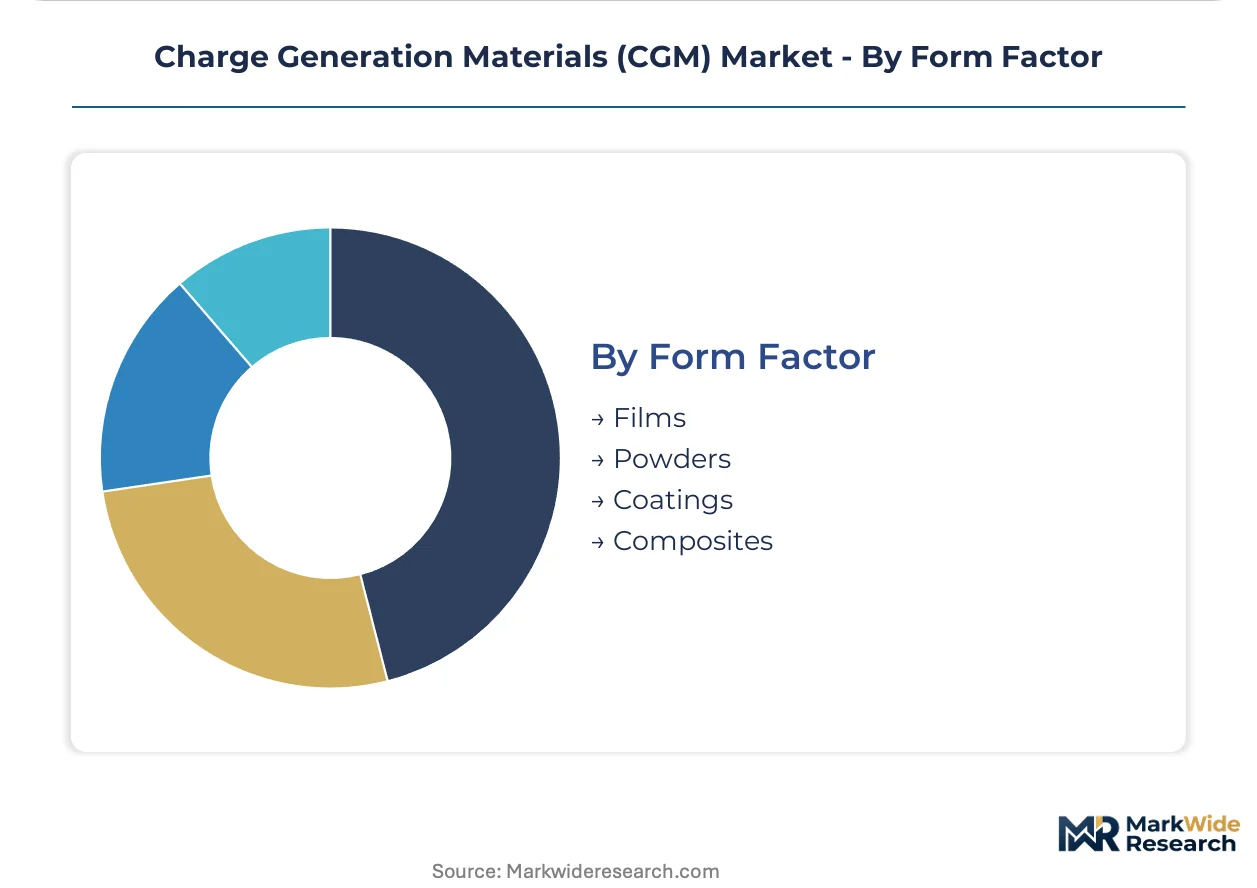
Films dominate value capture, with coatings gaining share fastest among mid-scale pigment houses seeking deposition flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting capital toward production zones with streamlined chemical substance notification pathways. Manufacturers are relocating formulation blending capacity to exploit gaps in REACH-equivalent compliance burdens while maintaining quality certification for export markets.
Japan
Automotive lidar module demand from Tier-1 suppliers in Stuttgart and Detroit is qualifying quantum-dot-enhanced charge generation layers produced in Kanagawa and Osaka prefectures. METI's Chemical Substances Control Law classifications restrict perfluorinated photoconductor additives, forcing reformulation of legacy products. Imaging drum fabricators in the Kansai region have consolidated procurement under three consortia controlling 80% of domestic organic photoconductor purchasing.
Germany
REACH authorization timelines for azo pigment intermediates are compressing reliance windows for legacy chemistries in European electrophotographic supply chains. ECHA's evolving substance restriction lists mandate validation of alternative charge generation precursors before 2026 regulatory deadlines. German imaging equipment producers in Baden-Württemberg are dual-sourcing phthalocyanine and perylene diimide formulations to maintain CE marking compliance.
United States
Streamlined TSCA review processes for pre-manufacture notifications are accelerating new CGM substance introductions into domestic electrophotographic supply chains. EPA oversight under the Toxic Substances Control Act governs new substance notifications while state-level chemical disclosure laws add secondary compliance layers. Precision electronics manufacturers in Texas and California are expanding procurement of high-purity organic photoconductors for photodetector applications.
China
Domestic display and solar cell fabrication expansion is driving roll-to-roll coating line investment compatible with film-form charge generation materials. GB standards administered by SAMR govern chemical substance safety in consumer electronics applications. Yangtze River Delta manufacturing clusters are attracting foreign CGM precursor suppliers establishing localized blending capacity for regional photovoltaic integration.
South Korea
Vapor-deposited small-molecule layer production for imaging drums concentrates in Seoul Capital Area and Busan-Ulsan industrial corridors. MFDS chemical safety classifications align with international purity thresholds for photodetector-grade formulations. Domestic photodetector module producers are consolidating procurement around REACH-compliant azo pigment and phthalocyanine suppliers.
Charge Generation Materials (CGM) Market Competitive Landscape
Capacity expansion dominates the current landscape as specialty chemical houses and nanomaterials startups integrate into unified coating partnerships. The vendor base separates into three tiers: multinational diversified chemical conglomerates with liquid crystal materials heritage, Japanese captive producers with azo pigment chemistry expertise, and emerging nanocomposite specialists. Two competitive moves define current positioning: backward integration into precursor synthesis and geographic expansion into India's PLI-subsidized electronics manufacturing zones.
Among diversified chemical conglomerates, Merck KGaA and BASF occupy positions anchored by European supply chain infrastructure for specialty CGM precursors. Japanese specialists Sumitomo Chemical and Idemitsu Kosan exemplify the captive production archetype, with the former sustaining domestic azo pigment chemistry and the latter competing in vapor-deposited small-molecule architectures. These four entities represent distinct strategic postures: REACH compliance leadership, geographic concentration in precision electronics corridors, and deposition process specialization respectively.
| Leading Market Players |
|---|
| Merck KGaA |
| Sumitomo Chemical |
| Idemitsu Kosan |
| BASF |
| Eastman Kodak |
| DuPont |
| Hewlett-Packard |
| Canon |
Pricing and Supply Chain Analysis
Three procurement consortia in Japan's Kansai region now control four-fifths of domestic organic photoconductor purchasing, concentrating buyer power and compressing channel margins for legacy drum coating formulations. This consolidation forces pricing discipline through direct mill relationships that bypass traditional distribution markups.
Pricing Analysis
Distributor margins for specialty CGM precursors have compressed to single-digit percentages as drum fabricators in Kanagawa and Osaka prefectures consolidate direct procurement. Three-tier pricing structure across photodetector-grade, imaging drum-standard, and refurbishment-economy levels reflects purity certification tiers under REACH and METI frameworks. Cost compression in legacy azo pigment formulations is intensifying because copper phthalocyanine feedstock volatility squeezes coating operation margins. Regional printer refurbishment shops exhibit highest price sensitivity, while automotive lidar module suppliers accept premium positioning for quantum-dot-enhanced layers.
Supply Chain Analysis
Refurbishment flows for imaging drums in Europe and North America create secondary raw material recovery channels that compete with virgin azo pigment supply. Production clusters in Japan, South Korea, and Germany anchor global supply, with vapor-deposited small-molecule layer fabrication drawing from specialized precursor synthesis capabilities. Copper cathode pricing volatility and perfluorinated additive restrictions under METI classifications constitute the primary structural risk. Distribution runs through direct mill relationships with precision electronics manufacturers, displacing long-tail distributors serving regional refurbishment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charge generation materials constitute a late-cycle quality story as automotive lidar deployment shifts procurement specifications toward quantum-dot-enhanced formulations with stringent REACH compliance requirements. This premium specification pull-through rewards suppliers with validated purity dossiers and deposition process control.
For Market Incumbents: Deepen backward integration into azo pigment precursor synthesis to offset copper phthalocyanine feedstock volatility and secure margin stability. Establish captive vapor-deposition expertise in South Korea's Seoul Capital Area to defend against emerging nanocomposite specialists. Prioritize dual-sourcing validation of phthalocyanine and perylene diimide alternatives ahead of ECHA substance restriction deadlines.
For New Entrants and Emerging Players: Mid-scale pigment houses in India's PLI-subsidized electronics manufacturing zones represent the most penetrable buyer archetype for solution-processed coating formulations lacking vapor-phase equipment. Building-integrated photovoltaics roll-to-roll coating lines offer white-space entry with distinct formulation requirements separate from saturated drum coating channels. Lead with deposition flexibility and regulatory dossier preparation services rather than price competition.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with liquid crystal materials heritage are the most active acquirer in this space, seeking nanocomposite coating partnerships to bridge quantum efficiency and manufacturing scalability. Target formulation houses with validated REACH registration pathways and thin-film deposition operator training programs. Monitor ECHA authorization timeline acceleration for azo pigment intermediates as the critical inflection signal for legacy chemistry displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive azo pigment chemistry secures margin stability against copper cathode volatility. |
| REACH Registration Acceleration | Early toxicity dossier completion locks in European electrophotographic supply chain access. |
| Quantum-Dot Coating Partnership | Hybrid organic-inorganic nanocomposite integration unifies previously separate supplier ecosystems. |
| India PLI Zone Blending Capacity | Localized precursor supply captures semiconductor and display fabrication incentive flows. |
| Vapor-Deposition Operator Training | Thin-film processing expertise scarcity limits supplier entry and commands premium positioning. |
Research Methodology
Coverage spans Japan, Germany, the United States, China, and South Korea, with primary inputs from each jurisdiction's precision electronics manufacturing clusters. The research combines structured interviews with imaging drum procurement directors, photodetector module materials scientists, specialty chemical regulatory affairs leads, and vapor-deposition equipment operators with secondary validation through customs trade data, SEC filings from diversified chemical conglomerates, ECHA substance registration databases, and METI chemical substance control notifications. Bottom-up volume modeling triangulates against top-down value estimates derived from procurement consortium purchasing patterns.
Granularity extends to material chemistry type, form factor compatibility, and end-use application with distinct deposition process requirements. Segmentation dimensions include organic photoconductor versus nanomaterial versus inorganic architectures, film versus coating versus powder versus composite formats, and imaging systems versus photodetectors versus solar cells versus consumer electronics channels. CAGRs were derived from fitted growth curves applied to procurement volume trajectories across the projection horizon, incorporating automotive lidar qualification timelines and REACH authorization deadline impacts as industry-specific forecast inputs.
Underlying measurement precision varies by segment; nanomaterial formulations carry tighter precision than legacy organic photoconductor volumes given concentrated buyer visibility. Forecasts reflect assumptions regarding regulatory timeline adherence, copper feedstock price stability, and quantum-dot deposition yield improvements. Practitioners should monitor ECHA substance restriction list updates, METI perfluorinated additive classification changes, and India PLI scheme electronics manufacturing capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Silicone Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Mica Sheet Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Organic Scintillators Market