
 Biopolymer Films Market | 2026-2036
Biopolymer Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biopolymer Films Market Analysis
Advanced extrusion and multilayer coextrusion technologies are reshaping how biopolymer films achieve barrier parity with conventional plastics. NatureWorks LLC leverages its integrated PLA resin-to-film pipeline to control quality and supply security for food packaging converters. Novamont S.p.A. anchors European capacity for starch-based and compostable grades, sustaining dominance in regulated retail bag markets. Toray Industries specializes in high-performance cellulose-derived films for electronics and medical applications where optical clarity and dimensional stability matter.
Biopolymer films are thin, flexible or rigid layers engineered from renewable biological feedstocks such as corn starch, cellulose, chitosan, or polylactic acid, typically processed through cast extrusion, blown film extrusion, or solution casting to achieve controlled thickness, tensile strength, and oxygen or moisture barrier properties for protective, functional, or decorative applications. PLA-based films lead in food packaging due to favorable clarity and sealability, though starch-based alternatives compete aggressively on cost in short-use agricultural mulch and carrier bag segments where full biodegradability within soil composting cycles is specified. Medical and coating applications occupy smaller volume positions but command margin pools tied to biocompatibility certification and custom formulation services.
The EU Green Deal and REACH frameworks mandate recyclability and restricted substance thresholds that redirect converter procurement toward certified compostable films, while FDA food contact notifications and USDA bio-preferred labeling shape product qualification pathways in North America. Japan's METI has issued plastic resource circulation guidelines that classify certified biobased films as preferred alternatives in public procurement, tightening market access for petroleum-derived competitors. Stakeholders must monitor how evolving composting infrastructure certification standards in target geographies determine which film chemistries qualify for premium labeling and regulatory compliance.
Market Dynamics
The EU Green Deal and Packaging and Packaging Waste Regulation are redirecting converter procurement toward certified compostable films, creating procurement friction for petroleum-derived alternatives while concentrating demand around PLA and starch-based supply clusters in Germany and Italy.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds and single-use plastic bans across European member states are forcing food packaging converters to qualify compostable films for retail bag and fresh produce applications.
- Japan METI plastic resource circulation guidelines:Public procurement preferences for certified biobased films are opening institutional demand channels for cellulose-derived and PLA grades in municipal and healthcare packaging.
- Multilayer coextrusion advancement:Barrier parity achievements with conventional plastics are unlocking oxygen-sensitive food categories previously closed to biopolymer solutions.
Market Restraints
- Feedstock cost volatility:Corn starch and sugarcane-derived lactic acid prices fluctuate with agricultural commodity cycles, compressing margin stability for PLA film producers against petroleum-based polyethylene.
- Composting infrastructure gaps:Industrial composting facility scarcity in Eastern Europe and parts of North America limits addressable market for certified compostable grades requiring specific end-of-life conditions.
- Performance limitations in high-humidity:Starch-based films exhibit moisture sensitivity that excludes them from refrigerated fresh meat and seafood packaging where extended shelf life is specified.
Strategic Opportunities
- USDA BioPreferred program expansion:Federal procurement mandates and voluntary labeling are creating pull-through demand for certified biobased content in government food service and institutional packaging contracts.
- Medical device coating applications:Biocompatibility certification pathways for chitosan and cellulose-derived films are opening margin pools in wound care and drug delivery substrates.
- Agricultural mulch film replacement:Soil-biodegradability specifications in Italian and Spanish farming regions are driving specification shifts away from conventional polyethylene mulch.
Industry Challenges
- Composting certification timeline compression:Evolving EN 13432 and ASTM D6400 testing protocols require reformulation cycles that delay product launches by 12-18 months.
- Extrusion technician scarcity:Specialized knowledge in biopolymer rheology and moisture control during blown film processing is concentrated among aging workforces in European packaging hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopolymer Films Market |
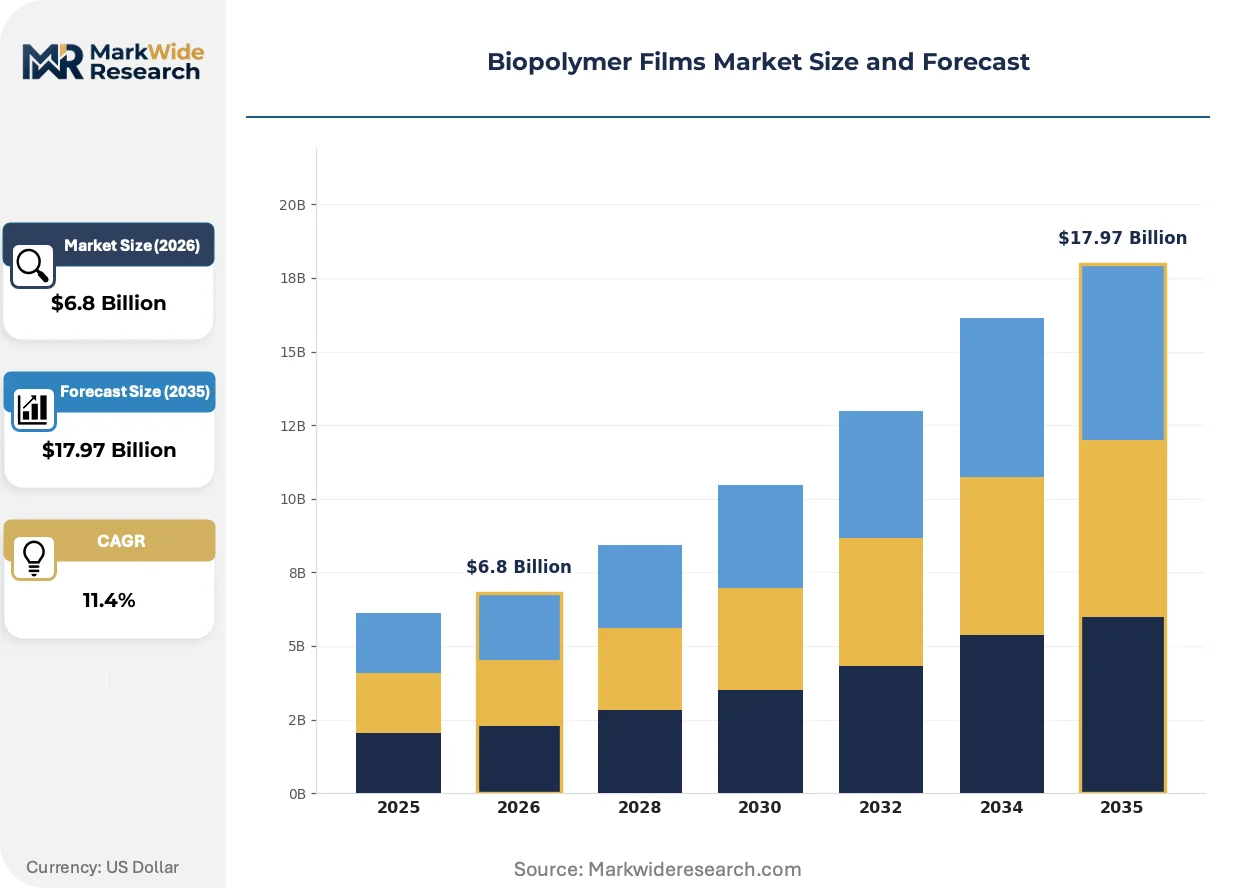
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-based, Cellulose-based, Chitosan-based, PLA-based Application: Packaging, Agriculture, Medical, Coating End User: Food Industry, Healthcare, Consumer Goods, Industrial Form: Flexible, Rigid, Biodegradable, Composite |
| Companies Covered | NatureWorks LLC, BASF SE, Novamont S.p.A., Toray Industries, Mondi Group, Taghleef Industries, Danimer Scientific, Braskem, Total Corbion PLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopolymer Films Market Emerging Trajectories
Barrier engineering and end-of-life certification are converging to redefine competitive positioning, with technology investments clustering around performance parity and regulatory qualification rather than cost minimization alone.
Active barrier coatings derived from nanocellulose and chitosan are migrating from laboratory demonstration to commercial food packaging lines. Modified atmosphere packaging converters in Germany and the Netherlands are qualifying these coatings for cheese and cured meat applications where oxygen transmission rates below 1 cc/m²/day are specified. The migration from conventional metallized PET laminates is compressing multilayer complexity and enabling thinner overall film constructions.
REACH restricted substance thresholds and the EU Green Deal's packaging recyclability mandates are forcing reformulation of conventional plastic additives. Film converters serving European retail chains are eliminating per- and polyfluoroalkyl substances from barrier layers ahead of 2025 enforcement deadlines. Starch-based and PLA grades with certified additive compliance are capturing specification wins in fresh produce and bakery segments where brand owners face retailer sustainability scorecards.
Brand-owner sustainability scorecards are redirecting supplier selection criteria toward verified end-of-life outcomes rather than biobased content alone. European grocery retailers are unbundling traditional packaging procurement to require separate composting certification documentation from film suppliers. This behavioral shift is most visible in German and French fresh produce supply chains where private-label packaging specifications now mandate industrial composting facility access maps for each SKU.
Biopolymer Films Market Segmentation
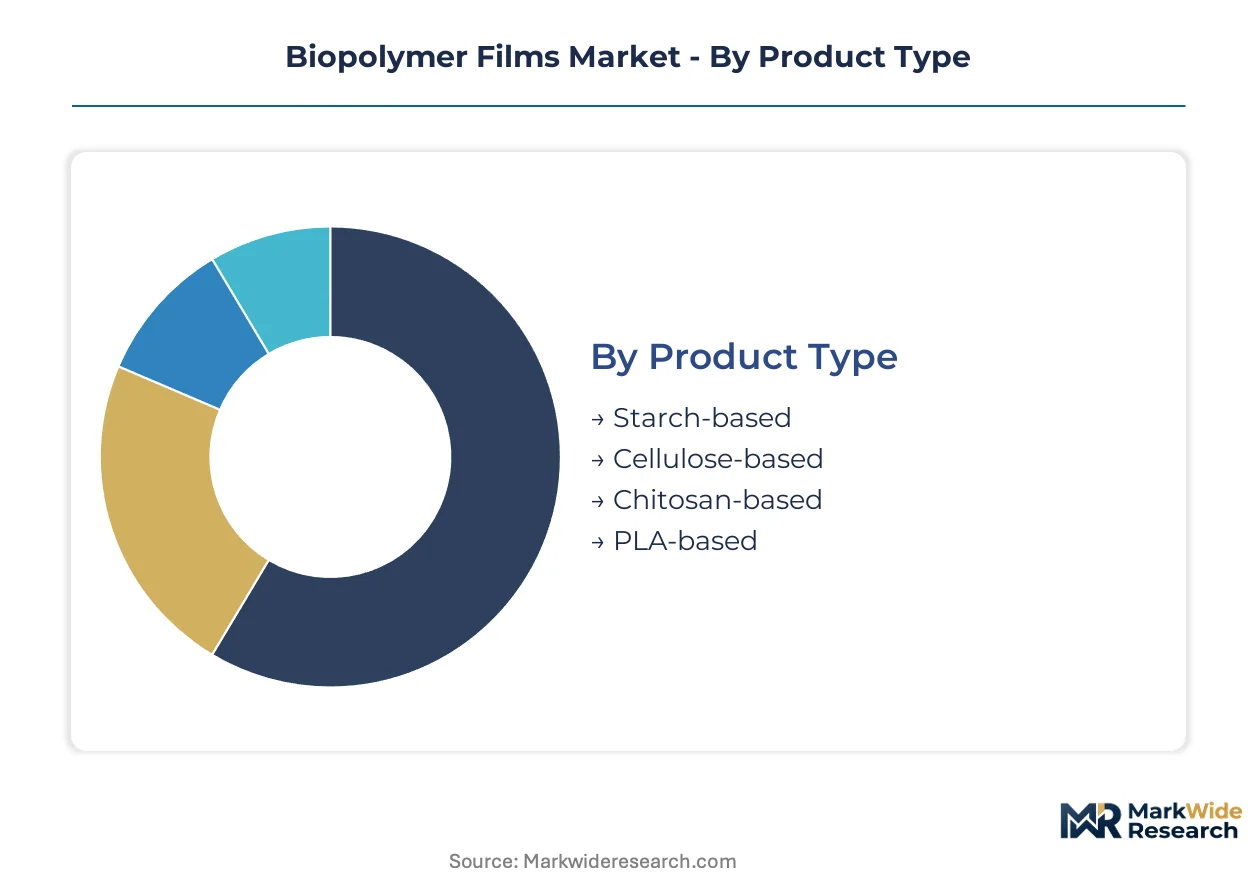
Segmentation in biopolymer films reveals how material chemistry, functional requirements, and end-of-life specifications fragment procurement patterns across converters. Each dimension—product type, application, end user, and form—carries distinct certification burdens and performance thresholds that reshape supplier qualification workflows.
Product Type:
Mature extrusion technologies dominate starch and cellulose derivatives, while PLA and chitosan formulations occupy emerging positions with steeper technical learning curves.
- Starch-based:Thermoplastic starch blends processed via blown film extrusion deliver cost-competitive biodegradability for short-use carrier bags and agricultural mulch. German retail chains specify these grades for private-label produce bags under EU Green Deal compliance timelines.
- PLA-based:Polylactic acid films produced from corn-derived lactic acid offer optical clarity and heat-sealability rivaling conventional plastics. Fresh produce packaging converters in the Netherlands and Belgium prioritize PLA for modified atmosphere applications where shelf-life extension justifies premium pricing.
- Cellulose-based:Regenerated cellulose and cellophane variants provide grease resistance and dead-fold characteristics for confectionery and bakery wraps.
- Chitosan-based:Marine-derived polysaccharide films command niche positioning in antimicrobial food coatings and biomedical substrates requiring biocompatibility certification.
Starch-based films retain volume leadership; PLA-based grades hold the steepest expansion curve.
Application:
Application segmentation tracks how barrier performance requirements and regulatory exposure determine material selection across use cases spanning disposable packaging to durable technical films.
- Packaging:Food contact films constitute the dominant application, with oxygen and moisture barrier specifications varying sharply by product category. Modified atmosphere packaging for cheese and cured meats demands multilayer constructions with oxygen transmission rates below 1 cc/m²/day, driving adoption of nanocellulose-coated PLA in German and Dutch converter lines.
- Agriculture:Soil-biodegradable mulch films replace conventional polyethylene in Italian and Spanish farming regions where till-in disposal eliminates collection costs. Starch-based formulations dominate this segment, though UV stability limitations restrict growing-season duration.
- Medical:Sterile barrier films and drug delivery substrates require ISO 10993 biocompatibility certification, creating margin pools for chitosan and cellulose derivatives in wound care applications.
- Coating:Functional coatings for paper and board leverage biopolymer barrier layers to eliminate per- and polyfluoroalkyl substances ahead of REACH enforcement deadlines.
Packaging commands absolute revenue share; agriculture is climbing fastest as soil-biodegradability specifications tighten.
End User:
End user segmentation exposes how procurement authority and sustainability scorecard pressure concentrate demand among food industry buyers with the most stringent compliance obligations.
- Food Industry:Retail chains and fresh produce packers drive specification-setting for compostable films, with German and French grocery retailers now mandating industrial composting facility access documentation for each SKU. Private-label packaging teams unbundle traditional procurement to verify end-of-life outcomes separately from biobased content claims.
- Healthcare:Hospital systems and medical device manufacturers prioritize sterilization compatibility and biocompatibility certification over biodegradability, favoring cellulose-derived films for sterile barrier applications.
- Consumer Goods:Personal care and household product brands specify biopolymer windows and overwraps for sustainability positioning, though cost sensitivity limits penetration in mass-market segments.
- Industrial:Technical applications including electronics packaging and adhesive tapes exploit dimensional stability and optical clarity in cellulose-derived grades.
Food Industry retains procurement volume dominance; Healthcare is expanding most quickly as biocompatibility certification pathways mature.
Form:
Form segmentation distinguishes how mechanical properties and end-of-life behavior segment manufacturing processes and converter equipment requirements.
- Flexible:Thin-gauge films processed via cast or blown extrusion serve wrapping, bagging, and lamination applications where conformability and sealability are paramount. Flexible formats constitute the overwhelming majority of food packaging volume.
- Rigid:Thermoformed sheets and molded trays provide structural integrity for clamshell produce packaging and medical device trays, requiring higher crystallinity PLA grades with elevated heat deflection temperatures.
- Biodegradable:Certified compostable films carrying EN 13432 or ASTM D6400 qualification command premium positioning in regulated European markets where industrial composting infrastructure supports specified end-of-life pathways.
- Composite:Multilayer constructions combining biopolymer substrates with bio-based coatings or tie layers optimize barrier performance while maintaining compostability claims, though recycling complexity increases with layer count.
Flexible formats maintain volume leadership; biodegradable-certified grades are gaining share fastest as regulatory compliance hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biopolymer film exports flow into French and Dutch fresh produce supply chains, while Italian agricultural mulch specifications pull starch-based formulations southward across Alpine logistics corridors.
Germany
Food packaging converters in the Rhine-Ruhr cluster specify PLA grades for modified atmosphere cheese applications. The EU Green Deal and Packaging and Packaging Waste Regulation mandate industrial composting certification for retail carrier bags. BASF SE anchors production capacity in Ludwigshafen, supplying certified films to Rewe and Aldi Süd private-label programs.
France
Paris-based retail chains unbundle procurement to require composting facility access documentation per SKU. REACH restricted substance thresholds eliminate per- and polyfluoroalkyl substances from barrier layers by 2025. Converter clusters in the Hauts-de-France region qualify nanocellulose-coated PLA for Carrefour and Intermarché bakery segments.
Italy
Soil-biodegradable mulch film specifications in Emilia-Romagna and Veneto farming regions displace conventional polyethylene. The EU Green Deal compliance timelines accelerate specification shifts ahead of 2025 enforcement. Novamont S.p.A. maintains production headquarters in Novara, anchoring starch-based supply to Mediterranean agricultural cooperatives.
Netherlands
Modified atmosphere packaging converters in Rotterdam and Eindhoven demand oxygen transmission rates below 1 cc/m²/day for cured meat exports. ECHA guidance on polymer recyclability redirects procurement toward certified compostable grades. Dutch retail cooperative Albert Heijn mandates industrial composting infrastructure verification across its fresh produce supply base.
Japan
METI plastic resource circulation guidelines classify certified biobased films as preferred alternatives in municipal and healthcare procurement. Public hospital systems in Tokyo and Osaka prioritize sterilization compatibility over biodegradability. Toray Industries anchors cellulose-derived film production in Shiga Prefecture for electronics and medical substrate applications.
Biopolymer Films Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base clusters around integrated resin producers, film converters with captive formulation expertise, and regional packaging conglomerates with sustainability scorecard leverage. Three archetypes dominate: upstream resin-to-film integrators, multilayer coextrusion specialists, and retail-channel converters with private-label specification authority. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with firms securing composting certification ahead of regulatory deadlines.
Among integrated resin-to-film specialists, NatureWorks LLC and Total Corbion PLA exemplify upstream control over lactic acid supply chains. Novamont S.p.A. occupies a position within the starch-based formulation tier, anchoring European compostable grade capacity. Toray Industries represents the high-performance cellulose derivative segment, serving medical and electronics applications where optical clarity specifications exceed commodity packaging thresholds.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| Novamont S.p.A. |
| Toray Industries |
| Mondi Group |
| Taghleef Industries |
| Danimer Scientific |
| Braskem |
| Total Corbion PLA |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European PLA resin production is pressuring film converters toward aggressive volume discounts while compressing margins for starch-based grades competing against subsidized agricultural feedstock imports. This utilization imbalance redirects procurement negotiations toward long-term offtake contracts with indexed raw material pass-through clauses.
Pricing Analysis
Cost-plus contracts indexed to corn starch and lactic acid commodity benchmarks dominate procurement between German resin producers and downstream converters. Three-tier pricing structure across premium certified compostable, standard industrial-grade, and economy agricultural mulch levels segments buyer budgets. Pricing pressure stems from subsidized Brazilian sugarcane-derived PLA entering European spot markets. Fresh produce packers exhibit highest price sensitivity, while medical device manufacturers accept premiums for ISO 10993-certified chitosan grades.
Supply Chain Analysis
Extended payment terms of 90-120 days from Rewe and Carrefour procurement teams strain working capital for mid-sized Italian converters, accelerating adoption of supply-chain finance facilities anchored by Novamont S.p.A. Production gravity centers on Germany, Italy, and the Netherlands, with raw material dependencies on Ukrainian corn starch, Brazilian sugarcane, and Southeast Asian chitosan feedstocks. Tariff exposure on agricultural commodity imports creates margin volatility. Distribution runs through converter-direct relationships with retail private-label programs, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopolymer film procurement is approaching a platform-economics inflection where industrial composting infrastructure access maps become the interoperability layer connecting resin certification to retail SKU qualification.
For Market Incumbents: Pre-empt margin erosion from subsidized Brazilian PLA by securing backward integration into lactic acid fermentation capacity in Ludwigshafen or Novara. Anchor long-term offtake with Dutch modified atmosphere packaging converters before 2025 REACH enforcement deadlines eliminate competitor additive portfolios. For New Entrants and Emerging Players: Build out soil-biodegradable mulch film production capacity in Emilia-Romagna to capture specification shifts away from polyethylene in Italian farming cooperatives. Target agricultural supply channels with direct technical service models rather than competing through converter intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-to-film specialists with captive composting certification pipelines. Five-to-ten year viability favors acquisition targets holding EN 13432 qualification ahead of EU Green Deal enforcement expansion. Monitor composting facility buildout rates in Eastern Europe as inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Composting Certification Acceleration | EN 13432 pre-qualification locks in Rewe and Aldi Süd shelf access ahead of regulatory deadlines. |
| Backward Integration into Lactic Acid | Captive fermentation capacity insulates Total Corbion PLA from Brazilian sugarcane price volatility. |
| Nanocellulose Coating Commercialization | Toray Industries barrier patents unlock oxygen-sensitive cheese packaging previously closed to biopolymers. |
| Agricultural Mulch Specification Capture | Novamont S.p.A. till-in biodegradability claims displace polyethylene in Italian tomato cultivation regions. |
| Industrial Composting Infrastructure Mapping | Facility access documentation satisfies Carrefour unbundled procurement requirements per SKU. |
Methodological Framework
Desk research of EU regulatory filings, ECHA polymer registration databases, and customs trade statistics preceded structured interviews with blown film extrusion technicians, retail packaging procurement managers, industrial composting facility operators, and agricultural cooperative supply directors. Primary fieldwork across Rhine-Ruhr converter clusters and Emilia-Romagna farming regions validated secondary estimates. Bottom-up volume modeling triangulated against top-down resin capacity assessments.
Assumptions held fixed include EU Green Deal enforcement timelines and existing composting infrastructure distribution; variables tested included Brazilian PLA import tariff scenarios and corn starch price volatility bands. Segmentation dimensions spanned material chemistry, application barrier requirements, end-user procurement authority, and form factor specifications. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through. Forecast inputs included lactic acid fermentation capacity expansion announcements and retail sustainability scorecard weighting shifts.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-subsidized Brazilian resin producers would shift pricing outcomes substantially. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biopolymers Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market