
 South America Polyether Ether Ketone (Peek) Market | 2026-2036
South America Polyether Ether Ketone (Peek) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyether Ether Ketone (Peek) Market Insights
Brazil's southeastern manufacturing belt is fragmenting as new compounding capacity comes online near São Paulo and Campinas. Victrex PLC leverages its global polymer expertise to supply high-purity grades for medical implant applications across the region. Solvay anchors its position through backward integration into key monomer precursors, securing supply continuity for Brazilian processors. Evonik Industries AG differentiates via specialized filled compounds targeting thermal management in automotive electronics.
Polyether ether ketone is a semi-crystalline thermoplastic belonging to the polyaryletherketone family, synthesized through step-growth polymerization of difluorobenzophenone and hydroquinone to yield a polymer with a melting point near 343°C and continuous service temperature up to 260°C. Its inherent flame resistance, chemical inertness, and mechanical retention at elevated temperatures make it indispensable for metal replacement in load-bearing components subjected to aggressive environments. Filled grades command premium positioning due to carbon fiber and glass reinforcement delivering stiffness-to-weight ratios critical for aerospace brackets and orthopedic implants. Medical applications represent the fastest-expanding demand pool as Brazilian and Argentine hospitals upgrade surgical instrument sterilization protocols. Unfilled virgin resin maintains volume leadership in general industrial sealing and valve components where machinability and purity specifications are less stringent.
ANVISA governs medical-grade PEEK implant approvals through Resolution RDC 185/2001, while INMETRO administers conformity assessment for automotive and electrical applications under Mercosur technical regulations. Argentina's ANMAT maintains parallel pharmaceutical and medical device oversight that imposes additional testing burdens on cross-border suppliers. Brazil's PLI-style industrial incentives for advanced materials are channeling R&D tax credits toward domestic PEEK compounding capabilities. Stakeholders must monitor Mercosur regulatory harmonization progress, as divergence between Brazilian and Argentine standards continues to fragment procurement specifications and complicate regional scale economics.
Market Dynamics
Brazil's tightening biocompatibility standards under ANVISA Resolution RDC 185/2001 are compressing qualification timelines for medical-grade PEEK, forcing suppliers to accelerate certification investments or cede implantable device contracts to pre-qualified competitors.
Growth Catalysts
- ANVISA implant-grade certification requirements:Brazil's medical device regulator mandates stricter biocompatibility testing for spinal and orthopedic implants, creating dedicated demand for high-purity PEEK compounds that withstand gamma sterilization protocols.
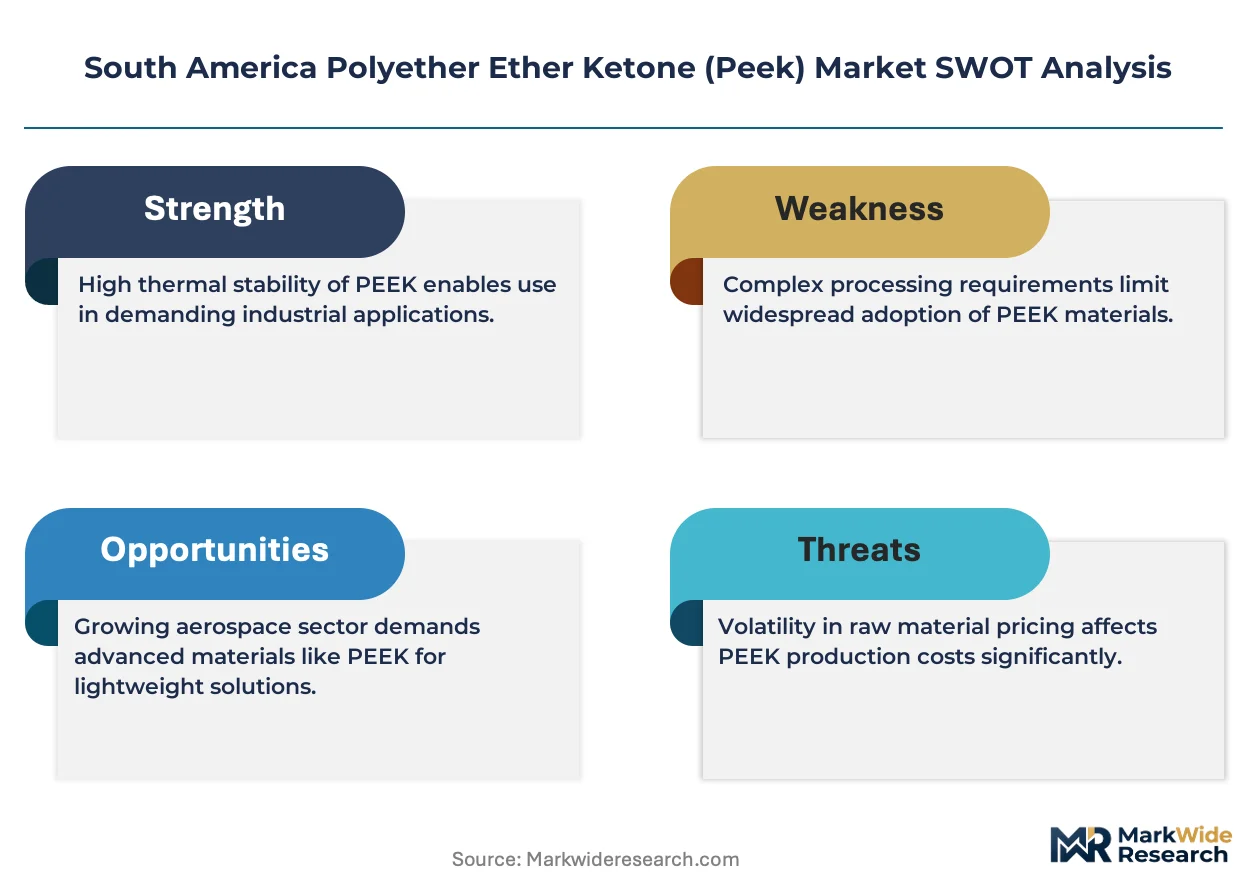
- Aerospace lightweighting mandates:Brazilian and Argentine aircraft manufacturers face fuel efficiency pressures that favor carbon fiber-reinforced PEEK brackets and ducting over aluminum equivalents in engine nacelles and interior structures.
- Automotive electronics thermal management:São Paulo's automotive electronics cluster requires filled PEEK grades for connector housings and sensor mounts that tolerate under-hood temperatures exceeding 200°C without degradation.
Market Restraints
- Fluorobenzophenone monomer supply concentration:Key difluorobenzophenone precursors originate from limited European and Asian sources, exposing Brazilian compounders to freight cost volatility and currency mismatch risks.
- High-temperature processing equipment scarcity:PEEK's 343°C melting point demands specialized twin-screw extruders and corrosion-resistant tooling that few South American processors currently operate, constraining domestic compounding scale.
- Polyphenylene sulfide substitution in cost-sensitive sealing:PPS offers adequate chemical resistance for valve and pump applications at 40-60% lower material cost, limiting PEEK penetration in general industrial markets outside critical-load specifications.
Strategic Opportunities
- Argentine medical device manufacturing revival:ANMAT regulatory alignment initiatives with MERCOSUR standards are reopening Buenos Aires and Córdoba production corridors for export-oriented orthopedic implant fabrication using imported PEEK blanks.
- Carbon fiber-PEEK hybrid additive manufacturing:Emerging laser sintering capabilities in Campinas and São Paulo enable patient-specific cranial implant production with topology-optimized structures impossible through conventional machining.
- Brazilian PLI-style advanced materials incentives:Federal R&D tax credits under the Inovação Brasil framework subsidize domestic PEEK compounding investments, reducing import dependency for medical and aerospace grades.
Industry Challenges
- Polymer rheology expertise scarcity:South American universities produce limited graduates trained in high-performance thermoplastics processing, forcing compounders to recruit from European or North American talent pools at premium compensation.
- MERCOSUR regulatory divergence:Brazil's INMETRO and Argentina's ANMAT maintain non-harmonized testing protocols for electrical and medical applications, duplicating certification costs for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyether Ether Ketone (Peek) Market |
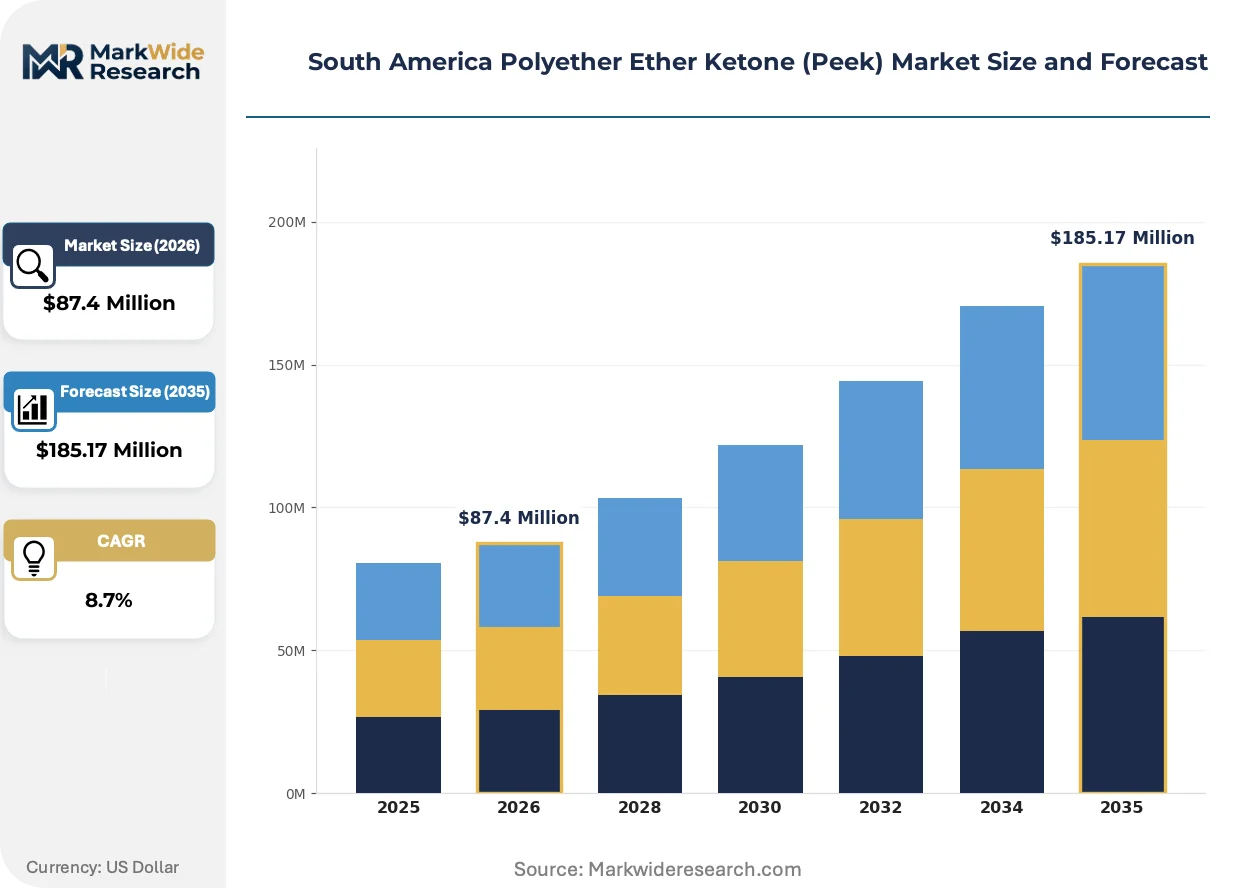
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Filled, Specialty, Composite Application: Aerospace, Automotive, Electronics, Medical End User: OEMs, Tier-1 Suppliers, Manufacturers, Research Institutions Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Victrex PLC, Solvay, Evonik Industries AG, Syensqo, Ensinger GmbH, Mitsubishi Chemical Advanced Materials, Celanese Corporation, SABIC, Arkema S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyether Ether Ketone (Peek) Market Trends and Innovations
Material science advances and regulatory harmonization pressures are restructuring how PEEK compounds are formulated, qualified, and procured across Brazilian and Argentine industrial corridors.
Reinforced PEEK formulations containing continuous carbon fiber are migrating from aerospace brackets into automotive structural battery enclosures. São Paulo-based EV manufacturers specify these composites for crash-resistant module housings that protect lithium-ion cells while shedding kilograms versus aluminum alternatives. This migration from metal-dominated designs is compressing traditional stamping supply chains and qualifying new polymer conversion specialists.
ANVISA's 2023 guidance on implantable device master files now requires real-time stability data rather than accelerated aging studies for PEEK spinal cage approvals. Medical device manufacturers in Osasco and Barueri industrial parks are responding by installing in-house environmental chambers to generate longitudinal datasets, extending product development cycles by 18-24 months but creating regulatory moats against unqualified competitors.
Hospital procurement consortia in Brazil's Southeast region now mandate vendor-managed inventory for orthopedic implant blanks, transferring working capital burdens from cash-constrained public health systems to PEEK suppliers. This arrangement concentrates purchasing power within three dominant hospital networks spanning São Paulo, Rio de Janeiro, and Belo Horizonte, squeezing margins for smaller compounders unable to finance extended payment terms or consignment stockholding.
South America Polyether Ether Ketone (Peek) Market Segmentation
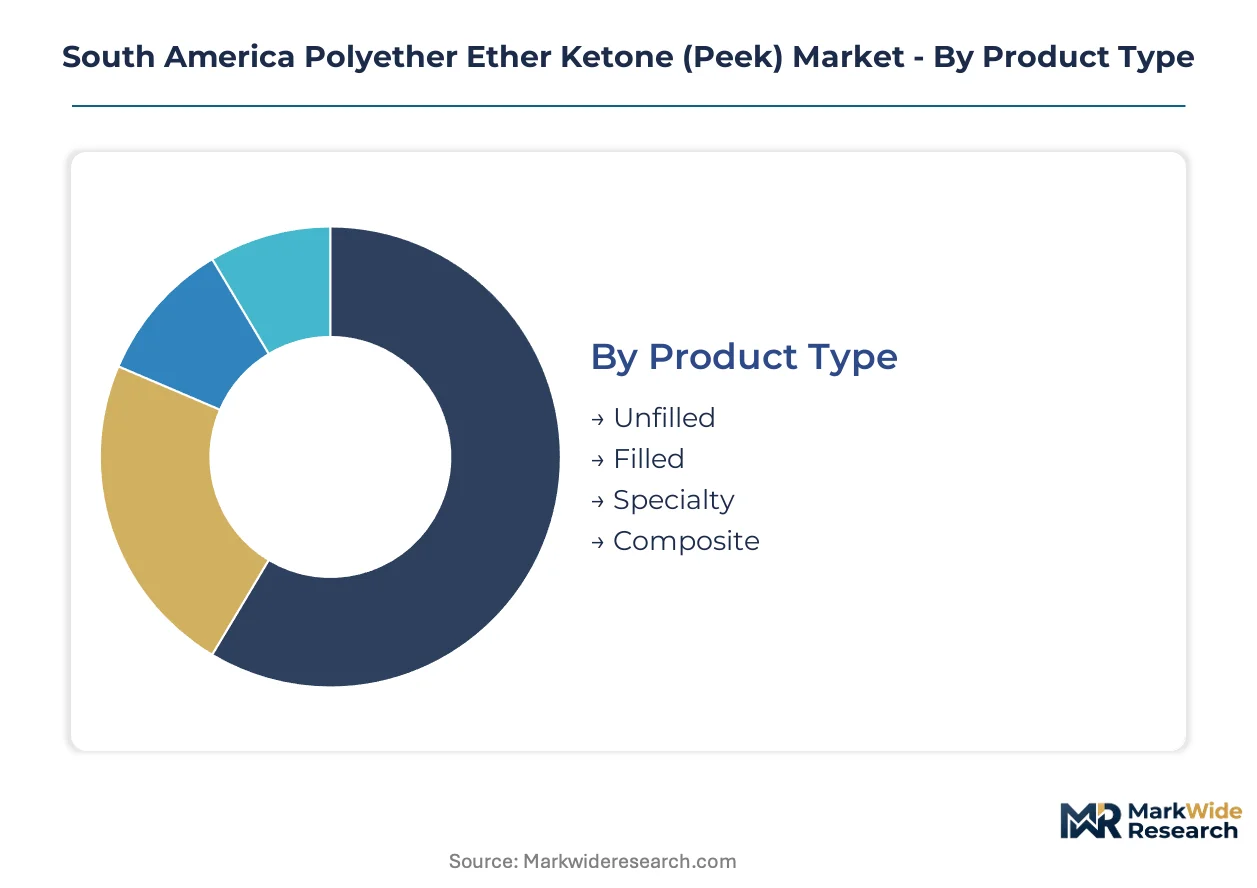
PEEK procurement patterns across South America diverge sharply by segment, with medical-grade specifications demanding intensive technical support while automotive volumes run through streamlined direct channels. Understanding these structural differences reveals where margin pools concentrate and which customer relationships require dedicated application engineering investment.
Product Type:
After-sales service intensity varies dramatically across PEEK product categories, with medical implant grades requiring ongoing regulatory file maintenance and sterilization validation support that unfilled industrial grades simply do not demand.
- Unfilled:Virgin resin without reinforcement offers the broadest machinability and lowest unit cost, serving São Paulo's general industrial valve and sealing manufacturers where specifications tolerate standard purity grades. Demand concentrates in Brazil's petrochemical maintenance sector, where processors value stock shape availability over compounded performance.
- Filled:Carbon fiber and glass-reinforced grades deliver stiffness-to-weight ratios critical for aerospace brackets and automotive under-hood components. Argentine and Brazilian aircraft manufacturers specify these compounds for engine nacelle applications where metal replacement drives fuel efficiency gains.
- Specialty:Medical-grade formulations with enhanced biocompatibility certifications command premium positioning for spinal implants and surgical instruments. ANVISA Resolution RDC 185/2001 compliance requires dedicated lot traceability and gamma sterilization validation that only specialized compounders provide.
- Composite:Continuous fiber-reinforced prepregs and hybrid formulations target emerging additive manufacturing applications in Campinas-based medical device prototyping. These materials enable patient-specific cranial implant production through laser sintering processes.
By volume, Unfilled leads. By growth pace, Filled is ahead.
Application:
Application selection dictates processing infrastructure requirements, with aerospace and medical segments demanding temperature-controlled supply chains that electronics and automotive procurement can relax.
- Aerospace:Carbon fiber-reinforced PEEK brackets and ducting replace aluminum in Brazilian and Argentine aircraft engine nacelles and interior structures. Fuel efficiency mandates from regional carriers accelerate qualification timelines for lightweight polymer alternatives.
- Automotive:Thermal management applications dominate São Paulo's automotive electronics corridor, where filled grades protect sensor mounts and connector housings from under-hood temperatures exceeding 200°C. EV battery enclosure specifications are emerging as a new demand vector.
- Electronics:Precision-machined insulators and semiconductor processing components require ultra-high purity grades with minimal metallic contamination. Brazilian electronics assemblers source these through authorized distributor networks with cleanroom handling capabilities.
- Medical:Spinal cages, orthopedic implants, and sterilizable surgical instruments represent the steepest expansion trajectory as Brazilian hospitals upgrade to gamma-compatible polymer systems. ANVISA's real-time stability data requirements extend development cycles but deepen supplier moats.
Medical commands the highest unit margins. Automotive delivers the largest absolute tonnage.
End User:
End user type determines contract structure, with OEMs demanding long-term supply agreements and research institutions requiring flexible minimum order quantities.
- OEMs:Brazilian medical device and aerospace original equipment manufacturers negotiate multi-year supply contracts with price-volume bands and dedicated inventory buffers. These relationships require compounders to finance consignment stock and extended payment terms.
- Tier-1 Suppliers:Automotive subsystem integrators in São Paulo's ABC manufacturing belt specify filled grades for under-hood component supply to final assemblers. Their procurement emphasizes just-in-time delivery and lot traceability rather than technical development partnership.
- Manufacturers:Small and mid-sized processors of stock shapes and machined components purchase unfilled grades through distributor channels with standard lead times and limited technical support.
- Research Institutions:Universities and hospital research centers in Campinas and Buenos Aires drive early-stage material qualification for novel implant designs and additive manufacturing processes.
OEMs anchor premium-grade demand. Research institutions pilot next-generation formulations.
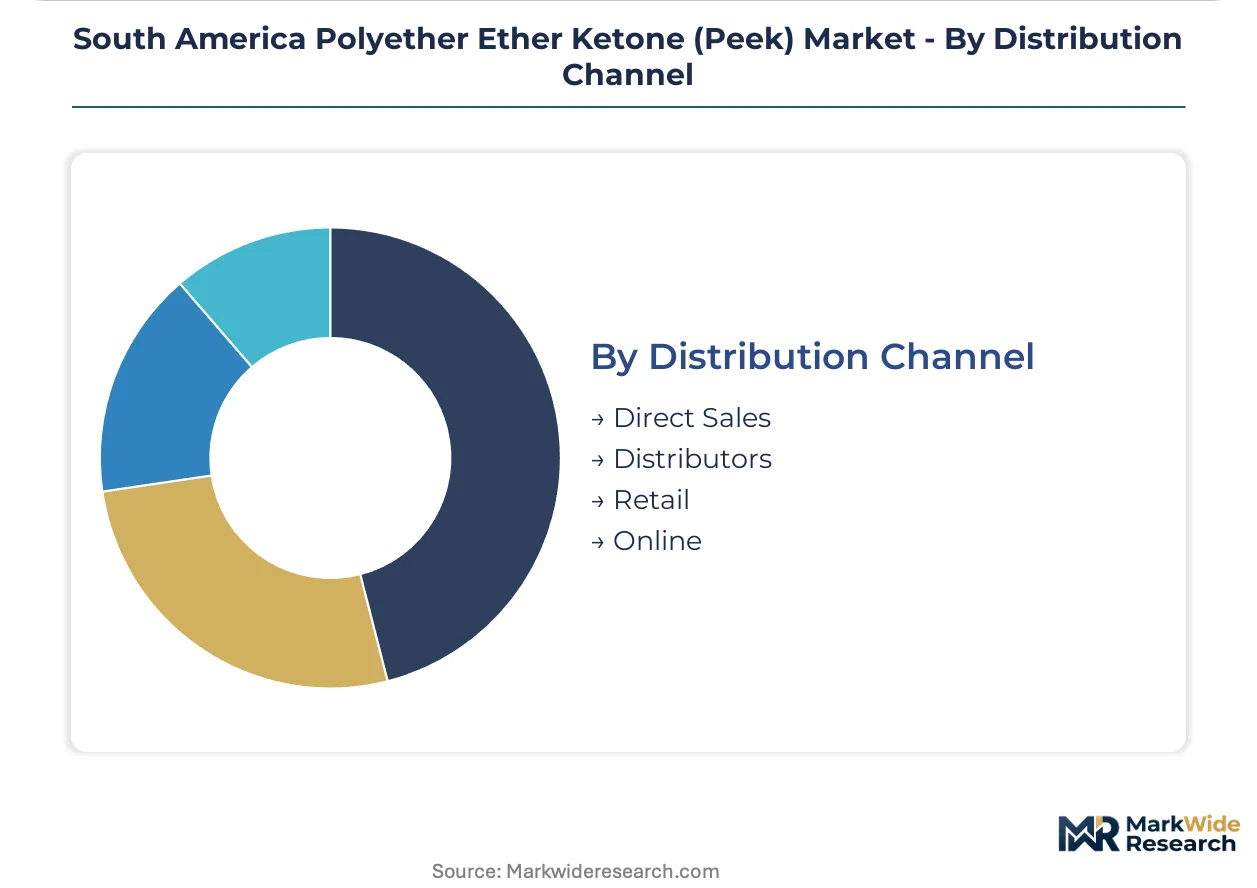
Distribution Channel:
Channel selection reflects order scale and technical complexity, with direct relationships reserved for qualified medical and aerospace accounts while standard industrial grades flow through intermediaries.
- Direct Sales:Medical-grade and aerospace compounders maintain dedicated technical sales engineers for Brazilian OEMs requiring application development support, regulatory file preparation, and sterilization validation assistance.
- Distributors:Authorized partners stock unfilled and standard filled grades for São Paulo's general industrial market, offering local availability and credit terms that resin producers prefer not to administer directly.
- Retail:Limited to small-quantity stock shape sales for maintenance repair operations and prototype shops lacking established supplier relationships.
- Online:Emerging channel for standard grades and technical documentation access, particularly among research institutions and smaller manufacturers seeking price transparency.
Direct sales capture the medical premium. Distributors handle the industrial volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PEEK resin flows into South America through a narrow import corridor dominated by European and Asian suppliers, with Brazilian ports handling the bulk of regional volume before redistribution to Argentine and Chilean processors.
Brazil
ANVISA's tightened biocompatibility standards under Resolution RDC 185/2001 are compressing qualification timelines for medical-grade PEEK, forcing suppliers to accelerate certification investments or cede implantable device contracts to pre-qualified competitors. The Inovação Brasil framework channels federal R&D tax credits toward domestic compounding capabilities, reducing import dependency for medical and aerospace grades. São Paulo's industrial corridor concentrates demand from automotive electronics clusters requiring thermal management grades for under-hood components.
Argentina
ANMAT regulatory alignment initiatives with MERCOSUR standards are reopening Buenos Aires and Córdoba production corridors for export-oriented orthopedic implant fabrication using imported PEEK blanks. Currency volatility continues to distort procurement economics, with Argentine processors favoring consignment inventory arrangements to mitigate working capital exposure. The Córdoba aerospace subcontracting cluster qualifies carbon fiber-reinforced grades for regional jet engine nacelle brackets.
Chile
Mining equipment maintenance operations in Antofagasta and Santiago generate steady demand for unfilled PEEK in valve seals and pump components exposed to acidic leaching environments. The national mining regulator's pressure equipment standards implicitly favor corrosion-resistant polymers in sulfuric acid handling systems. Santiago's emerging medical device assembly sector sources specialty grades through Brazilian distributors rather than direct import channels.
Colombia
Petrochemical maintenance clusters in Barrancabermeja and Cartagena specify unfilled grades for refinery sealing applications where chemical resistance outweighs load-bearing requirements. The national standards body has adopted modified ASTM protocols for thermoplastic qualification in pressure-containing equipment. Bogotá's orthopedic hospital networks remain dependent on imported implant blanks, with distribution routed through Miami-based intermediaries.
Peru
Minera Antamina and Cerro Verde operations drive niche demand for filled PEEK in hydrocyclone liners and flotation cell components subjected to abrasive slurry exposure. The Ministry of Energy and Mines has issued technical guidelines encouraging polymer substitution in corrosive process streams. Lima's limited polymer conversion infrastructure forces reliance on Brazilian compounders for machined stock shapes.
South America Polyether Ether Ketone (Peek) Market Competitive Landscape
Global resin specialists and regional distribution specialists split the market into distinct capability tiers. European-headquartered polymer producers dominate medical-grade supply through direct technical sales relationships, while authorized distributors handle standard industrial grades for São Paulo's general manufacturing base. Three archetypes define competitive positioning: vertically integrated resin producers with monomer backward integration, specialized compounders offering filled formulations, and distributor-led technical service providers. Capacity expansion and regulatory file preparation represent the dominant competitive moves, with suppliers racing to secure ANVISA master file approvals ahead of implant-grade demand acceleration.
Among European resin producers, Victrex PLC, Solvay, and Evonik Industries AG occupy positions exemplifying distinct strategic archetypes within the premium-grade segment. Victrex represents the dedicated high-performance polymer pure-play model, Solvay anchors the diversified chemicals conglomerate approach with backward integration into key monomer precursors, and Evonik exemplifies the specialty additives and compounds pathway targeting thermal management applications. These three entities collectively shape qualification standards and pricing benchmarks for medical and aerospace grades across Brazilian and Argentine industrial corridors.
| Leading Market Players |
|---|
| Victrex PLC |
| Solvay |
| Evonik Industries AG |
| Syensqo |
| Ensinger GmbH |
| Mitsubishi Chemical Advanced Materials |
| Celanese Corporation |
| SABIC |
| Arkema S.A. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on European difluorobenzophenone precursors determines both the premium spread between medical and industrial PEEK grades and the triangular supply chain shape funneling through Brazilian ports before redistribution across Mercosur markets.
Pricing Analysis
ANVISA Resolution RDC 185/2001 dictates the pricing tier structure by mandating separate certification tracks for implantable versus non-implantable grades. Three-tier pricing structure across premium, standard, and economy levels separates gamma-validated medical compounds from automotive-filled grades and unfilled industrial stock shapes. Cost compression in the medical tier is intensifying because hospital procurement consortia now mandate vendor-managed inventory with extended payment terms. Tier-1 automotive suppliers exhibit the highest price sensitivity due to polyphenylene sulfide substitution threats, while orthopedic OEMs accept premium positioning for regulatory file security.
Supply Chain Analysis
Tariff exposure between European monomer producers and Brazilian compounders dominates supply chain risk calculus, with freight cost volatility amplifying working capital burdens for São Paulo processors. Raw material flows draw from Germany, the United Kingdom, and Japan for difluorobenzophenone and hydroquinone precursors. Single-source vulnerability concentrates in high-purity resin grades where Victrex and Solvay maintain captive production. Distribution runs through authorized technical distributors for standard grades while medical and aerospace compounds move via direct sales with dedicated inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America PEEK market is recovering from a cyclical trough driven by post-pandemic hospital capital expenditure normalization and aerospace production rate restarts.
For Market Incumbents: Insulate margin position by accelerating ANVISA master file preparation ahead of competitor qualification timelines, and anchor backward integration into monomer precursors to neutralize currency mismatch risks on European imports. Threats from polyphenylene sulfide substitution in sealing applications demand reinforced technical service capabilities in São Paulo's petrochemical maintenance corridor. For New Entrants and Emerging Players: Establish a beachhead in Argentine orthopedic implant fabrication by leveraging ANMAT-MERCOSUR regulatory alignment to serve export-oriented Córdoba and Buenos Aires production corridors. The most penetrable white space sits in carbon fiber-PEEK hybrid additive manufacturing for patient-specific cranial implants, where Campinas-based prototyping labs seek qualified material suppliers with laser sintering validation support. For Investors and Strategic Acquirers: ANVISA's 2023 real-time stability data requirement reshapes the acquisition landscape by extending regulatory moats for compounders with installed environmental chamber infrastructure. Long-term viability over the next decade hinges on exposure to medical-grade demand pools rather than commoditized industrial sealing. The signal to watch is Brazilian PLI-style incentive uptake rates for domestic compounding capacity, which would compress import dependency and reposition margin capture toward local processors.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Master File Preparation | Regulatory pre-qualification secures implant-grade supply contracts before competitor certification completion. |
| Backward Integration into Monomers | In-house production of difluorobenzophenone neutralizes European freight cost volatility for Brazilian compounders. |
| Carbon Fiber-PEEK Hybrid Development | Laser sintering compatibility opens patient-specific cranial implant production in Campinas medical prototyping clusters. |
| Vendor-Managed Inventory Programs | Extended payment terms and consignment stockholding align with São Paulo hospital procurement consortium requirements. |
| Argentine Production Corridor Entry | ANMAT regulatory alignment enables export-oriented orthopedic fabrication from Córdoba and Buenos Aires facilities. |
Research Methodology
Desk research of customs trade databases, ANVISA regulatory filings, and SEC 10-K disclosures preceded structured interviews with polymer plant managers, medical device procurement leads at São Paulo hospital networks, aerospace subsystem engineers in Córdoba, and authorized distributor technical sales staff. Primary intelligence on processing economics and qualification timelines was cross-validated against secondary trade flow data and bottom-up volume estimates were triangulated with top-down market sizing from import statistics.
Assumptions around ANVISA regulatory enforcement intensity and aerospace production rate recovery were held fixed across baseline scenarios while currency volatility bands and polyphenylene sulfide substitution elasticity were stress-tested in sensitivity runs. The analytical framework modeled volume and value across product type, application, end user, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical import trajectories and elasticity-adjusted demand projections for medical implant and aerospace lightweighting applications.
Stress conditions across Brazilian real exchange rate bands, European monomer supply disruption scenarios, and ANMAT regulatory divergence timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory harmonization progress and hospital capital expenditure recovery that could revise trajectories if MERCOSUR standards diverge or public health budgets contract. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Montan Wax Market
Specialty Materials
United States Microspheres Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Solar Control Films Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Global Supplementary Cementitious Materials Market