
 Europe Microdisplay Market | 2026-2036
Europe Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microdisplay Market Intelligence
Modular display engine bundling is recalibrating how OEMs source microdisplay subsystems across Europe. HOLOEYE Photonics AG leverages its Berlin-based LCoS foundry to anchor high-resolution spatial light modulator supply for industrial and medical imaging. Sony Group Corporation dominates image sensor-to-display integration for augmented reality headsets. Seiko Epson Corporation sustains its position in projection microdisplay modules through tight control over HTPS LCD manufacturing scale.
A microdisplay is a compact screen, typically under two inches diagonal, engineered with pixel densities exceeding two thousand pixels per inch for near-eye or projection viewing applications. These devices employ silicon backplane substrates, organic electroluminescent layers, or liquid crystal-on-silicon architectures to project imagery through magnifying optics in head-mounted devices, vehicle windshields, and precision instruments. OLED product types command premium positioning in wearable devices due to self-emissive contrast ratios and millisecond response times that eliminate motion artifacts during head tracking. LCoS technology leads projection displays and automotive HUDs where luminous efficiency and thermal stability outweigh form factor constraints. Thin film manufacturing routes are gaining traction as foundries seek to reduce deposition complexity for microLED migration paths.
EMA medical device regulations and CE marking requirements under the EU MDR govern microdisplay integration in surgical visualization and diagnostic imaging equipment across European member states. REACH chemical restrictions and the EU Green Deal framework constrain rare earth procurement and fluorinated compound usage in display backplane etching processes, pushing manufacturers toward aqueous processing alternatives. Stakeholders must monitor how the EU AI Act classification rules reshape demand for transparent microdisplays in human-machine interface applications where algorithmic decision support requires visual audit trails.
Market Dynamics
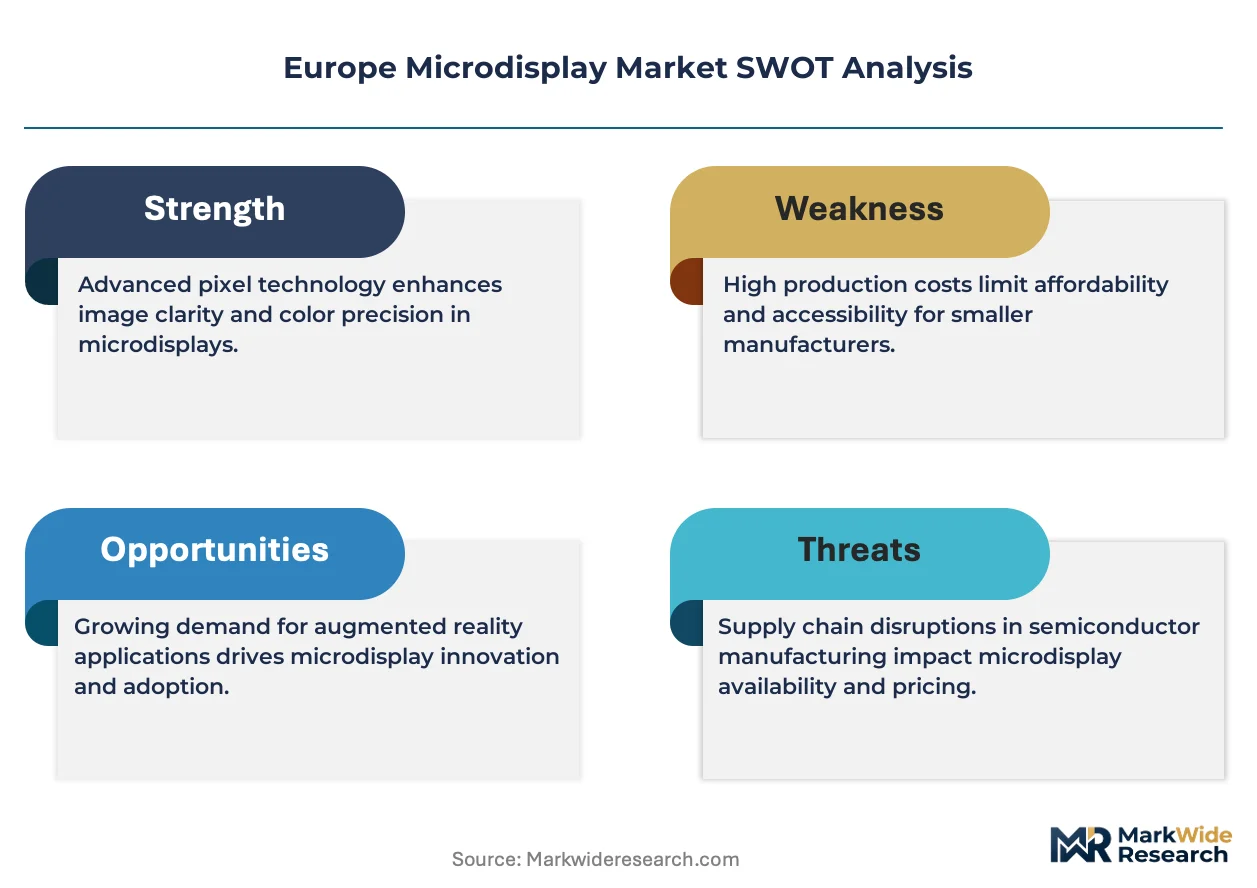
OLED microdisplay architectures are displacing legacy LCD configurations across European near-eye applications, compressing supply chain margins for incumbent foundries while creating entry points for specialized semiconductor backplane providers.
Growth Catalysts
- EU Green Deal compliance:REACH chemical restrictions on fluorinated compounds are accelerating aqueous processing adoption in German and French display backplane fabrication.
- Automotive HUD demand:German OEM supply chains are expanding augmented reality windshield projections, requiring high-brightness microdisplay engines with thermal stability specifications.
- Defense procurement:Military head-mounted display programs in France and Germany are generating multi-year contracts for ruggedized OLED and LCoS modules.
Market Restraints
- Rare earth supply concentration:Europium and terbium procurement dependencies on external suppliers create input cost volatility for phosphor-converted microLED development.
- EMA MDR certification timelines:Surgical visualization device approvals now require extended clinical validation periods, delaying product launches by 18-24 months.
- Silicon backplane fabrication:Foundry capacity constraints at 300mm CMOS facilities limit wafer starts for high-resolution LCoS panels.
Strategic Opportunities
- EU AI Act transparency mandates:Human-machine interface applications requiring visual audit trails for algorithmic decision support are creating demand for transparent microdisplay overlays.
- Polish industrial imaging cluster:Underpenetrated machine vision markets in Central Europe offer expansion paths for spatial light modulator suppliers.
- MicroLED-on-silicon convergence:Hybrid integration of gallium nitride emitters with CMOS backplanes is opening performance tiers beyond current OLED limits.
Industry Challenges
- Compound semiconductor talent scarcity:Epitaxial growth specialists for microLED fabrication remain concentrated at a handful of research institutions.
- Legacy system integration:Automotive HUD suppliers face firmware compatibility burdens when retrofitting new microdisplay engines into existing electronic control unit architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microdisplay Market |
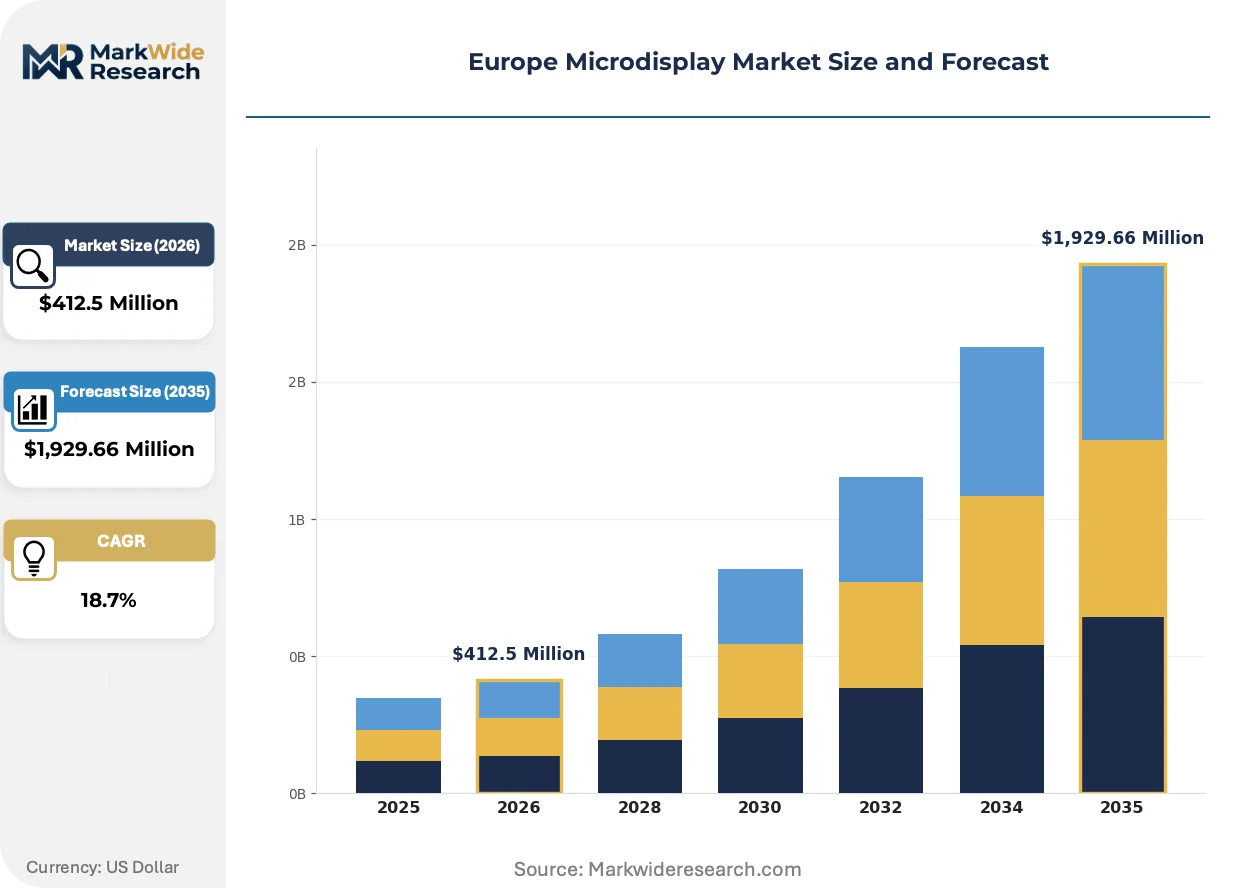
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, DLP, MicroLED Application: Wearable Devices, HUDs, Projection Displays, Digital Signage Technology: LCoS, Active Matrix, Passive Matrix, Thin Film End User: Consumer Electronics, Automotive, Aerospace, Healthcare |
| Companies Covered | HOLOEYE Photonics AG, Seiko Epson Corporation, Sony Group Corporation, Kopin Corporation, Himax Technologies, Inc., eMagin Corporation, SeeYA Technology, OLEDWorks, MicroOLED Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microdisplay Market Strategic Shifts & Innovations
Display engine miniaturization is compressing optical stack dimensions while pixel density requirements escalate. Foundries are reconfiguring deposition equipment for heterogeneous integration.
MicroLED arrays with sub-10-micron pitch are rewriting performance benchmarks for augmented reality headsets. Defense contractors in France are qualifying these panels for pilot helmet-mounted cueing systems. The technology is compressing the luminance gap between emissive and reflective microdisplay architectures.
REACH F-Gas Regulation amendments are restricting sulfur hexafluoride usage in plasma etching processes for silicon backplane manufacturing. German foundries are retrofitting etch chambers with fluorocarbon alternatives. Medical device manufacturers face reformulation costs for CE-marked surgical visualization equipment.
Automotive OEMs are consolidating microdisplay procurement through tier-one mirror suppliers rather than direct component sourcing. This disintermediation compresses supplier margins while extending payment terms. German HUD supply chains exhibit the most pronounced concentration of buying power.
Europe Microdisplay Market Segmentation
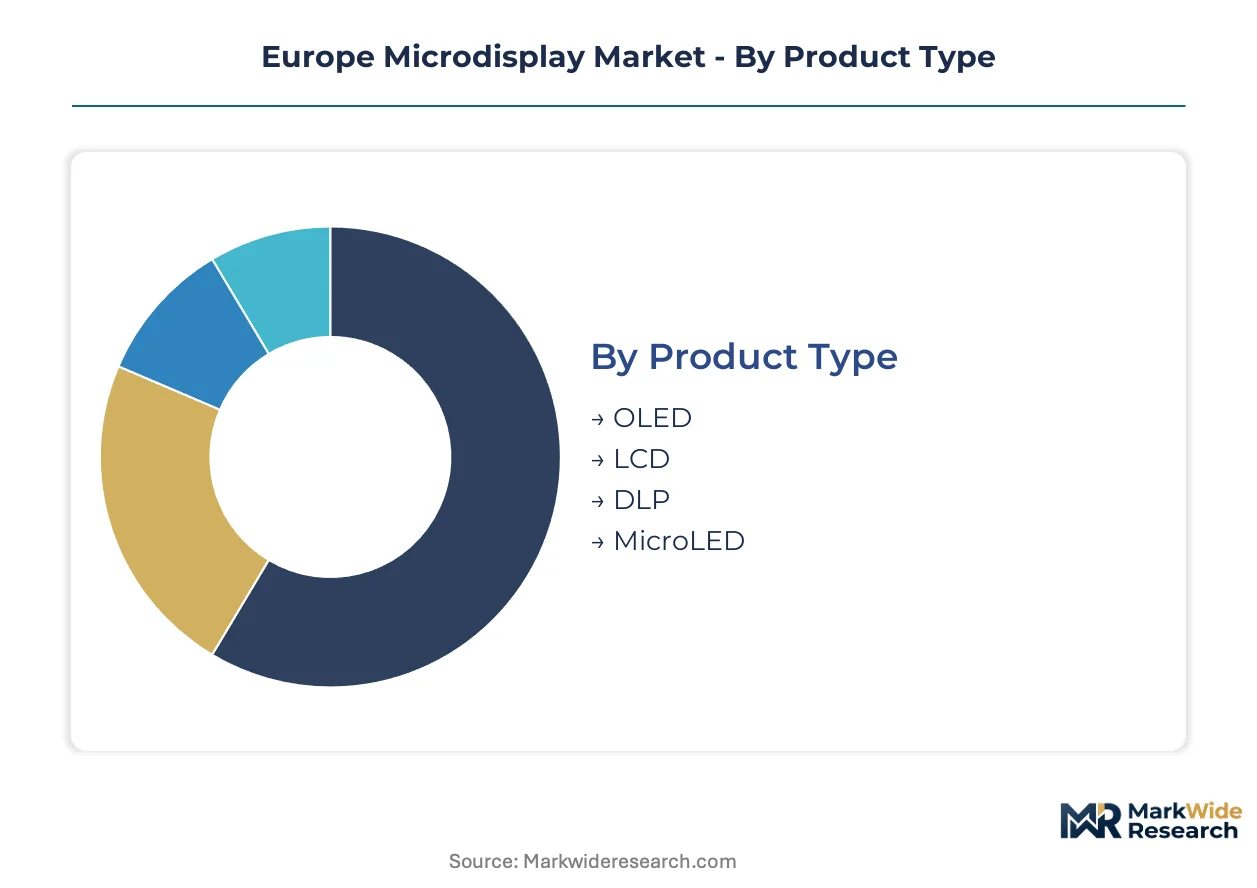
Microdisplay procurement patterns diverge sharply across European end-use sectors, with defense contractors prioritizing ruggedized emissive architectures while automotive OEMs optimize for thermal stability in augmented reality windshields. Understanding these segment boundaries clarifies how technology roadmaps and regulatory compliance reshape supplier positioning.
Product Type:
Buyers differentiate primarily by luminance requirements and form factor constraints, with near-eye applications demanding self-emissive contrast ratios that reflective architectures cannot deliver.
- OLED:Organic electroluminescent layers deposited on silicon backplanes deliver sub-millisecond response times and infinite contrast ratios. German defense electronics clusters specify these for pilot helmet-mounted cueing systems where motion artifact elimination is mandatory.
- LCD:Liquid crystal shutters modulate backlight intensity through polarizing filters, requiring higher drive voltages than emissive alternatives. French industrial imaging customers retain LCD procurement for cost-sensitive spatial light modulator applications where volume scale outweighs pixel response specifications.
- DLP:Digital micromirror devices from Texas Instruments route light through electrostatically controlled tilt mirrors. Projection display integrators in Poland specify DLP engines for machine vision systems requiring programmable illumination patterns.
- MicroLED:Gallium nitride emitters hybridized with CMOS backplanes achieve brightness levels beyond OLED thermal limits. Development programs at Fraunhofer institutes are qualifying microLED arrays for automotive HUD deployment.
LCD leads volumes today; MicroLED is gaining share fastest.
Application:
Volume concentration tracks end-user procurement centralization, with German automotive tier-ones consolidating purchasing power while defense agencies fragment demand across national programs.
- Wearable Devices:Smart glasses and augmented reality headsets require sub-inch diagonal panels with pixel densities exceeding three thousand per inch. Sony Group Corporation integration pipelines dominate this segment through direct OEM relationships.
- HUDs:Head-up display systems project vehicle telemetry onto windshields without driver gaze diversion. German OEM supply chains specify high-brightness LCoS engines capable of operating across ambient illumination extremes.
- Projection Displays:Pico-projectors and embedded cinema systems demand luminous efficiency over pixel density. Seiko Epson Corporation HTPS manufacturing scale anchors procurement for this application tier.
- Digital Signage:Compact projection modules enable retail and transit advertising in space-constrained environments. Italian display integrators are expanding microLED-based signage pilots for luxury brand installations.
HUD applications command the steepest expansion trajectory; projection displays retain the largest installed base.
Technology:
Manufacturing process maturity determines which foundries can supply each architecture, with 300mm CMOS capacity constraints limiting high-resolution LCoS wafer starts.
- LCoS:Liquid crystal-on-silicon sandwiches nematic fluid between reflective metal electrodes and glass cover plates. HOLOEYE Photonics AG Berlin foundry anchors European supply for medical imaging and industrial holography applications.
- Active Matrix:Thin-film transistors at each pixel address enable high refresh rates and complex compensation circuits. OLED microdisplay backplanes universally employ active matrix architectures for uniform brightness distribution.
- Passive Matrix:Row-column voltage multiplexing reduces silicon complexity at the cost of duty cycle limitations. Legacy low-resolution applications in basic instrumentation retain this technology for cost minimization.
- Thin Film:Solution-processed organic semiconductors or printed quantum dots enable substrate-flexible deposition. Research programs at IMEC and CEA-Leti are advancing thin film routes for microLED transfer processes.
Active matrix dominates revenue concentration; thin film processing shows the most rapid technology maturation.
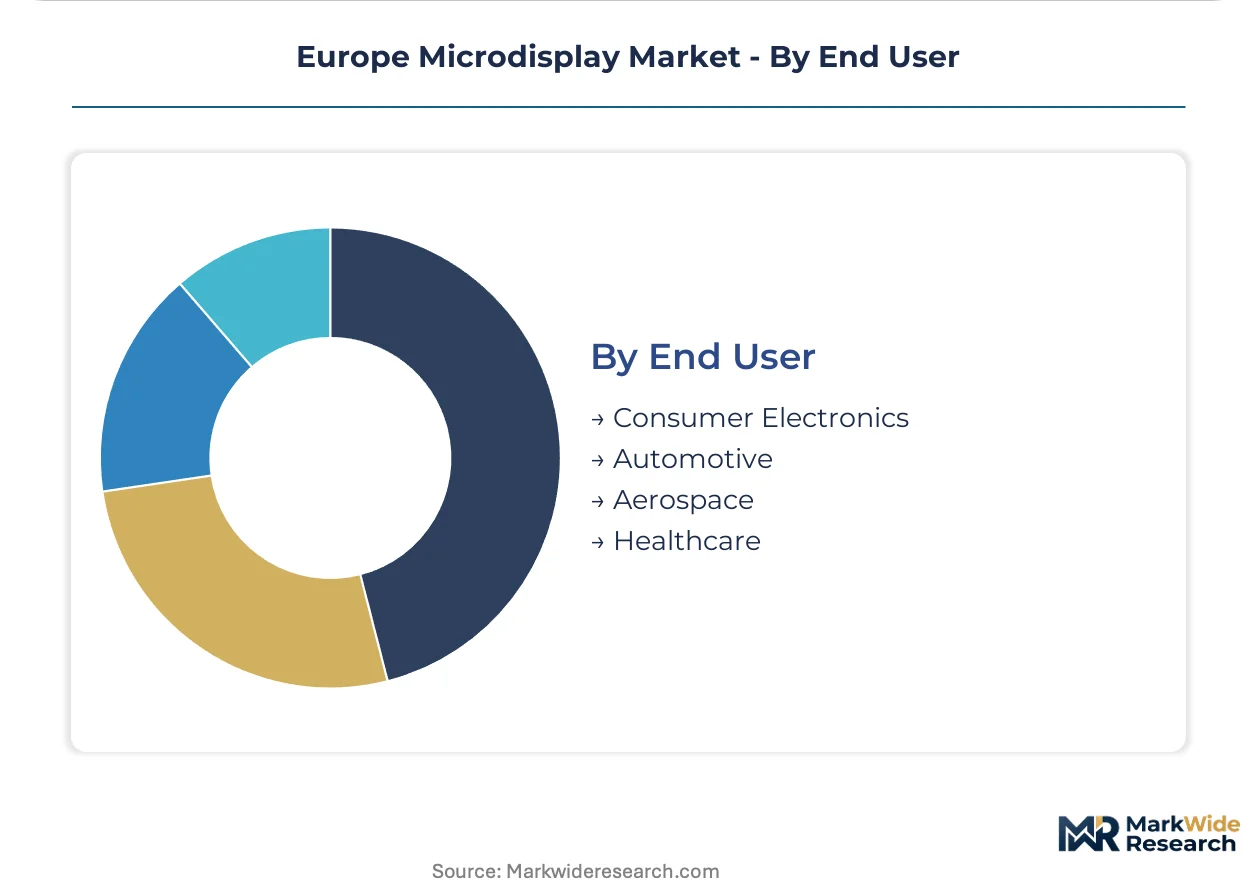
End User:
Regulatory certification timelines fragment demand by vertical, with EMA MDR requirements imposing eighteen-to-twenty-four month delays on medical device launches absent from consumer electronics procurement cycles.
- Consumer Electronics:Gaming headsets and smart glasses drive volume demand for cost-optimized OLED panels. CE marking requirements under EU MDR do not apply to non-medical wearable devices, compressing product development cycles.
- Automotive:HUD and mirror replacement displays must satisfy KBA type approval and UNECE regulation compliance. German OEMs are consolidating procurement through tier-one mirror suppliers, extending payment terms while compressing component margins.
- Aerospace:Military head-mounted display programs in France and Germany generate multi-year contracts for ruggedized modules. ANSM quality system requirements overlay EU defense procurement directives for French suppliers.
- Healthcare:Surgical visualization and diagnostic imaging equipment falls under EMA MDR jurisdiction with extended clinical validation mandates. Swissmedic parallel certification enables Swiss-headquartered device manufacturers to access EU markets through mutual recognition agreements.
Automotive captures the largest revenue pool; healthcare exhibits the most pronounced regulatory barrier effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microdisplay manufacturing in Europe traces its commercial roots to German precision optics clusters established during the 1990s for head-mounted simulation systems. Foundry infrastructure subsequently expanded across the continent as defense procurement agencies standardized on near-eye displays for pilot training programs.
Germany
KBA type approval requirements for automotive HUD systems are accelerating validation timelines for augmented reality windshield modules. The EU Green Deal framework constrains fluorinated compound usage in Berlin and Dresden foundries, pushing aqueous processing adoption. Bavarian automotive tier-ones are consolidating microdisplay procurement through mirror suppliers, compressing component margins while extending payment terms.
France
ANSM quality system requirements overlay EU defense procurement directives for military head-mounted display programs generating multi-year contracts. The EU AI Act classification rules are reshaping demand for transparent microdisplays in human-machine interface applications requiring visual audit trails. Paris and Grenoble defense electronics clusters are qualifying microLED arrays for pilot helmet-mounted cueing systems.
United Kingdom
CE marking under EU MDR governs surgical visualization equipment despite post-Brexit regulatory divergence, with extended clinical validation periods delaying product launches. London and Cambridge AR headset developers are sourcing OLED panels through Sony integration pipelines. Scottish industrial imaging specialists retain LCD procurement for cost-sensitive spatial light modulator applications.
Poland
Underpenetrated machine vision markets in Central Europe are offering expansion paths for spatial light modulator suppliers seeking volume diversification. REACH chemical restrictions apply equally to Polish display backplane fabrication, though enforcement timelines lag Western European adoption curves. Wrocław and Kraków industrial automation clusters are specifying DLP engines for programmable illumination pattern systems.
Switzerland
Swissmedic parallel certification enables Swiss-headquartered device manufacturers to access EU markets through mutual recognition agreements, circumventing EMA MDR bottlenecks. Geneva and Zurich surgical visualization developers are leveraging this pathway for accelerated CE-marked product launches. The country's precision manufacturing heritage anchors medical imaging equipment supply chains serving German and French hospital networks.
Europe Microdisplay Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and certification burden dimensions. The vendor base stratifies between silicon backplane foundries controlling high-resolution LCoS wafer starts and assembly houses bundling display engines for tier-one automotive suppliers. Three archetypes dominate: integrated semiconductor manufacturers with captive CMOS capacity, specialized spatial light modulator foundries serving medical and industrial imaging, and projection module assemblers leveraging HTPS manufacturing scale. Competitive moves concentrate on strategic partnerships with automotive HUD integrators and portfolio diversification into microLED-on-silicon development programs.
Within the specialized foundry tier, HOLOEYE Photonics AG represents European LCoS manufacturing capabilities anchored in Berlin. Sony Group Corporation exemplifies integrated semiconductor positioning through image sensor-to-display integration pipelines. Seiko Epson Corporation occupies a position reflecting projection microdisplay module assembly at manufacturing scale. These three entities collectively illustrate how geographic concentration of CMOS foundry capacity, precision optics heritage, and vertical integration into backplane fabrication shape competitive positioning across the European procurement landscape.
| Leading Market Players |
|---|
| HOLOEYE Photonics AG |
| Seiko Epson Corporation |
| Sony Group Corporation |
| Kopin Corporation |
| Himax Technologies, Inc. |
| eMagin Corporation |
| SeeYA Technology |
| OLEDWorks |
| MicroOLED Technologies |
| Others |
Cost & Logistics Intelligence
Silicon backplane wafer costs cascade through three distinct pricing tiers as they move from 300mm CMOS foundries in Germany and France toward automotive HUD integrators and defense electronics clusters. Rare earth phosphor materials for microLED development concentrate pricing volatility in the premium tier, while aqueous processing investments driven by REACH F-Gas Regulation compliance reshape cost structures across mid-market LCoS supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with CE marking under EU MDR and KBA type approval separating certified medical and automotive tiers from consumer electronics volumes. Price differentiation hinges on certification grade and volume scale, with German automotive tier-ones extracting steep discounts through consolidated mirror supplier channels. Cost compression in the standard tier is intensifying because foundry capacity constraints at 300mm CMOS facilities limit wafer starts for high-resolution LCoS panels. Consumer electronics buyers exhibit highest price sensitivity, while French defense procurement agencies accept premium positioning for ruggedized OLED modules with ANSM quality system overlays.
Supply Chain Analysis
Returns and refurbishment flows for surgical visualization equipment under EMA MDR jurisdiction create reverse-logistics complexity that Swiss device manufacturers circumvent through Swissmedic parallel certification pathways. Supply concentrates in Germany, France, and Taiwan, with Berlin and Dresden foundries anchoring European LCoS capacity while Taiwanese CMOS facilities feed high-resolution backplane demand. Raw material dependencies center on europium and terbium for phosphor-converted microLED development, alongside fluorinated compounds now restricted under EU Green Deal frameworks. Single-source vulnerability at 300mm CMOS foundries presents structural supply chain risk. Distribution runs through tier-one automotive mirror suppliers and specialized medical device integrators rather than direct component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Microdisplay Market represents a late-cycle quality story as defense procurement agencies and German automotive OEMs shift demand toward premium-specification OLED and microLED architectures with enhanced thermal stability and motion artifact elimination.
For Market Incumbents: Deploy backward integration into silicon backplane fabrication to secure captive 300mm CMOS capacity as foundry constraints intensify. Incumbent LCoS specialists must defend against microLED substitution by accelerating aqueous processing certification under REACH amendments, locking in regulatory compliance ahead of competitor retrofit timelines.
For New Entrants and Emerging Players: Capture underpenetrated machine vision demand in Polish industrial automation clusters where DLP engine specifications dominate and incumbent presence remains thin. New entrants should prioritize transparent microdisplay development for EU AI Act human-machine interface applications, leveraging visual audit trail mandates as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where compound semiconductor talent scarcity constrains microLED epitaxial growth capacity at European research institutions. Long-term viability favors acquisition targets with heterogeneous integration capabilities bridging gallium nitride emitters with CMOS backplanes. Investors should monitor Fraunhofer qualification timelines for automotive microLED deployment as an inflection indicator for technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| MicroLED-on-Silicon Convergence | Fraunhofer institutes are qualifying hybrid integration for automotive HUD deployment beyond OLED thermal limits. |
| Aqueous Processing Retrofit | German foundries are replacing sulfur hexafluoride etch chambers to satisfy REACH F-Gas Regulation amendments. |
| Defense Procurement Consolidation | French ANSM quality system requirements overlay EU directives for multi-year ruggedized module contracts. |
| Tier-One Mirror Supplier Channel | Bavarian automotive OEMs are compressing component margins while extending payment terms through disintermediation. |
| Swissmedic Parallel Certification | Swiss-headquartered surgical visualization developers access EU markets faster than EMA MDR timelines permit. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with display foundry engineers, automotive tier-one procurement managers, defense electronics program officers, and medical device regulatory affairs specialists with secondary validation against SEC filings, EMA MDR submission databases, and KBA type approval records. Bottom-up demand modeling across German automotive HUD supply chains and French defense electronics clusters was triangulated with top-down market sizing from customs trade data and foundry capacity disclosures.
Segment-weighting approaches distributed value and volume across product type, application, technology, and end-user dimensions, with additional granularity for regulatory certification tier and geographic procurement cluster. CAGRs were derived from fitted growth curves across the projection horizon, incorporating silicon backplane fabrication capacity constraints, REACH chemical restriction phase-in schedules, and EU AI Act implementation timelines as industry-specific forecast inputs.
Regulatory enforcement delays, foundry capacity expansion decisions, and microLED yield improvement trajectories are the dominant revision risks that could reshape volume and value outputs. Forecasts reflect documented assumptions about procurement consolidation patterns and technology substitution elasticities. Practitioners should monitor EMA MDR certification timeline extensions and Fraunhofer microLED qualification milestones for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global LED Digital Signage Market
Display Technologies
Microdisplay Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Privacy Screens Market
Display Technologies
Global Industrial Display System Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
3D Display Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Head Up Display Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Electrochromic Window Market
Display Technologies
Volumetric Display Market
Display Technologies
Wireless Display Market