
 Electrochromic Window Market | 2026-2036
Electrochromic Window Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochromic Window Market Analysis
Market Context with Strategic Players
Specialized thin-film coating engineers is reorganizing how electrochromic glass manufacturers scale fabrication lines across North America and Europe. SageGlass leverages captive ion-conductive layer expertise to dominate premium commercial facade contracts in the United States. View, Inc. sustains vertical integration from sputtering equipment to installed systems, anchoring its position in intelligent building retrofits. Gentex Corporation specializes in automotive rearview mirror electrochromics and extends that competency into aerospace cabin dimming applications.
Technical Definition and Structural Segments
Electrochromic windows are multilayer glass assemblies incorporating tungsten oxide or nickel oxide films between transparent conductor layers, reversibly modulating visible light transmission and solar heat gain coefficients through lithium-ion intercalation driven by low-voltage electrical signals. This technology serves commercial and residential buildings seeking dynamic daylight harvesting and HVAC load reduction without mechanical shading. Active Windows leads product type adoption in high-rise retrofits where manual control interfaces add tenant value, while Switchable Glazing captures the fastest growth in healthcare facilities requiring instant privacy transitions. Photovoltaic-integrated electrochromic systems occupy emerging margin pools as building-integrated energy generation converges with envelope intelligence.
Regulatory Frame and Forward Outlook
The U.S. Department of Energy's Building Technologies Office and California Title 24 energy standards shape demand by mandating dynamic envelope performance in new commercial construction above four stories. The European Union's Energy Performance of Buildings Directive and REACH chemical compliance frameworks restrict certain electroactive materials while accelerating certified low-carbon glazing procurement. Stakeholders must monitor evolving F-Gas Regulation thresholds in Europe and emerging state-level stretch codes in Massachusetts and Washington that could bifurcate product certification requirements across jurisdictions.
Market Dynamics
California Title 24 and New York Local Law 97 are forcing commercial developers to specify dynamic glazing systems that modulate solar heat gain without mechanical shading, compressing payback periods below five years in Class A office retrofits.
Growth Catalysts
- Net-zero building mandates:California's Title 24 energy code requires dynamic envelope performance in new commercial construction above four stories, pulling electrochromic specifications into standard design practice.
- Healthcare privacy requirements:Switchable glazing systems enable instant visual privacy transitions in patient rooms and surgical suites, replacing manual blinds that harbor pathogens.
- Tungsten oxide film advances:Magnetron sputtering process improvements reduce lithium-ion intercalation layer thickness while maintaining optical density range.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor layer fabrication depends on indium refining capacity concentrated in Chinese smelting operations, exposing manufacturers to export quota volatility.
- REACH chemical compliance:ECHA restrictions on certain electroactive materials force reformulation of ion-conductive layers, extending product certification timelines.
- Electrochromic film curing duration:Vacuum deposition and thermal annealing cycles require 72-hour batch processing, constraining throughput scaling at fabrication facilities.
Strategic Opportunities
- Photovoltaic-integrated systems:Building-integrated energy generation converges with envelope intelligence, creating margin pools in net-positive energy building contracts.
- Massachusetts stretch codes:Emerging state-level mandates beyond base IECC requirements could bifurcate certification standards and create first-mover advantages for pre-certified suppliers.
- Aerospace cabin dimming:Automotive-derived electrochromic competencies transfer to commercial aircraft passenger windows, opening replacement cycles in fleet retrofit programs.
Industry Challenges
- Thin-film coating technician scarcity:Specialized vacuum deposition expertise concentrates in legacy semiconductor fabrication regions, forcing manufacturers to compete for talent with battery and display sectors.
- Multi-jurisdictional certification timelines:Separate UL, CE marking, and state-level energy code approvals extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochromic Window Market |
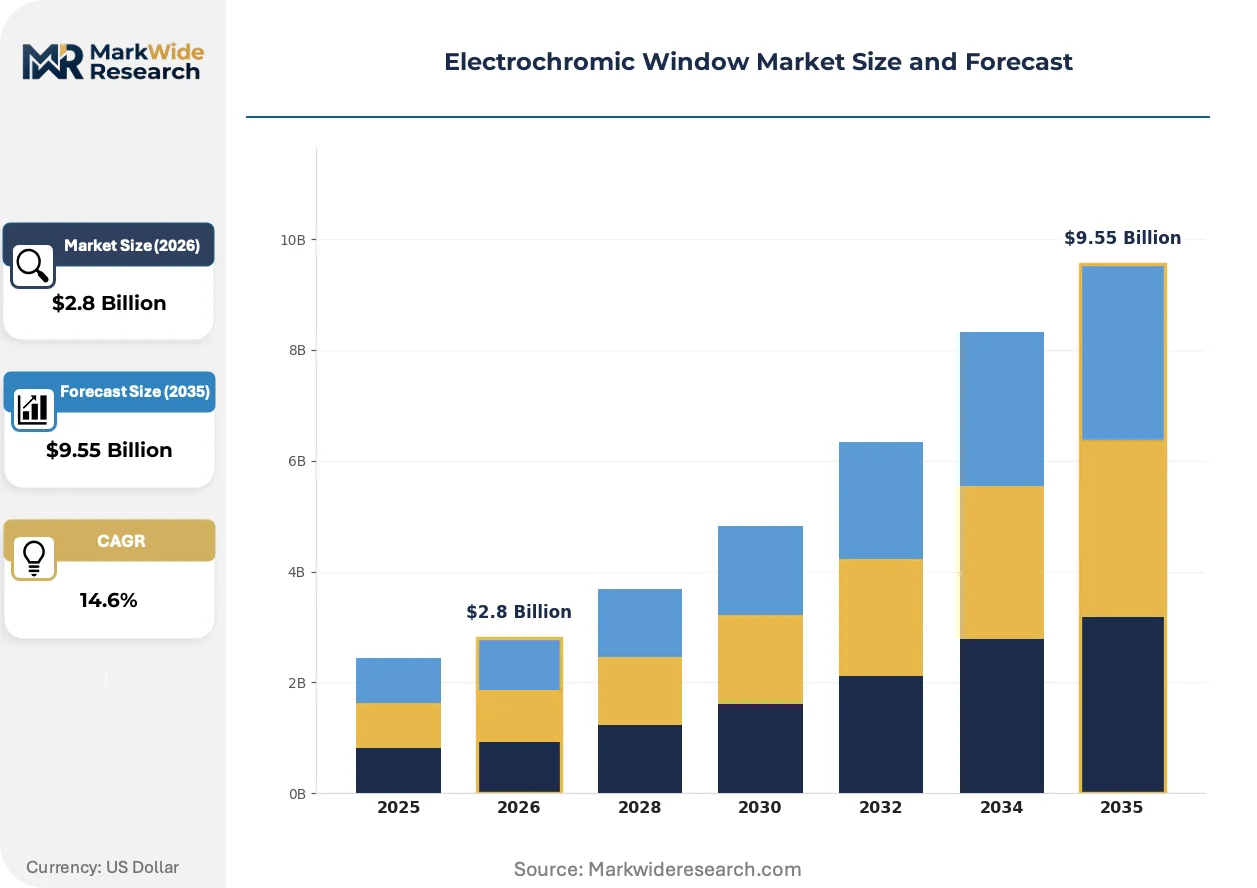
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Windows, Active Windows, Switchable Glazing, Tintable Glass Technology: Electrochemical, Electromechanical, Thermochromic, Photovoltaic Application: Residential Buildings, Commercial Spaces, Automotive, Aerospace End User: Architects, Contractors, Manufacturers, Facility Managers |
| Companies Covered | Saint-Gobain S.A., Chromogenics AB, SageGlass, Miru Smart Technologies, Guardian Industries, View, Inc., AGC Inc., Research Frontiers Inc., Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochromic Window Market Emerging Trajectories
Electrochromic window technology is compressing toward solid-state architectures and integrated power systems that eliminate external wiring, while regulatory pressure accelerates performance certification standardization across North American and European jurisdictions.
Solid-state electrochromic devices are miniaturizing control electronics into the glazing laminate itself, embedding photovoltaic micro-cells that harvest ambient light to power lithium-ion intercalation without grid connection. Healthcare facility designers specify these self-powered units for isolation room retrofits where electrical infrastructure modification costs exceed material premiums. The elimination of external power routing is miniaturizing installation labor requirements and enabling deployment in historic building envelopes where conduit runs face preservation restrictions.
California Title 24 energy standards now mandate dynamic solar heat gain coefficient modulation in new commercial construction above four stories, treating static glazing as non-compliant regardless of U-factor performance. Building departments in Los Angeles and San Francisco enforce this through plan check holds that delay occupancy permits for non-compliant envelope specifications. Developers respond by specifying pre-certified electrochromic assemblies that carry documented performance degradation curves across 20-year service life.
Facility managers now bundle electrochromic glazing procurement with 10-year performance guarantees that include optical density maintenance and switching speed thresholds, displacing traditional equipment-only purchasing. This service-integrated model spreads capital expenditure across operating budgets and transfers degradation risk to manufacturers. The shift is most visible in Class A office retrofits in Manhattan and Chicago, where lease rollover schedules compress installation windows and favor single-source accountability.
Electrochromic Window Market Segmentation
Electrochromic window segmentation reveals how substitution pressure from static high-performance glazing and mechanical shading systems varies across product architectures. Technology choices determine lithium-ion intercalation efficiency and manufacturing scalability. Application contexts impose divergent performance requirements for switching speed, optical density range, and integration complexity.
Product Type:
Passive Windows face the most acute substitution threat from low-emissivity static glazing as building codes tighten thermal performance without mandating dynamic modulation.
- Passive Windows:Fixed-tint electrochromic assemblies with minimal electrical infrastructure requirements. Demand concentrates in residential retrofits across California and New York where simplified installation reduces labor costs and permitting complexity.
- Active Windows:Fully addressable multizone glazing with manual override interfaces and automated daylight harvesting algorithms. High-rise commercial retrofits in Manhattan and Chicago specify these units where tenant comfort controls justify premium procurement.
- Switchable Glazing:Binary clear-to-opaque systems optimized for instant privacy transitions. Healthcare facilities in Boston and surgical suite construction drive specifications where pathogen-harboring manual blinds face elimination mandates.
- Tintable Glass:Continuously variable transmission glazing with gradient control across surface areas. Automotive sunroof applications and luxury residential skylights represent primary demand clusters.
Active Windows retains volume leadership; Switchable Glazing holds the steepest expansion curve.
Technology:
Cost tier stratification separates mature electrochemical platforms from emerging solid-state architectures competing on installation labor reduction.
- Electrochemical:Established tungsten oxide and nickel oxide film stacks with proven 20-year degradation curves. Commercial building developers in California specify these systems for Title 24 compliance where pre-certification accelerates permitting.
- Electromechanical:Micro-blind and suspended particle devices offering faster switching than ion-intercalation systems. Automotive rearview mirror applications dominate demand where Gentex Corporation holds captive process expertise.
- Thermochromic:Temperature-responsive vanadium dioxide coatings requiring no electrical input. Residential markets in sun-belt states adopt these where first-cost sensitivity exceeds performance optimization priorities.
- Photovoltaic:Self-powered electrochromic laminates embedding amorphous silicon micro-cells. Historic building envelopes in preservation districts specify these where conduit runs face architectural review restrictions.
Electrochemical platforms retain volume leadership; Photovoltaic integration gains share fastest.
Application:
Customer type divergence separates specification-driven commercial procurement from price-sensitive residential adoption patterns.
- Residential Buildings:Single-family and multifamily installations prioritizing glare reduction and HVAC load management. California net-zero mandates and federal tax incentives accelerate replacement cycles in new construction.
- Commercial Spaces:Class A office, hospitality, and retail facades requiring dynamic solar heat gain coefficient modulation. New York Local Law 97 carbon caps force retrofit specifications where five-year payback thresholds govern capital allocation.
- Automotive:Sunroofs, side windows, and rearview mirrors demanding rapid switching and extreme temperature durability. OEM integration timelines extend 36-48 months from specification to production.
- Aerospace:Passenger cabin dimming windows and cockpit glare control. Fleet retrofit programs for narrow-body aircraft create replacement demand cycles independent of new platform development.
Commercial Spaces retains volume leadership; Aerospace applications expand most quickly.
End User:
Supply concentration among thin-film coating engineers forces specification influencers to compete for limited fabrication capacity across divergent project scales.
- Architects:Design-phase specification authority controlling envelope performance criteria in competitive bid processes. Firms with net-zero project portfolios concentrate in California, New York, and Massachusetts.
- Contractors:Installation and commissioning responsibility holders managing glazing subcontractor coordination. Union labor jurisdictions in Chicago and New York impose training requirements for smart envelope systems.
- Manufacturers:Original equipment producers and fabricators operating sputtering deposition lines. Capacity constraints at vacuum coating facilities extend lead times 14-18 months for large commercial contracts.
- Facility Managers:Operations and maintenance decision-makers with replacement authority during lease rollover events. Service-integrated procurement models transfer degradation risk to manufacturers through 10-year performance guarantees.
Architects retain specification leadership; Facility Managers gain procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochromic window consumption patterns diverge sharply by geography: North American developers prioritize Title 24 compliance and carbon cap retrofits, while European procurement emphasizes REACH-certified low-carbon materials, and Asian markets concentrate on cost-optimized electrochemical platforms for high-rise residential towers.
United States
California's net-zero building mandates and New York Local Law 97 carbon caps drive Class A office retrofits in Los Angeles and Manhattan. The Department of Energy's Building Technologies Office accelerates dynamic envelope performance standards. Fabrication capacity concentrates in upstate New York and the Pacific Northwest where vacuum deposition expertise clusters near legacy semiconductor regions.
Germany
Commercial facade developers in Frankfurt and Munich specify electrochromic assemblies to meet the EU Energy Performance of Buildings Directive efficiency thresholds. ECHA REACH compliance frameworks restrict certain electroactive materials while accelerating certified glazing procurement. Industrial coating specialists in Bavaria and Baden-Württemberg operate magnetron sputtering lines serving Central European retrofit contracts.
China
High-rise residential construction in Shanghai and Shenzhen absorbs cost-optimized electrochemical glazing for solar heat gain management. The Ministry of Ecology and Environment's dual carbon goals pressure envelope performance in new commercial towers above 100 meters. Domestic indium refining capacity supplies transparent conductor layers, though export quota volatility exposes manufacturers to input cost swings.
Japan
Tokyo's dense commercial districts favor compact electrochromic retrofits where mechanical shading proves structurally impractical. METI building efficiency standards mandate dynamic solar control in new construction above eight stories. Automotive-derived coating expertise in the Chubu region transfers to architectural applications through technology licensing arrangements.
United Kingdom
London's heritage building preservation rules accelerate self-powered photovoltaic-integrated electrochromic deployments where conduit runs face architectural review restrictions. The Future Homes Standard and building regulation Part L revisions tighten envelope performance requirements. Installation contractors in the Southeast and Midlands develop specialized glazing crews for smart envelope systems.
Electrochromic Window Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive ion-conductive layer expertise and vertical control over sputtering equipment separating premium facade suppliers from component assemblers. The market structure rewards backward integration into transparent conductor fabrication and thermal annealing capabilities, while specialist coating engineers compete for limited vacuum deposition talent across battery and display sector demand. Dominant competitive moves include capacity expansion at fabrication facilities and strategic partnerships with glazing subcontractors in union labor jurisdictions.
Among North American-integrated specialists, SageGlass and View, Inc. occupy positions exemplifying captive process control from film deposition through installed systems, while Gentex Corporation represents the automotive-to-aerospace competency transfer archetype. These three anchors illustrate how vertical integration depth, application domain focus, and regional regulatory alignment separate competitive tiers in dynamic glazing procurement.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| Chromogenics AB |
| SageGlass |
| Miru Smart Technologies |
| Guardian Industries |
| View, Inc. |
| AGC Inc. |
| Research Frontiers Inc. |
| Gentex Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between electrochromic glass manufacturers and Class A commercial developers in California lock in both indium tin oxide supply access and five-year price visibility against raw material volatility. These contracts bundle installation labor with performance guarantees, transferring degradation risk to suppliers while securing capacity reservation at fabrication facilities facing 14-18 month lead times.
Pricing Analysis
Project-based contracting dominates electrochromic window procurement, with pricing stratifying across premium certified, standard pre-certified, and economy non-certified tiers based on UL and Title 24 compliance status. Price differentiation rests on optical density range guarantees and switching speed thresholds, with healthcare facilities in Boston showing least price sensitivity due to infection control mandates. Cost compression in the economy tier is intensifying as Chinese electrochemical platforms enter North American distribution channels.
Supply Chain Analysis
China and South Korea anchor transparent conductor layer production, with Chinese smelters supplying indium tin oxide and Korean manufacturers producing high-purity lithium-ion intercalation films. The electrochromic supply chain draws from tungsten oxide refiners in Jiangxi province, nickel oxide processors in Finland, and vacuum deposition equipment fabricators in Germany. Single-source vulnerability concentrates in Chinese indium refining capacity, exposing manufacturers to export quota volatility. Distribution runs through glazing subcontractors in union labor jurisdictions and direct OEM relationships with facade integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochromic window demand is recovering through the commercial real estate retrofit cycle, with lease rollover schedules in Manhattan and Chicago compressing installation windows and accelerating replacement decisions.
For Market Incumbents: Compound captive ion-conductive layer expertise through backward integration into tungsten oxide film deposition, defending against emerging solid-state architectures that threaten electrochemical platform margins. Add capacity in upstate New York fabrication clusters to capture Massachusetts stretch code compliance demand before certification timelines extend. For New Entrants and Emerging Players: CE marking fast-track through ECHA REACH pre-certification opens white-space access in German commercial facade retrofits where incumbent capacity constraints extend lead times. Target healthcare switchable glazing specifications in Boston and surgical suite construction as the most penetrable segment, deploying self-powered photovoltaic-integrated units that eliminate electrical infrastructure modification costs. For Investors and Strategic Acquirers: Thin-film coating specialists with captive magnetron sputtering expertise represent the priority acquisition archetype, given talent scarcity across battery and display sector competition. Long-term viability hinges on regulatory alignment with dynamic envelope mandates across North American and European jurisdictions. Watch for Massachusetts and Washington state stretch code adoptions as inflection signals for pre-certified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Deposition | Captive supply of lithium-ion intercalation layers reduces exposure to Chinese indium quota volatility. |
| Massachusetts Stretch Code Pre-Certification | First-mover positioning ahead of bifurcated state-level energy standards accelerates permitting timelines. |
| Photovoltaic-Integrated Product Launch | Self-powered solid-state architectures unlock historic building envelopes where conduit runs face preservation restrictions. |
| Healthcare Facility Partnership | Surgical suite specifications in Boston replace pathogen-harboring manual blinds with instant privacy transitions. |
| 10-Year Performance Guarantee Program | Service-integrated procurement transfers degradation risk to manufacturers while capturing Class A office retrofit demand. |
Methodological Framework
The analysis maps electrochemical, solid-state, and photovoltaic-integrated sub-sectors, each validated through thin-film coating engineers, commercial glazing contractors, and facility managers with lease rollover authority. Primary interviews with vacuum deposition specialists, facade integrators, and Title 24 compliance officers combined with secondary validation against California Energy Commission filings, UL certification databases, and ECHA REACH substance restrictions. Bottom-up project pipeline tracking and top-down construction spend analysis triangulate volume estimates.
Consistency checks validated outputs against commercial building permit data and electrochromic specification frequencies in Class A office retrofits. The forecast framework models technology adoption by product architecture, application context, and regional regulatory cluster across the projection horizon. CAGRs derive from lithium-ion intercalation efficiency improvements and tungsten oxide film deposition cost curves, with inputs including magnetron sputtering throughput scaling and indium tin oxide price indices.
Decision-makers should treat outputs as directional under sustained Title 24 enforcement and REACH compliance stability; material deviation in indium export quotas or F-Gas Regulation thresholds would warrant model refresh. Recalibration cycles align with state-level stretch code adoptions and fabrication facility capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Low Power Display Market
Display Technologies
Flexible Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
OLED Panel Market
Display Technologies
Laptop Panels Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Smart Screen Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Thin Display Technology Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Global Medical Display Market
Display Technologies
Microdisplay Market
Display Technologies
Global Magic Wall Interactive Surface Market