
 Europe Lithium Niobate Modulator Market | 2026-2036
Europe Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lithium Niobate Modulator Market Analytics
Component refurbishment revenue is fragmenting across legacy telecom rebuilds and emerging quantum communication pilots. iXblue Group leverages its French manufacturing base to dominate naval and satellite-grade modulator supply. Thorlabs sustains broad catalog distribution across European research institutions. Gooch & Housego specializes in acousto-optic variants that compete for niche industrial sensing contracts.
Lithium niobate modulators exploit the electro-optic coefficient of LiNbO3 crystals to encode electrical signals onto optical carriers at bandwidths exceeding 40 GHz, serving fiber-optic transmission and precision measurement systems. Optical modulators lead European volume shipments due to dense wavelength-division multiplexing rollouts in core networks. Integrated photonics is displacing bulk-crystal assemblies in quantum key distribution nodes across Dutch and Swiss pilot programs.
REACH chemical restrictions and the EU Green Deal shape material sourcing and wet-etching process standards for LiNbO3 substrate production. CE marking under the RoHS framework governs market access for modulators deployed in civilian telecommunications hardware. Stakeholders must track ECHA substance-of-very-high-concern listings that could restrict niobium pentoxide precursor availability.
Market Dynamics
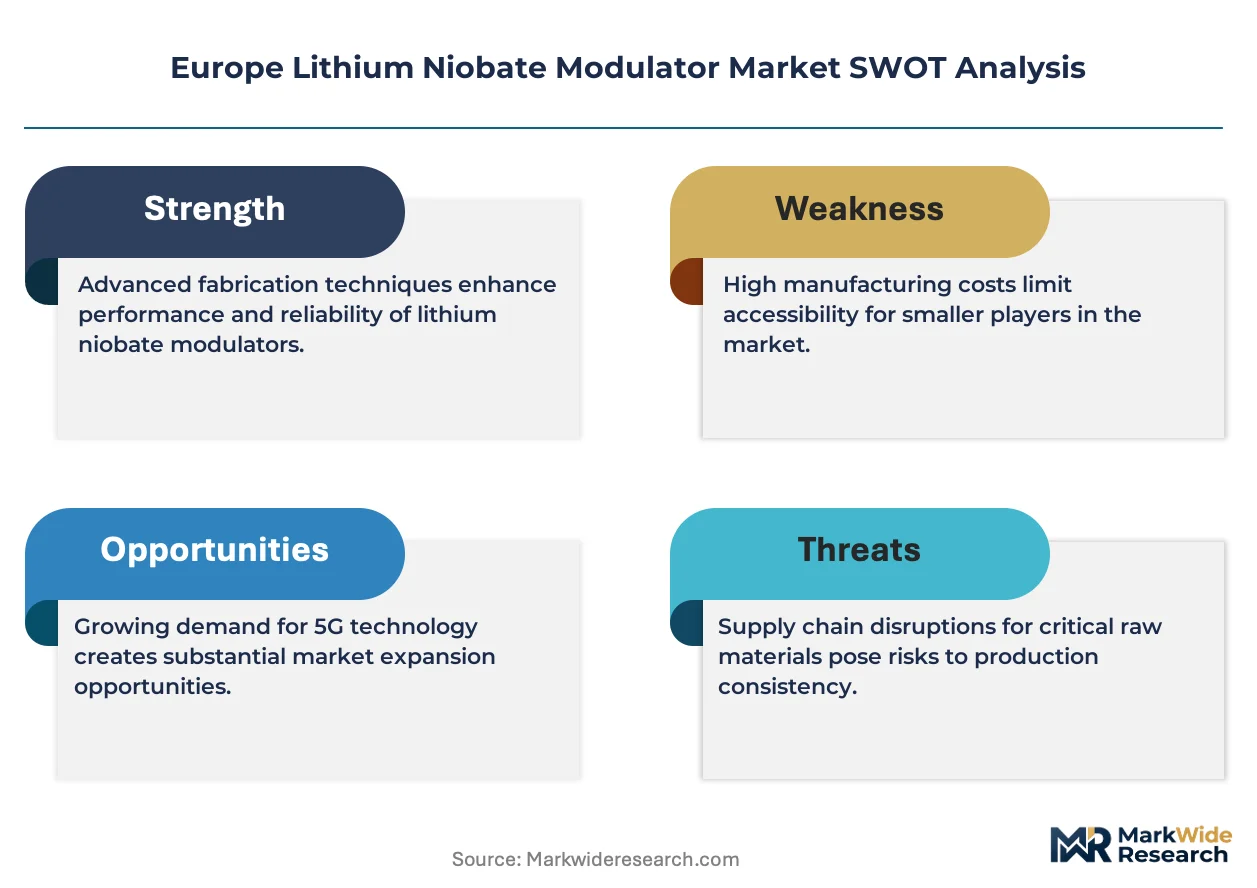
Integrated photonics architectures are compressing demand for bulk-crystal assemblies across European quantum communication pilots, while REACH compliance costs reshape wet-etching process economics for LiNbO3 substrate fabrication.
Growth Catalysts
- EU Green Deal:Carbon-neutral manufacturing mandates accelerate thin-film lithium niobate adoption over legacy bulk-crystal methods in German and French production facilities.
- Telecommunications infrastructure:Dense wavelength-division multiplexing rollouts in core networks drive optical modulator volume shipments across Germany's photonics cluster.
- Quantum key distribution:Dutch and Swiss pilot programs deploy integrated photonic modulators for cryptographic applications, creating specialized demand channels.
Market Restraints
- Niobium pentoxide supply concentration:ECHA substance-of-very-high-concern listings threaten precursor availability from concentrated Brazilian and Canadian mining operations.
- Thin-film fabrication capex:Ion-beam etching and wafer-bonding equipment requires capital outlays that exclude mid-tier European contract manufacturers.
- Silicon photonics substitution:CMOS-compatible modulators from integrated photonics foundries capture price-sensitive datacom applications below 40 GHz.
Strategic Opportunities
- Naval and satellite-grade supply:French manufacturing bases capture defense procurement contracts requiring radiation-hardened and thermally stable modulator specifications.
- Research institution channels:European universities and national laboratories fund bespoke modulator development for quantum sensing and spectroscopy applications.
- CSRD disclosure requirements:Corporate sustainability reporting mandates create audit-ready supply chain documentation services as a value-added revenue stream.
Industry Challenges
- Electro-optic design talent:Compound semiconductor and lithium niobate process engineering expertise concentrates in aging workforce cohorts across Jena and Berlin corridors.
- CE marking timelines:RoHS framework compliance testing for civilian telecommunications hardware extends product launch cycles by four to six months.
- Legacy telecom integration:Fiber-optic network operators require backward-compatible modulator interfaces that increase firmware complexity and qualification burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lithium Niobate Modulator Market |
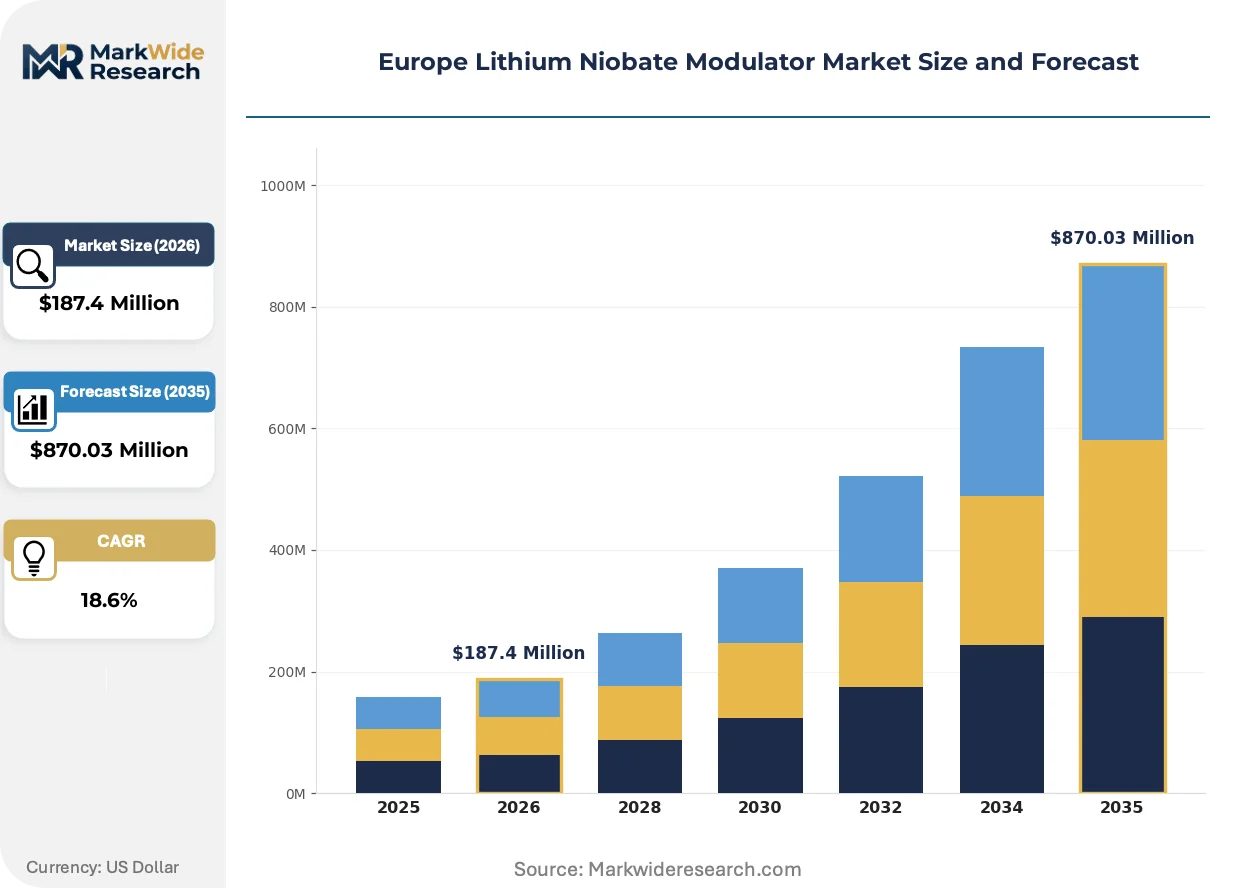
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Modulators, Electrical Modulators, Hybrid Modulators, RF Modulators End User: Telecommunications, Aerospace, Industrial Automation, Research Institutions Deployment: On-Premise, Cloud, Hybrid, Edge Technology: LiNbO3 Technology, Integrated Photonics, Microfabrication, Quantum Dots |
| Companies Covered | iXblue Group, Thorlabs, EOSPACE, Gooch & Housego, Fujitsu Optical Components, Lumentum Operations, Phase Sensitive Innovations, Optilab, AFR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lithium Niobate Modulator Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are reconfiguring how European modulator suppliers design, manufacture, and document their electro-optical components for next-generation networks.
Thin-film lithium niobate on insulator is hybridizing electro-optic performance with semiconductor scalability. Research consortia in the Netherlands and Switzerland are adopting this platform for quantum key distribution nodes at pilot scale. The technology is hybridizing previously separate bulk-crystal and integrated photonics supply chains into unified wafer-fabrication ecosystems.
REACH chemical restrictions are tightening wet-etching process standards for LiNbO3 substrate production across European fabrication facilities. Manufacturers must substitute hydrofluoric acid-based chemistries with fluorine-free alternatives or invest in closed-loop recycling systems. German modulator suppliers face the steepest compliance costs due to existing production volumes and ECHA reporting thresholds.
Specification-driven purchasing is consolidating buyer power among telecommunications infrastructure operators. Network equipment vendors now demand modulator performance guarantees tied to field failure rates rather than laboratory specifications, compressing supplier margins. This behavioral shift is most visible in procurement contracts from German and French national broadband rollout programs.
Europe Lithium Niobate Modulator Market Segmentation
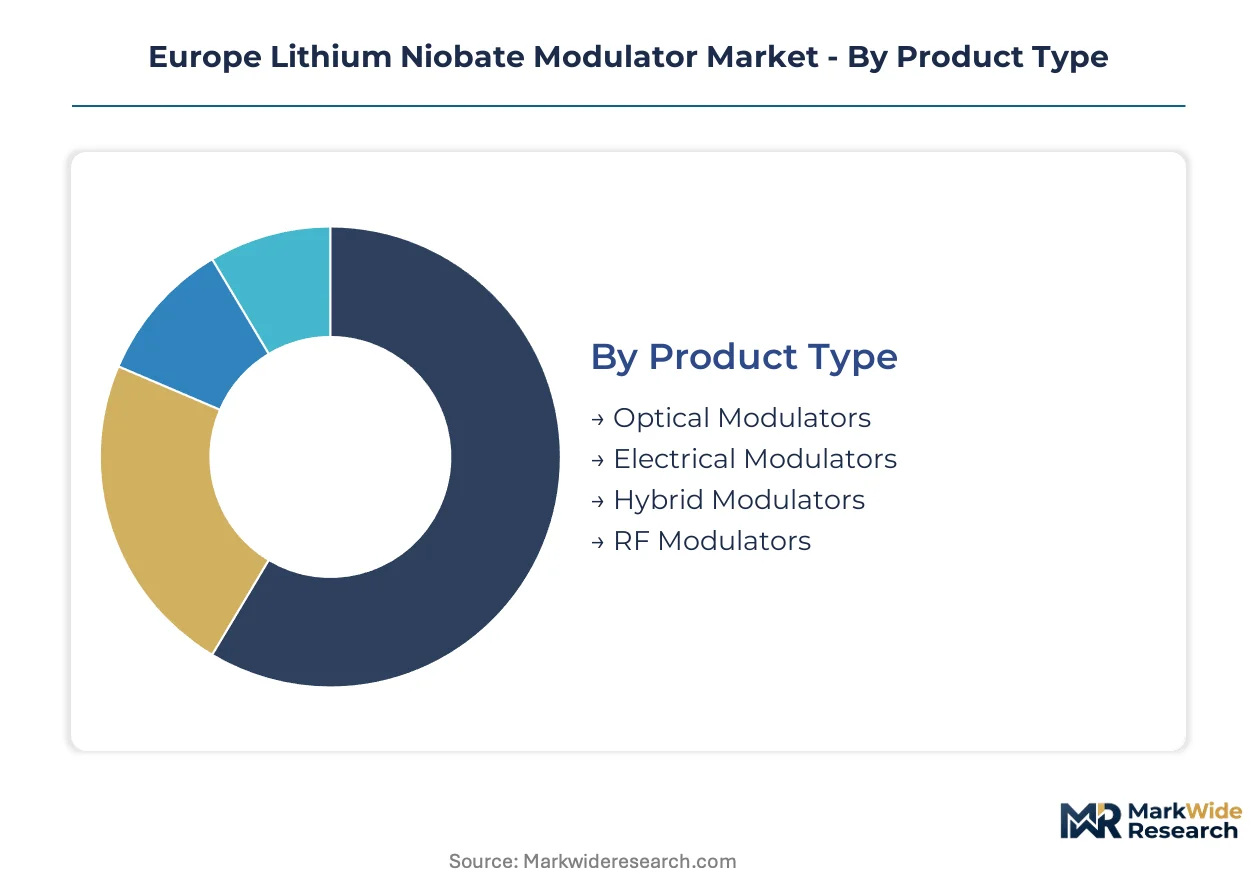
Segmentation in the Europe Lithium Niobate Modulator Market exposes divergent service intensity requirements across product architectures. Optical modulators demand field calibration protocols, while emerging integrated photonics platforms shift failure modes toward wafer-level diagnostics. Procurement patterns in German telecom infrastructure versus French defense applications create distinct aftermarket revenue profiles.
Product Type:
After-sales service intensity varies sharply across electro-optic architectures, with bulk-crystal assemblies requiring periodic alignment maintenance while thin-film platforms concentrate reliability risk at the packaging stage.
- Optical Modulators:These LiNbO3 crystal-based devices encode electrical signals onto optical carriers through the Pockels effect, achieving bandwidths beyond 40 GHz. Dense wavelength-division multiplexing rollouts in Germany's core networks concentrate procurement volume, though REACH compliance costs for wet-etching substrate fabrication compress supplier margins on replacement units.
- Electrical Modulators:Direct voltage-controlled phase shifters operating at lower optical power thresholds suit laboratory environments and test equipment. Swiss and Dutch quantum key distribution pilots drive specialized demand for low-Vπ configurations, with procurement specifications tightening around thermal drift coefficients.
- Hybrid Modulators:Multi-material assemblies combining lithium niobate with silicon nitride waveguides serve research institutions requiring tunable extinction ratios.
- RF Modulators:Microwave-frequency variants with specialized electrode geometries target satellite communication ground stations in France and Italy.
By volume, Optical Modulators leads. By growth pace, Hybrid Modulators is gaining share fastest as research consortia scale pilot programs.
End User:
Cost tier stratification separates volume telecommunications procurement from premium-priced defense and scientific applications, with certification requirements driving 3-4x price multiples at the top tier.
- Telecommunications:National broadband infrastructure operators in Germany and France specify modulators with guaranteed field failure rates rather than laboratory performance metrics. Procurement contracts from Deutsche Telekom and Orange SA consolidate buyer power, compressing supplier margins while mandating backward-compatible firmware interfaces.
- Aerospace:Satellite-grade modulators require radiation-hardened specifications and thermal cycling resilience across orbital temperature extremes. French defense procurement channels through iXblue Group and Thales Alenia Space concentrate demand for space-qualified LiNbO3 assemblies with decade-long operational lifetimes.
- Industrial Automation:Machine vision and laser machining systems deploy acousto-optic modulator alternatives where Gooch & Housego competes for niche sensing contracts.
- Research Institutions:European universities and national laboratories fund bespoke electro-optic device development for quantum sensing and spectroscopy applications.
Telecommunications generates the highest unit volumes. Aerospace commands the steepest expansion trajectory as constellation deployment accelerates.
Deployment:
Customer type segmentation distinguishes hyperscale network operators with captive technical staff from enterprise buyers requiring managed service overlays.
- On-Premise:Dedicated hardware installations in carrier central offices and data centers. German photonics clusters around Berlin and Jena concentrate manufacturing and integration expertise for these traditional deployments.
- Cloud:Virtualized network functions displacing physical modulators in software-defined optical transport. This segment climbs the fastest as telecom operators consolidate infrastructure.
- Hybrid:Split architectures with edge modulation and cloud-based digital signal processing.
- Edge:Distributed access network nodes requiring low-power, thermally stable modulator specifications.
On-Premise retains installed base dominance. Cloud deployment is expanding most quickly through virtualization of optical layer functions.
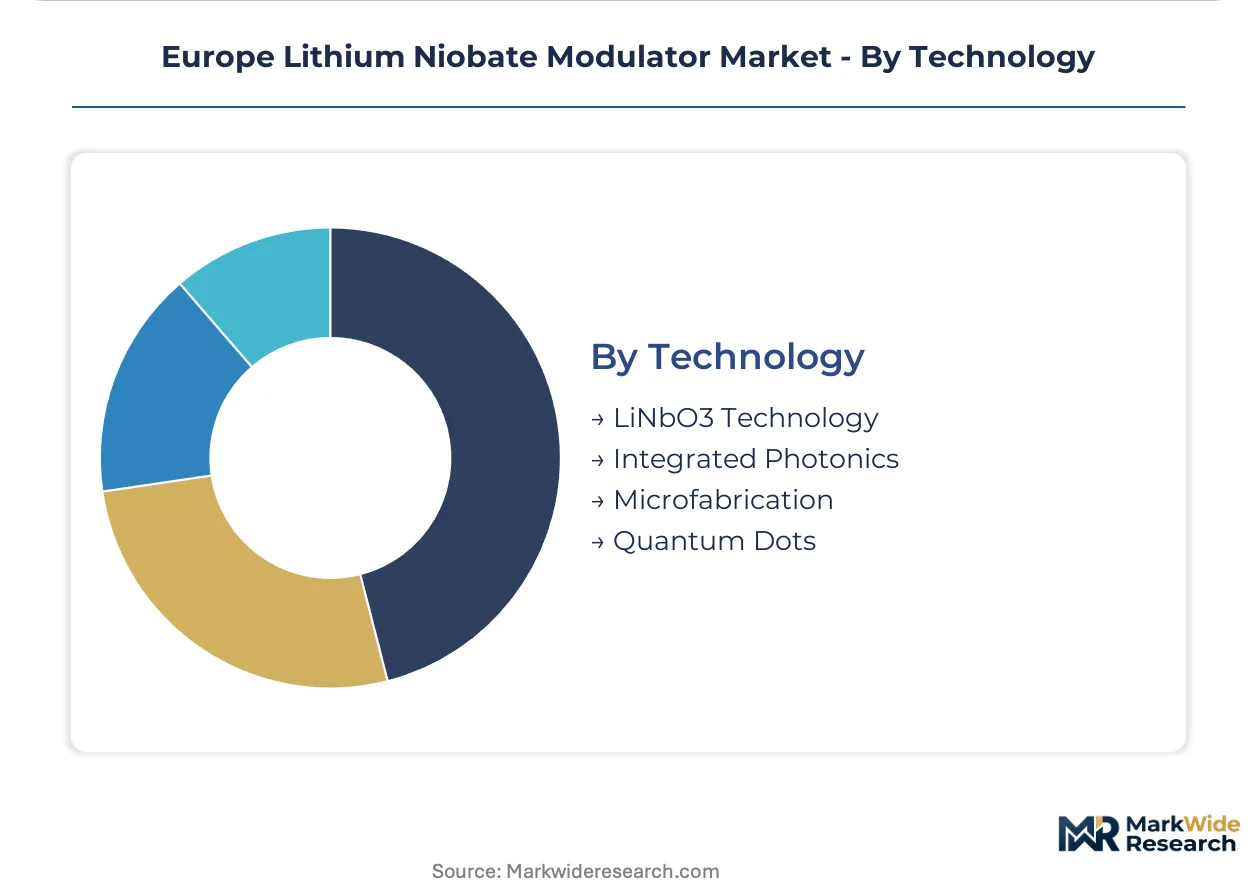
Technology:
Supply concentration for ion-beam etching and wafer-bonding equipment excludes mid-tier European contract manufacturers from thin-film lithium niobate production.
- LiNbO3 Technology:Conventional bulk-crystal electro-optic modulators fabricated from z-cut or x-cut lithium niobate substrates. Mature wet-etching processes face REACH chemical restrictions on hydrofluoric acid usage, with German suppliers bearing steepest compliance costs due to ECHA reporting thresholds.
- Integrated Photonics:Thin-film lithium niobate on insulator hybridizing electro-optic performance with semiconductor scalability. Netherlands and Swiss research consortia adopt this platform for quantum key distribution nodes, unifying previously separate bulk-crystal and wafer-fabrication supply chains.
- Microfabrication:MEMS-compatible processing for miniaturized modulator arrays in sensing applications.
- Quantum Dots:Emerging single-photon source integration for quantum communication protocols.
LiNbO3 Technology retains volume leadership. Integrated Photonics shows the steepest expansion trajectory as thin-film platforms displace legacy assemblies in pilot deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European lithium niobate modulator manufacturing clusters in Germany and France command the dominant share of regional output, with Dutch and Swiss research hubs accelerating thin-film platform adoption for quantum communication pilots.
Germany
Deutsche Telekom's national broadband infrastructure drives dense wavelength-division multiplexing procurement volumes. REACH compliance costs for hydrofluoric acid etching processes burden Berlin and Jena suppliers with elevated ECHA reporting thresholds. The photonics cluster around Jena concentrates bulk-crystal assembly expertise and ion-beam etching equipment installations.
France
Naval and satellite-grade modulator demand from Thales Alenia Space anchors defense procurement channels. The EU Green Deal carbon-neutral manufacturing mandates push iXblue Group toward thin-film lithium niobate process transitions at its French manufacturing base. Paris-region facilities specialize in radiation-hardened specifications for orbital deployment lifetimes.
Netherlands
Quantum key distribution pilot programs at TU Delft and QuTech generate specialized demand for integrated photonic modulators. ECHA substance-of-very-high-concern monitoring affects niobium pentoxide precursor sourcing strategies for Dutch research consortia. The Eindhoven-Utrecht corridor hosts wafer-bonding equipment installations serving thin-film platform development.
Switzerland
Swiss quantum communication initiatives at ID Quantique and university laboratories procure low-Vπ electrical modulator configurations. Swissmedic-equivalent device standards for optical components apply to telecommunications hardware certification timelines. The Zurich-Geneva axis concentrates precision measurement system suppliers serving spectroscopy applications.
United Kingdom
Gooch & Housego's acousto-optic specialization competes for industrial sensing contracts in laser machining and machine vision segments. RoHS framework CE marking requirements extend product launch cycles for civilian telecommunications hardware by four to six months. The Cambridge-Oxford photonics corridor funds bespoke electro-optic device development for national laboratory research programs.
Europe Lithium Niobate Modulator Market Competitive Landscape
Defense-anchored specialists and broad-catalog distributors split the market into distinct competitive spheres. The vendor base organizes around three strategic archetypes: vertically integrated defense contractors with captive foundry capacity, catalog distributors serving research institutions, and component specialists competing for niche industrial contracts. Capacity expansion into thin-film lithium niobate platforms and strategic partnerships with quantum communication research consortia constitute the dominant competitive moves reshaping positioning.
Within the defense-specialist tier, iXblue Group exemplifies vertically integrated French manufacturing with naval and satellite-grade supply concentration. Thorlabs occupies the catalog distributor archetype, sustaining broad distribution relationships across European research institutions. Gooch & Housego represents the component-specialist position, anchoring acousto-optic variant competition for industrial sensing applications. These three entities collectively illustrate the geographic and strategic segmentation defining European competitive dynamics.
| Leading Market Players |
|---|
| iXblue Group |
| Thorlabs |
| EOSPACE |
| Gooch & Housego |
| Fujitsu Optical Components |
| Lumentum Operations |
| Phase Sensitive Innovations |
| Optilab |
| AFR |
| Others |
Value Network & Pricing Analysis
Jena's photonics cluster concentrates ion-beam etching capacity and wet-etching expertise, granting German suppliers outsized leverage over thin-film lithium niobate pricing while REACH compliance costs compress margins for legacy bulk-crystal producers. French defense procurement channels anchor premium pricing for radiation-hardened specifications, creating a bifurcated cost structure across civilian and military-grade segments.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across European lithium niobate modulator supply, separating fluorine-free compliant producers from legacy hydrofluoric acid users. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with aerospace buyers absorbing the steepest premiums for radiation-hardened orbital specifications. Cost compression in standard-tier telecommunications procurement is intensifying because Deutsche Telekom and Orange SA consolidate buyer power through national broadband contracts. Research institutions exhibit the least price sensitivity due to bespoke development requirements, while datacom volume buyers drive the hardest unit-cost negotiations.
Supply Chain Analysis
ECHA substance-of-very-high-concern listings for niobium pentoxide dominate supply chain risk, threatening precursor availability from concentrated Brazilian and Canadian mining operations. European fabrication draws from German ion-beam etching equipment, French wafer-bonding installations, and Dutch thin-film research consortia. Raw material dependencies center on niobium pentoxide precursors, hydrofluoric acid etchants, and specialized electrode metallization. Single-source vulnerability concentrates in Brazilian niobium ore extraction controlled by CBMM. Distribution runs through direct defense procurement channels for satellite-grade units and catalog distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Lithium Niobate Modulator Market sits at an inflection where thin-film lithium niobate on insulator platforms disrupt legacy bulk-crystal economics, with EU Green Deal carbon-neutral mandates accelerating process transitions that will reshape competitive positioning across the projection horizon.
For Market Incumbents: Pre-empt silicon photonics substitution by accelerating thin-film lithium niobate capacity additions in French and German manufacturing corridors before CMOS-compatible alternatives capture sub-40 GHz datacom share. Anchor defensive positioning through backward integration into niobium pentoxide precursor sourcing to mitigate ECHA supply restrictions. Prioritize CE marking investment to compress four-to-six month compliance timelines that currently delay product launches against faster silicon photonics rivals. For New Entrants and Emerging Players: Swiss quantum communication laboratories represent underpenetrated demand for low-Vπ electrical modulator configurations with specialized thermal drift specifications. Target research institution channels with hybrid modulator offerings combining lithium niobate and silicon nitride waveguides, where procurement cycles favor technical differentiation over scale economies. Pursue partnership-based go-to-market models with Netherlands and Swiss quantum key distribution pilot programs rather than competing head-to-head in consolidated telecommunications procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive foundry capacity and established defense procurement relationships. Long-term viability hinges on thin-film platform transitions completing before silicon photonics achieves electro-optic coefficient parity. Watch for ion-beam etching equipment order backlogs as the signal indicating which suppliers will secure thin-film lithium niobate manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Lithium Niobate Capacity Expansion | EU Green Deal mandates accelerate carbon-neutral manufacturing transitions at French and German facilities. |
| Backward Integration into Niobium Sourcing | ECHA substance-of-very-high-concern listings threaten Brazilian and Canadian precursor supply security. |
| Research Consortium Partnership | Netherlands and Swiss quantum key distribution pilots generate specialized demand for integrated photonic platforms. |
| Defense Procurement Channel Deepening | Thales Alenia Space and French naval programs anchor decade-long operational lifetime contracts. |
| CE Marking Acceleration Investment | RoHS framework compliance testing currently extends product launch cycles for civilian telecommunications hardware. |
Research Methodology
Initial hypotheses were tested against primary input from electro-optic device engineering directors, telecommunications procurement managers at Deutsche Telekom and Orange SA, defense program officers at Thales Alenia Space, and research laboratory principal investigators, then refined through secondary validation against ECHA regulatory filings, EU Green Deal implementation documents, SEC 10-K disclosures from listed photonics suppliers, and customs trade data for niobium pentoxide imports. Bottom-up triangulation across component-level bill-of-materials analysis and top-down demand modeling from national broadband rollout schedules produced convergent volume estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, end-user industry, deployment model, and technology platform. CAGRs were derived from installed base replacement cycles, pilot program scaling trajectories, and regulatory compliance cost curves. Industry-specific forecast inputs incorporated REACH chemical restriction implementation timelines and quantum communication research funding allocations from Dutch and Swiss national programs.
Macroeconomic conditions sit as an overlay; deviation in euro-denominated capital equipment costs, niobium ore commodity volatility, or defense budget prioritization would shift the trajectory. Forecasts reflect documented assumptions about thin-film lithium niobate yield rates and ECHA substance-of-very-high-concern listing enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Electro-Optic Modulators Market
Optical Components
Liquid Light Guides Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Portable Lenses Market
Optical Components
Infrared Filter Market
Optical Components
Pancake Optical Module Market
Optical Components
Europe Optical Film Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Optical Position Sensors Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Bio-Optics Market
Optical Components
Faraday Rotator Market
Optical Components
ROADM WSS Component Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Ellipsometer Market