
 Global Monochrome Display Market | 2026-2036
Global Monochrome Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monochrome Display Market Foresight
Modular display kit configurations is recalibrating how industrial buyers evaluate monochrome panel procurement. Kyocera leverages its ceramic-to-display manufacturing heritage to sustain captive supply chains for high-reliability segments. BOE anchors volume production through in-house glass substrate and driver IC capabilities that competitors struggle to match. Richardson Electronics differentiates by dominating aftermarket replacement channels for legacy vacuum fluorescent and CRT-to-LCD conversions.
Monochrome display denotes a visual output device rendering images in a single color or grayscale spectrum without full RGB subpixel arrays, typically employing twisted nematic LCD, passive matrix OLED, or electrophoretic E Ink technologies with pixel densities ranging from 80 to 300 ppi for applications demanding sunlight readability and minimal power draw. Industrial instruments and medical devices constitute the primary commercial purpose, where color fidelity matters less than contrast ratio, viewing angle stability, and decade-long operational lifespan. Passive matrix LCD technology leads unit shipments across telecommunications equipment and basic instrumentation, while active matrix OLED segments capture margin pools in aerospace systems and premium medical imaging where rapid refresh and wide temperature tolerance command price premiums. E Ink technology occupies a defensible niche in battery-powered portable instruments and electronic shelf labels where bistable image retention eliminates continuous power consumption.
FDA device classification rules and the EU MDR framework shape product roadmaps by mandating specific display luminance, contrast minimums, and electromagnetic interference shielding for diagnostic equipment market access. Japan's METI energy efficiency directives and China's GB standards for electronic display modules add compliance layers that favor suppliers with established certification laboratories and regional testing partnerships. Stakeholders must monitor how RoHS exemptions for legacy industrial equipment interact with REACH substance restrictions affecting liquid crystal and backlight chemistries.
Market Dynamics
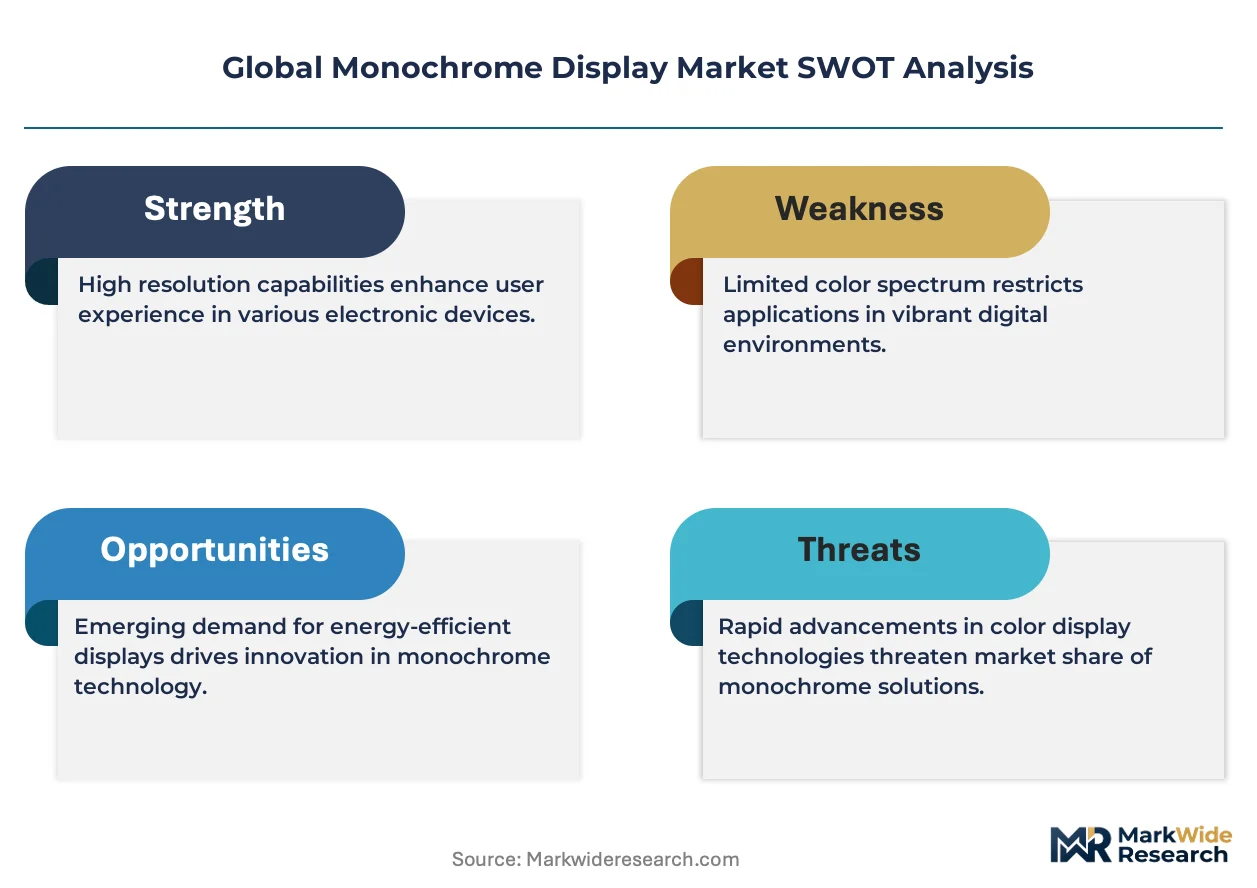
EU MDR luminance mandates and FDA electromagnetic compatibility rules are compressing supplier qualification timelines while simultaneously fragmenting procurement across certified and non-certified vendor pools.
Growth Catalysts
- Diagnostic Imaging Standards:FDA device classification rules now mandate minimum contrast ratios for patient monitoring interfaces, pulling monochrome panels into Class II medical equipment certifications.
- Telecommunications Infrastructure:5G base station deployments in Germany and Japan require outdoor-readable displays with decade-long operational lifespans, favoring passive matrix LCD architectures.
- REACH Compliance Arbitrage:RoHS exemptions for legacy industrial equipment are narrowing, creating replacement demand for compliant monochrome modules in process control systems.
Market Restraints
- Driver IC Supply Concentration:Taiwan and South Korea dominate integrated circuit fabrication for display controllers, exposing buyers to single-source vulnerability.
- Backlight Chemistry Constraints: REACH substance restrictions on liquid crystal compounds limit formulation flexibility and extend reformulation cycles for European market access.
- Color Display Substitution:Low-cost full-color TFT-LCD panels from Chinese glass substrate producers are penetrating price-sensitive instrumentation segments.
Strategic Opportunities
- Battery-Powered Portable Instruments:E Ink bistable technology eliminates continuous power draw, opening diagnostic device categories previously closed to active displays.
- Aerospace System Retrofits:FAA certification pathways for active matrix OLED wide-temperature modules are expanding addressable share in avionics replacement cycles.
- Electronic Shelf Label Migration:Retail automation in France and Germany is displacing paper price tags with electrophoretic monochrome displays.
Industry Challenges
- Electromagnetic Shielding Integration:EU MDR electromagnetic interference requirements demand specialized engineering talent scarce outside established medical device clusters.
- Legacy System Interface Compatibility:CRT-to-LCD conversion projects face signal timing mismatches requiring custom firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monochrome Display Market |
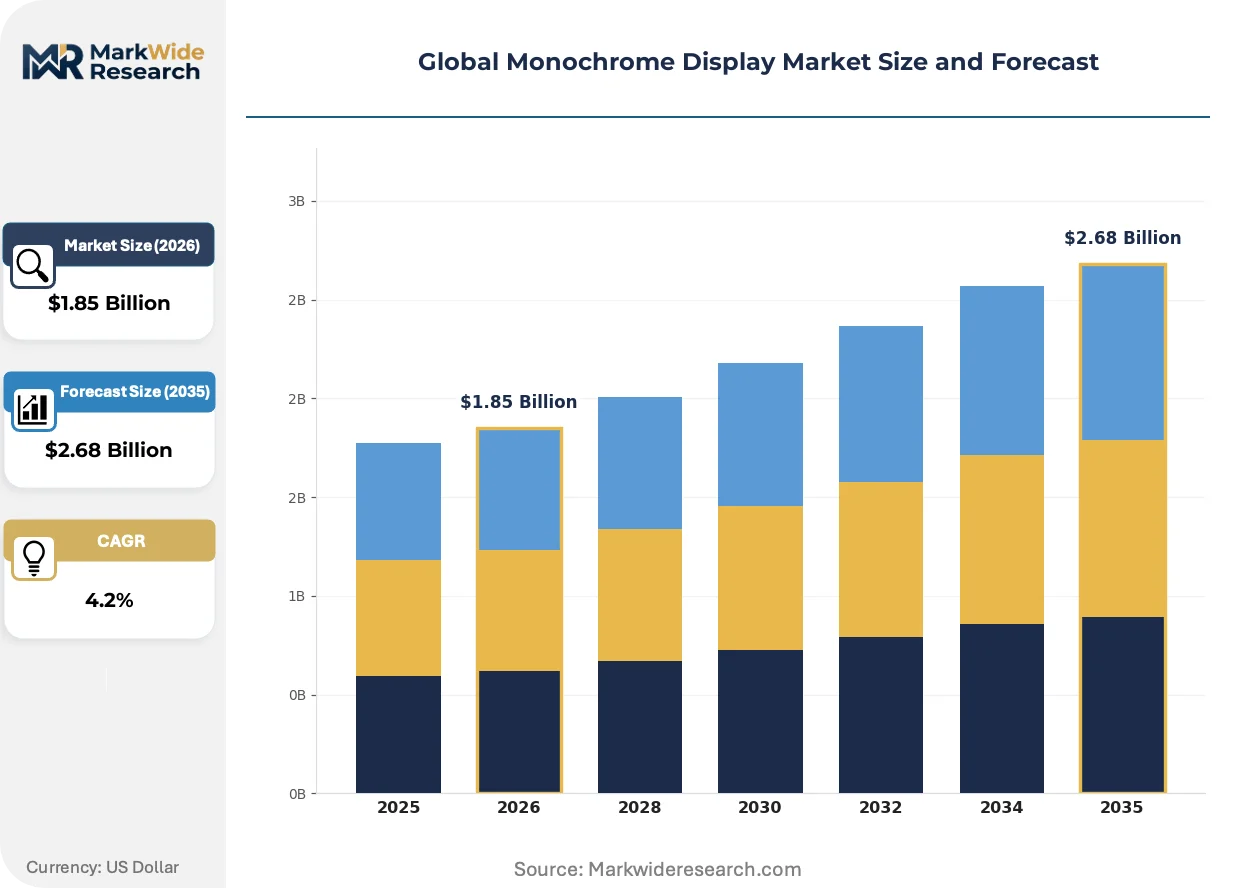
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, E Ink, MicroLED, LCD-Reflective Technology: Passive Matrix, Active Matrix, Segment, Character, Graphic Application: Consumer Electronics, Industrial Instruments, Telecommunications Equipment, Medical Devices, Aerospace Systems End User: Manufacturers, System Integrators, OEMs, Aftermarket Suppliers, Research Labs |
| Companies Covered | Kyocera, BOE, Japan Display Inc., Richardson Electronics, Eizo Corporation, AZ Displays, Raystar Optronics, Tianma Microelectronics, WiseChip Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monochrome Display Market Shifts & Advancements
Active matrix OLED modules are compressing refresh rate benchmarks while regulatory pressure on display luminance is rewriting procurement specifications across diagnostic equipment categories.
Electrophoretic E Ink technology is rewriting power architecture assumptions for battery-dependent instruments. Portable diagnostic device manufacturers in Germany are adopting bistable displays for glucose monitors and pulse oximeters. This shift is compressing the addressable market for traditional twisted nematic LCD in sub-5-inch portable categories.
EU MDR framework revisions are tightening electromagnetic compatibility shielding mandates for diagnostic imaging equipment. Industrial consequence includes extended certification timelines and expanded testing documentation. German and French medical device assemblers are responding by consolidating supplier relationships around pre-certified panel vendors.
Consolidated procurement by hospital group purchasing organizations is compressing vendor qualification cycles. Distributor networks serving independent medical device manufacturers are losing volume to direct OEM contracts. This pattern is most visible in United States healthcare technology procurement, where IDN consolidation favors suppliers with established FDA 510(k) clearance pathways.
Global Monochrome Display Market Segmentation
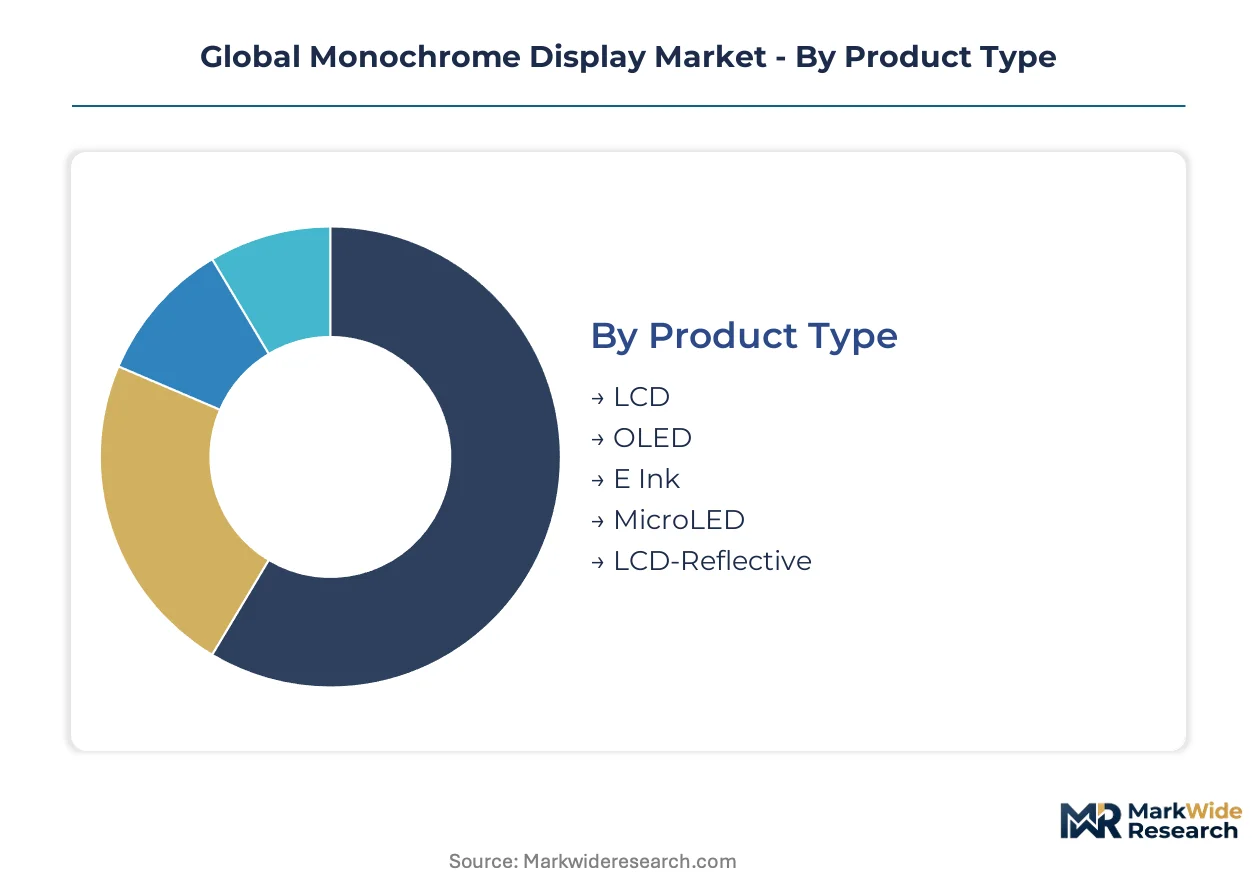
Monochrome display procurement patterns diverge sharply across product architectures, with passive matrix LCD dominating telecommunications infrastructure while active matrix OLED captures aerospace retrofit premiums. Technology selection directly determines certification pathways under FDA and EU MDR frameworks, fragmenting supplier pools by end-use compliance requirements.
Product Type:
Buyers differentiate primarily by power architecture constraints and ambient light performance rather than unit cost alone.
- LCD:Twisted nematic liquid crystal cells with LED edge-lit or reflective backing dominate outdoor telecommunications equipment in Germany and Japan. 5G base station deployments favor these modules for decade-long operational lifespans under METI efficiency directives.
- OLED:Active matrix organic diode stacks deliver sub-millisecond refresh rates and wide temperature tolerance for avionics systems. FAA certification pathways for these modules are expanding addressable share in aerospace replacement cycles.
- E Ink:Electrophoretic bistable technology eliminates continuous power draw, opening diagnostic device categories in France and Germany previously closed to active displays.
- MicroLED:Gallium nitride emitter arrays promise luminance durability beyond organic alternatives, with development concentrated in defense-funded research labs.
- LCD-Reflective:Front-lit reflective polarizer configurations serve battery-constrained portable instruments where backlight power budgets are prohibitive.
LCD leads volumes today; E Ink is gaining share fastest in medical portable categories.
Technology:
Manufacturing process complexity separates commodity supply from premium-margin segments with specialized driver IC requirements.
- Passive Matrix:Row-column electrode addressing without active switching elements sustains lowest unit costs for basic instrumentation. Taiwan and South Korea dominate the integrated circuit fabrication for these controllers.
- Active Matrix:Thin-film transistor backplanes enable per-pixel addressing for rapid refresh medical imaging. EU MDR luminance mandates pull these panels into Class II equipment certifications.
- Segment:Fixed-pattern electrode configurations display numeric or simple alphanumeric readouts in process control systems.
- Character:Pre-defined dot matrix blocks render standard ASCII sets for industrial terminals and telecommunications equipment.
- Graphic:Fully addressable pixel arrays support custom iconography and waveform rendering for patient monitoring interfaces.
Passive Matrix anchors production scale; Active Matrix commands the steepest expansion trajectory in diagnostic equipment.
Application:
Regulatory intensity varies dramatically by end-use, with medical and aerospace segments demanding specialized electromagnetic shielding engineering.
- Consumer Electronics:E-readers and portable instruments in Germany and France drive electrophoretic display demand for retail automation and battery-powered devices.
- Industrial Instruments:Process control systems across manufacturing clusters face REACH substance restrictions on liquid crystal compounds, narrowing RoHS exemption windows.
- Telecommunications Equipment:5G infrastructure in Japan and Germany requires outdoor-readable passive matrix LCD with minimal power draw.
- Medical Devices:Diagnostic imaging equipment under FDA classification rules mandates minimum contrast ratios and electromagnetic compatibility shielding.
- Aerospace Systems:Avionics retrofits favor active matrix OLED for wide temperature tolerance and rapid refresh performance.
Industrial Instruments leads procurement volume today; Medical Devices is climbing the fastest on regulatory-driven replacement cycles.
End User:
Consolidation patterns reshape channel access, with hospital group purchasing organizations compressing vendor qualification timelines for direct OEM contracts.
- Manufacturers:Medical device assemblers in Germany and France consolidate supplier relationships around pre-certified panel vendors under EU MDR framework revisions.
- System Integrators:Industrial automation specialists manage CRT-to-LCD conversion projects facing signal timing mismatches requiring custom firmware development.
- OEMs:Original equipment manufacturers in United States healthcare technology procurement favor suppliers with established FDA 510(k) clearance pathways.
- Aftermarket Suppliers:Legacy vacuum fluorescent and CRT replacement channels serve process control systems with extended operational lifespans.
- Research Labs:Defense and medical imaging research facilities pilot MicroLED and advanced OLED architectures before commercial scale-up.
OEMs dominate contract value today; Aftermarket Suppliers are expanding most quickly on legacy system replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered monochrome display commercialization through early liquid crystal research at Hitachi and Sharp facilities in the 1970s. German precision engineering clusters subsequently scaled industrial-grade panel production for automotive and medical instrumentation. Contemporary procurement concentrates in manufacturing corridors where FDA and EU MDR certification infrastructure overlaps with dense OEM ecosystems.
Japan
5G base station deployments and METI energy efficiency directives sustain demand for passive matrix LCD modules with decade-long operational lifespans. METI's Top Runner program mandates progressive efficiency improvements for electronic display modules. Manufacturing concentrates in Nagoya's Chubu region, where Kyocera leverages ceramic-to-display heritage for high-reliability telecommunications equipment.
Germany
Diagnostic imaging equipment manufacturers and industrial automation specialists drive procurement of EU MDR-certified panels with electromagnetic shielding integration. The EU Medical Device Regulation framework mandates specific luminance and contrast minimums for Class II equipment market access. Bavaria's Munich-Stuttgart corridor hosts medical device assemblers consolidating supplier relationships around pre-certified panel vendors.
United States
Hospital group purchasing organizations and IDN consolidation compress vendor qualification timelines for patient monitoring interfaces. FDA device classification rules now mandate minimum contrast ratios, pulling monochrome panels into 510(k) clearance pathways. Greater Boston's medical technology cluster anchors demand for aerospace-qualified active matrix OLED in avionics retrofit programs.
China
Volume production of passive matrix LCD modules for basic instrumentation and telecommunications equipment sustains manufacturing scale. GB standards for electronic display modules add compliance layers favoring suppliers with established regional testing partnerships. Yangtze River Delta facilities anchor BOE's in-house glass substrate and driver IC capabilities that competitors struggle to match.
South Korea
Driver IC fabrication concentration for display controllers creates single-source vulnerability exposure across global supply chains. MFDS medical device regulations align with FDA electromagnetic compatibility requirements, facilitating dual-market certification. Seoul Capital Area semiconductor foundries supply integrated circuits for active matrix backplanes in premium medical imaging segments.
Global Monochrome Display Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and temperature-tolerance specifications. The vendor base organizes into three tiers: integrated display-glass manufacturers commanding captive supply advantages, specialized medical-grade certifiers with established FDA pathways, and aftermarket replacement specialists serving legacy vacuum fluorescent conversions. Consolidation pressures intensify as hospital group purchasing organizations and European medical device assemblers narrow qualified supplier pools. Dominant competitive moves include backward integration into driver IC capabilities and geographic expansion through regional certification laboratory partnerships.
Within the integrated manufacturing tier, Kyocera and BOE exemplify divergent scale-positioning strategies. Kyocera represents the ceramic-to-display heritage archetype with captive supply chain control for high-reliability segments. BOE occupies the volume-production position through upstream control over glass substrate and driver IC fabrication. Richardson Electronics anchors the aftermarket replacement channel archetype, dominating legacy vacuum fluorescent and CRT-to-LCD conversion demand. Japan Display Inc. sits within the premium medical-grade certification tier where established regulatory pathways create defensive positioning.
| Leading Market Players |
|---|
| Kyocera |
| BOE |
| Japan Display Inc. |
| Richardson Electronics |
| Eizo Corporation |
| AZ Displays |
| Raystar Optronics |
| Tianma Microelectronics |
| WiseChip Semiconductor |
| Others |
Supply & Pricing Matrix
Glass substrate costs cascade through three distinct pricing tiers before reaching end-equipment assemblers in Germany and Japan. Driver IC wafer fabrication in Taiwan and South Korea anchors the premium tier for active matrix medical-grade panels, while passive matrix LCD modules from Yangtze River Delta facilities feed standard instrumentation segments.
Pricing Analysis
Three-tier pricing structure across FDA-certified premium, industrial-standard, and economy instrumentation levels governs contract negotiations. Certification grade under EU MDR and FDA 510(k) pathways creates the steepest price differentiation, with electromagnetic shielding integration adding substantial engineering premiums. Cost compression in the economy tier is intensifying because Chinese glass substrate producers are scaling reflective LCD output for basic telecommunications equipment. Hospital group purchasing organizations exhibit the highest price sensitivity through consolidated volume tenders, while aerospace OEMs prioritize temperature tolerance over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy CRT and vacuum fluorescent displays sustain aftermarket channel economics, with Richardson Electronics dominating North American recovery operations. Taiwan, South Korea, and China concentrate driver IC fabrication and glass substrate production, creating geographic clustering around semiconductor foundries and liquid crystal chemistry facilities. Raw material dependencies center on indium tin oxide for transparent electrodes, liquid crystal compounds subject to REACH restrictions, and gallium nitride for emerging MicroLED architectures. Single-source vulnerability in Taiwan's display controller wafer fabrication exposes buyers to geopolitical disruption. Distribution runs through direct OEM contracts for medical device assemblers and specialized industrial distributors serving process control retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in active matrix OLED medical imaging segments where EU MDR certification barriers protect pricing power. E Ink bistable technology penetration in portable diagnostics opens premium-tier displacement potential previously locked by LCD cost structures.
For Market Incumbents: Cement defensive positioning through backward integration into driver IC capabilities and captive glass substrate supply. Kyocera's ceramic-to-display heritage demonstrates how manufacturing heritage protects high-reliability telecommunications contracts. Threats from Chinese color TFT-LCD substitution in price-sensitive instrumentation demand accelerated certification investments under FDA electromagnetic compatibility rules. Channel control through pre-certified panel vendor status with German medical device assemblers represents the critical defensive lever. For New Entrants and Emerging Players: Capture white-space in aftermarket CRT-to-LCD conversion services where signal timing expertise creates service-layer stickiness. The most penetrable segment lies in French and German electronic shelf label deployment, where electrophoretic display demand outruns established supplier capacity. Battery-powered portable instruments for glucose monitoring and pulse oximetry present adjacent expansion terrain. A go-to-market angle anchored in regional certification laboratory partnerships accelerates EU MDR compliance timelines for niche medical device categories. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital group purchasing organizations compress qualified supplier pools to three-to-five pre-certified vendors per diagnostic equipment category. Long-term viability favors acquisition targets with established FDA 510(k) clearance pathways and active matrix OLED temperature-tolerance specifications. Mid-scale certifiers with electromagnetic shielding engineering talent in Bavaria's Munich-Stuttgart corridor represent the optimal target archetype. Practitioners should monitor FAA certification pathway expansion for wide-temperature avionics modules as an inflection signal for aerospace retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates market access for Class II diagnostic imaging equipment in Germany and France. |
| Driver IC Backward Integration | Reduces Taiwan wafer fabrication exposure for active matrix medical panel suppliers. |
| Regional Testing Partnership Expansion | Compresses electromagnetic compatibility validation timelines under METI efficiency directives. |
| Aftermarket Channel Strengthening | Captures legacy vacuum fluorescent replacement demand in process control systems. |
| E Ink Portable Diagnostic Development | Opens battery-powered instrument categories previously closed to active display technologies. |
Research Methodology
Coverage spans Japan, Germany, the United States, China, and South Korea, with primary inputs from each region's medical device and industrial instrumentation clusters. The analysis combines interviews with biomedical engineers, hospital GPO contracts managers, industrial automation procurement leads, and telecommunications equipment manufacturers with secondary validation from FDA 510(k) filings, EU MDR technical documentation, METI efficiency directive databases, and customs trade records. Bottom-up panel shipment estimates triangulate against top-down diagnostic equipment production forecasts.
Granularity-level framing models unit and value outputs at the product architecture level (LCD, OLED, E Ink, MicroLED), technology tier (passive matrix, active matrix, segment, character, graphic), and application segment (medical devices, industrial instruments, telecommunications equipment, aerospace systems, consumer electronics) across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns weighted by regulatory-driven replacement cycle acceleration. Industry-specific forecast inputs include 5G base station deployment schedules in Japan and Germany, EU MDR transition timelines for legacy equipment, and E Ink adoption curves in portable diagnostic devices.
Underlying measurement precision varies by segment; medical device and aerospace applications carry tighter precision than consumer electronics and basic instrumentation due to regulatory filing transparency. Forecasts reflect assumptions about certification timeline stability, driver IC supply continuity, and REACH substance restriction enforcement intensity. Practitioners should monitor FAA active matrix OLED certification pathway expansion, hospital GPO consolidation velocity, and Chinese color TFT-LCD pricing aggression for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Plasma Display Module Market
Display Technologies
Video Projector Market
Display Technologies
AMOLED Display Market
Display Technologies
Foldable Display Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Industrial Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Smart Screen Market