
 OLED Microdisplay Market | 2026-2036
OLED Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Microdisplay Market Intelligence
Defense avionics is pivoting toward helmet-mounted displays for fighter pilots and rotary-wing crews, reshaping procurement volumes across NATO-aligned fleets. Sony Corporation dominates high-resolution microdisplay supply for military-qualified systems through its semiconductor division in Japan. eMagin Corporation specializes in direct-patterned OLED technology for thermal weapon sights and night-vision goggles, sustaining its position in US Department of Defense programs. Kopin Corporation competes with liquid-crystal-on-silicon alternatives but navigates toward OLED partnerships for next-generation soldier systems.
OLED microdisplays are silicon-backplane-driven emissive devices measuring typically below one inch diagonally, fabricated by depositing organic electroluminescent layers onto CMOS wafers to achieve pixel densities exceeding 3,000 pixels per inch for near-eye viewing. Their primary purpose is to generate high-contrast, low-latency imagery in compact optical systems where space and power budgets are severely constrained. Head-Mounted Displays and Augmented Reality Devices command the largest revenue pools as enterprise and defense buyers prioritize field-of-view expansion and optical see-through performance. Active Matrix OLED technology leads production volumes due to its superior refresh rates and uniform luminance control, while Transparent OLED occupies niche architectural and automotive prototype applications with limited near-term scale.
The US Department of Defense mandates MIL-STD-810 environmental testing and ITAR compliance for display components in weapon systems, restricting supplier eligibility to domestic or allied-country manufacturers. China's MIIT promotes domestic OLED supply chain independence through GB standards and subsidy programs for semiconductor display equipment, altering competitive access for foreign firms. The EU AI Act and CE marking requirements for wearable devices will shape product certification pathways for European healthcare and industrial AR deployments. Stakeholders must monitor how export control expansions and dual-use technology classifications reshape cross-border component flows and foundry partnerships.
Market Dynamics
Active Matrix OLED technology is displacing legacy LCD architectures in near-eye applications, compressing refresh rates below 10 milliseconds and eliminating backlight assemblies to reduce optical stack thickness by 60%.
Growth Catalysts
- Military modernization mandates:NATO-aligned defense ministries are accelerating helmet-mounted sighting system procurement for fighter and rotary-wing platforms, creating sustained demand for ITAR-qualified display suppliers.
- MIIT domestic subsidy programs:China's Ministry of Industry and Information Technology channels capital into semiconductor display equipment localization, reducing import dependency for OLED deposition tools.
- Silicon backplane pixel density advances:CMOS wafer lithography improvements now enable 4,000+ pixels per inch in sub-inch diagonal formats, unlocking photorealistic imagery for surgical navigation and industrial inspection.
Market Restraints
- Organic emitter material cost volatility:Iridium-based phosphorescent dopants and rare metal precursors face supply concentration from South Korean and Japanese chemical processors, inflating bill-of-materials unpredictability.
- Wafer-level packaging yield limitations:Hermetic sealing of organic layers against moisture ingress requires thin-film encapsulation stacks that suffer 15-20% yield loss at foundries lacking automotive-grade cleanroom protocols.
- ITAR compliance barriers:US Department of Defense export controls restrict technology transfer to non-allied fabrication facilities, fragmenting supplier eligibility and elongating qualification timelines for foreign entrants.
Strategic Opportunities
- German industrial AR deployment:Automotive and precision manufacturing clusters in Baden-Württemberg and Bavaria are piloting OLED-based assisted-reality headsets for assembly guidance, representing an underpenetrated volume pool outside defense.
- EU AI Act certification pathways:The European Union's risk-based AI governance framework creates first-mover advantage for microdisplay vendors achieving CE-MDR dual compliance for diagnostic imaging wearables.
- Micro-LED convergence timing:Gallium nitride micro-LED maturation remains 3-5 years from cost parity, opening a window for OLED microdisplay vendors to establish architectural lock-in across medical and defense platforms.
Industry Challenges
- Multi-physics simulation talent scarcity:Opto-mechanical-thermal co-design for compact near-eye systems requires expertise spanning electromagnetic wave optics, CMOS transistor physics, and organic thin-film degradation modeling that concentrates at fewer than twelve global research centers.
- MIL-STD-810G environmental qualification timelines:Shock, vibration, and thermal cycling certification for avionics displays extends 18-24 months, compressing product refresh cycles and straining R&D amortization.
- Legacy night-vision goggle interface incompatibility:Existing PVS-14 and PVS-31 optical trains require mechanical redesign to accommodate OLED microdisplay form factors, forcing parallel sustainment of cathode ray tube supply chains during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Microdisplay Market |
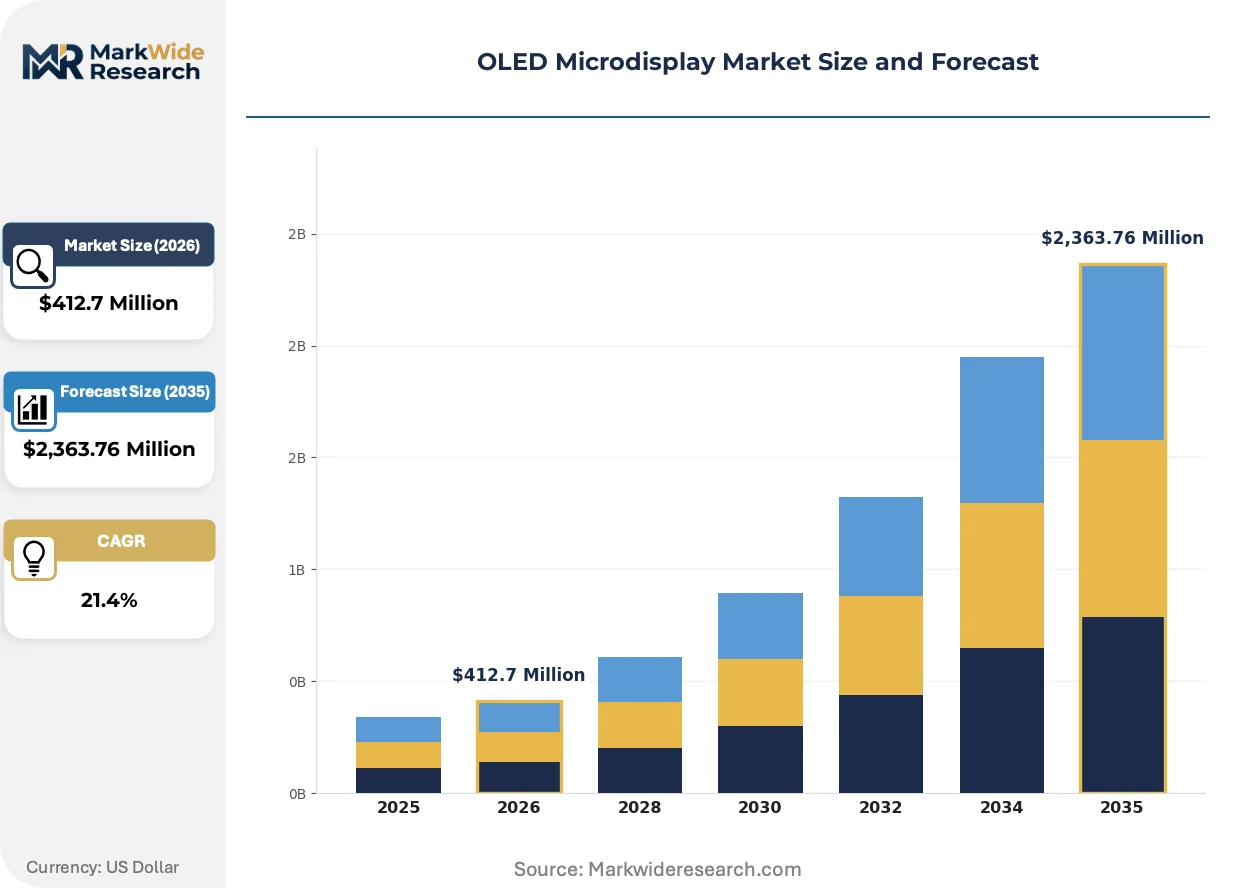
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $2,363.76 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Smart Glasses, Augmented Reality Devices, Virtual Reality Headsets End User: Consumer Electronics, Military & Defense, Healthcare, Automotive Technology: Micro LED, Active Matrix OLED, Passive Matrix OLED, Transparent OLED Size: 1 inch, 2 inch, 3 inch, 4 inch |
| Companies Covered | BOE Technology Group, eMagin Corporation, Sony Corporation, Seiko Epson Corporation, Himax Technologies, Samsung Display, Kopin Corporation, WiseChip Semiconductor, LG Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Microdisplay Market Strategic Shifts & Innovations
Foveated rendering architectures and direct-patterned OLED deposition are compressing power budgets and expanding field-of-view simultaneously, reshaping competitive requirements across defense and medical verticals.
Direct-patterned OLED technology eliminates color filter losses by depositing red, green, and blue organic emitters through precision shadow masking onto CMOS backplanes. Thermal weapon sight manufacturers in the United States are adopting this architecture to achieve 10,000+ candela-per-square-meter luminance for daylight-readable reticles. This approach is converging with waveguide combiner optics to enable 80-degree diagonal fields-of-view in sub-100-gram headborne packages.
The EU AI Act's high-risk system classification for medical diagnostic devices is mandating algorithmic transparency and post-market surveillance for AR-guided surgical systems. European Medicines Agency coordination with notified bodies is extending conformity assessment durations by 8-12 months for AI-integrated displays. German and French healthcare procurement agencies are responding by pre-qualifying vendors with established MDR technical documentation, concentrating contract awards among incumbent suppliers.
Defense acquisition offices are compressing supplier qualification cycles through Other Transaction Authority contracting vehicles that bypass traditional FAR-based procurement. The US Army's IVAS program and similar NATO soldier modernization initiatives are disintermediating prime contractors to source microdisplays directly from qualified foundries. This pattern is most visible in the United States, where the Defense Innovation Unit maintains rapid prototyping pathways for non-traditional vendors meeting MIL-STD-810H environmental baselines.
OLED Microdisplay Market Segmentation
OLED microdisplay architectures diverge sharply across application requirements, with military systems demanding ITAR-qualified ruggedization while consumer AR prioritizes weight minimization. Each segmentation dimension reveals distinct procurement patterns, qualification timelines, and margin structures that reshape supplier positioning.
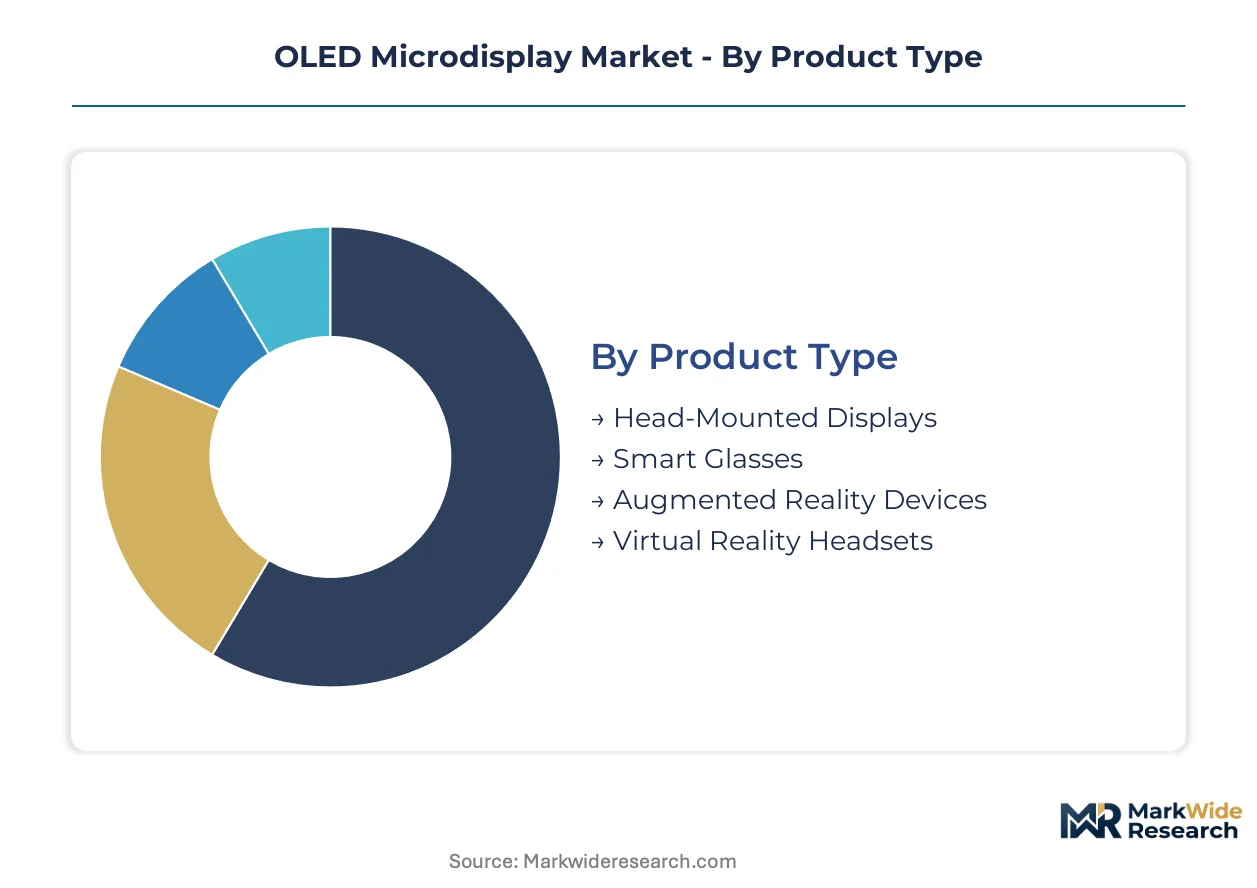
Product Type:
Standardization dominates high-volume consumer segments while defense and medical applications require bespoke optical integration.
- Head-Mounted Displays:Silicon-backplane-driven emissive devices with sub-10 millisecond refresh rates anchor fighter pilot helmet-mounted sighting systems. NATO-aligned defense ministries in the United States, Germany, and the United Kingdom sustain procurement volumes through avionics modernization programs constrained by MIL-STD-810H qualification timelines.
- Augmented Reality Devices:Waveguide combiner optics paired with direct-patterned OLED deposition enable 80-degree diagonal fields-of-view in sub-100-gram packages. German automotive and precision manufacturing clusters in Baden-Württemberg pilot assisted-reality headsets for assembly guidance, representing an underpenetrated volume pool outside defense.
- Smart Glasses:Compact optical see-through architectures target enterprise logistics and remote assistance workflows with reduced field-of-view specifications.
- Virtual Reality Headsets:Larger form factors accommodate higher luminance requirements for immersive entertainment and training simulation environments.
Leading the category by volume: Head-Mounted Displays. Expanding most quickly: Augmented Reality Devices.
End User:
Customer procurement authority fragments across federal acquisition offices, hospital procurement committees, and consumer electronics retail channels.
- Military & Defense:ITAR compliance and MIL-STD-810 environmental testing restrict supplier eligibility to domestic or allied-country manufacturers. The US Department of Defense mandates these standards for display components in weapon systems, with the US Army's IVAS program disintermediating prime contractors to source directly from qualified foundries.
- Healthcare:EU AI Act high-risk system classification and CE-MDR dual compliance extend conformity assessment durations for AR-guided surgical systems. European Medicines Agency coordination with notified bodies concentrates contract awards among incumbent suppliers with established technical documentation.
- Consumer Electronics:Price-sensitive volume procurement through retail channels prioritizes pixel density-per-dollar metrics over environmental ruggedization.
- Automotive:Prototype transparent OLED applications in head-up displays remain niche with limited near-term scale.
Fastest share gain: Healthcare. Volume anchor: Military & Defense.
Technology:
Process maturity and deposition equipment availability determine competitive entry barriers across each architecture.
- Active Matrix OLED:CMOS wafer lithography enables 4,000+ pixels per inch in sub-inch diagonal formats with superior refresh rates and uniform luminance control. This architecture dominates production volumes as it displaces legacy LCD configurations in near-eye applications.
- Micro LED:Gallium nitride maturation remains three to five years from cost parity, opening a window for OLED microdisplay vendors to establish architectural lock-in.
- Passive Matrix OLED:Simpler drive electronics suit cost-constrained applications with lower resolution requirements.
- Transparent OLED:Architectural and automotive prototype deployments exploit see-through characteristics for spatial computing interfaces.
Technology leader by shipment volume: Active Matrix OLED. Steepest expansion trajectory: Micro LED.
Size:
Optical system form factor and eyebox geometry dictate diagonal dimension selection across end-use categories.
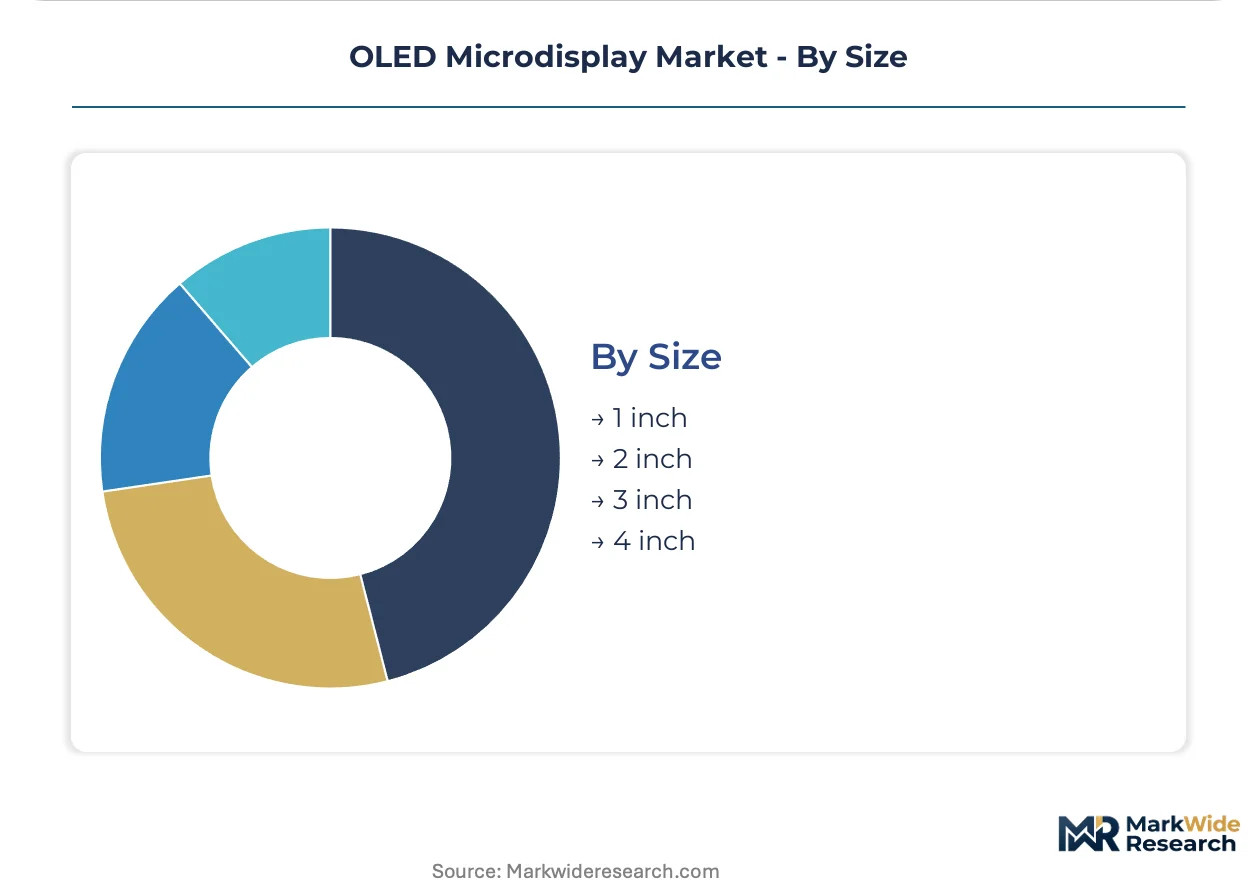
- 1 inch:Sub-inch formats concentrate pixel density for surgical navigation and thermal weapon sight reticles requiring daylight-readable luminance.
- 2 inch:Balanced field-of-view and optical stack thickness for enterprise AR headsets.
- 3 inch:Expanded eyebox accommodation for immersive VR training simulations.
- 4 inch:Largest diagonal formats serve specialized projection and near-eye display hybrid systems.
Volume concentration: 1 inch formats. Fastest-growing dimension: 2 inch formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian fabrication clusters while consumption splits between Western defense procurement and Chinese domestic equipment programs. The United States, China, Germany, Japan, and South Korea host the dominant supply bases and end-use equipment manufacturers.
United States
Defense procurement of helmet-mounted sighting systems for fighter and rotary-wing platforms sustains demand through the US Army's IVAS program and similar soldier modernization initiatives. The Department of Defense mandates ITAR compliance and MIL-STD-810H environmental testing, restricting supplier eligibility to domestic or allied-country manufacturers. Greater Boston and Texas host defense electronics clusters where prime contractors disintermediate to source microdisplays directly from qualified foundries.
China
Domestic equipment manufacturers for AR headsets and thermal weapon sights drive procurement volumes as consumer and industrial applications scale. MIIT channels capital into semiconductor display equipment localization through subsidy programs, reducing import dependency for OLED deposition tools. The Yangtze River Delta fabrication corridor concentrates backplane wafer processing and organic emitter deposition capacity.
Germany
Automotive and precision manufacturing clusters in Baden-Württemberg and Bavaria pilot OLED-based assisted-reality headsets for assembly guidance, representing an underpenetrated volume pool outside defense. The EU AI Act and CE-MDR dual compliance requirements shape certification pathways for diagnostic imaging wearables. Stuttgart and Munich anchor industrial AR deployment programs among automotive OEMs and tier-one suppliers.
Japan
High-resolution microdisplay supply for military-qualified systems flows through semiconductor divisions with established CMOS backplane expertise. METI promotes domestic supply chain resilience for critical display components through technology roadmaps and research consortia. The Kanto region concentrates precision shadow masking equipment manufacturing and organic emitter material processing capabilities.
South Korea
Display panel conglomerates leverage existing OLED television and smartphone fabrication expertise to enter microdisplay segments. The national industrial policy prioritizes advanced display technology leadership through R&D tax incentives and equipment depreciation allowances. The Seoul Capital Area hosts deposition tool manufacturers and rare metal precursor chemical processors serving global emitter material supply chains.
OLED Microdisplay Market Key Industry Players
Top-tier vendors anchor defense-qualified supply chains, while mid-tier specialists compete on deposition technology differentiation and regional market access. The vendor base stratifies across ITAR-compliant domestic suppliers, East Asian scale fabricators, and niche technology licensors. Three archetypes dominate: semiconductor-integrated conglomerates with captive backplane capacity, pure-play microdisplay foundries with direct-patterning expertise, and optical systems integrators outsourcing display procurement. Competitive moves concentrate on strategic partnerships for waveguide combiner integration and qualification timeline compression through Other Transaction Authority contracting vehicles.
Among East Asian scale fabricators, BOE Technology Group and Samsung Display exemplify the vertical integration archetype spanning CMOS wafer processing through final module assembly. Sony Corporation occupies a distinctive position as a technology originator with sustained presence in military-qualified system supply. These three entities represent contrasting strategic postures: Chinese domestic market prioritization, Korean consumer electronics leverage, and Japanese defense technology continuity.
| Leading Market Players |
|---|
| BOE Technology Group |
| eMagin Corporation |
| Sony Corporation |
| Seiko Epson Corporation |
| Himax Technologies |
| Samsung Display |
| Kopin Corporation |
| WiseChip Semiconductor |
| LG Display |
| Others |
Cost & Logistics Intelligence
Iridium-based phosphorescent dopants flow from South Korean and Japanese chemical processors through deposition tool manufacturers to microdisplay foundries, concentrating cost volatility in military-qualified supply tiers while consumer segments absorb standard-grade emitter pricing.
Pricing Analysis
Cost-down pressure on ITAR-compliant display tiers accelerates because organic emitter material volatility inflates bill-of-materials unpredictability. Three-tier pricing structure across ITAR-qualified, industrial-grade, and consumer tiers separates certification investment levels. Price differentiation centers on MIL-STD-810H environmental qualification and pixel density specifications. Defense procurement offices exhibit lowest price sensitivity due to sole-source mandates, while consumer electronics retail channels prioritize pixel density-per-dollar metrics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense buyer demand through qualified foundry relationships, bypassing traditional distribution layers. Supply concentrates in the United States, China, and Japan for CMOS backplane wafer processing and precision shadow masking equipment. Raw material dependencies span iridium precursors, rare metal dopants, and high-purity organic emitters. Single-source vulnerability concentrates in South Korean and Japanese chemical processors for phosphorescent materials. Distribution runs through prime contractor disintermediation pathways accelerated by Other Transaction Authority contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active Matrix OLED technology is displacing legacy LCD architectures in near-eye applications, compressing refresh rates and eliminating backlight assemblies to reshape procurement requirements across defense and medical verticals.
For Market Incumbents: Acquire direct-patterned OLED deposition expertise to defend against gallium nitride micro-LED substitution threats. Expand captive backplane capacity in allied-country fabrication clusters to compress ITAR qualification timelines. Deepen waveguide combiner partnerships to lock in optical system architecture for next-generation soldier modernization programs.
For New Entrants and Emerging Players: Foveated rendering algorithm integration offers entry into German industrial AR deployment programs among automotive OEMs. Target Baden-Württemberg and Bavaria manufacturing clusters with assisted-reality headset pilots for assembly guidance workflows. Pursue EU AI Act CE-MDR dual compliance pathways to concentrate contract awards among pre-qualified diagnostic imaging wearable suppliers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play microdisplay foundries with established MIL-STD-810H environmental baselines in Greater Boston and Texas defense electronics clusters. Long-term viability hinges on architectural lock-in before gallium nitride micro-LED cost parity emerges. Monitor Other Transaction Authority contracting volume as inflection indicator for rapid qualification pathway expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Patterned OLED Deposition Scale-Up | Enables 10,000+ candela-per-square-meter luminance for daylight-readable thermal weapon sight reticles. |
| ITAR-Compliant Foundry Certification | Unlocks US Department of Defense helmet-mounted sighting system procurement through MIL-STD-810H qualification. |
| Waveguide Combiner Partnership | Expands field-of-view to 80-degree diagonal in sub-100-gram headborne packages for soldier modernization. |
| EU AI Act CE-MDR Dual Compliance | Concentrates AR-guided surgical system contract awards among incumbent suppliers with established technical documentation. |
| Silicon Backplane Lithography Advancement | Unlocks 4,000+ pixels per inch for photorealistic surgical navigation and industrial inspection imagery. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with defense procurement officers, microdisplay foundry engineers, thermal weapon sight manufacturers, and medical device regulatory affairs leads combined with secondary validation from FDA 510(k) submissions, EMA MDR technical documentation, and US Army IVAS program disclosures. Bottom-up wafer throughput estimates and top-down defense budget allocation triangulation cross-checked volume assumptions.
Reconciliation of shipment data, foundry capacity utilization, and end-use equipment bill-of-materials informed the analytical framework across the analysis window. Segmentation dimensions spanned product architecture, end-user procurement authority, deposition technology maturity, and diagonal format specification. CAGRs derived from wafer-level yield improvement trajectories and defense modernization program funding profiles. Forecast inputs incorporated organic emitter material cost curves and gallium nitride micro-LED maturation timelines.
Several conditions sit outside the modeled scope, including speculative micro-LED cost parity acceleration, export control regime expansions beyond current ITAR baselines, and automotive transparent OLED volume scaling. Forecasts reflect documented assumptions regarding defense procurement continuity and cleanroom protocol standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Display Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Projector Screen Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Global Portable Monitor Market
Display Technologies
AMOLED Display Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Low Power Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Display Port Market
Display Technologies
Smartphone Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Global UHD Display Market
Display Technologies
Electronic Display Market