
 Wireless Display Market | 2026-2036
Wireless Display Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Display Market Intelligence
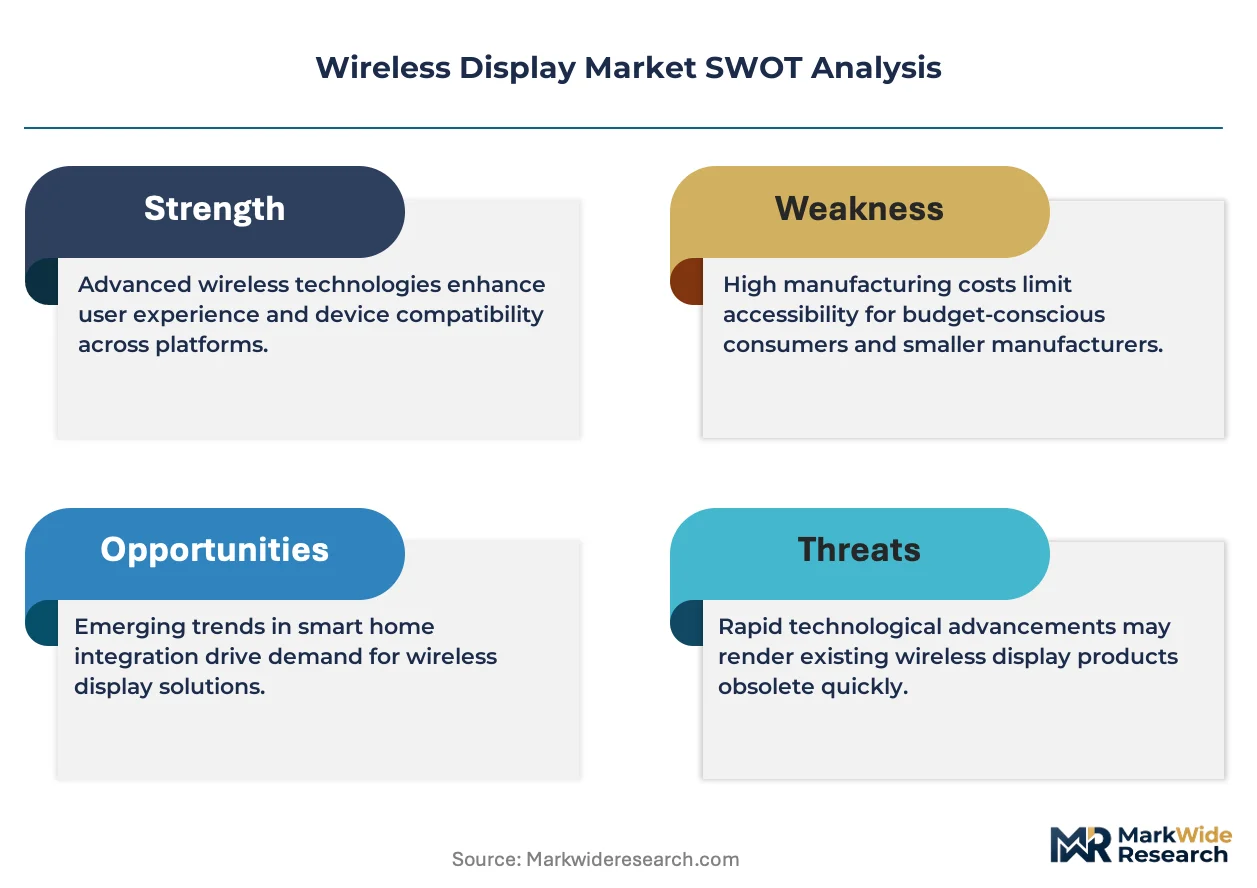
The European Union's Green Deal, with its focus on reducing electronic waste, is shifting enterprise procurement towards streamlined, hardware-minimal solutions. Microsoft leverages its deep integration with the Windows operating system to capture the corporate presentation market. Google competes through the widespread adoption of its Chromecast ecosystem in home entertainment. Intel Corporation provides foundational WiDi technology, supporting a broad base of device manufacturers.
Wireless display technology enables the streaming of audio and video content from a source device to a display screen without physical cables. It operates over local area wireless networks using protocols such as Wi-Fi Direct, which establishes peer-to-peer connections. Among product types, proprietary protocols like Apple AirPlay and Google Chromecast maintain strong positions within their device ecosystems. The corporate presentations application segment shows significant expansion, driven by demand for collaborative meeting environments.
Compliance with radio frequency regulations from bodies like the US Federal Communications Commission (FCC) and China's MIIT is mandatory for market access. In Europe, CE marking signifies adherence to essential health and safety requirements for electronic devices. Stakeholders must now decide whether to prioritize proprietary, ecosystem-locked standards or to champion open, interoperable protocols for broader device compatibility.
Market Dynamics
The market's central dynamic is the conflict between proprietary standards, which create ecosystem lock-in, and the enterprise demand for open, interoperable protocols. This tension dictates technology roadmaps and influences procurement decisions in corporate and consumer segments.
Growth Catalysts
- 5G Network Deployment:The rollout of 5G infrastructure enhances streaming quality and reduces latency. This makes wireless displays more reliable for high-bandwidth applications in corporate and public settings, supporting smoother 4K video and interactive content.
- Corporate Office Demand:A persistent need for seamless presentation and collaboration tools in modern meeting rooms fuels adoption. This is particularly strong in high-tech business districts where collaborative workflows are standard practice.
- EU Green Deal:This policy's focus on reducing electronic waste encourages hardware-minimal solutions. It favors software-driven wireless display technology over cabled setups that require more physical hardware and accessories.
Market Restraints
- Performance Instability:In environments with high Wi-Fi congestion, such as dense office buildings or public venues, signal interference can degrade performance. This creates a reliability gap compared to dedicated wired connections for mission-critical applications.
- Substitution from Smart TVs:The native casting capabilities built into modern smart TV platforms can substitute for dedicated wireless display adapters. This is a significant restraint in home entertainment and small office environments where basic functionality suffices.
- Fragmented Regulatory Compliance:Navigating divergent radio frequency regulations and certification processes from bodies like the US FCC and China's MIIT adds cost and time-to-market for manufacturers targeting multiple international markets.
Strategic Opportunities
- Digital Signage Applications:The transition from static displays to dynamic, centrally managed content streams offers a significant growth vector. Wireless technology simplifies deployment and content updates in retail, transportation, and hospitality venues.
- Integration with IoT:Linking wireless displays to smart building systems and IoT sensors enables context-aware information delivery. This can enhance user experiences in corporate campuses, hospitals, and smart city projects.
- Expansion in Education:Growing adoption of digital learning tools creates an opportunity for wireless displays in classrooms and lecture halls. This allows educators and students to share content from various devices without physical tethers.
Industry Challenges
- Interoperability Fragmentation:The lack of a universal standard across platforms like Miracast, Apple AirPlay, and Google Chromecast creates user confusion. It also requires IT departments to support multiple protocols, complicating enterprise-wide deployment and support.
- Network Security Vulnerabilities:As connected devices, wireless displays present a potential attack surface on corporate networks. This requires robust security protocols and continuous firmware updates to defend against unauthorized access and data breaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Display Market |
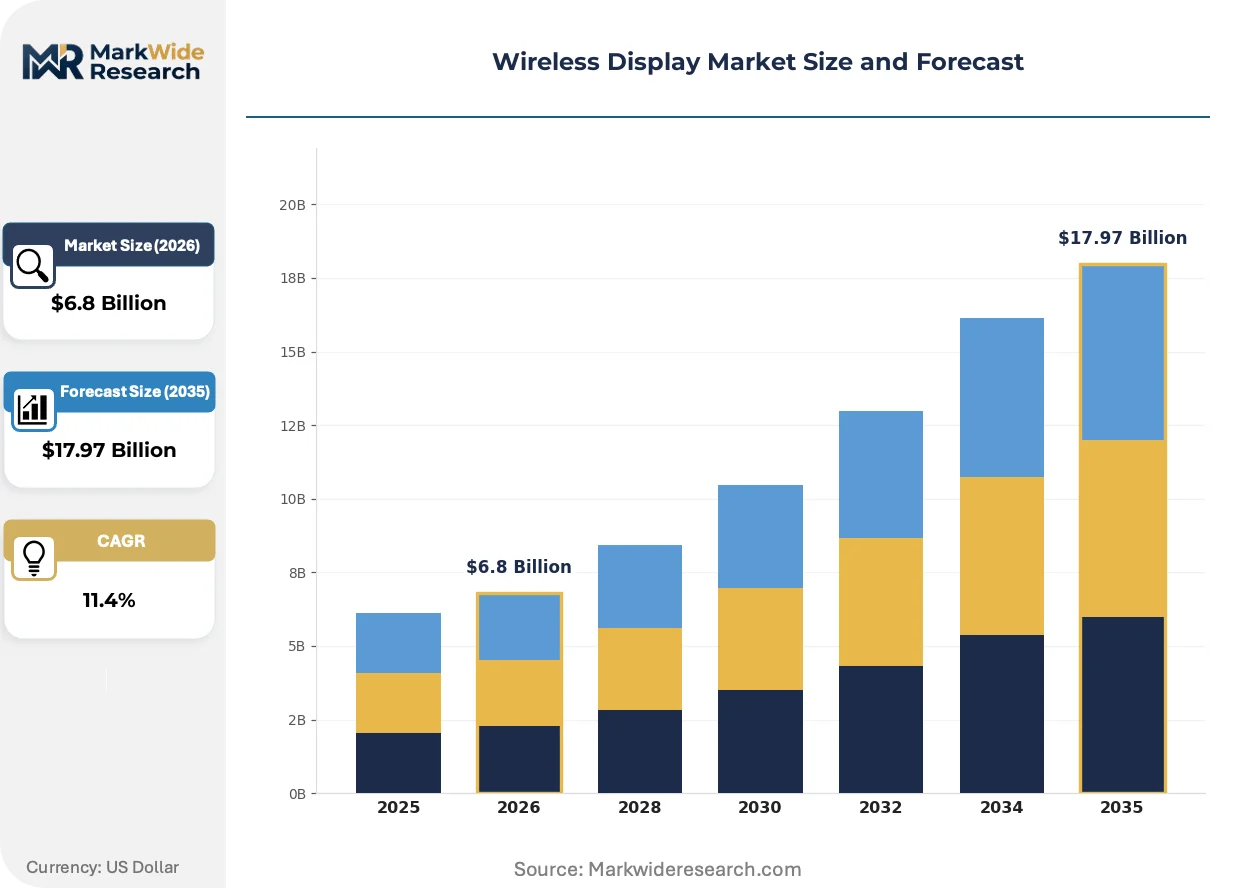
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miracast Devices, Chromecast, Apple AirPlay, WiDi, DLNA Players, Others Technology: Wi-Fi Direct, Bluetooth, Infrared, 5G, NFC, Ultra-Wideband Application: Home Entertainment, Corporate Presentations, Education Sector, Digital Signage, Gaming Consoles, Event Broadcasting End User: Consumer Electronics, Educational Institutions, Corporate Offices, Hospitality Industry, Event Management, Media Production |
| Companies Covered | Apple Inc., Google LLC, Microsoft Corporation, Amazon.com, Inc., Intel Corporation, Samsung Electronics Co., Ltd., Roku, Inc., NETGEAR, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Display Market Strategic Shifts & Innovations
The evolution of wireless display technology is now defined by software-centric innovations and the integration of higher-level protocols. This moves the competitive focus from basic connectivity toward intelligent features and seamless ecosystem integration.
Wi-Fi 6 and Wi-Fi 6E technologies provide higher throughput and lower latency through features like OFDMA, specifically designed for dense device environments. Corporate IT and pro-AV integrators are rapidly adopting these standards for new deployments to guarantee performance. This advancement is consolidating the market's performance tiers, making high-quality, low-latency 4K streaming the new baseline expectation.
Europe's Cyber Resilience Act (CRA) imposes strict cybersecurity rules for products with digital elements, including wireless displays. This forces manufacturers to implement "security-by-design" and provide ongoing vulnerability management. The consumer and SMB segments are most affected, as enterprise-grade security becomes a baseline requirement.
Enterprise buyers are moving from single-function hardware purchases toward subscription-based "meeting room as a service" (MRaaS) models. This disrupts the traditional channel of one-time sales, favoring managed service providers. The trend is most visible in North American and European corporate verticals seeking to standardize user experiences.
Wireless Display Market Segmentation
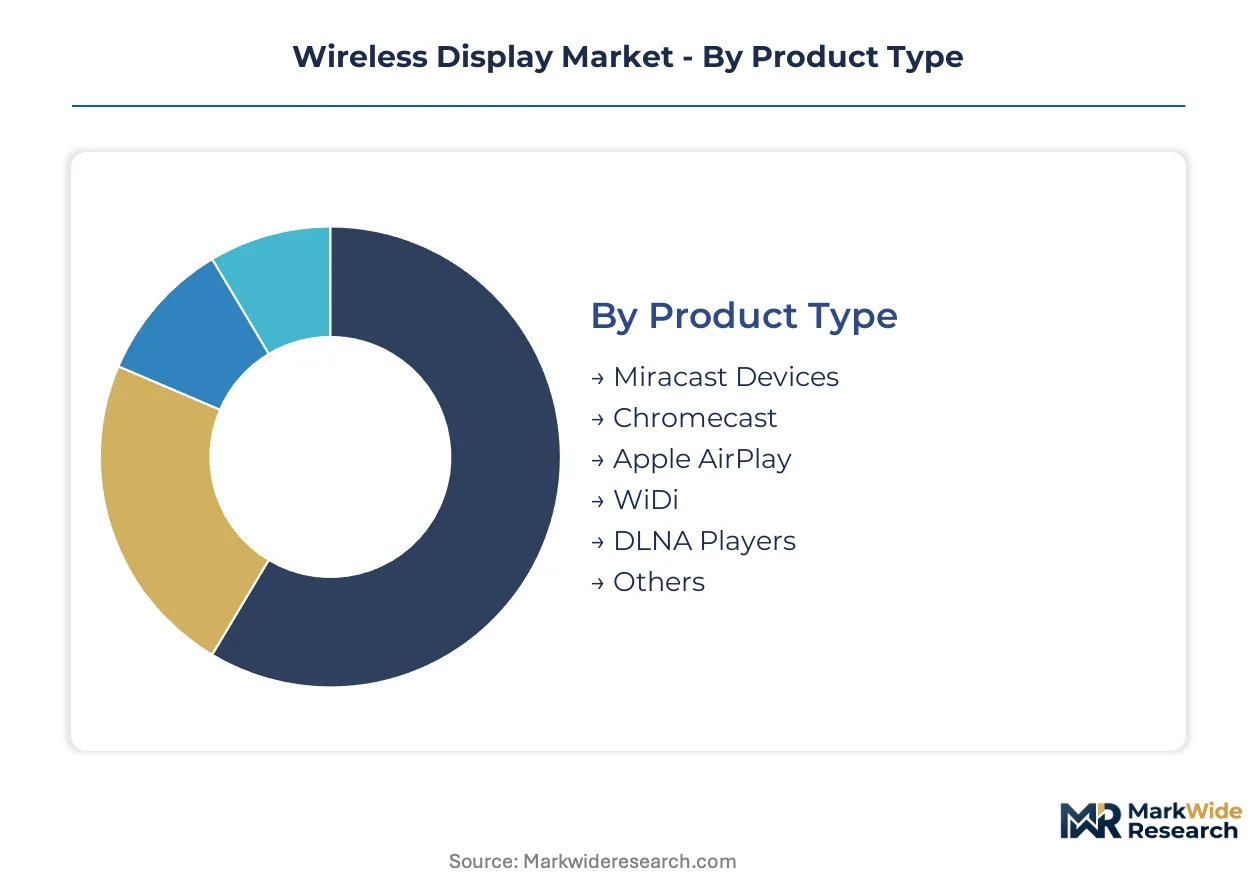
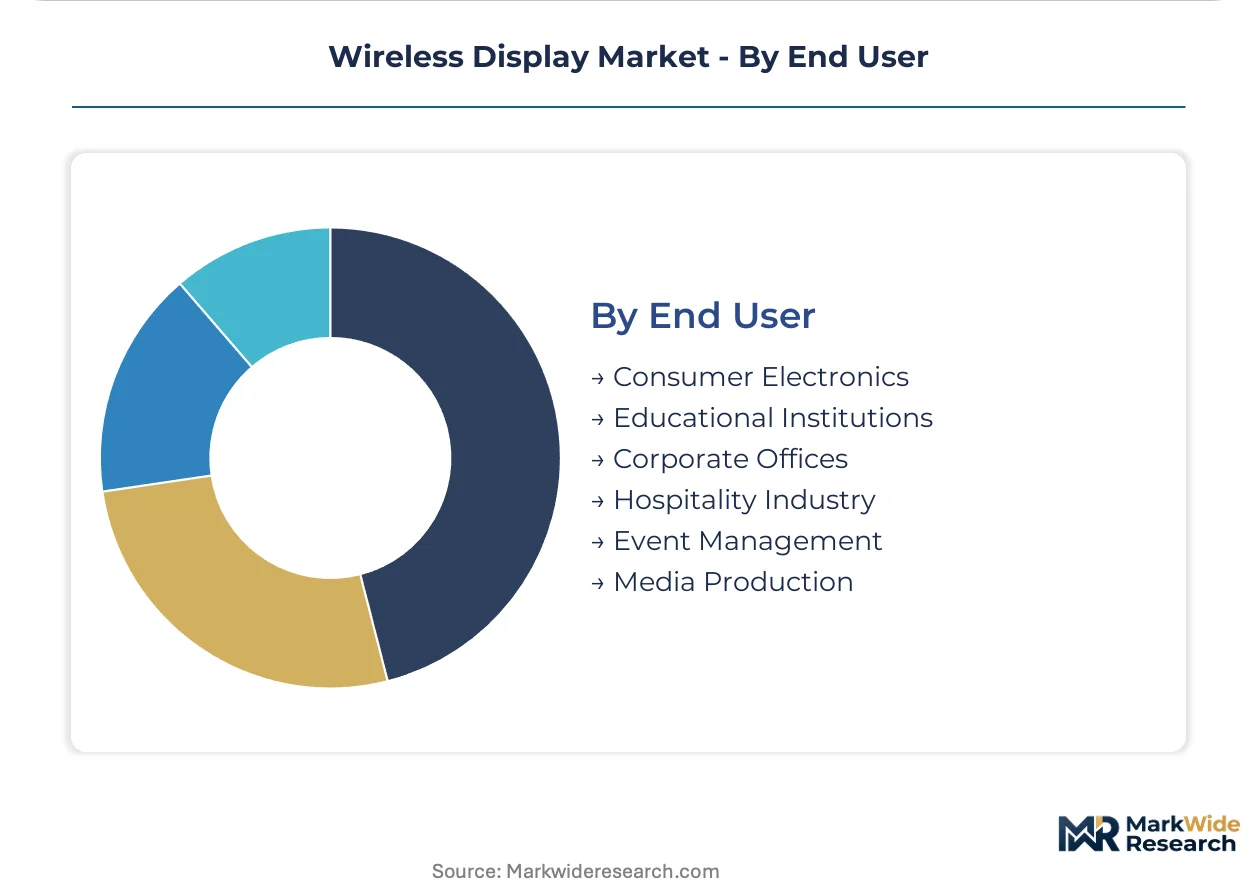
The Wireless Display Market segments reveal distinct patterns in technology adoption and end-user preferences. Understanding these divisions helps stakeholders tailor products and services to specific market needs. Each segment reflects unique technological requirements and deployment challenges across various environments.
Product Type:
The customization-versus-standardization spectrum defines product type offerings in the wireless display market.
- Miracast Devices:These devices employ an open standard for screen mirroring, enabling direct peer-to-peer connections between compatible devices. Demand concentrates in corporate offices, where cross-platform compatibility simplifies presentation setups.
- Chromecast:Google's proprietary technology facilitates streaming content from mobile devices or web browsers to a display. Home entertainment remains a significant demand driver for Chromecast, particularly in North America and Europe.
- Apple AirPlay:This proprietary protocol enables seamless content streaming within the Apple ecosystem.
- WiDi:Intel Wireless Display technology provides a foundational platform for wireless video transmission.
- DLNA Players:Digital Living Network Alliance players allow media sharing across connected home devices.
- Others:This category includes various niche or emerging proprietary solutions.
Most installed capacity flows through Chromecast. Expansion is steepest in Miracast Devices.
Technology:
Performance and reliability considerations primarily differentiate the various wireless display technologies.
- Wi-Fi Direct:This technology establishes direct peer-to-peer connections without requiring a router, offering flexibility for ad-hoc presentations. Corporate presentations rely heavily on Wi-Fi Direct for quick, secure connections in meeting rooms.
- 5G:The fifth generation of cellular technology provides high bandwidth and ultra-low latency, enhancing the reliability of wireless displays for real-time applications. Digital signage in public venues increasingly leverages 5G for dynamic content updates.
- Bluetooth:This short-range wireless technology is suitable for basic audio streaming and device pairing.
- Infrared:Infrared technology offers line-of-sight communication, primarily for remote control functions.
- NFC:Near Field Communication facilitates quick, short-range pairing for wireless display setups.
- Ultra-Wideband:UWB technology offers high bandwidth for short distances, providing precise location capabilities.
Adoption patterns are primarily dictated by latency requirements. High-bandwidth applications increasingly demand 5G capabilities.
Application:
The scale of deployment and user interaction models shape demand across different wireless display applications.
- Corporate Presentations:This segment involves sharing content from laptops or mobile devices to large screens in meeting rooms. Demand in corporate offices drives this segment, particularly in technology hubs like South Korea.
- Home Entertainment:Consumers use wireless displays to stream movies, photos, and music from personal devices to smart televisions. This application sees widespread adoption in residential settings across Europe and North America.
- Education Sector:Wireless displays facilitate interactive learning and content sharing in classrooms.
- Digital Signage:This application involves displaying dynamic content on screens in public or commercial spaces.
- Gaming Consoles:Wireless display technology enables screen mirroring or extended display for gaming.
- Event Broadcasting:This segment utilizes wireless displays for live content sharing during conferences or shows.
High-value enterprise applications drive significant revenue. Consumer-facing solutions account for substantial volume.
End User:
Organizational scale and specific operational requirements influence wireless display adoption among various end users.
- Corporate Offices:Businesses require robust, secure, and interoperable wireless display solutions for collaborative environments. The demand for seamless meeting room technology in major business districts remains strong.
- Consumer Electronics:Individual users integrate wireless display capabilities into their home entertainment systems and personal devices. The adoption rate among consumers for streaming content to smart TVs continues to expand.
- Educational Institutions:Schools and universities employ wireless displays for interactive teaching and student collaboration.
- Hospitality Industry:Hotels and resorts use wireless displays for guest entertainment and informational purposes.
- Event Management:Organizers utilize wireless displays for presentations and content sharing during events.
- Media Production:Production houses employ wireless displays for content review and collaborative editing.
Established enterprise users remain the largest revenue contributors. The consumer segment offers substantial volume opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless display technology scaled significantly in high-tech economies, particularly within Asia, where early infrastructure investments fostered rapid adoption. South Korea emerged as a foundational market, driven by its advanced digital landscape and a strong corporate demand for collaborative tools. This initial growth established benchmarks for subsequent global expansion.
South Korea
Demand for advanced presentation tools in corporate offices drives wireless display adoption. The national regulator, MFDS, ensures product safety and compliance for electronic devices. Seoul's Gangnam district, a major business hub, shows widespread implementation of wireless display solutions in modern meeting environments.
United States
Corporate offices persistently seek seamless presentation and collaboration tools, fueling market expansion. The US Federal Communications Commission (FCC) regulates radio frequency devices, ensuring compliance for market access. Silicon Valley, California, demonstrates high demand for wireless displays in its numerous tech campuses and startups.
Germany
Enterprise procurement shifts towards hardware-minimal solutions, aligning with the EU Green Deal's objectives. CE marking signifies adherence to essential health and safety requirements for electronic devices within the European market. Munich, a major industrial center, integrates wireless display technology into advanced manufacturing facilities and corporate headquarters.
China
The significant rollout of 5G networks enhances streaming quality and reduces latency for wireless displays. China's Ministry of Industry and Information Technology (MIIT) mandates specific radio frequency regulations for all electronic devices. Shenzhen, a global manufacturing and technology hub, sees widespread adoption in its numerous corporate offices and digital signage applications.
Japan
High-bandwidth applications increasingly demand 5G capabilities, improving wireless display reliability for real-time uses. METI supports innovation in digital technologies, influencing procurement decisions for advanced display solutions. Tokyo's business districts, including Marunouchi, leverage wireless displays for collaborative workspaces and public information systems.
Wireless Display Market Key Industry Players
Premium-margin players sit above commodity-margin players across the wireless display value chain, segmenting the market by ecosystem integration and proprietary technology offerings. The competitive landscape features a tiered structure, with established technology giants dominating the proprietary ecosystem segments through deep software-hardware integration. Strategic archetypes include platform providers, specialized hardware manufacturers, and enterprise software solution specialists. Companies frequently engage in strategic partnerships to expand device compatibility and continuously invest in R&D for enhanced streaming protocols and security features.
Within the platform provider tier, Apple Inc. and Google LLC represent key players driving ecosystem-locked standards through AirPlay and Chromecast, respectively. These technology giants anchor significant market share by leveraging their extensive device ecosystems and brand loyalty. Microsoft Corporation also occupies a position in the corporate presentation market, deeply integrating its solutions with the Windows operating system. Intel Corporation, a foundational technology provider, supports a broad base of device manufacturers with its WiDi technology, exemplifying the hardware-centric approach within the broader competitive landscape.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| Amazon.com, Inc. |
| Intel Corporation |
| Samsung Electronics Co., Ltd. |
| Roku, Inc. |
| NETGEAR |
| LG Electronics |
| Others |
Cost & Logistics Intelligence
Vertically integrated technology giants, through their substantial R&D investments, exert significant influence over both component supply and end-product pricing discipline in the wireless display market.
Pricing Analysis
Tiered subscription and hardware licensing models define pricing in the wireless display market. Price differentiation stems from brand premium, ecosystem integration capabilities, and the performance tier offered, such as 4K streaming. Pricing pressure intensifies for basic functionality due to native casting features in smart TVs. Corporate offices exhibit lower price sensitivity for robust, secure solutions, while home entertainment consumers remain highly price-sensitive for basic devices.
Supply Chain Analysis
Wireless display component supply relies heavily on semiconductor manufacturing in Taiwan and advanced display panel production in South Korea. Key input dependencies include specialized integrated circuits, Wi-Fi modules, and high-resolution display components. Geopolitical tensions affecting semiconductor trade represent a significant structural risk for the entire supply chain. Distribution runs through a dual channel of direct-to-consumer sales for proprietary systems and enterprise solution providers for corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wireless Display Market functions as a stable compounder, driven by the persistent corporate demand for seamless presentation and collaboration tools.
For Market Incumbents:
Anticipate the need for continuous investment in security-by-design to meet evolving regulatory standards like Europe's Cyber Resilience Act. Expand "meeting room as a service" offerings to capture recurring revenue streams and standardize user experiences. Focus R&D on enhancing streaming protocols and improving interoperability to mitigate fragmentation threats. Deepen ecosystem integration to maintain competitive positioning against emerging platform alternatives.
For New Entrants and Emerging Players:
Begin with a focus on underpenetrated segments like digital signage or the education sector, where demand for flexible content sharing is high. Target small and medium-sized businesses with cost-effective, open-standard solutions that simplify IT management. A strong go-to-market angle involves offering robust security features and cross-platform compatibility as core differentiators. Prioritize solutions that reduce hardware complexity and align with green procurement policies.
For Investors and Strategic Acquirers:
Specialized technology firms are the most active acquirers in this space, seeking to consolidate intellectual property and expand service portfolios. The market demonstrates long-term viability, supported by the ongoing digital transformation of workplaces and public venues. Identify acquisition targets with strong foundational WiDi technology or innovative software-centric solutions. The emergence of a dominant open, interoperable standard will serve as a key signal to watch for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Wi-Fi 6E Devices | New devices leverage advanced network capabilities for enhanced corporate presentation reliability. |
| Platform Integration with IoT | Linking wireless displays to smart building systems improves context-aware information delivery. |
| Strategic Partnership: Pro-AV Integrators | Collaborations with integrators expand market reach into complex enterprise deployment projects. |
| Acquisition of Specialist Firmware Vendor | Acquiring firmware expertise strengthens device security and enables rapid feature development. |
| Geographic Expansion: Southeast Asian Tech Hubs | Expanding into new tech-dense regions captures emerging demand for collaborative solutions. |
Research Approach
Multiple input streams — industry reports, regulatory filings, and expert interviews — were reconciled to construct a comprehensive market view. Primary research involved discussions with CTOs, IT procurement officers, product managers, and pro-AV integrators. Secondary validation drew from SEC filings, government technology reports, and academic research, triangulating data for accuracy. Both bottom-up and top-down approaches informed market sizing and segmentation.
Historical data cross-referenced with expert panel input formed the basis of the forecast framework. Segmentation dimensions modeled included product type, technology, application, end user, and regional adoption patterns across the analysis window. Compound annual growth rates were derived from a robust growth model. Key industry-specific forecast inputs included 5G network rollout rates and corporate office renovation cycles.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or rapid shifts in consumer electronics trends. Forecasts reflect assumptions documented through extensive research and analysis. Major supply chain disruptions or new regulatory mandates impacting wireless spectrum represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Commercial Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Display Port Market
Display Technologies
Touch Screen Film Market
Display Technologies
3LCD Projector Market
Display Technologies
United States Microdisplay Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Global Display Controllers Market
Display Technologies
Collaboration Display Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
PMOLED Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Middle East and Africa Industrial Display Market