
 Microdisplay Market | 2026-2036
Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
Microdisplay Market Analysis
Software-defined display calibration is broadening what microdisplay vendors monetize beyond hardware shipments. Sony Group Corporation leverages its CMOS backplane expertise to sustain premium positioning in near-eye applications. Kopin Corporation anchors defense contracts with ruggedized OLED modules for thermal weapon sights.
A microdisplay is a compact screen typically measuring under one inch diagonally, fabricated on silicon wafers using semiconductor lithography to achieve pixel densities exceeding 3,000 pixels per inch. These devices serve as image sources for optical magnification systems in headsets, projection engines, and compact viewfinders. Micro OLED leads in premium near-eye applications where luminance and contrast ratios determine user immersion, while LCoS retains cost advantages in pico-projection and structured-light sensing. Head-Up Display applications in automotive are attracting fresh engineering investment as windshield-integrated AR becomes a differentiator for luxury vehicle platforms.
FDA scrutiny of augmented-reality surgical overlays shapes healthcare validation pathways for Himax Technologies and eMagin, while EU RoHS and REACH constraints restrict hazardous substances in phosphor and organic emitter chemistries. The FCC governs radio-frequency emissions from wireless-connected AR headsets that embed microdisplays. Stakeholders must track how CE marking under the EU AI Act classifies autonomous visual systems before committing regional product roadmaps.
Market Dynamics
Silicon backplane lithography now determines competitive moats as pixel density thresholds exceed 3,000 PPI, forcing foundry partnerships and mask-set investments that favor vertically integrated semiconductor houses over fabless display designers.
Growth Catalysts
- EU Ecodesign mandates:Emissive OLED microdisplays bypass mercury-containing backlights, qualifying for CE marking under RoHS exemptions that liquid-crystal alternatives cannot match.
- Automotive HUD retrofit demand:Tier-1 suppliers embed waveguide combiners in windshield AR systems for luxury OEM platforms, creating pull-through for high-brightness LCoS engines.
- Defense procurement centralization:Thermal weapon sight programs in North America and Asia-Pacific specify ruggedized OLED modules with ITAR-compliant supply chains.
Market Restraints
- Compound semiconductor input volatility:Indium phosphide and gallium arsenide wafer prices fluctuate with 5G base station demand, squeezing Micro LED epitaxy margins.
- East Asian foundry concentration:TSMC and Samsung Foundry control 90nm and 40nm CMOS backplane capacity, creating single-source risk for fabless microdisplay vendors.
- Organic emitter lifetime limits:Blue OLED materials degrade below 10,000 hours at 1,000 nits, constraining always-on AR headset architectures.
Strategic Opportunities
- India PLI scheme for electronics:Display manufacturing incentives under the Modified Programme for Semiconductors attract assembly investment for consumer VR headsets.
- EU AI Act visual system classification:Autonomous surgical overlays face new validation pathways, creating first-mover advantage for FDA-cleared vendors seeking CE marking reciprocity.
- Micro LED + silicon photonics convergence:Heterogeneous integration of emitters with optical waveguides enables chip-scale LiDAR engines for automotive sensing.
Industry Challenges
- Backplane design talent scarcity:Mixed-signal CMOS architects with pixel-driver experience command premium compensation, constraining startup hiring pipelines.
- FDA 510(k) timeline compression:Augmented-reality surgical overlays require clinical validation studies that extend product launch cycles by 18-24 months.
- Legacy projector channel obsolescence:Distributor inventories of lamp-based pico-projectors block shelf space for solid-state LCoS replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microdisplay Market |
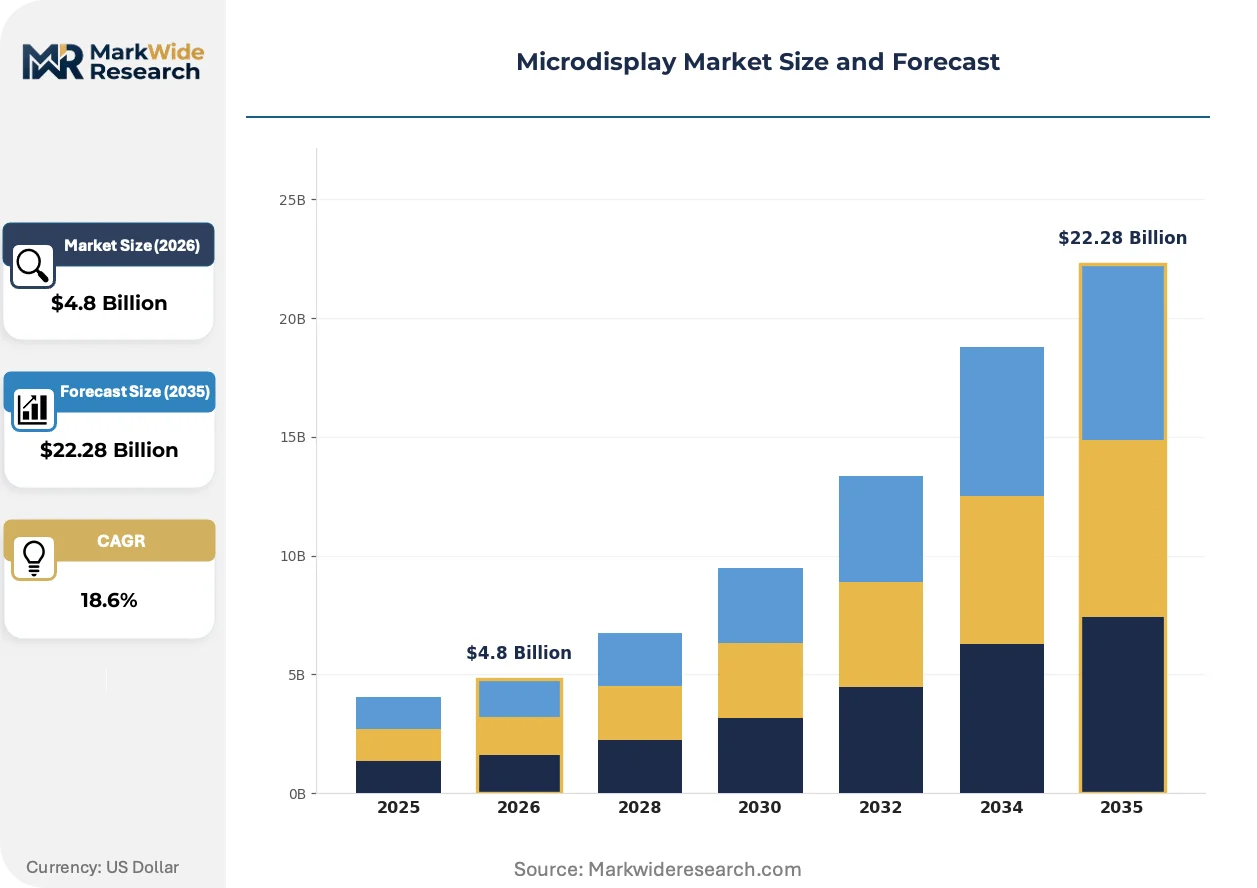
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro OLED, LCoS, DLP, LCD Application: Augmented Reality, Virtual Reality, Head-Up Display, Wearable Tech End User: Consumer Electronics, Automotive, Defense, Healthcare Technology: Reflective, Transmissive, Emissive, Hybrid |
| Companies Covered | Sony Group Corporation, Seiko Epson Corporation, Kopin Corporation, eMagin, SeeYA Technology, Himax Technologies, LG Display, BOE Technology Group, OLEDWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microdisplay Market Emerging Trajectories
Emissive display architectures are absorbing capital and engineering talent at the expense of transmissive alternatives, while regulatory fragmentation around autonomous visual systems forces parallel certification tracks.
Micro LED is absorbing foundry investment as epitaxy-on-silicon processes mature. Defense contractors now specify Micro LED engines for helmet-mounted cueing systems where sunlight readability exceeds 10,000 nits. This technology is absorbing market share from OLED in applications requiring extreme luminance without thermal runaway.
REACH restrictions on phosphor-activated quantum dots are tightening formulation options for color-converted Micro LED panels. ECHA substance evaluations now cover cadmium-free alternatives, pushing vendors toward indium phosphide cores. European medical imaging OEMs are responding by qualifying OLED-based surgical microscopes ahead of Micro LED readiness.
Defense procurement offices now mandate ITAR-compliant supply chains for thermal weapon sight microdisplays, disqualifying offshore assembly. This specification shift compresses vendor qualification timelines and favors captive US production. The pattern is most visible in Army IVAS program deliveries, where domestic backplane fabrication is now contractually required.
Microdisplay Market Segmentation
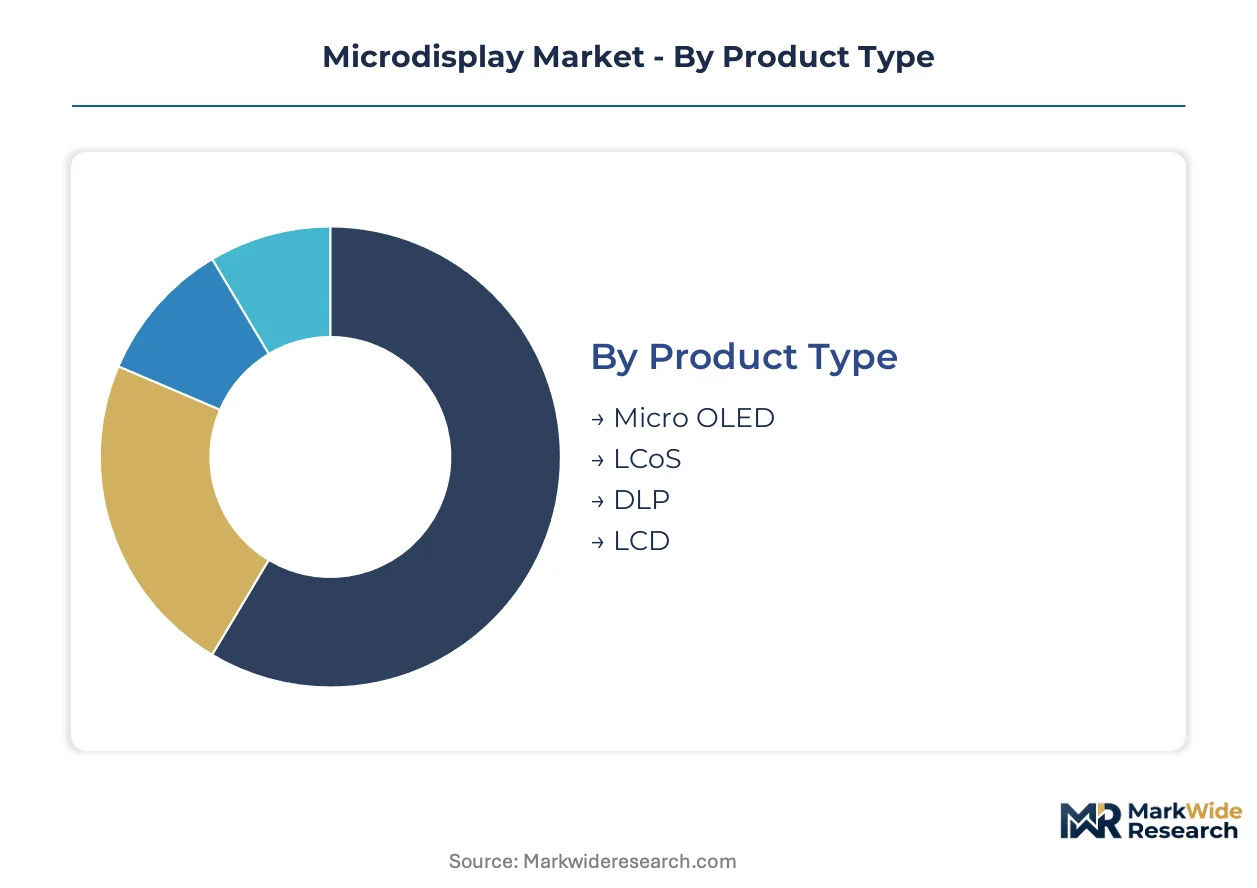
Microdisplay segmentation reveals technology bifurcation between premium emissive architectures and cost-optimized reflective alternatives. Product type and application categories determine foundry partnerships, regulatory pathways, and margin structures across the value chain.
Product Type:
Volume shipments concentrate in mature reflective technologies while premium positioning attaches to emissive architectures with superior pixel density.
- Micro OLED:Silicon backplane integration achieves pixel densities exceeding 3,000 PPI through semiconductor lithography. Demand concentrates in near-eye AR headsets for consumer electronics, constrained by blue emitter lifetime degradation below 10,000 hours at operational luminance.
- LCoS:Liquid crystal on silicon leverages mature CMOS foundry infrastructure for cost-efficient production. Automotive HUD applications in Germany and Japan specify LCoS engines for waveguide combiner integration where brightness requirements remain moderate.
- DLP:Digital micromirror devices from Texas Instruments anchor pico-projection and structured-light sensing with established supply chains.
- LCD:Transmissive liquid crystal microdisplays retain position in cost-sensitive wearable viewfinders with limited optical complexity.
Mature deployment sits with LCD. Newer deployment is concentrated in Micro OLED.
Application:
Customer investment cycles separate enterprise-grade visualization from mass-market entertainment consumption.
- Augmented Reality:Optical see-through architectures demand luminance exceeding 5,000 nits for outdoor readability. Healthcare surgical overlays in the United States face FDA 510(k) validation timelines extending 18-24 months.
- Virtual Reality:Enclosed headsets prioritize refresh rate and motion-to-photon latency over ambient light rejection. Consumer electronics procurement in China drives volume scaling for VR-specific panel formats.
- Head-Up Display:Windshield-integrated AR navigation attracts Tier-1 supplier engineering investment for luxury automotive platforms.
- Wearable Tech:Compact viewfinders for photography and drone piloting emphasize power efficiency over immersion depth.
Volume concentration remains with Virtual Reality. Steepest expansion trajectory belongs to Augmented Reality.
End User:
Procurement rigor separates defense and healthcare qualification pathways from consumer electronics velocity.
- Consumer Electronics:VR headsets and camera viewfinders demand cost-optimized panels with six-month product refresh cycles. Assembly concentration in China leverages BOE Technology Group and SeeYA Technology procurement.
- Automotive:HUD integration requires thermal cycling validation and AEC-Q100 compliance for cabin electronics. German KBA type approval governs windshield projection safety.
- Defense:Thermal weapon sights specify ITAR-compliant supply chains with domestic backplane fabrication. United States Army IVAS program mandates captive US production.
- Healthcare:Surgical microscopes and augmented overlays require FDA clearance with clinical evidence packages. European medical imaging OEMs qualify OLED ahead of Micro LED readiness.
Procurement standardization is highest in Defense. Gaining share fastest is Healthcare.
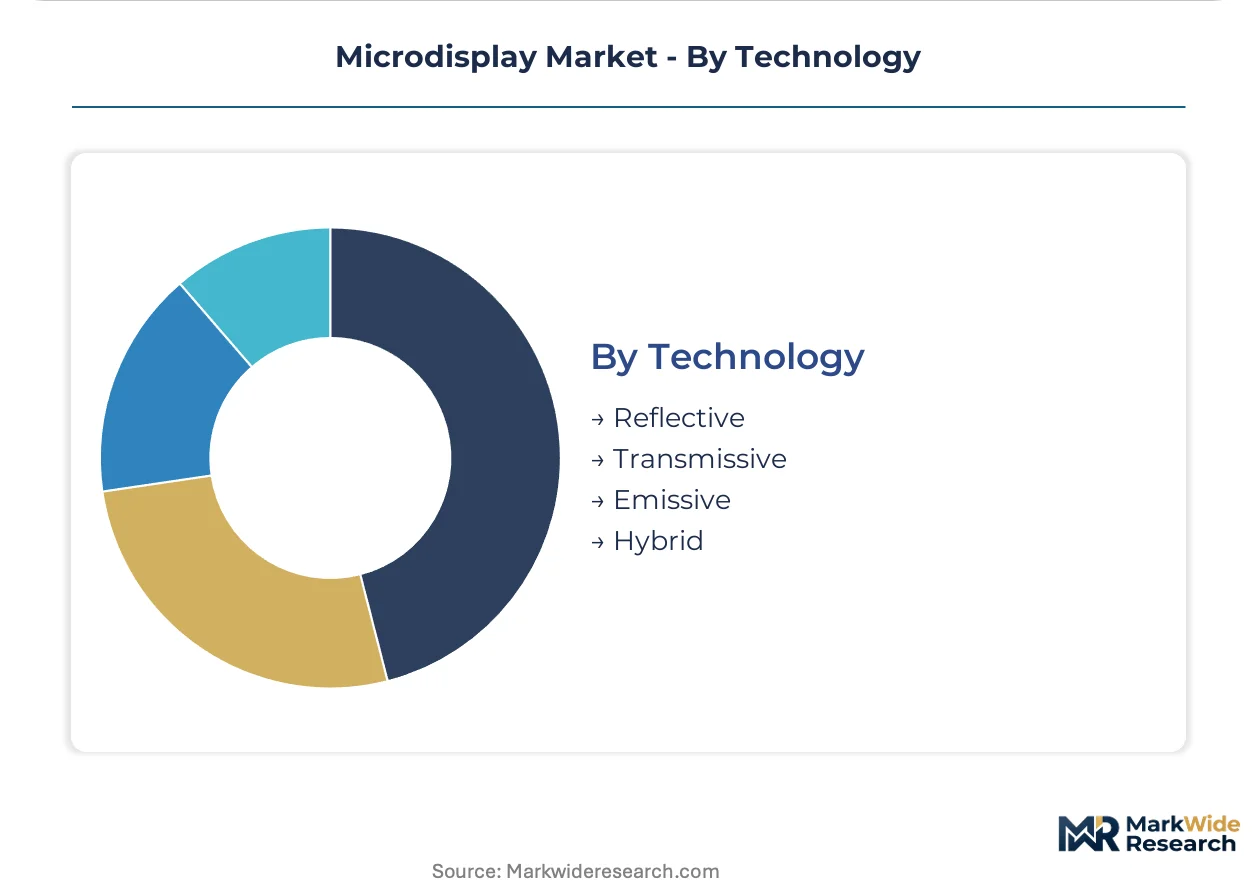
Technology:
Optical architecture determines compatibility with illumination source, thermal budget, and color gamut requirements.
- Emissive:Self-illuminating pixels eliminate backlight assembly and enable infinite contrast ratios. EU RoHS exemptions favor emissive OLED over mercury-containing alternatives.
- Reflective:External illumination enables high brightness for HUD applications without thermal runaway. LCoS and DLP dominate this architecture.
- Transmissive:Backlight-dependent liquid crystal retains cost position in low-specification viewfinders with limited ambient light challenges.
- Hybrid:Combinations of emissive and reflective elements address specific luminance and efficiency trade-offs in emerging headset designs.
Technology maturation centers on Reflective. Engineering investment is concentrating in Emissive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the most concentrated microdisplay assembly corridor, with BOE Technology Group and SeeYA Technology procurement channels feeding defense and consumer headset production lines.
United States
Army IVAS program deliveries mandate ITAR-compliant supply chains with domestic backplane fabrication. FDA 510(k) clearance timelines extend 18-24 months for augmented-reality surgical overlays from Himax Technologies and eMagin. Boston and Austin clusters host defense contractors specifying ruggedized OLED modules for thermal weapon sights.
China
Dual carbon goals from MEE accelerate emissive display adoption over mercury-containing alternatives. MIIT semiconductor subsidies support BOE Technology Group and SeeYA Technology capacity expansion for defense and consumer procurement. Yangtze River Delta concentration spans wafer-level packaging through final headset assembly.
Germany
KBA type approval governs windshield projection safety for automotive HUD integration. EU Ecodesign mandates under RoHS exemptions favor emissive OLED microdisplays from OLEDWorks. Stuttgart and Munich corridors host Tier-1 suppliers embedding waveguide combiners in luxury OEM platforms.
Japan
METI technology roadmaps prioritize silicon backplane lithography exceeding 3,000 PPI for near-eye applications. JIS standards govern thermal cycling validation for automotive cabin electronics. Tokyo-Osaka industrial belt concentrates CMOS foundry partnerships and mask-set investments.
South Korea
MFDS medical device regulations shape validation pathways for surgical microscopes. Samsung Foundry controls 40nm CMOS backplane capacity critical for fabless microdisplay vendors. Seoul Capital Area clusters span epitaxy through final panel test for emissive architectures.
Microdisplay Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across backplane fabrication and emitter integration. The market structures around vertically integrated semiconductor houses, captive foundry partnerships, and fabless display specialists. Two dominant archetypes emerge: CMOS backplane owners leveraging lithography expertise, and OLEDWorks-style emissive technology specialists qualifying for EU regulatory exemptions. Competitive moves concentrate on foundry capacity reservations and heterogeneous integration partnerships for Micro LED plus silicon photonics convergence.
Within the vertically integrated tier, Sony Group Corporation exemplifies premium positioning through CMOS backplane ownership. Among US-based defense suppliers, Kopin Corporation and eMagin occupy positions anchoring ITAR-compliant thermal weapon sight programs. OLEDWorks represents the European regulatory-focused archetype qualifying emissive architectures for CE marking under RoHS exemptions.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Seiko Epson Corporation |
| Kopin Corporation |
| eMagin |
| SeeYA Technology |
| Himax Technologies |
| LG Display |
| BOE Technology Group |
| OLEDWorks |
| Others |
Supply Flow & Price Mechanics
ITAR-compliant procurement mandates from United States Army IVAS program offices force domestic backplane fabrication, compressing supplier qualification timelines and elevating pricing for qualified vendors against offshore alternatives.
Pricing Analysis
Margin tightening in defense-grade OLED modules reflects captive US production requirements and limited foundry partners with ITAR clearance. Three-tier pricing structure across ITAR-qualified, CE-marked, and consumer-grade panels separates premium military specifications from automotive HUD and mass-market VR tiers. Price differentiation centers on certification level and silicon backplane lithography node. Cost-down pressure on consumer VR panels accelerates because BOE Technology Group and SeeYA Technology capacity expansion in China feeds volume procurement. Healthcare surgical overlays show lowest price sensitivity due to FDA 510(k) validation barriers; consumer electronics procurement exhibits highest sensitivity with six-month refresh cycles.
Supply Chain Analysis
Silicon wafer supply rests on TSMC in Taiwan, Samsung Foundry in South Korea, and domestic US foundries for ITAR-compliant defense programs. Gallium arsenide and indium phosphide inputs for Micro LED epitaxy draw from compound semiconductor specialists in Japan and Germany. Single-source vulnerability concentrates in 90nm and 40nm CMOS backplane capacity where TSMC and Samsung Foundry control allocation. Distribution runs through Tier-1 automotive suppliers for HUD integration, defense prime contractors for thermal weapon sights, and direct OEM procurement for consumer headset assembly in Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity reservations for advanced CMOS backplanes constitute the binding constraint, propping pricing power for vertically integrated semiconductor houses against fabless competitors.
For Market Incumbents: Hedge against Micro LED displacement by accelerating heterogeneous integration partnerships with silicon photonics foundries. Secure multi-year capacity reservations at TSMC or Samsung Foundry before 40nm backplane allocation tightens further. Prioritize ITAR-compliant supply chain certification to capture Army IVAS program volumes.
For New Entrants and Emerging Players: Capture white-space in India PLI scheme incentives for consumer VR headset assembly, where display manufacturing subsidies reduce capital barriers. Target healthcare surgical overlay segments where FDA 510(k) reciprocity with EU AI Act CE marking creates dual-market validation efficiency. Lead with software-defined display calibration services rather than hardware panel production.
For Investors and Strategic Acquirers: The window for entry favors CMOS backplane owners with lithography expertise exceeding 3,000 PPI. Long-term viability hinges on heterogeneous integration capabilities for Micro LED plus silicon photonics convergence. Watch for ITAR compliance certification announcements as inflection indicators for defense revenue visibility.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Supply Chain Certification | Army IVAS program mandates domestic backplane fabrication, disqualifying offshore assembly. |
| Silicon Photonics Partnership | Heterogeneous integration enables chip-scale LiDAR engines for automotive sensing applications. |
| EU Ecodesign Qualification | RoHS exemptions favor emissive OLED from OLEDWorks over mercury-containing alternatives. |
| Foundry Capacity Reservation | TSMC and Samsung Foundry control 90nm and 40nm CMOS backplane allocation for microdisplays. |
| FDA-CE Reciprocity Pathway | Dual validation efficiency attracts surgical overlay vendors seeking healthcare market expansion. |
Methodological Framework
Independent corroboration across CMOS foundry executives, defense procurement officers, and automotive Tier-1 supplier engineering leads underwrites the qualitative findings. Secondary validation draws from SEC filings of display technology vendors, MIIT semiconductor subsidy disclosures from China, and FDA 510(k) clearance databases. Customs records tracking indium phosphide and gallium arsenide wafer shipments provide input cost calibration. Bottom-up panel shipment estimates from BOE Technology Group and SeeYA Technology channels triangulate against top-down automotive HUD and defense program budget allocations.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions span product type, application, end user, and technology architecture. CAGRs derive from installed base modeling for AR headset penetration, automotive HUD content per vehicle, and defense thermal weapon sight replacement cycles. Blue OLED emitter lifetime degradation curves and Micro LED epitaxy yield improvements constitute key forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to compound semiconductor input volatility and East Asian foundry concentration risk. Assumptions reflect current regulatory pathways for EU AI Act visual system classification and FDA surgical overlay validation. A small set of triggers warrants ongoing watch: ITAR compliance mandate expansion, REACH restrictions on quantum dot formulations, and TSMC capacity allocation shifts toward AI accelerator demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Laptops Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Global Monochrome Display Market
Display Technologies
OLED Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
3D Holographic Display Market
Display Technologies
AMOLED Display Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Smart Display Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Touch Screen Display Market
Display Technologies
Head Up Display Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Global Transparent Display Market