
 Digital Holographic Display Market | 2026-2036
Digital Holographic Display Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Holographic Display Market Insights
South Korean panel foundries is repositioning their OLED pilot lines toward holographic-capable substrates, tightening upstream supply for downstream integrators. Leia Inc specializes in diffractive light-field architectures for mobile form factors. Looking Glass Factory Inc dominates desktop volumetric workstations with factory-calibrated lenticular arrays. Light Field Lab Inc extends its reach into large-format immersive installations through proprietary solid-light modulation.
A digital holographic display renders three-dimensional imagery through coherent light interference or light-field reconstruction without requiring wearable optics, typically achieving spatial resolutions between 0.5 and 5 millimeters per hogel depending on the modulation substrate. These systems serve medical visualization, automotive HUD prototyping, and experiential retail where depth cues reduce operator error and elevate engagement. Projection systems currently anchor the hardware revenue pool due to cinema and live-event deployment scale, while head-mounted displays represent the fastest-expanding category as waveguide efficiency improves. Desktop monitors command premium pricing in surgical planning suites where stereoscopic fidelity directly impacts clinical outcomes.
FDA 510(k) clearance pathways for diagnostic holographic viewers are lengthening validation timelines for healthcare entrants, while FCC electromagnetic emissions rules constrain laser-source power thresholds in consumer-facing devices. ECHA REACH compliance adds material-scrutiny costs for European-bound electrochromic modulators containing rare-earth dopants. Stakeholders must weigh regulatory pre-certification investments against first-mover positioning in medical and defense procurement channels.
Market Dynamics
Panel foundries in South Korea are repurposing OLED pilot lines toward holographic-capable substrates, compressing upstream supply availability and forcing downstream integrators to secure multi-year substrate commitments earlier in development cycles.
Growth Catalysts
- Light-field rendering architectures:Advances in diffractive waveguide design are reducing hardware cost curves for desktop volumetric workstations, expanding addressable demand in surgical planning suites.
- FDA 510(k) diagnostic viewer pathways:Regulatory pre-certification investments by medical imaging vendors are accelerating hospital procurement cycles for holographic visualization systems in North American healthcare networks.
- Volumetric cinema deployment:Live-event and cinema-scale projection systems are anchoring hardware revenue pools through venue retrofit programs in Germany and the United States.
Market Restraints
- Rare-earth dopant supply concentration:ECHA REACH compliance scrutiny on electrochromic modulators containing europium and terbium compounds elevates material qualification costs for European-bound devices.
- Laser-source power thresholds:FCC electromagnetic emissions rules constrain coherent light output in consumer-facing holographic displays, limiting brightness performance in retail and automotive HUD applications.
- Waveguide efficiency limitations:Current photopolymer gratings achieve only 15-20% light extraction efficiency, creating thermal management burdens that increase subsystem complexity.
Strategic Opportunities
- Automotive HUD prototyping:German OEMs are expanding holographic windscreen evaluation programs, creating demand for solid-light modulation systems that eliminate virtual image accommodation conflict.
- Experiential retail installations:South Korean duty-free operators are piloting gesture-interactive volumetric displays for luxury product visualization, establishing proof points for scalable deployment.
- Medical training simulation:MFDS regulatory harmonization initiatives in South Korea are streamlining approval pathways for holographic anatomical trainers, reducing time-to-market for educational device manufacturers.
Industry Challenges
- Computational holography talent scarcity:The intersection of Fourier optics, GPU shader programming, and real-time point-cloud processing requires skill profiles rarely found in conventional display engineering pipelines.
- Legacy DICOM integration complexity:Hospital IT departments face extended validation timelines when connecting volumetric viewers to existing PACS infrastructure, delaying clinical workflow adoption.
- Cross-licensing friction in light-field IP:Patent thickets covering hogel array geometries and eye-tracking fusion algorithms complicate freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Holographic Display Market |
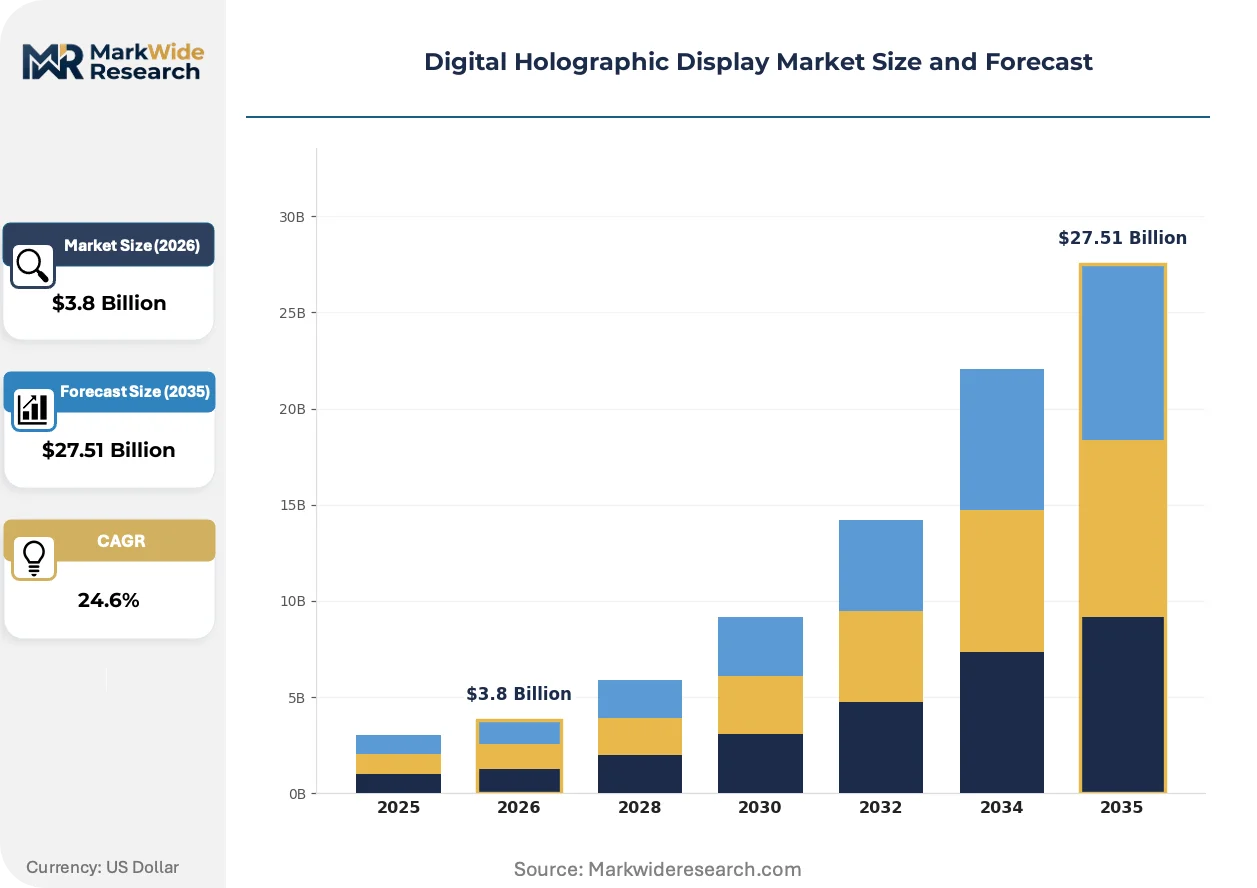
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Desktop Monitors, Projection Systems, Holographic Tablets End User: Entertainment, Education, Healthcare, Retail Technology: Laser Light, Digital Light Processing, Liquid Crystal, Electrochromic Application: Advertising, Simulation, Training, Virtual Tours |
| Companies Covered | RealView Imaging Ltd, Holoxica Ltd, Leia Inc, EON Reality Inc, HYPERVSN, VividQ Ltd, Looking Glass Factory Inc, MDH Hologram, Light Field Lab Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Holographic Display Market Trends and Innovations
Coherent light modulation is crossing threshold efficiency levels that enable practical deployment outside controlled laboratory environments, while regulatory bodies in three major economies are establishing distinct pre-market clearance frameworks for medical and consumer applications.
Real-time holographic compute pipelines are automating the generation of interference patterns from standard depth-camera inputs, eliminating the need for specialized capture rigs. Automotive HUD engineering teams at German Tier-1 suppliers are adopting these systems for rapid prototyping cycles. This compression of content creation workflows is automating what previously required dedicated optical physicists, broadening supplier participation beyond legacy holography specialists.
EMA's Medical Device Regulation (MDR) implementation is tightening clinical evidence requirements for diagnostic display systems marketed in Europe, forcing manufacturers to generate hologram-specific contrast sensitivity data rather than relying on legacy 2D monitor studies. The regulatory burden falls most heavily on desktop surgical planning monitors, where stereoscopic fidelity claims must now demonstrate measurable outcome improvements in randomized trials. European healthcare procurement consortia are responding by consolidating vendor qualification lists around MDR-certified suppliers.
Hospital radiology departments are unbundling hardware acquisition from software licensing and maintenance contracts, treating holographic viewers as capital equipment with separate PACS integration service agreements. This disaggregation disrupts the traditional bundled pricing models of incumbent medical display vendors. The shift is most pronounced in United States academic medical centers, where centralized IT governance is mandating interoperability-first procurement specifications that favor modular system architectures over vertically integrated offerings.
Digital Holographic Display Market Segmentation
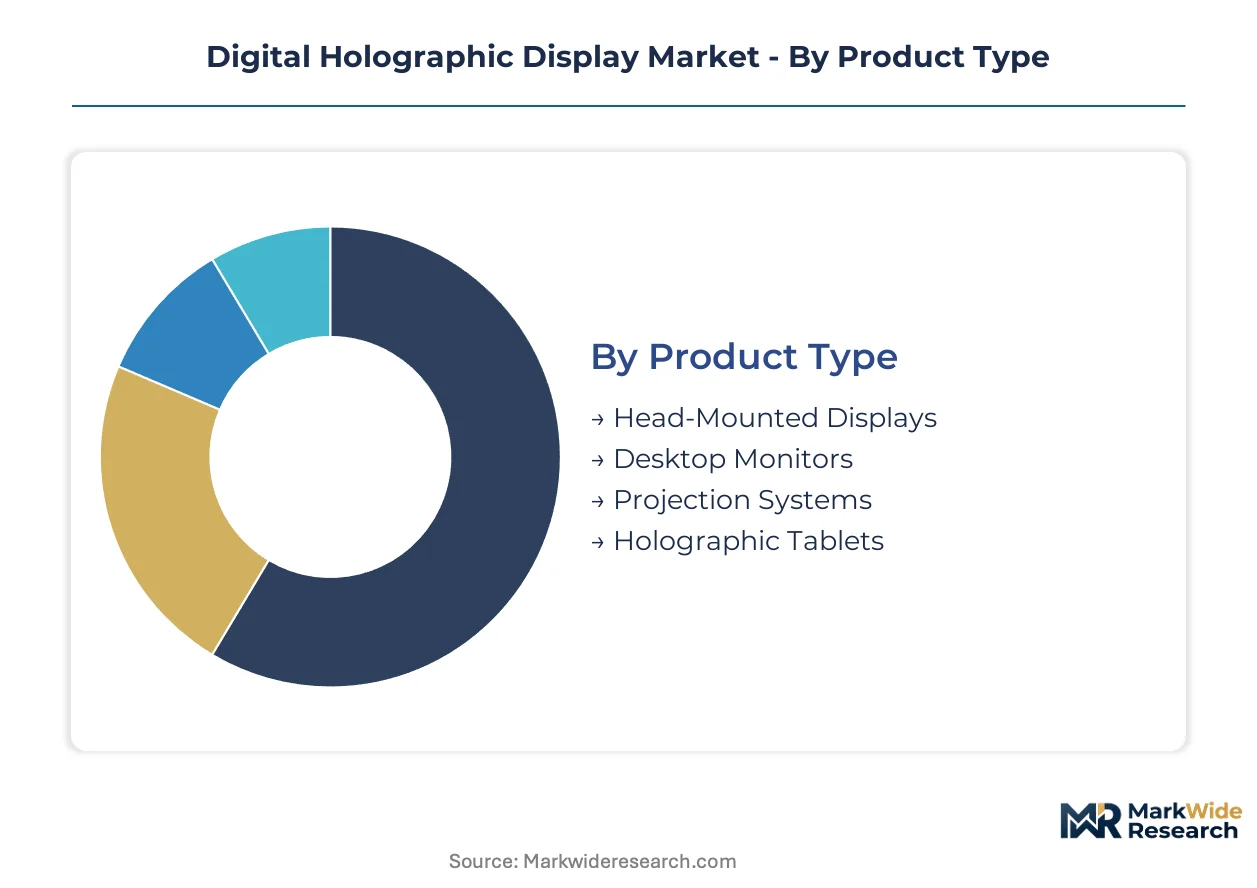
Holographic display architectures diverge sharply across use cases, with medical visualization demanding sub-millimeter hogel precision while retail installations prioritize scale economics over fidelity. Segmentation reveals how substrate chemistry, form factor constraints, and regulatory pathways fragment addressable demand into distinct procurement channels.
Product Type:
Customization intensity spans from factory-calibrated lenticular arrays for surgical suites to mass-market waveguide assemblies for consumer electronics, creating tiered margin structures across the hardware spectrum.
- Projection Systems:Cinema-scale volumetric engines deploy coherent laser interference across retrofit venue installations. German live-event operators and United States cinema chains anchor procurement volume, though thermal management complexity limits residential penetration.
- Head-Mounted Displays:Diffractive waveguide architectures achieve retinal resolution through photopolymer gratings. South Korean OEM evaluation programs for extended-reality headsets are compressing development cycles, while FCC laser-power thresholds constrain brightness specifications for consumer variants.
- Desktop Monitors:Factory-calibrated lenticular arrays serve surgical planning suites where stereoscopic fidelity impacts clinical outcomes.
- Holographic Tablets:Mobile-form-factor light-field engines prioritize battery efficiency over spatial resolution.
Most installed capacity flows through Projection Systems. Expansion is steepest in Head-Mounted Displays.
End User:
Procurement authority concentrates in institutional buyers with dedicated capital equipment budgets rather than consumer discretionary spend, reshaping go-to-market economics toward long sales cycles and certification requirements.
- Healthcare:FDA 510(k) diagnostic viewers and MFDS-regulated anatomical trainers command premium pricing in radiology departments. United States academic medical centers are unbundling hardware from PACS integration contracts, favoring modular architectures over vertically integrated systems.
- Retail:South Korean duty-free operators pilot gesture-interactive volumetric displays for luxury product visualization, establishing scalable deployment proof points ahead of broader experiential commerce adoption.
- Entertainment:Cinema and live-event venues drive large-format projection demand through retrofit programs.
- Education:Medical training simulation requirements are streamlining regulatory pathways for holographic anatomical trainers.
Revenue concentration sits with Healthcare. Steepest expansion trajectory belongs to Retail.
Technology:
Light modulation physics determines thermal budgets, material qualification costs, and regulatory jurisdiction, with laser-based architectures facing distinct electromagnetic emissions constraints versus solid-state alternatives.
- Laser Light:Coherent interference systems achieve highest spatial resolution through precise phase control. FCC emissions rules constrain power thresholds in consumer-facing devices, while FDA diagnostic pathways lengthen validation timelines for medical applications.
- Electrochromic:Rare-earth-doped substrates enable solid-light modulation without coherent sources. ECHA REACH compliance elevates material-scrutiny costs for European-bound devices containing europium and terbium compounds.
- Digital Light Processing:Micromirror arrays offer mature supply chains from legacy projection markets.
- Liquid Crystal:Polarization-modulation architectures leverage existing panel foundry infrastructure.
Manufacturing scale currently favors Laser Light. Regulatory headwinds are shifting investment toward Electrochromic alternatives.
Application:
Content creation workflows and real-time compute requirements fragment addressable use cases, with pre-rendered cinematic content facing fundamentally different technical constraints than interactive simulation environments.
- Simulation:Real-time holographic compute pipelines automate interference pattern generation from depth-camera inputs. German automotive Tier-1 suppliers adopt these systems for HUD prototyping cycles, eliminating previous requirements for dedicated optical physicists.
- Training:Holographic anatomical trainers benefit from MFDS regulatory harmonization in South Korea, compressing approval timelines for educational device manufacturers.
- Advertising:Experiential retail installations prioritize gesture interactivity over medical-grade fidelity.
- Virtual Tours:Cultural heritage and real estate visualization demand portable form factors with reduced thermal footprints.
Simulation commands the highest technical specification requirements. Training applications are gaining share fastest through regulatory pathway streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing holographic display manufacturing capacity toward jurisdictions with streamlined pre-market clearance pathways. South Korean and German foundries attract substrate fabrication investment due to shorter validation timelines than FDA-governed alternatives.
United States
FDA 510(k) diagnostic viewer pathways are lengthening validation timelines for healthcare entrants, compressing first-mover advantages for domestic manufacturers. FCC electromagnetic emissions rules constrain laser-source power thresholds in consumer-facing devices, limiting brightness performance in retail and automotive HUD applications. Academic medical centers in Boston and the San Francisco Bay Area are unbundling hardware acquisition from PACS integration contracts.
South Korea
MFDS regulatory harmonization initiatives are streamlining approval pathways for holographic anatomical trainers, reducing time-to-market for educational device manufacturers. Panel foundries in Gyeonggi Province are repurposing OLED pilot lines toward holographic-capable substrates, tightening upstream supply for downstream integrators. Seoul Capital Area duty-free operators are piloting gesture-interactive volumetric displays for luxury product visualization.
Germany
EMA Medical Device Regulation implementation is tightening clinical evidence requirements for diagnostic display systems, forcing manufacturers to generate hologram-specific contrast sensitivity data. ECHA REACH compliance adds material-scrutiny costs for European-bound electrochromic modulators containing rare-earth dopants. Automotive HUD engineering teams in Stuttgart and Munich are adopting real-time holographic compute pipelines for rapid prototyping cycles.
China
NMPA medical device registration timelines for holographic diagnostic equipment remain opaque, creating uncertainty for foreign entrants seeking market access. MIIT standards development for laser display safety is proceeding faster than international harmonization efforts, potentially creating technical barriers. Yangtze River Delta panel manufacturers are evaluating electrochromic substrate alternatives to reduce rare-earth dependency.
Japan
METI funding programs for next-generation display technologies are accelerating domestic holographic research commercialization. PMDA consultation procedures for novel medical imaging devices provide clearer pre-submission guidance than equivalent FDA pathways. Kansai region optical component suppliers are expanding diffractive waveguide manufacturing capacity for extended-reality headset integrators.
Digital Holographic Display Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in automotive HUD and experiential retail installations. The vendor base stratifies across three maturity tiers: legacy holography specialists with deep optical physics expertise, display panel incumbents repurposing existing fabrication infrastructure, and venture-backed startups commercializing real-time compute pipelines. Dominant competitive moves include strategic partnerships between substrate foundries and system integrators, plus technology licensing arrangements that circumvent patent thickets in hogel array geometries.
Within the venture-backed tier, Leia Inc and Light Field Lab Inc exemplify divergent scale strategies, with the former targeting mobile form factors and the latter extending into large-format immersive installations. Looking Glass Factory Inc anchors the desktop volumetric workstation segment through factory-calibrated lenticular arrays. These three entities collectively represent the competitive frontier where light-field rendering architectures are compressing hardware cost curves and expanding addressable demand beyond controlled laboratory environments.
| Leading Market Players |
|---|
| RealView Imaging Ltd |
| Holoxica Ltd |
| Leia Inc |
| EON Reality Inc |
| HYPERVSN |
| VividQ Ltd |
| Looking Glass Factory Inc |
| MDH Hologram |
| Light Field Lab Inc |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH compliance on rare-earth dopants gates qualified substrate supply and premium-tier pricing access for electrochromic modulators bound for European healthcare procurement. Manufacturers absorbing material-scrutiny costs for europium and terbium compounds capture pricing power in MDR-certified diagnostic display segments while competitors face margin compression or market exclusion.
Pricing Analysis
Distributor margins in holographic display hardware compress as panel foundries in South Korea tighten upstream supply through multi-year substrate commitments. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared surgical planning monitors from uncertified desktop units and mass-market waveguide assemblies. Pricing pressure stems from FCC laser-power thresholds constraining brightness specifications in consumer-facing head-mounted displays. Hospital procurement committees demonstrate lowest price sensitivity due to unbundled capital equipment budgets, while retail duty-free operators piloting gesture-interactive installations drive hardest bargain on volume scale.
Supply Chain Analysis
Workforce availability for Fourier optics and GPU shader programming concentrates in South Korea's Gyeonggi Province panel foundries and Germany's Stuttgart automotive engineering clusters. Substrate fabrication draws from repurposed OLED pilot lines, photopolymer grating suppliers in Japan's Kansai region, and rare-earth compound processors subject to ECHA REACH scrutiny. Single-source vulnerability sits with South Korean holographic-capable substrate capacity where multi-year commitments now lock out late entrants. Distribution runs through direct OEM partnerships for automotive HUD prototyping and specialized medical device distributors for hospital radiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital holographic displays rests on light-field rendering architectures compressing hardware cost curves while premium-tier clinical certification commands pricing power in unbundled procurement environments.
For Market Incumbents: Deploy backward integration into holographic-capable substrate fabrication to secure supply continuity as South Korean foundries tighten allocation. Deepen FDA 510(k) pre-certification investments to defend positioning against emerging entrants facing lengthened validation timelines, while expanding factory-calibrated lenticular array capacity for surgical planning suites where stereoscopic fidelity claims justify premium positioning. For New Entrants and Emerging Players: MFDS regulatory harmonization in South Korea opens a window for holographic anatomical trainers ahead of FDA-equivalent pathway complexity. Target experiential retail installations in Seoul Capital Area duty-free operators where gesture-interactive volumetric displays lack entrenched vendor relationships. Pursue white-label partnerships with German automotive Tier-1 suppliers adopting real-time holographic compute pipelines for rapid HUD prototyping cycles. For Investors and Strategic Acquirers: Roll-up economics work for computational holography talent-scarce specialists because Fourier optics and real-time point-cloud processing skill profiles resist commoditization. Platform consolidation across diffractive waveguide design houses and solid-light modulation developers offers five-to-ten year viability as light-field rendering crosses laboratory-to-deployment thresholds. Watch for FDA 510(k) clearance acceleration as inflection signal for healthcare segment capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Substrate Commitment | Locks holographic-capable OLED supply from South Korean foundries before allocation tightens further. |
| FDA 510(k) Pre-Certification Investment | Accelerates hospital procurement cycles in United States academic medical centers with unbundled contracting. |
| Real-Time Compute Pipeline Acquisition | Automates interference pattern generation eliminating dedicated optical physicist requirements for automotive HUD prototyping. |
| EMA MDR Contrast Sensitivity Study | Generates hologram-specific clinical evidence mandatory for European diagnostic display procurement consolidation. |
| Gesture-Interactive Retail Pilot | Establishes scalable deployment proof points with Seoul duty-free operators ahead of broader experiential commerce adoption. |
Research Methodology
Multiple input streams — primary interviews with holographic display engineering leads, hospital biomedical equipment procurement managers, and automotive Tier-1 supplier platform architects; secondary validation through FDA 510(k) filing databases, EMA MDR implementation guidance, and MFDS regulatory harmonization notices; plus customs records for rare-earth compound trade flows — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Historical shipment data for projection systems, head-mounted displays, and desktop monitors were cross-referenced against panel foundry capacity announcements and regulatory pathway timelines across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement authority, light modulation physics, and application compute requirements. CAGRs were derived from installed base growth trajectories and replacement cycle compression in medical visualization, with specific inputs from waveguide efficiency improvement curves and laser-source power threshold regulatory constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ECHA REACH restriction expansion or FCC electromagnetic emissions rule tightening. Material deviation in FDA 510(k) clearance velocity, South Korean substrate allocation policy shifts, or photopolymer grating yield breakthroughs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Global Display Controllers Market
Display Technologies
Global OLED Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Screenless Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
AMOLED Display Market
Display Technologies
Display Port Market
Display Technologies
PMOLED Display Market
Display Technologies
OLED Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Smartwatch Display Panel Market