
 Phosphor Screen Scanner Market | 2026-2036
Phosphor Screen Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphor Screen Scanner Market Outlook
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between qualified incumbents and new entrants. AGFA Healthcare leverages its vertically integrated imaging film heritage to sustain service contracts across hospital networks. Planmeca dominates Nordic dental markets through localized manufacturing and direct channel control. Carestream Dental anchors North American demand with extensive dealer networks and legacy equipment upgrade cycles.
A phosphor screen scanner captures latent X-ray images stored in photostimulable phosphor plates through laser stimulation and photoelectric conversion, typically resolving spatial detail below 100 micrometers for diagnostic clarity. The device translates trapped electron energy into digital signals for medical, industrial, or security analysis. Fixed scanner installations occupy the largest revenue pool across healthcare institutions, while portable scanner demand accelerates fastest among mobile veterinary and emergency response units. Laser scanning technology leads precision applications in non-destructive testing, though CCD imaging segments attract margin-focused buyers in educational laboratories.
FDA 510(k) premarket notification requirements govern U.S. market entry for diagnostic phosphor systems, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking across European Economic Area states. Japan's PMDA enforces QMS Ministerial Ordinance inspections that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EUDAMED as digital connectivity becomes standard in next-generation scanner architectures.
Market Dynamics
Healthcare digitization mandates and ISO 13485 certification requirements are compressing procurement cycles while bifurcating vendor qualifications between established imaging specialists and unqualified entrants. This structural pressure reshapes competitive positioning across dental, medical, and industrial radiography segments.
Growth Catalysts
- FDA 510(k) pathway streamlining:Pre-market notification requirements for digital radiography devices accelerate product development timelines for qualified manufacturers seeking U.S. market access.
- Veterinary mobile imaging:Emergency response units and field veterinary services drive portable scanner demand through rapid-deployment diagnostic protocols.
- Photostimulable phosphor plate advances:Improved electron trapping efficiency in barium fluorohalide crystals enhances image resolution below 100 micrometers for diagnostic clarity.
Market Restraints
- CE marking clinical evidence burdens:EU Medical Device Regulation imposes stricter documentation standards that extend approval timelines for European Economic Area market entry.
- Laser source supply concentration:Precision scanning modules depend on concentrated semiconductor laser manufacturing in East Asian supply clusters.
- CCD imaging substitution pressure:Educational laboratories and margin-focused buyers migrate toward lower-cost charge-coupled device alternatives for non-critical applications.
Strategic Opportunities
- Nordic dental network expansion:Localized manufacturing advantages create penetration pathways through direct channel control in Sweden, Norway, and Denmark markets.
- Cybersecurity guidance alignment:FDA post-market surveillance obligations for connected devices create service contract opportunities for vendors with embedded security architectures.
- Non-destructive testing convergence:Industrial quality assurance sectors combine laser stimulation protocols with automated defect recognition algorithms for aerospace and automotive inspection.
Industry Challenges
- PMDA QMS inspection complexity:Japan's Ministerial Ordinance enforcement extends foreign manufacturer approval timelines through repeated quality management system audits.
- EUDAMED registration friction:Post-market surveillance database obligations impose operational overhead for small and mid-cap scanner vendors serving European Economic Area states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphor Screen Scanner Market |
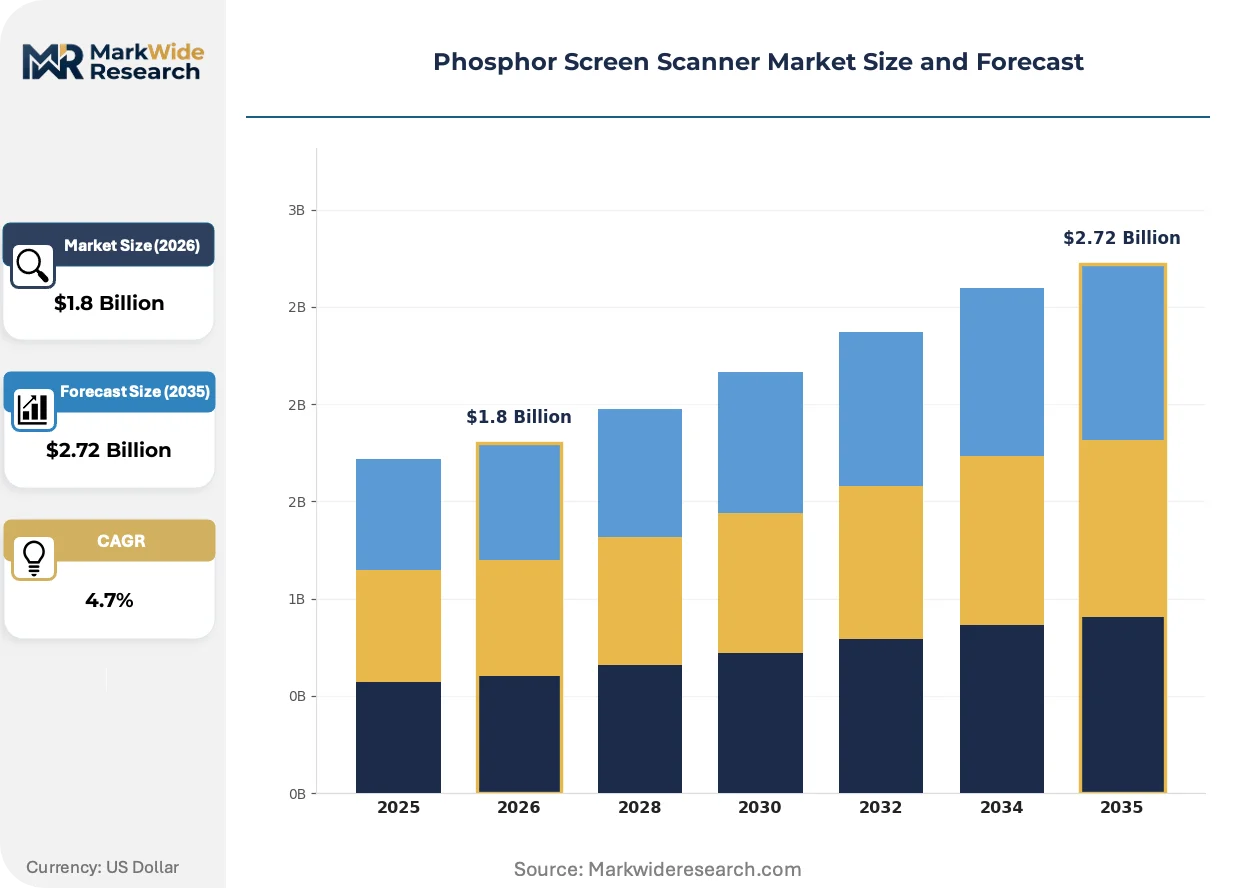
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Scanner, Portable Scanner, Handheld Scanner, Desktop Scanner End User: Healthcare Institutions, Research Laboratories, Educational Institutes, Industrial Applications Technology: Laser Scanning, CCD Imaging, Photoelectric Sensors, Digital Imaging Application: Medical Imaging, Quality Control, Non-Destructive Testing, Security Screening |
| Companies Covered | AGFA Healthcare, Soredex, Gendex, Owandy Radiology, ACTEON Group, Planmeca, Kavo, Dürr Dental, Carestream Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphor Screen Scanner Market Strategic Shifts
Scanner architectures are converging with cloud-native imaging platforms while regulatory bodies impose cybersecurity mandates on connected diagnostic equipment. These simultaneous pressures compress product development cycles and elevate service contract value.
Laser-based photostimulable phosphor readout is decomposing the traditional separation between high-precision medical imaging and portable field diagnostics. Veterinary emergency units and mobile dental clinics adopt compact laser modules for latent image capture. This convergence is decomposing the premium pricing hierarchy that previously segmented fixed hospital installations from portable alternatives.
EU Medical Device Regulation clinical evidence standards are restructuring product portfolio prioritization for manufacturers seeking CE marking. Stricter documentation requirements favor established vendors with dedicated regulatory affairs functions. Small and mid-cap entrants face compressed European Economic Area launch timelines or forced partnership strategies with notified bodies.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts across North American hospital networks. Procurement departments negotiate separate agreements for hardware acquisition, software licensing, and technical support. This disaggregation is most visible in U.S. dental group practices where centralized buying consortia extract modular pricing from legacy equipment upgrade cycles.
Phosphor Screen Scanner Market Segmentation
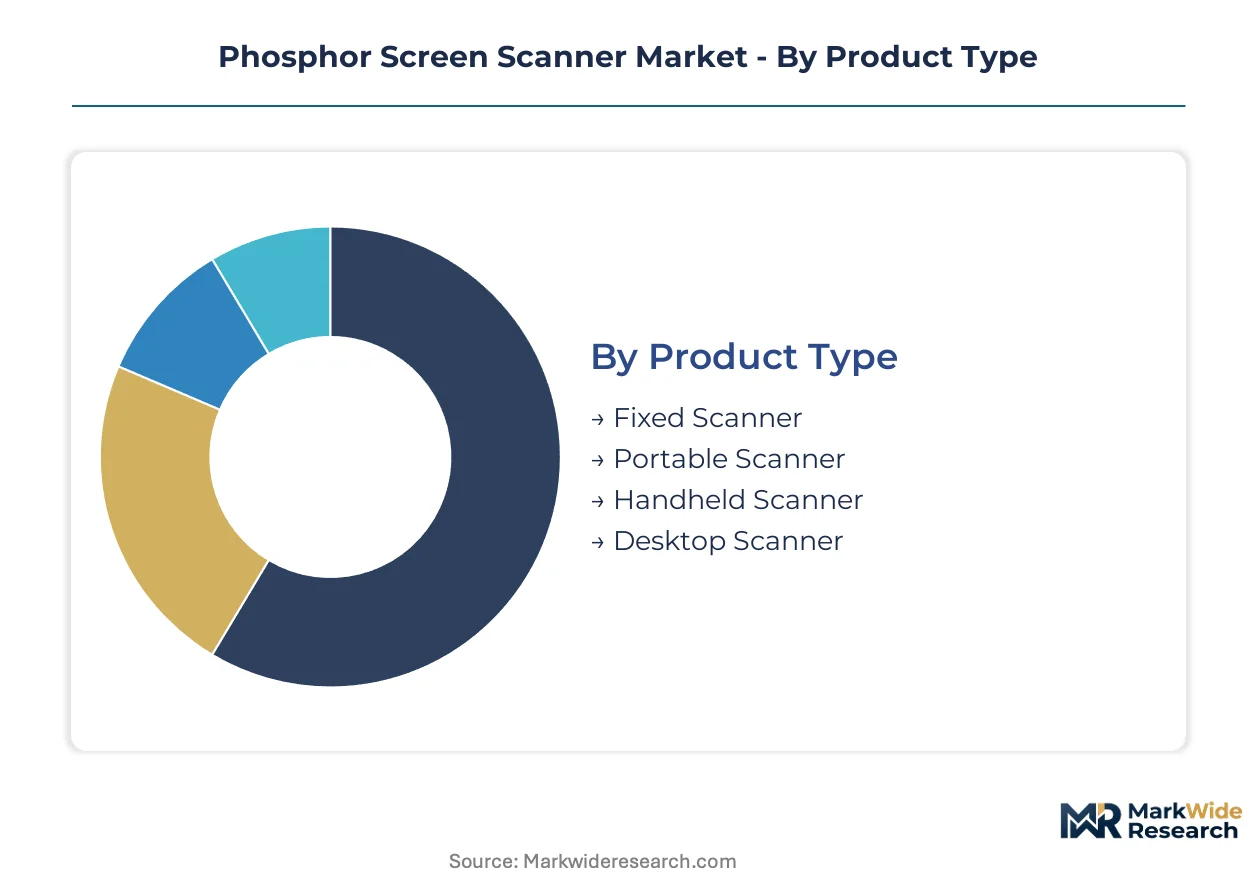
Phosphor screen scanner procurement channels diverge sharply by installation permanence and mobility requirements. Hospital networks favor capital-intensive fixed systems through integrated equipment tenders, while field-deployable units penetrate veterinary and emergency response markets through specialized distributors.
Product Type:
Channel mix splits between capital equipment procurement for fixed installations and rental or lease arrangements for mobile units. Healthcare systems consolidate fixed scanner purchases through group purchasing organizations, whereas portable and handheld variants flow through dental supply dealers and emergency equipment distributors.
- Fixed Scanner:Permanent installations integrate laser readout modules with automated plate handling mechanisms for high-throughput hospital radiology departments. Demand concentrates in United States and German hospital networks where ISO 13485-certified vendors secure multi-year service contracts tied to equipment refresh cycles.
- Portable Scanner:Compact laser stimulation units with battery power enable field deployment for veterinary emergency services and mobile dental clinics. Expansion concentrates in Nordic countries where Dürr Dental and Planmeca maintain direct distribution control over rural healthcare networks.
- Handheld Scanner:Single-plate manual readout devices serve point-of-care diagnostic protocols with reduced spatial resolution specifications.
- Desktop Scanner:Semi-portable units bridge fixed and mobile applications through modular connectivity options for small clinic environments.
Fixed scanner installations dominate installed base across hospital radiology departments. Portable scanner configurations are where expansion concentrates for veterinary and emergency response market penetration.
End User:
Cost tier stratification separates premium-certified medical installations from budget-constrained educational and research procurement. Healthcare institutions absorb compliance and validation costs that price-sensitive academic buyers circumvent through refurbished equipment channels.
- Healthcare Institutions:Hospitals and dental clinics demand FDA 510(k)-cleared or CE-marked systems with embedded quality management documentation. Demand concentrates in United States academic medical centers and German university hospitals where procurement mandates require ISO 13485 supplier certification.
- Research Laboratories:Non-diagnostic applications in materials science and biological imaging prioritize resolution specifications over regulatory clearance, enabling CCD-based alternatives.
- Educational Institutes:Training programs in radiologic technology procure entry-level desktop scanners through educational pricing agreements with legacy equipment vendors.
- Industrial Applications:Non-destructive testing facilities in aerospace and automotive sectors combine laser phosphor readout with automated defect recognition software for quality assurance protocols.
Healthcare institutions dominate installed base through regulatory-mandated procurement standards. Research laboratories are climbing the fastest as materials science applications expand beyond traditional medical imaging boundaries.
Technology:
Application specificity determines technology selection, with precision medical diagnostics requiring laser-based photostimulable phosphor readout while cost-sensitive educational markets accept CCD imaging compromises.
- Laser Scanning:Semiconductor laser stimulation of barium fluorohalide phosphor plates achieves sub-100 micrometer spatial resolution for diagnostic-grade image clarity. Demand concentrates in United States dental group practices and German industrial NDT facilities where resolution specifications justify premium pricing.
- CCD Imaging:Charge-coupled device alternatives substitute direct digital capture for phosphor plate readout, sacrificing dynamic range for acquisition speed and capital cost reduction.
- Photoelectric Sensors:Solid-state detection arrays enable compact scanner architectures for portable field deployment with reduced power consumption.
- Digital Imaging:Direct radiography panels bypass phosphor plate chemistry entirely, displacing scanner-dependent workflows in high-volume hospital installations.
Laser scanning dominates installed base across precision diagnostic applications. Digital imaging direct capture is gaining share fastest as panel cost curves compress hospital procurement decisions.
Application:
Geography and maturity separate established medical imaging markets from emerging industrial and security screening segments. Regulatory frameworks fragment procurement requirements across diagnostic and non-diagnostic use cases.
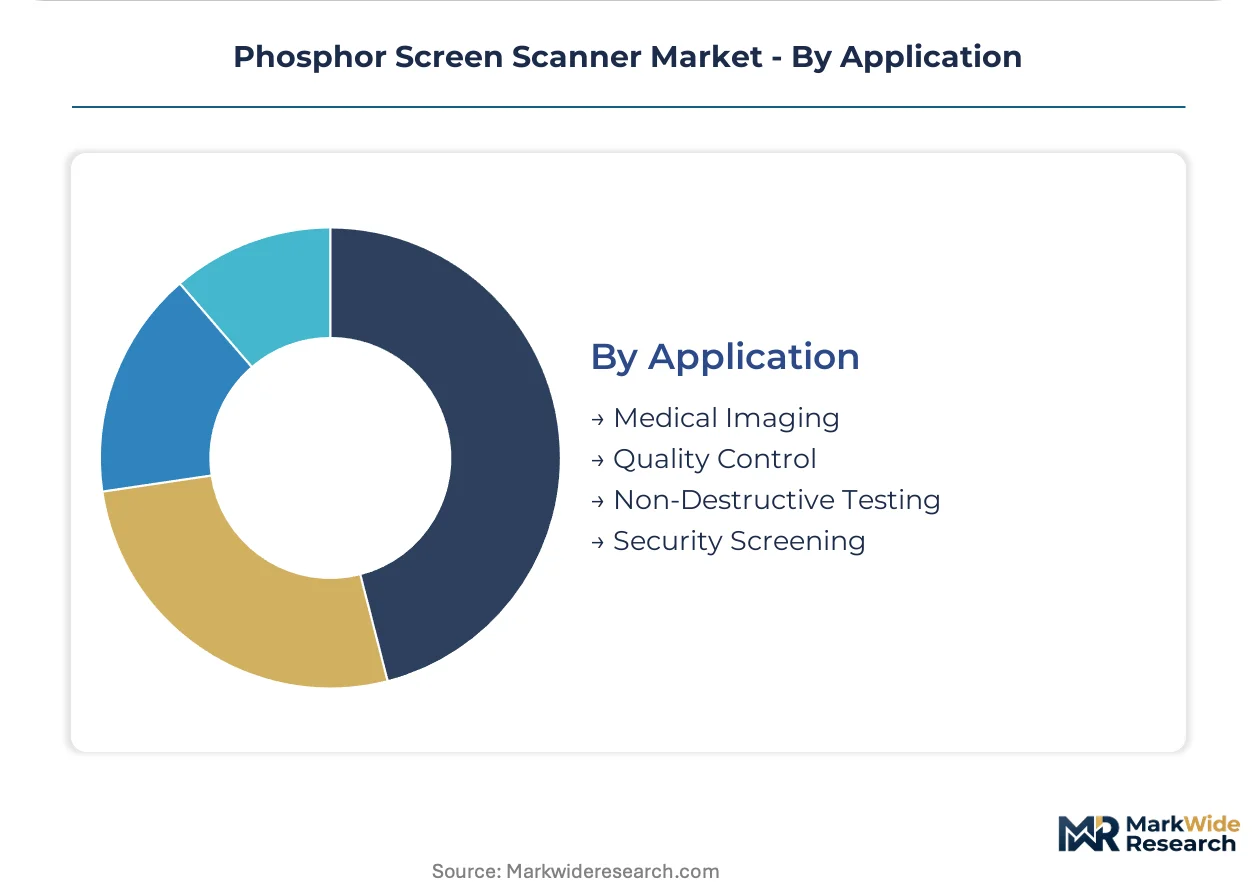
- Medical Imaging:Dental and general radiography applications require FDA 510(k) or CE marking with clinical evidence documentation for diagnostic claim support. Demand concentrates in United States dental service organizations and German statutory health insurance reimbursement networks.
- Quality Control:Manufacturing inspection protocols integrate phosphor screen scanners with automated part handling for weld and casting verification.
- Non-Destructive Testing:Aerospace component inspection and pipeline integrity assessment deploy portable laser scanners for field radiography with computed radiography workflows.
- Security Screening:Cargo and baggage inspection applications utilize high-throughput fixed scanners for contraband detection at ports and airports.
Medical imaging dominates installed base through reimbursement-supported procurement cycles. Non-destructive testing is where expansion concentrates as infrastructure inspection mandates proliferate across industrial economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European distribution for phosphor plate components and finished scanner systems, while the Trans-Siberian Railway corridor facilitates East Asian supply chain integration for semiconductor laser modules.
United States
FDA 510(k) premarket notifications govern diagnostic scanner approvals, compressing development timelines for qualified manufacturers. Dental service organizations in Texas and Florida consolidate procurement through group purchasing organizations. The Mayo Clinic Rochester campus anchors demand for high-throughput fixed installations across Upper Midwest hospital networks.
Germany
EU Medical Device Regulation clinical evidence requirements extend CE marking timelines for European Economic Area access. Statutory health insurance reimbursement networks concentrate demand in Bavaria and North Rhine-Westphalia. Dürr Dental anchors regional supply chains from its Bietigheim-Bissingen headquarters for intraoral scanner distribution.
Japan
PMDA QMS Ministerial Ordinance inspections extend foreign manufacturer approval timelines through repeated audits. Tokyo and Osaka dental clinics drive replacement demand for legacy film-based systems. The Kansai region hosts precision optics manufacturing clusters supplying laser scanning modules.
China
NMPA medical device registration requirements impose documentation burdens for diagnostic imaging equipment. Yangtze River Delta manufacturing hubs produce photostimulable phosphor plates for domestic and export markets. Shanghai's Pudong district concentrates import distribution for foreign scanner brands.
Sweden
Localized manufacturing advantages create penetration pathways through direct channel control across Nordic dental markets. Stockholm and Gothenburg academic medical centers mandate ISO 13485 supplier certification for procurement. Planmeca anchors regional supply from its Helsinki-adjacent production facilities serving Swedish networks.
Phosphor Screen Scanner Market Competitive Environment
Listed leaders compete with private specialists across regulatory qualification tiers, creating a bifurcated structure where ISO 13485-certified incumbents defend service contract positions against unqualified entrants. The vendor base splits between vertically integrated imaging heritage companies and modular component assemblers. Three archetypes dominate: legacy film processors with digital transition capabilities, dental-specialist equipment manufacturers with direct channel control, and industrial radiography providers repurposing medical-grade technology. Competitive moves concentrate on portfolio diversification into cybersecurity-enabled service contracts and geographic expansion through notified body partnerships for CE marking acceleration.
Within the dental-specialist tier, Planmeca and Dürr Dental exemplify direct channel control strategies across Nordic and German-speaking markets respectively. AGFA Healthcare occupies a position representing legacy imaging film heritage transitioning toward digital service contract models. Carestream Dental anchors North American demand through extensive dealer network relationships. These three players collectively illustrate how regulatory qualification depth separates sustainable competitive positioning from transactional equipment sales.
| Leading Market Players |
|---|
| AGFA Healthcare |
| Soredex |
| Gendex |
| Owandy Radiology |
| ACTEON Group |
| Planmeca |
| Kavo |
| Dürr Dental |
| Carestream Dental |
| Others |
Value Chain & Pricing Dynamics
Semiconductor laser manufacturing scale in East Asian hubs concentrates cost leverage among precision scanner module suppliers, compressing price floors for portable configurations while fixed installations retain premium positioning through ISO 13485-certified service bundling. Hospital procurement consolidation in United States dental service organizations and German statutory networks extracts volume discounts that strain margins for unqualified entrants lacking vertical integration into phosphor plate chemistry.
Pricing Analysis
Volume-discount tiering structures stratify across equipment-plus-service bundles, with healthcare institutions commanding 15-25% reductions through multi-year contracts tied to legacy system refresh cycles. Price differentiation hinges on FDA 510(k) clearance tier and geographic proximity to service engineering teams, with Nordic direct-channel vendors capturing brand premiums. Pricing pressure stems from CCD imaging substitution in educational laboratories, where budget-constrained buyers prioritize capital cost over diagnostic-grade resolution specifications. Research laboratories exhibit highest price sensitivity, while academic medical centers in United States absorb compliance premiums for embedded cybersecurity architectures.
Supply Chain Analysis
Just-in-time inventory strategies dominate finished scanner assembly, though strategic stockpiling of barium fluorohalide phosphor plates buffers against raw material concentration in Yangtze River Delta chemical processing clusters. Semiconductor laser modules draw from Taiwan and South Korea fabrication facilities, while precision optics for readout assemblies centers on Kansai region manufacturing in Japan. Single-source vulnerability concentrates in photostimulable phosphor plate substrate supply, with tariff exposure on rare-earth dopants amplifying cost volatility. Distribution runs through hospital group purchasing organizations in North America and direct channel control in Nordic dental networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare digitization mandates and cybersecurity guidance convergence are compressing product development cycles, creating asymmetric returns for vendors with pre-positioned regulatory qualification depth and embedded service contract architectures.
For Market Incumbents: Consolidate service contract positions through ISO 13485-certified cybersecurity module integration, defending against unqualified entrants lacking post-market surveillance capabilities. Deepen backward integration into phosphor plate chemistry to capture margin compression from East Asian laser module supply concentration. Prioritize notified body partnerships for CE marking acceleration under EU Medical Device Regulation clinical evidence standards.
For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest regulatory validation for portable scanner configurations targeting veterinary emergency services and mobile dental clinics. White-space penetration concentrates in Nordic rural healthcare networks where direct channel control gaps persist. Pursue modular hardware-plus-SaaS pricing to circumvent capital equipment procurement consolidation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated imaging heritage companies with captive phosphor plate supply and multi-year hospital service contracts. Long-term viability favors acquisition targets with embedded cybersecurity architectures and EUDAMED registration completion. Monitor FDA post-market surveillance obligation enforcement as inflection indicator for service contract pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation clinical evidence standards favor established vendors with dedicated regulatory affairs functions. |
| Hospital System Partnership | Mayo Clinic Rochester and Upper Midwest networks anchor demand for high-throughput fixed installations. |
| Software Companion Development | Cloud-native imaging platform integration elevates service contract value beyond transactional equipment sales. |
| Reimbursement Strategy | German statutory health insurance networks concentrate demand through validated diagnostic claim support. |
| Backward Integration | Captive phosphor plate chemistry supply insulates margin compression from East Asian laser module concentration. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at notified bodies, hospital procurement managers at United States academic medical centers, biomedical engineers at German university hospitals, and GPO contracts managers; alongside secondary validation through FDA 510(k) premarket notification databases, EUDAMED registration records, EU Medical Device Regulation guidance documents, and hospital procurement database extracts. Bottom-up scanner shipment estimates triangulated against top-down healthcare capital equipment spending patterns.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type mobility tier, end-user regulatory mandate intensity, technology resolution specification, and geographic reimbursement framework cluster. CAGRs derived from equipment refresh cycle analysis and veterinary mobile imaging penetration curves, with inputs from semiconductor laser module cost curves and phosphor plate electron trapping efficiency advances.
Decision-makers should treat outputs as directional under assumptions of sustained FDA 510(k) pathway stability and EU MDR enforcement continuity; material deviation in cybersecurity guidance stringency or East Asian supply chain disruption would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA QMS inspection timelines and EUDAMED operational friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
US Near Infrared Imaging Market
Imaging
3D Sensing and Imaging Market
Imaging
Industrial Machine Vision Market
Imaging
Digitizer Market
Imaging
Digital Camera Market
Imaging
Europe CT Market
Imaging
Computational Photography Market
Imaging
Instaprint Camera Market
Imaging
Frame Grabber Market
Imaging
Facial Recognition Machine Market
Imaging
Acoustic Microscopy Market
Imaging
Automotive Compact Camera Module Market
Imaging
Industrial Camera Market
Imaging
Machine Vision Camera Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Europe IP Camera Market