
 Vietnam Digital Signage Market | 2026-2036
Vietnam Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Digital Signage Market Outlook
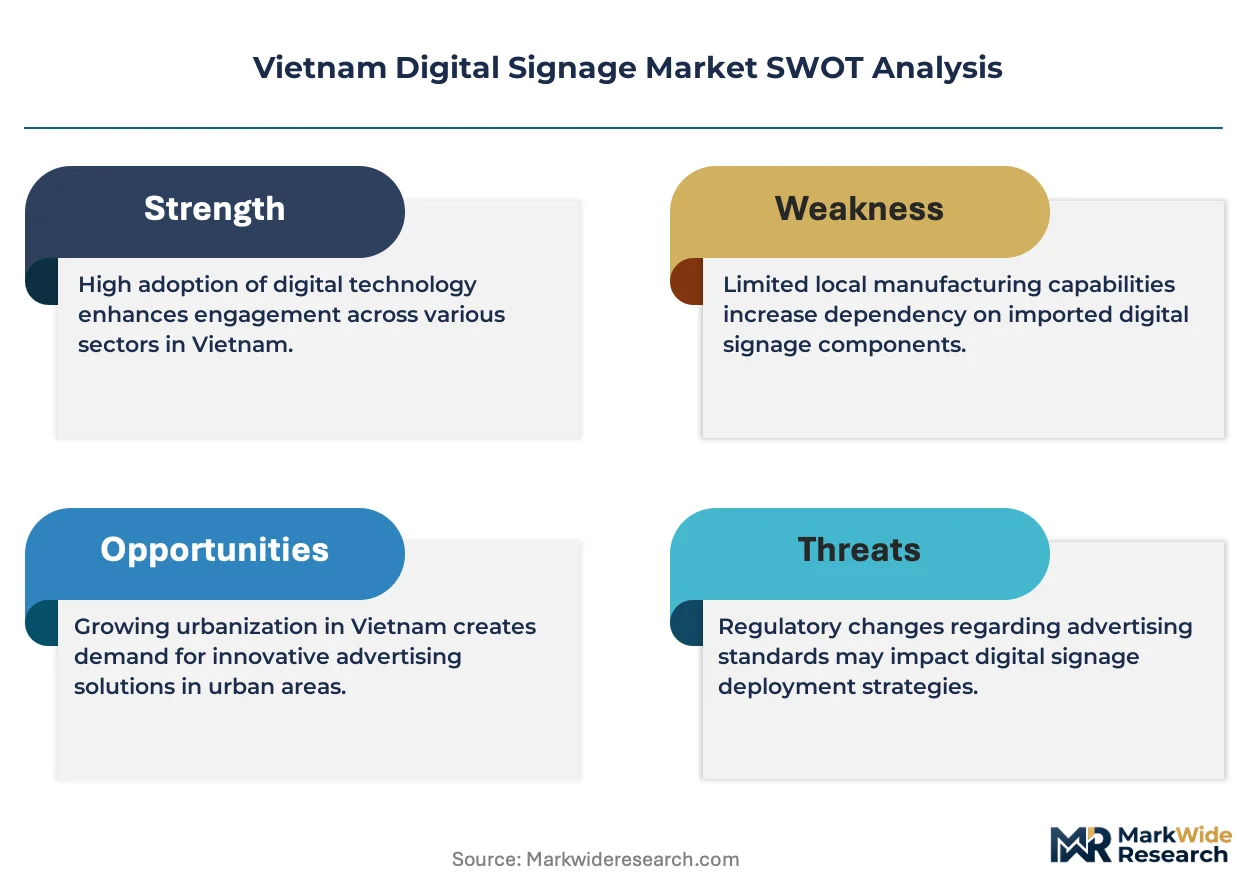
Domestic electronics assembly capacity in northern Vietnam is hardening as contract manufacturers expand dedicated display module lines. Samsung Electronics leverages its existing smartphone panel ecosystem to feed downstream signage production. LG Electronics anchors its position through captive LED driver IC sourcing from regional semiconductor partners. Panasonic Corporation differentiates via industrial-grade thermal management systems suited to tropical operating conditions.
Vietnam digital signage encompasses networked visual communication systems comprising LED, OLED, and LCD panels with embedded media players, content management software, and connectivity modules, typically operating at brightness levels of 2,500 to 5,000 nits for outdoor visibility and 350 to 700 nits for indoor environments. These systems serve commercial and institutional buyers by delivering scheduled, remotely updatable visual content for advertising, wayfinding, and operational communication. LED Display products dominate volume shipments due to falling per-unit costs and modular scalability for large-format installations, while OLED Display segments command premium positioning in hospitality and corporate lobbies where contrast ratios and slim form factors justify higher expenditure. Interactive technology applications are expanding fastest across retail and educational end users as touch-enabled wayfinding and self-service kiosks displace static poster networks.
Vietnam's Ministry of Information and Communications regulates content broadcasting over public digital networks, requiring licensing for outdoor advertising displays and enforcing cybersecurity protocols for cloud-connected signage systems. The country's national standards body aligns display energy efficiency requirements with regional ASEAN harmonization frameworks, creating compliance thresholds for imported equipment. Buyers must monitor evolving localization mandates for software hosting and data residency as authorities scrutinize cross-border content delivery infrastructure.
Market Dynamics
Vietnam's digital signage sector is tightening around content localization mandates as the Ministry of Information and Communications enforces data residency requirements for cloud-connected display networks, forcing infrastructure reconfiguration across commercial deployments.
Growth Catalysts
- Hospitality construction pipeline:Luxury hotel developments in Da Nang and Phu Quoc are specifying large-format LED installations for lobby and conference environments, creating concentrated demand clusters.
- Retail screen densification:Shopping centers across Ho Chi Minh City and Hanoi are replacing static poster networks with networked digital displays to enable dynamic pricing and promotional content rotation.
- ASEAN energy efficiency harmonization:The national standards body's alignment with regional display power consumption frameworks is accelerating equipment upgrade cycles among institutional buyers.
Market Restraints
- LED driver IC supply concentration:Regional semiconductor partners in Taiwan and South Korea control captive sourcing channels, exposing assemblers to allocation constraints during demand spikes.
- Outdoor licensing friction:The Ministry of Information and Communications requires site-specific permits for public-facing advertising displays, extending deployment timelines by four to eight weeks.
- LCD panel input cost volatility:Glass substrate and polarizer prices fluctuate with global display panel cycles, compressing margin predictability for indoor signage integrators.
Strategic Opportunities
- Central Highlands hospitality corridor:Emerging resort developments in Lam Dong and Dak Lak provinces remain underscreened relative to coastal markets, offering first-mover positioning for outdoor-rated LED systems.
- Touch-enabled wayfinding convergence:Integration of capacitive touch layers with wayfinding software is opening self-service kiosk deployments across university campuses and medical facilities.
- Cybersecurity protocol compliance:The ministry's cloud-connected signage security mandates are creating certified-system preferences that favor domestic integrators with localized server infrastructure.
Industry Challenges
- Embedded systems firmware development:Shortage of engineers fluent in real-time operating systems for media player integration is delaying product certification cycles.
- Legacy static network displacement:Retailers with existing poster frame contracts face contractual friction and site access renegotiation when transitioning to powered digital installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Digital Signage Market |
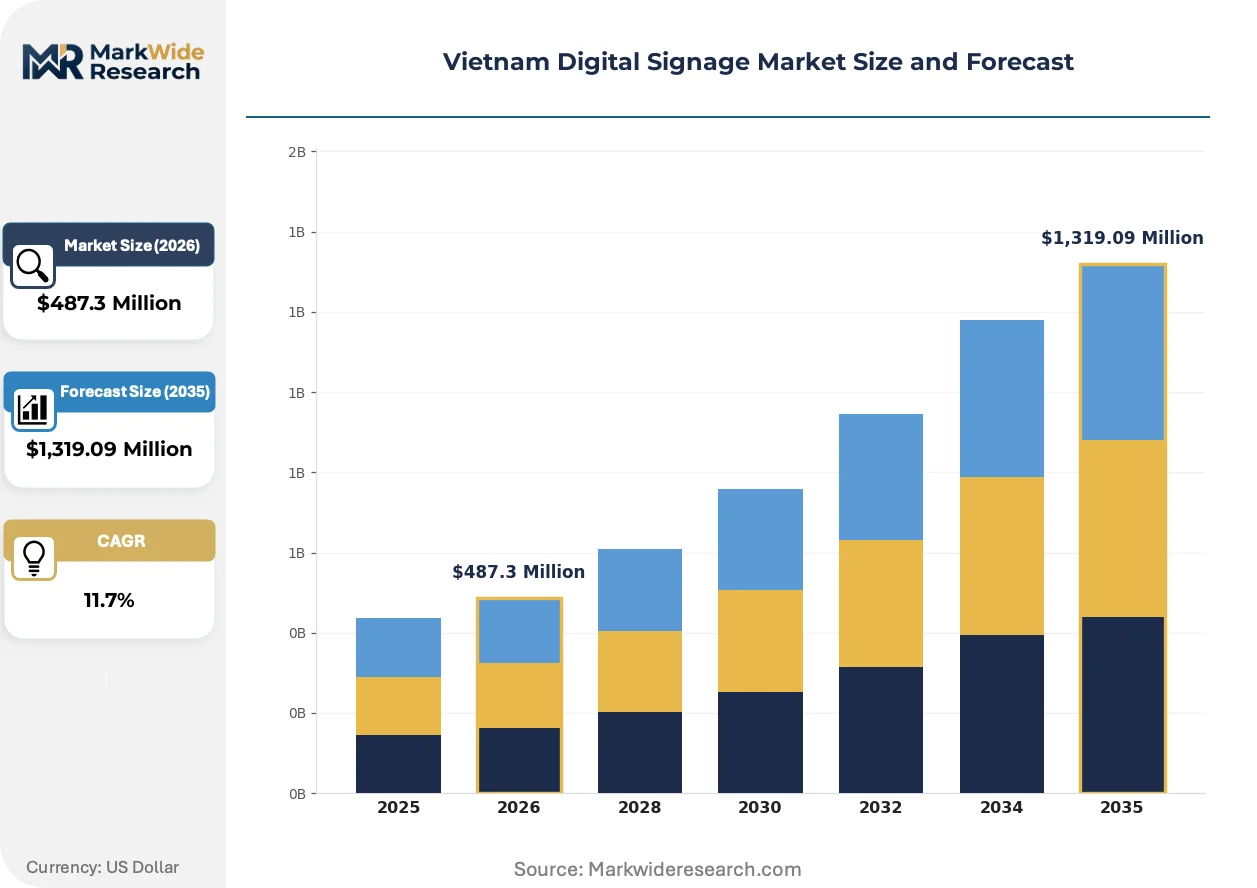
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
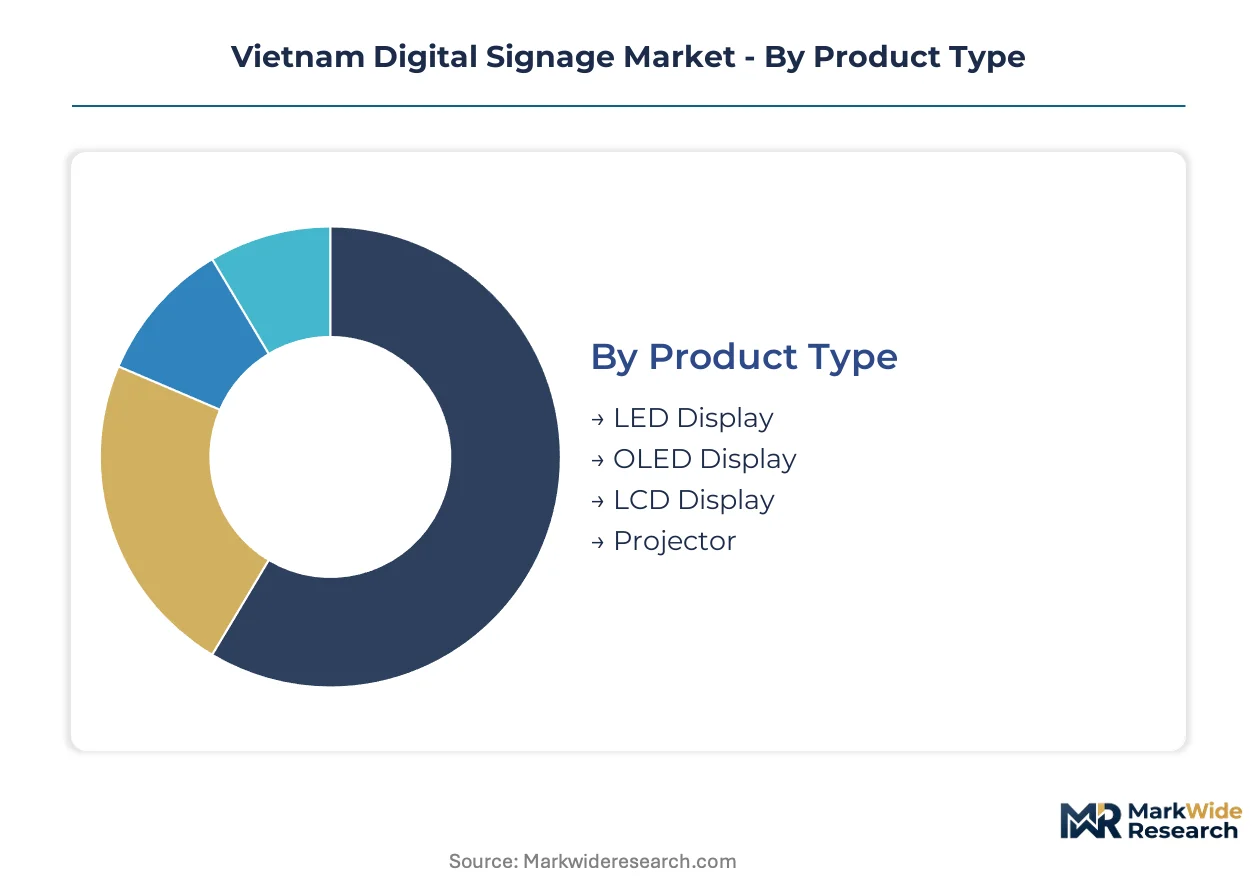
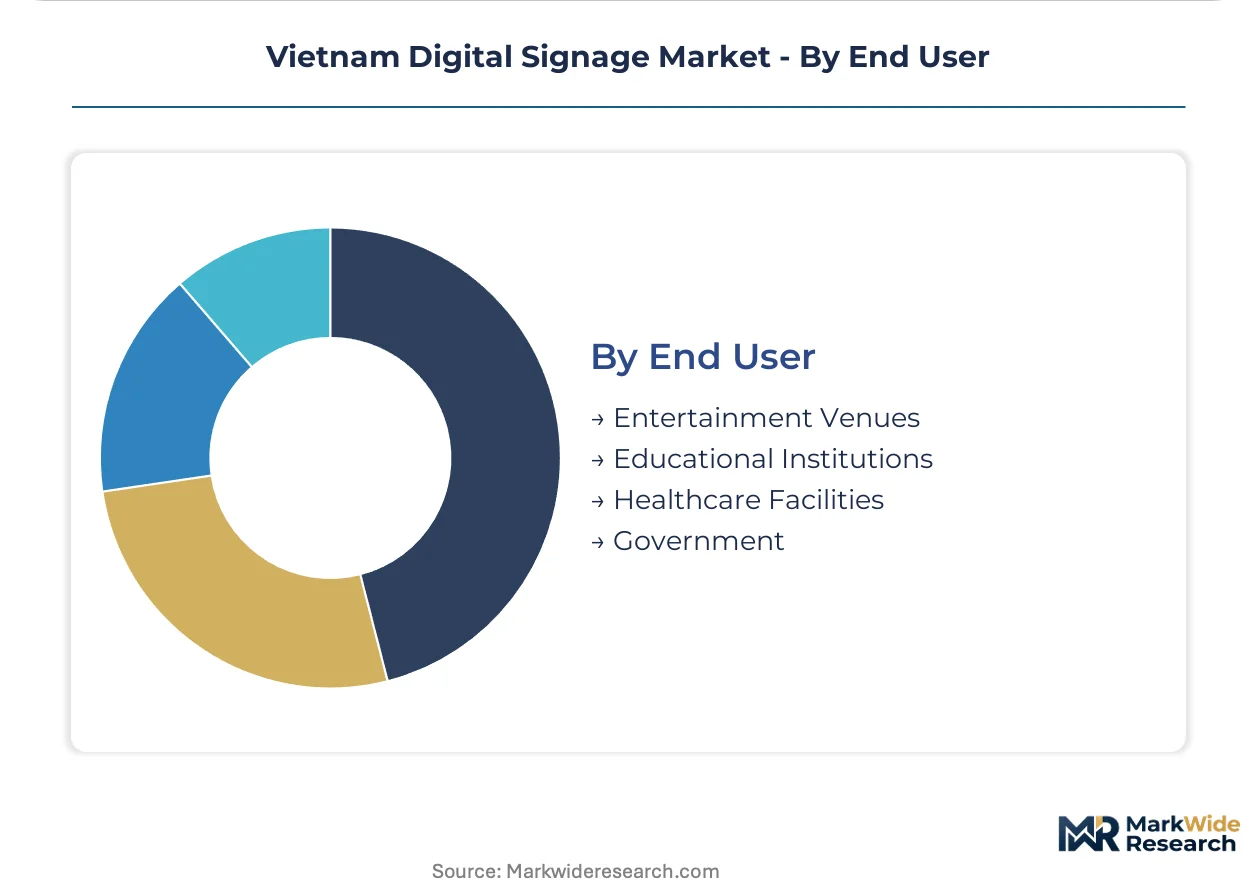
| Segmentation | Product Type: LED Display, OLED Display, LCD Display, Projector Application: Retail, Transportation, Hospitality, Corporate Technology: Interactive, Non-Interactive, Networked, Standalone End User: Entertainment Venues, Educational Institutions, Healthcare Facilities, Government |
| Companies Covered | Intel Corporation, Net & Com Integrated Telecom, NEC Corporation, Sony Group Corporation, Panasonic Corporation, LG Electronics, AT&T Inc., Vodatel Integrated Solutions Vietnam, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Digital Signage Market Strategic Shifts
Edge computing architectures are redistributing processing loads across Vietnam's signage networks, reducing latency for interactive applications while complicating centralized content governance.
System-on-chip display controllers with integrated Android or Linux environments are decentralizing media player functionality directly into panel electronics, eliminating separate set-top box procurement for retail chains and educational institutions deploying fifty-plus unit networks.
Vietnam's Ministry of Information and Communications is tightening content broadcasting standards for public digital displays, requiring encrypted transmission protocols and audit logging that increase hardware BOM costs by fifteen to twenty percent while creating compliance differentiation for certified domestic assemblers.
Buying committees at retail and hospitality groups are consolidating vendor relationships from fragmented display, software, and maintenance contracts toward single-source managed service agreements, compressing supplier margins in Ho Chi Minh City and Hanoi while elevating recurring revenue visibility for integrated platform providers.
Vietnam Digital Signage Market Segmentation
Vietnam's digital signage market fragments across product technologies, deployment contexts, and connectivity architectures. Procurement committees at retail chains and hospitality groups weigh brightness specifications against content management complexity when segmenting vendor shortlists.
Product Type:
Panel sourcing concentrates among Samsung and LG display fabs serving northern Vietnam assembly lines, with LED module costs declining fastest.
- LED Display:Direct-view LED panels with pixel pitches from 1.2mm to 10mm deliver 2,500 to 5,000 nits for outdoor visibility. Luxury hotel developments in Da Nang specify large-format LED walls for lobby installations, driven by modular scalability and falling per-unit costs from regional semiconductor partnerships.
- OLED Display:Self-emitting diode technology achieves contrast ratios exceeding 1,000,000:1 with sub-5mm panel thickness. Corporate headquarters in Ho Chi Minh City deploy OLED screens for executive reception areas, where slim form factors justify premium expenditure despite limited regional supply.
- LCD Display:Transmissive liquid crystal panels with LED edge-lit backlighting dominate indoor retail deployments.
- Projector:Laser-phosphor and lamp-based projection systems serve temporary event installations and budget-constrained educational buyers.
LED Display absorbs the bulk of installed capacity; OLED Display is expanding most quickly in hospitality premium segments.
Application:
Demand concentrates where foot traffic density supports advertising revenue models or operational communication requirements.
- Retail:Networked screen deployments across Ho Chi Minh City and Hanoi shopping centers enable dynamic pricing and promotional rotation. Department store chains are replacing static poster networks with 46-inch to 55-inch LCD arrays, pressured by competitive screen densification.
- Hospitality:Large-format installations serve wayfinding, conference scheduling, and brand storytelling functions. Resort developments in Phu Quoc specify outdoor-rated LED for poolside entertainment, constrained by Ministry of Information and Communications licensing timelines.
- Transportation:Digital wayfinding and advertising screens deploy at Tan Son Nhat International Airport and Hanoi railway terminals.
- Corporate:Internal communication networks and visitor management displays serve headquarters and manufacturing facilities.
Retail captures the largest deployment volumes; Hospitality is gaining share fastest as coastal resort construction accelerates.
Technology:
System architecture choices determine content update latency, interactivity capability, and cybersecurity compliance burden.
- Interactive:Capacitive touch layers integrated with wayfinding software enable self-service kiosk deployments. University campuses in Hanoi and medical facilities are adopting touch-enabled directories, displacing static directory boards.
- Networked:Cloud-connected systems with encrypted transmission protocols meet Ministry of Information and Communications data residency mandates. Retail chains favor managed service agreements with localized server infrastructure to satisfy audit logging requirements.
- Non-Interactive:Passive playback systems without user input capability serve cost-sensitive budget tiers.
- Standalone:USB or SD-card updated displays operate without persistent network connectivity for remote or security-sensitive locations.
Networked systems dominate new procurement; Interactive configurations are climbing the fastest as touch layer costs decline.
End User:
Budget authority and procurement sophistication vary sharply across institutional buyer categories.
- Entertainment Venues:Cinemas, bowling centers, and karaoke establishments deploy promotional screens and queue management displays.
- Educational Institutions:Universities and K-12 schools adopt interactive whiteboards and campus wayfinding kiosks. Foreign university branch campuses in Ho Chi Minh City specify high-brightness outdoor LED for sports facility scoreboards, constrained by embedded systems firmware development bottlenecks.
- Healthcare Facilities:Hospitals and clinics install patient queue management and wayfinding systems. Public hospitals face extended procurement cycles under Ministry of Health equipment tendering rules.
- Government:Administrative buildings and public service centers deploy citizen information displays subject to national standards body energy efficiency compliance.
Educational Institutions absorb the bulk of interactive technology shipments; Healthcare Facilities are expanding most quickly as hospital construction accelerates in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel fabs in northern Vietnam supply downstream assembly operations across Southeast Asia. Regional semiconductor partnerships in Taiwan and South Korea feed LED driver IC sourcing channels. The Ministry of Information and Communications enforces data residency requirements that reshape cross-border content delivery infrastructure.
Thailand
Bangkok retail developers deploy large-format LED installations in shopping districts along Sukhumvit Road. The country's national telecommunications regulator mandates cybersecurity certification for cloud-connected public displays. Industrial estates in Eastern Economic Corridor zones attract signage assembly joint ventures seeking ASEAN market access.
Singapore
Financial services headquarters specify premium OLED lobby displays for client reception environments. The Infocomm Media Development Authority enforces strict content broadcasting standards for outdoor digital advertising networks. Marina Bay commercial developments concentrate demand for high-brightness outdoor-rated systems with integrated wayfinding software.
Indonesia
Jakarta shopping mall operators replace static poster networks with networked LCD arrays for dynamic promotional content. The Ministry of Communication and Informatics requires licensing for public-facing advertising displays in urban centers. Batam free trade zone electronics assemblers source display modules from Vietnamese component suppliers.
Malaysia
Iskandar Malaysia special economic zone hospitality projects specify outdoor LED installations for resort entertainment venues. The Malaysian Communications and Multimedia Commission aligns equipment standards with regional ASEAN harmonization frameworks. Penang industrial parks host contract manufacturers expanding dedicated display module production lines.
Vietnam Digital Signage Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hospitality specialization and interactive software integration. The vendor base concentrates around three strategic archetypes: integrated electronics conglomerates with captive display fabs, domestic system integrators with localized server infrastructure, and regional telecom providers bundling connectivity with managed display services. Competitive positioning hardens through backward integration into LED driver semiconductor sourcing and geographic expansion into underscreened provincial markets.
Among Korea-based electronics conglomerates, Samsung Electronics and LG Electronics exemplify integrated manufacturing archetypes with upstream control over panel production. Panasonic Corporation represents the industrial-grade systems tier with thermal management specialization for tropical deployment conditions. NEC Corporation occupies a position within the enterprise solutions segment, anchoring corporate and institutional buyer relationships through managed service frameworks.
| Leading Market Players |
|---|
| Intel Corporation |
| Net & Com Integrated Telecom |
| NEC Corporation |
| Sony Group Corporation |
| Panasonic Corporation |
| LG Electronics |
| AT&T Inc. |
| Vodatel Integrated Solutions Vietnam |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent concentration in northern Vietnam's Bac Ninh and Bac Giang provinces feeds labor-cost differentials that widen pricing-tier spreads between premium certified systems and commodity display assemblies.
Pricing Analysis
Extended warranty and cloud-content subscription bundling separates premium-tier domestic integrators from unbundled transactional hardware vendors. Pricing stratifies across premium, standard, and economy tiers based on Ministry of Information and Communications cybersecurity certification status and localized server infrastructure presence. Cost compression in economy LCD segments is intensifying because glass substrate input volatility transfers directly to integrator margins. Hospitality buyers in Da Nang and Phu Quoc exhibit lowest price sensitivity due to brand-experience budgets, while educational institutions face procurement constraints that favor economy-tier standalone systems.
Supply Chain Analysis
Inbound freight costs from Taiwan and South Korea for LED driver ICs constitute a material landed-cost component for northern Vietnam assembly operations. Panel sourcing draws from Samsung and LG display fabs in Thai Nguyen province, while semiconductor inputs rest on regional partners in Hsinchu and Seoul. Single-source vulnerability in driver IC allocation channels exposes assemblers to demand-spike rationing. Distribution runs through domestic system integrators with localized content management infrastructure, bypassing direct brand-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's digital signage sector functions as a cost-of-compliance market where Ministry of Information and Communications data residency mandates erect barrier-to-entry moats favoring certified domestic integrators over unlicensed hardware importers.
For Market Incumbents: Cement certification-derived pricing power by deepening captive LED driver IC sourcing relationships with Taiwan semiconductor partners, insulating against allocation constraints during hospitality construction surges. Fortify recurring revenue visibility through single-source managed service agreements that consolidate fragmented display, software, and maintenance contracts for retail chains in Ho Chi Minh City and Hanoi.
For New Entrants and Emerging Players: E-commerce platform routes into Central Highlands hospitality corridors in Lam Dong and Dak Lak provinces bypass incumbent field-sales density in coastal markets. Target emerging resort developments with outdoor-rated LED systems specified for poolside entertainment, leveraging first-mover positioning before licensing friction extends deployment timelines. Pursue university campus touch-enabled wayfinding kiosk deployments as the most penetrable interactive segment.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic integrators possessing localized server infrastructure given Ministry of Information and Communications audit logging mandates that favor compliant players. Long-term viability centers on recurring-revenue managed service models rather than transactional hardware margins. Monitor hospitality construction permit issuance velocity in Da Nang and Phu Quoc as inflection indicator for demand-cluster formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Ministry of Information and Communications compliance creates certified-system preference among retail and hospitality buyers. |
| Localized Server Infrastructure Deployment | Data residency mandates require domestic content hosting, elevating integrators with captive cloud infrastructure. |
| Touch-Enabled Wayfinding Integration | Capacitive touch layer convergence with campus directory software displaces static poster networks in Hanoi medical facilities. |
| Central Highlands Geographic Expansion | Underscreened resort developments in Lam Dong and Dak Lak offer first-mover positioning for outdoor-rated LED systems. |
| Managed Service Agreement Consolidation | Single-source contracts compress supplier margins while elevating recurring revenue visibility for integrated platform providers. |
Study Parameters
Multi-period observation of screen deployment volumes, content management software licensing patterns, and Ministry of Information and Communications enforcement actions anchored the trend analysis, supplemented by interviews with procurement directors at retail chains, hospitality technology managers, system integrators, LED module assemblers, and semiconductor sourcing leads. Secondary validation drew from customs import records, national standards body energy efficiency filings, construction permit databases for hospitality developments, and ASEAN harmonization framework documentation. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Input-output matrix modeling connected hospitality construction pipeline data, retail square footage expansion rates, and technology substitution curves to generate segment-level projections across the analysis window. Segmentation dimensions included product technology, application context, connectivity architecture, and end-user procurement sophistication. CAGRs were derived from fitted growth curves applied to base-year estimates, with LED module cost decline trajectories and interactive technology penetration rates serving as key forecast inputs.
Inputs from procurement directors and construction permit databases were available through the study window; gaps in real-time LED driver IC allocation data introduce uncertainty bands around assembler margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Foldable Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Smartphone Display Market
Display Technologies
Global OLED Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Display Mask Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Touch Screen Film Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Global Display Controllers Market