
 Global 4K Display Resolution Market | 2026-2036
Global 4K Display Resolution Market Size, Share, and Industry Trends Forecast 2026-2036
Global 4K Display Resolution Market Analysis
Chinese panel fabrication capacity is recalibrating global supply dynamics for 4K display modules. Samsung Electronics Co. Ltd leverages vertical integration across semiconductor and display divisions to sustain premium OLED output. BOE Technology Group anchors mainland China's supply base through massive Gen 10.5 fab operations. LG Display Co. Ltd differentiates via white OLED technology leadership in large-format television panels.
4K display resolution denotes a pixel matrix of 3840 × 2160, delivering four times the density of 1080p Full HD and enabling granular image reproduction at viewing distances below two meters. The specification serves broadcast studios, medical imaging suites, and consumer living rooms where visual fidelity determines operational or experiential value. LCD technology occupies the volume tier in televisions and monitors, while OLED captures margin pools in premium residential and commercial segments. Streaming devices represent the fastest-growing product category as over-the-top platforms expand 4K content catalogs. The educational end-user segment remains underpenetrated relative to entertainment and commercial verticals.
EPA energy conservation standards in the United States, EU Ecodesign requirements under the EU Green Deal, and Japan's Top Runner program collectively mandate display efficiency thresholds that OEMs must satisfy for market access. China's GB standards for electronic product energy consumption add compliance complexity for panel imports. Stakeholders must monitor regulatory tightening on standby power and cadmium content, as these parameters will determine which technology platforms retain market access across major economies.
Market Dynamics
Panel fabrication concentration in China and South Korea is compressing margins for downstream OEMs while creating captive supply advantages for integrated electronics conglomerates. This supply-side consolidation is the dominant structural force reshaping competitive positioning in 4K display modules.
Growth Catalysts
- EU Ecodesign Requirements:Energy efficiency mandates under the EU Green Deal are accelerating replacement cycles for legacy televisions and commercial displays across member states.
- Medical Imaging Suites:Diagnostic radiology departments are standardizing on 4K resolution for surgical monitors and PACS workstations to enable sub-millimeter pathology detection.
- Over-the-Top Streaming:Content libraries from Netflix, Amazon Prime Video, and Disney+ are expanding native 4K catalogs, pulling hardware upgrades in residential living rooms.
Market Restraints
- OLED Input Cost Volatility:Organic emitter material prices fluctuate with rare earth supply constraints from Chinese processing facilities.
- South Korean Supply Concentration:Samsung Display and LG Display control over 70% of large-format OLED capacity, creating single-source risk for premium television brands.
- Quantum Dot Substitution:Mini-LED backlit LCD panels with quantum dot enhancement are capturing price-sensitive segments that previously demanded OLED.
Strategic Opportunities
- India Educational Infrastructure:Smart classroom initiatives under the country's digital education mission remain underpenetrated for 4K interactive displays relative to entertainment verticals.
- Japan Top Runner Program:Stringent efficiency benchmarks are creating first-mover advantages for manufacturers with advanced backlight dimming architectures.
- AI-Enhanced Upscaling:Machine learning silicon from MediaTek and Realtek is converging with display controllers to enable near-4K quality from legacy 1080p content libraries.
Industry Challenges
- Gen 10.5 Fab Capex Burden:Glass substrate manufacturing at 2940mm × 3370mm scale demands $4-5 billion per production line, restricting new entrants.
- HDMI 2.1 Certification Complexity:48Gbps bandwidth validation for 4K at 120Hz refresh rates extends product launch timelines by 4-6 months.
- Legacy Broadcast Infrastructure:Regional cable operators in Southeast Asia and Latin America maintain 1080i transmission standards, fragmenting content availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 4K Display Resolution Market |
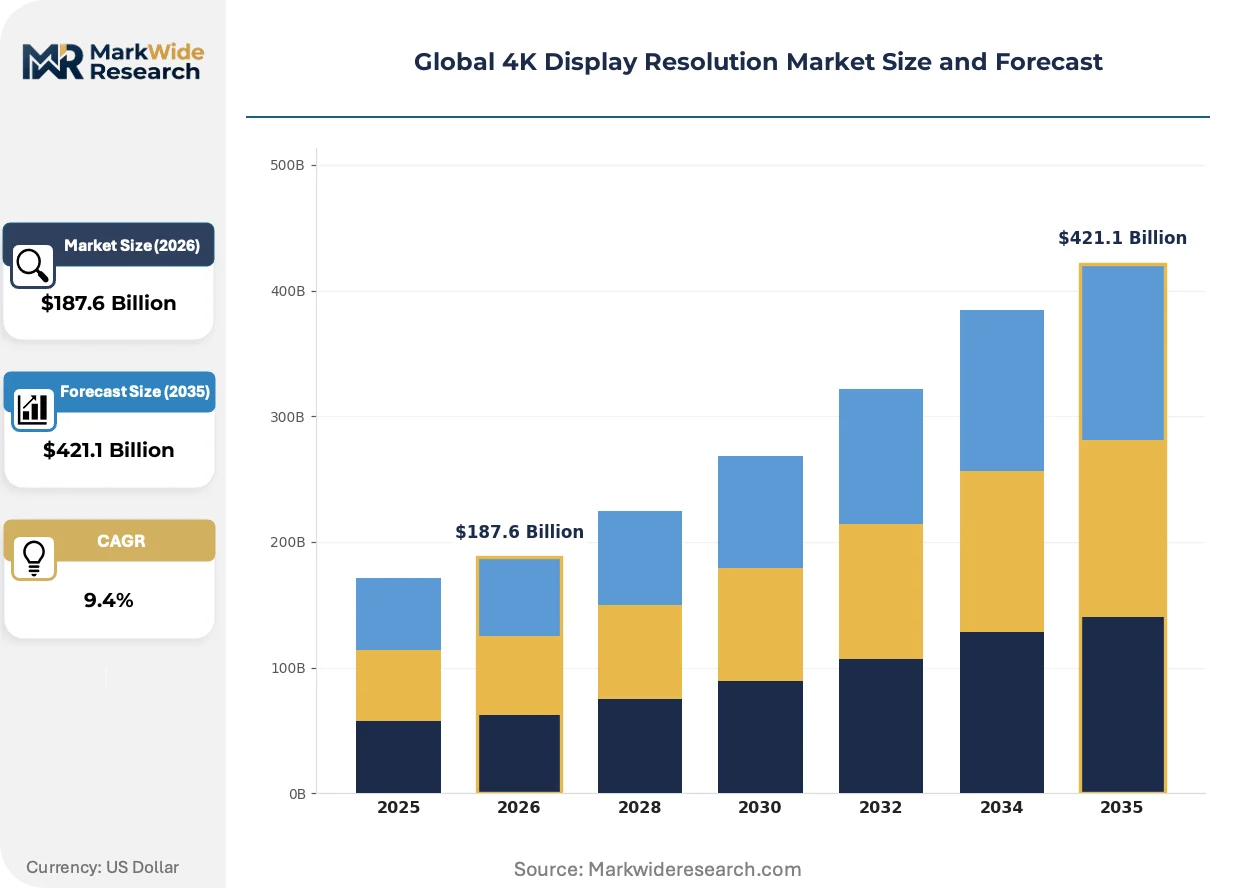
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Monitors, Projectors, Streaming Devices Technology: LCD, OLED, LED, DLP End User: Residential, Commercial, Educational, Entertainment Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Toshiba Corporation, Panasonic Corporation, Samsung Electronics Co. Ltd, AU Optronics, BOE Technology Group, LG Display Co. Ltd, Sharp Corporation, Innolux Corporation, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 4K Display Resolution Market Emerging Trajectories
Display controller semiconductor architectures are automating image processing pipelines. Three convergent developments are compressing traditional hardware boundaries while opening new application categories for 4K resolution.
Local dimming algorithms embedded in AI accelerator silicon are automating zone-by-zone backlight control. Medical imaging OEMs are adopting these controllers for diagnostic monitors requiring precise luminance uniformity. The technology is automating the calibration workflows that previously required manual technician intervention in radiology departments.
China's GB standards for electronic product energy consumption are tightening standby power thresholds for televisions above 65 inches. MIIT compliance deadlines in 2025 are forcing panel makers to redesign driver IC architectures. Premium residential segments in Shanghai and Shenzhen are absorbing efficiency premiums faster than export markets.
Enterprise procurement teams are consolidating display vendor relationships around managed service contracts bundling hardware, installation, and refresh cycles. Commercial integrators are displacing traditional AV distributors in North American corporate rollouts. This concentration is most visible in Fortune 500 headquarters relocations where facilities teams standardize on single-source 4K signage platforms.
Global 4K Display Resolution Market Segmentation
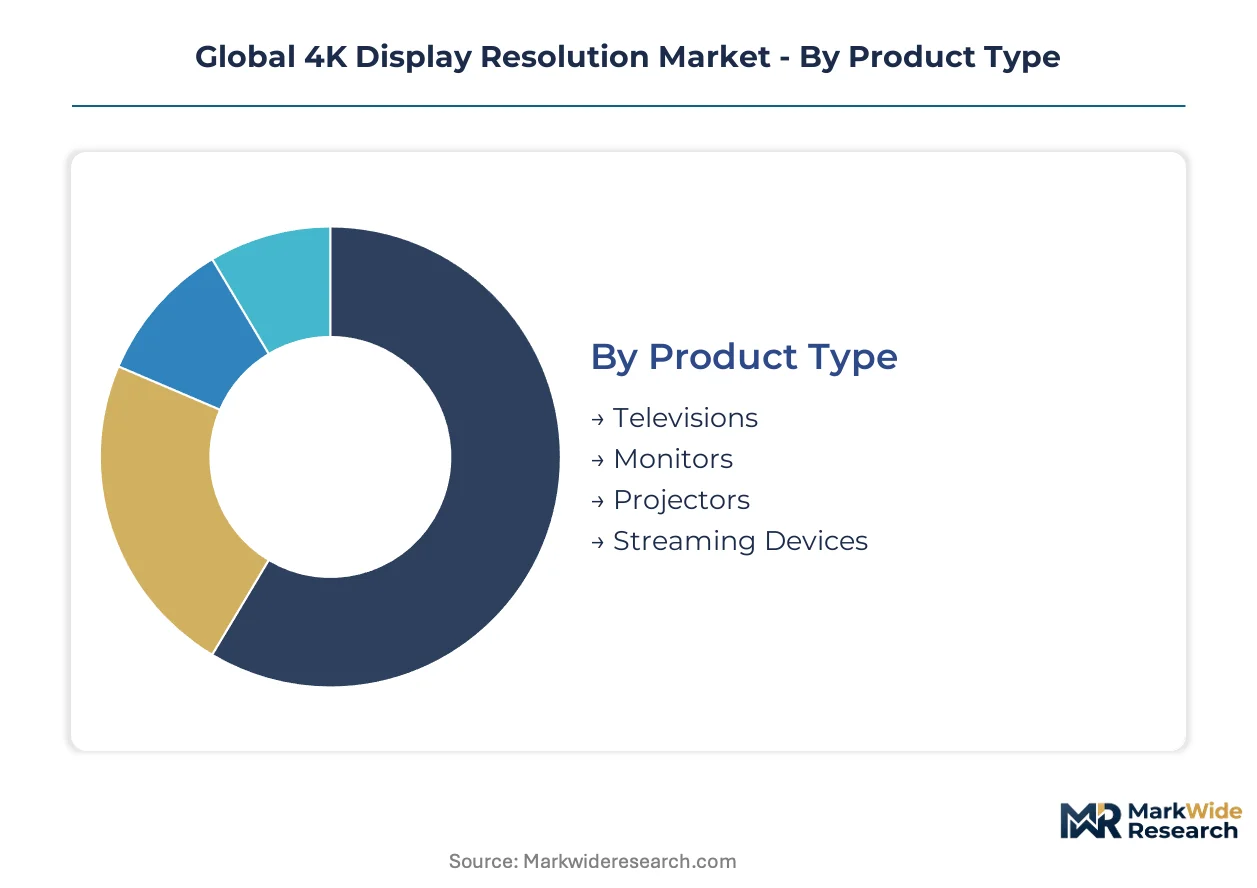
4K display markets fragment across hardware form factors, underlying light-engine technologies, and procurement contexts that determine specification requirements. Segmentation reveals where standardization yields economies of scale versus where customization commands premium positioning.
Product Type:
Standardization dominates televisions and monitors, while projectors and streaming devices occupy opposite ends of the customization spectrum.
- Televisions:LCD and OLED panels at 55-inch to 85-inch diagonal sizes anchor residential volume. China's Gen 10.5 fabs in Hefei and Wuhan supply glass substrates that compress per-unit costs for mainstream living room deployments.
- Monitors:Desktop displays at 27-inch to 32-inch target professional workstations and gaming setups. Medical imaging suites in Germany and Japan specify surgical monitors with 4K resolution for sub-millimeter pathology detection.
- Projectors:DLP and laser-phosphor engines serve commercial installations requiring scalable image sizes.
- Streaming Devices:HDMI 2.1-enabled set-top boxes and sticks pull hardware upgrades as Netflix and Disney+ expand native 4K catalogs.
Leading the category by volume: Televisions. Growing fastest: Streaming Devices.
Technology:
Cost tier stratification separates mature LCD volume from OLED margin capture, with LED and DLP occupying specialized niches.
- LCD:Twisted nematic and in-plane switching variants with LED backlighting dominate price-sensitive segments. BOE Technology Group and CSOT supply panels that satisfy EU Ecodesign efficiency thresholds for mass-market televisions.
- OLED:Organic emitter stacks enable self-emissive pixels with infinite contrast ratios. Samsung Display and LG Display control large-format capacity, creating single-source risk for premium television brands seeking white OLED or QD-OLED configurations.
- LED:Direct-view LED walls serve digital signage and command-center applications requiring seamless scaling.
- DLP:Digital micromirror devices from Texas Instruments power cinema projectors and commercial installation markets.
Highest shipment volumes: LCD. Steepest expansion trajectory: OLED in premium residential segments.
End User:
Application maturity varies sharply, with entertainment and commercial verticals saturated while educational infrastructure lags.
- Residential:Living room upgrades driven by streaming platform content expansion. Over-the-top services from Amazon Prime Video and Disney+ pull hardware refreshes as 4K catalogs deepen.
- Commercial:Corporate signage, retail digital displays, and hospitality installations. Fortune 500 headquarters relocations in the United States standardize on single-source 4K signage platforms with managed service contracts.
- Educational:Smart classroom initiatives remain underpenetrated relative to entertainment verticals. India's digital education mission represents untapped demand for interactive 4K displays.
- Entertainment:Cinema projectors, broadcast studios, and gaming venues where visual fidelity determines experiential value. Post-production houses in Los Angeles and London standardize on 4K reference monitors.
Deepest market penetration: Entertainment and Commercial. Gaining share fastest: Educational infrastructure in emerging economies.
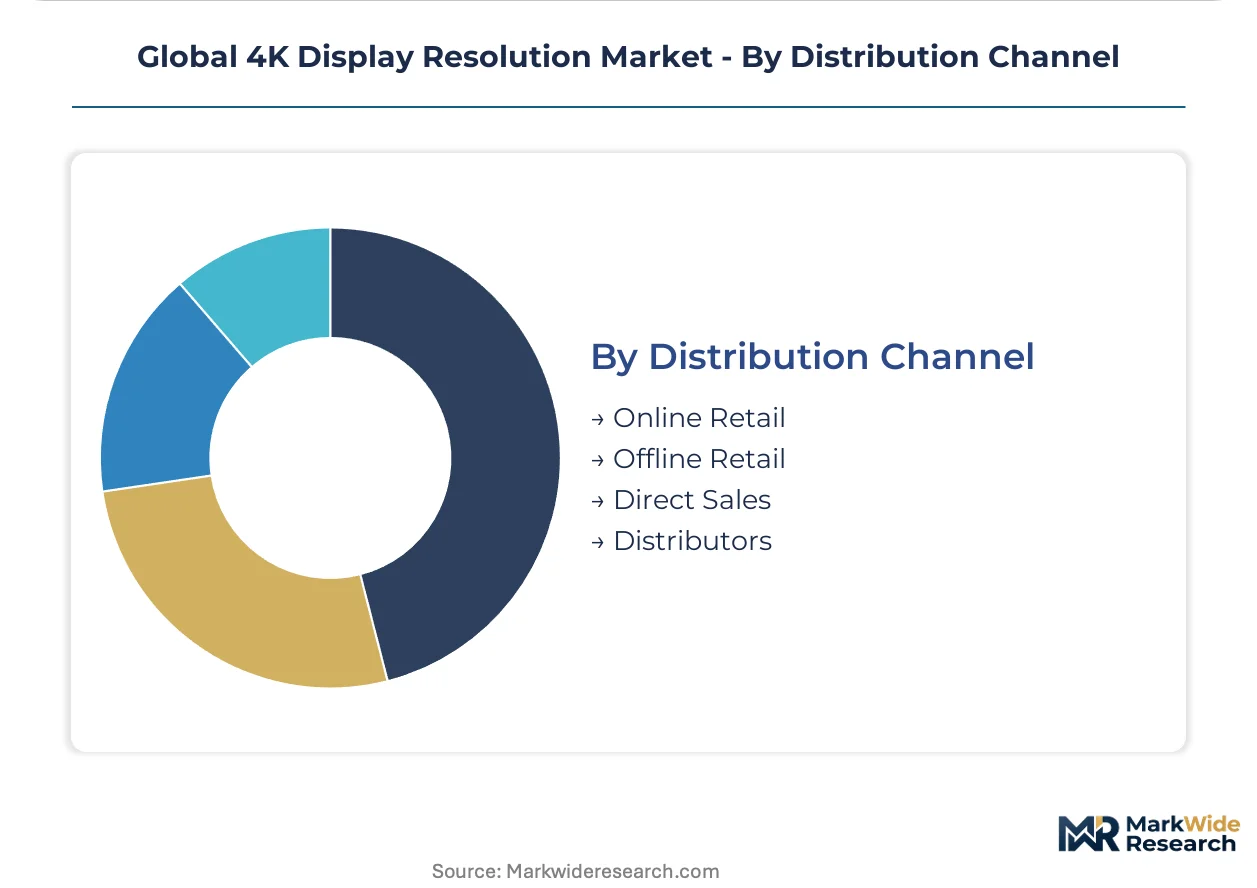
Distribution Channel:
Customer type and purchase scale determine whether transactions flow through retail intermediaries or direct procurement relationships.
- Online Retail:E-commerce platforms serve price-comparing consumers and small-business buyers. Amazon and regional marketplaces absorb volume from brick-and-mortar decline in North America and Europe.
- Offline Retail:Big-box electronics stores and specialty AV dealers provide tactile evaluation for premium purchases. Showroom presence matters for OLED televisions where black-level demonstration influences selection.
- Direct Sales:Enterprise procurement teams negotiate managed service contracts bundling hardware, installation, and refresh cycles. Commercial integrators displace traditional AV distributors in North American corporate rollouts.
- Distributors:Regional wholesalers serve system integrators and installation contractors with project-based demand. Inventory pooling reduces lead times for commercial deployment timelines.
Dominant transaction mode: Online Retail for consumer volume. Expanding most quickly: Direct Sales for enterprise consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing facilities in Jiangxi Province supply organic emitter precursors that Korean and Chinese panel makers consume at scale. This feedstock geography concentrates OLED chemistry expertise in East Asian manufacturing corridors.
United States
Streaming hardware upgrades and medical imaging procurement drive residential and commercial demand. EPA energy conservation standards mandate efficiency thresholds for market access. Austin and San Jose host semiconductor design clusters advancing display controller architectures.
China
Gen 10.5 fab scale and smart classroom initiatives pull LCD and interactive display volumes. MIIT compliance deadlines on standby power force driver IC redesigns. Hefei and Wuhan anchor glass substrate manufacturing at 2940mm × 3370mm scale.
Germany
Diagnostic radiology standardization and corporate signage consolidation sustain premium monitor procurement. EU Ecodesign requirements under the Green Deal accelerate replacement cycles for legacy commercial displays. Dresden's semiconductor cluster supports precision lithography for display driver chips.
South Korea
QD-OLED television exports and white OLED technology leadership capture premium residential margins. The country's national industrial regulator maintains efficiency benchmarks through the Top Runner program. Gumi and Paju concentrate large-format OLED fabrication capacity.
Japan
Broadcast studio reference monitors and cinema projection equipment demand precision 4K panels. METI efficiency mandates through the Top Runner program shape technology roadmaps. Osaka and Nagoya house optical component suppliers serving medical imaging OEMs.
Global 4K Display Resolution Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in AI-enhanced upscaling silicon and managed service contracts. The vendor base stratifies across integrated conglomerates with captive semiconductor divisions, pure-play panel fabricators, and controller semiconductor specialists. Three archetypes dominate: vertically integrated electronics groups, massive-scale Gen 10.5 fab operators, and fabless display controller designers. Capacity expansion and strategic partnerships constitute the primary competitive moves reshaping supply relationships.
Among East Asian conglomerates, Samsung Electronics Co. Ltd and LG Display Co. Ltd exemplify integrated producers with semiconductor-display synergies, while BOE Technology Group anchors the massive-scale fab archetype from mainland China. These three occupy positions across the technology spectrum from QD-OLED to Gen 10.5 LCD, representing distinct approaches to capturing margin pools in premium versus volume tiers.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd |
| AU Optronics |
| BOE Technology Group |
| LG Display Co. Ltd |
| Sharp Corporation |
| Innolux Corporation |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and South Korea anchor display panel manufacturing, compressing margins for downstream OEMs while concentrating pricing power with integrated conglomerates possessing captive semiconductor divisions. This ownership pattern ties supply discipline directly to state industrial policy objectives, creating pricing floors that resist pure commodity dynamics even as volume tiers face cost compression.
Pricing Analysis
Warranty and service bundling separates premium OLED configurations from unbundled LCD volume tiers, with Samsung Electronics and LG Display commanding 18-24 month comprehensive coverage against 12-month standard terms for mainstream panels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU Ecodesign compliance and medical imaging ISO 13485 certification commanding 15-25% uplifts. Pricing pressure stems from quantum dot-enhanced Mini-LED LCD encroaching on OLED's historical premium positioning. Enterprise procurement teams demonstrate lowest price sensitivity through managed service contracts, while educational sector buyers in emerging economies exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for 4K displays center on refurbishment streams from corporate refresh cycles in the United States and Japan, with commercial integrators recovering 27-32 inch panels for secondary educational deployment. Supply concentrates in China, South Korea, and Taiwan, with rare earth processing in Jiangxi Province feeding organic emitter precursor production. Glass substrate manufacturing draws from Corning facilities in Kentucky and South Korea, while driver IC production rests on TSMC's Taiwan foundries. Single-source vulnerability permeates large-format OLED capacity, where Samsung Display and LG Display control over 70% of global output. Distribution runs through commercial integrators displacing traditional AV distributors in North American enterprise rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panel fabrication consolidation in East Asia is forcing weaker pure-play fabricators toward distressed restructuring, with Gen 10.5 fab capex burdens eliminating sub-scale competitors unable to amortize $4-5 billion production line investments.
For Market Incumbents: Hedge against quantum dot LCD substitution by accelerating QD-OLED capacity ramps in South Korea while securing long-term rare earth supply agreements with Jiangxi processors. Defensive consolidation through backward integration into driver IC design at Austin and Dresden semiconductor clusters reduces exposure to foundry allocation volatility. Priority lever rests on medical imaging certification pipelines where diagnostic radiology standardization creates sticky demand. For New Entrants and Emerging Players: Commercial integrators represent the most accessible channel partner type for bypassing entrenched distributor relationships in North American corporate signage. White-space targets include India's smart classroom infrastructure and Japan's broadcast studio reference monitor refresh cycles. Go-to-market execution should emphasize managed service contract bundling to match Fortune 500 procurement consolidation patterns. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless display controller specialists with AI upscaling silicon roadmaps in Taiwan and Israel, where MediaTek and Realtek competitive dynamics create acquisition opportunities. Long-term viability through the projection horizon hinges on software-defined display architectures converging edge processing with cloud-rendered content. Signal to monitor: MIIT compliance deadline acceleration in China forcing driver IC redesigns and creating technology obsolescence windows for non-compliant inventory positions.| Strategic Initiative | Industry Significance |
|---|---|
| QD-OLED Capacity Expansion | Samsung Display captures premium residential margins as white OLED differentiation erodes. |
| Backward Integration into Driver ICs | BOE Technology reduces foundry dependency through Dresden lithography partnerships. |
| Medical Imaging Certification Investment | Surgical monitor OEMs lock in radiology department standardization decisions. |
| Managed Service Contract Bundling | Commercial integrators displace AV distributors in Fortune 500 headquarters relocations. |
| AI-Enhanced Upscaling Silicon Development | MediaTek and Realtek converge machine learning with display controllers for legacy content. |
Methodological Framework
SEC 10-K filings, EU Ecodesign regulatory databases, and MIIT compliance bulletins formed the secondary backbone, supplemented by customs trade data tracking glass substrate and driver IC flows. Primary interviews with display controller semiconductor designers, commercial integrators, and hospital biomedical engineering directors validated shipment assumptions and replacement cycle timing. Triangulation across bottom-up panel shipment aggregation and top-down consumer electronics revenue attribution anchored volume estimates.
Bottom-up modeling tracked unit economics across LCD, OLED, LED, and DLP technology tiers, while top-down analysis calibrated aggregate market expansion against streaming platform content library growth and medical imaging procurement budgets. Segmentation dimensions included product type, underlying light-engine technology, end-user vertical, and distribution channel complexity. CAGRs derived from installed base penetration curves and replacement cycle compression under efficiency regulations. Forecast inputs incorporated HDMI 2.1 certification timelines and regional broadcast infrastructure upgrade schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth supply chains and abrupt shifts in streaming platform content investment priorities. Forecasts reflect assumptions around regulatory implementation timelines and technology substitution elasticities that could revise materially. Practitioners should monitor EU Ecodesign enforcement intensity and China dual carbon goal acceleration for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
4K Technology Market
Display Technologies
Backlit Displays Market
Display Technologies
Global Wearable Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
AMOLED Display Market
Display Technologies
Global Medical Display Market
Display Technologies
Smartphone Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Video Projector Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
United States Microdisplay Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Glass-Free HD 3D Display Market