
 Global Plasma Pulse Technology Market | 2026-2036
Global Plasma Pulse Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Pulse Technology Market Outlook
The EU Green Deal is broadening the addressable market for plasma pulse well stimulation as European operators face binding decarbonization mandates. ExxonMobil leverages its Permian Basin infrastructure to pilot plasma pulse completions across mature acreage. Halliburton Energy Services anchors its technology portfolio with proprietary plasma pulse tools for unconventional reservoirs. Schlumberger Limited differentiates through integrated diagnostics that pair plasma pulse delivery with real-time formation evaluation.
Plasma pulse technology generates high-energy electrical discharges in fluid media to create shock waves that fracture rock formations or modify material surfaces without chemical additives. Systems typically operate at pulse frequencies between 1 Hz and 100 Hz with peak voltages exceeding 100 kV, enabling controlled energy delivery for oilfield stimulation, surface treatment, and biomedical applications. Ultra-high voltage systems lead deployment in oil and gas well intervention where depth and formation hardness demand maximum energy density. Surface treatment applications in electronics manufacturing represent the fastest-expanding segment as miniaturization drives demand for precision cleaning and adhesion enhancement without thermal damage.
EPA regulations under the Clean Air Act constrain flaring and venting from conventional stimulation operations, indirectly advantaging plasma pulse methods that eliminate combustion at the wellhead. REACH compliance in Europe restricts chemical additives in hydraulic fracturing fluids, creating regulatory headroom for non-chemical alternatives. China's MEE enforces stricter groundwater protection standards that complicate traditional fracturing permits in the Sichuan Basin. Stakeholders must monitor how rapidly evolving carbon border mechanisms reshape the cost calculus of well intervention technologies across jurisdictions.
Market Dynamics
Binding decarbonization mandates across multiple jurisdictions are redirecting capital from hydraulic fracturing toward non-chemical well stimulation methods, compressing deployment timelines for plasma pulse systems in mature oilfields.
Growth Catalysts
- EPA Clean Air Act enforcement:Constraints on flaring and venting from conventional stimulation operations create regulatory headroom for plasma pulse methods that eliminate combustion at the wellhead.
- Electronics miniaturization:Semiconductor manufacturers in Taiwan and South Korea are adopting plasma surface treatment for precision cleaning without thermal damage to advanced packaging.
- Permian Basin concentration:Cost pressures in this mature US oil province accelerate operator experimentation with alternatives to chemical-intensive fracturing.
Market Restraints
- Ultra-high voltage component supply:Specialized capacitors and switching systems concentrate among a limited supplier base in Germany and Japan, creating input vulnerability.
- Formation depth limitations:Energy attenuation in deep shale reservoirs exceeding 4,500 meters constrains plasma pulse effectiveness compared to conventional perforation.
- REACH compliance costs:European chemical registration requirements for residual dielectric fluids add procedural friction to system deployment.
Strategic Opportunities
- Sichuan Basin groundwater protections:China's MEE enforcement complicates traditional fracturing permits, opening trial deployment of non-chemical alternatives.
- Biomedical application expansion:Plasma pulse sterilization for surgical instruments and wound treatment represents an emerging revenue vertical with distinct regulatory pathways.
- EU Green Deal carbon border mechanisms:Emerging import tariffs on carbon-intensive extraction methods will reprice competitive alternatives for European operators.
Industry Challenges
- High-voltage engineering talent scarcity:The specialized skill set spanning pulsed power physics and oilfield operations concentrates among aging workforce cohorts in Texas and Alberta.
- Integration with legacy wellhead infrastructure:Plasma pulse tool compatibility with existing casing designs and downhole telemetry requires case-by-case engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Pulse Technology Market |
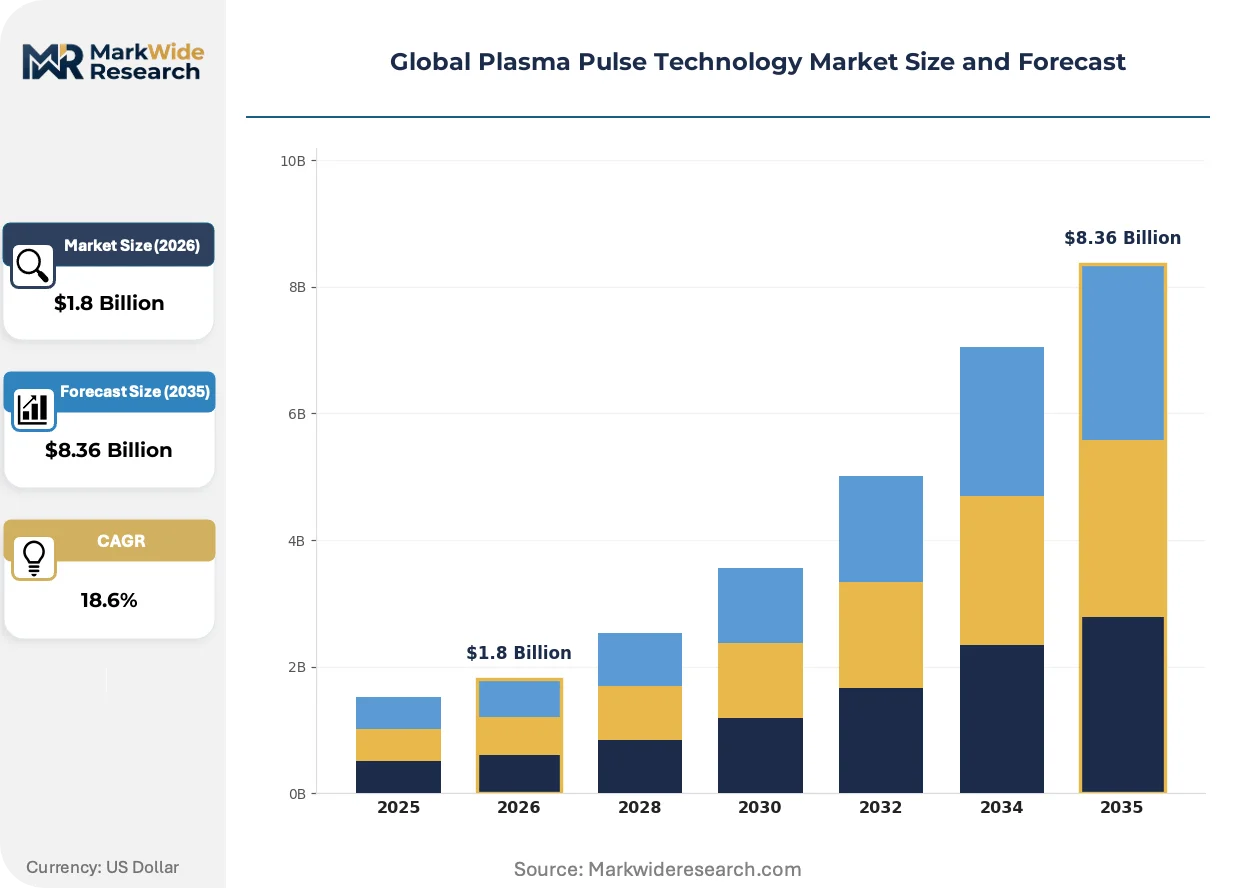
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High-Frequency, Ultra-High Voltage, Low Frequency, Microwave End User: Healthcare, Electronics, Automotive, Research Institutions Application: Surface Treatment, Material Modification, Plasma Medicine, Sterilization Deployment: On-Site, Portable, Remote, In-Lab |
| Companies Covered | ExxonMobil, TotalEnergies, Halliburton Energy Services, CNPC, Schlumberger Limited, Baker Hughes, Chevron Phillips Chemical, Plasmatreat GmbH, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Pulse Technology Market Strategic Shifts
Plasma pulse technology is crossing from oilfield niche into diversified industrial applications through voltage scaling innovations and regulatory arbitrage opportunities created by chemical restrictions.
Solid-state Marx generator architectures are replacing gas-based spark gap switches in next-generation plasma pulse systems. Electronics manufacturers in Japan and South Korea are adopting these compact platforms for inline surface treatment at 50-100 Hz pulse frequencies. The technology is converging with automated semiconductor packaging lines, compressing equipment footprints by 60% while enabling real-time process control.
The EU F-Gas Regulation is phasing down hydrofluorocarbon dielectric fluids used in conventional high-voltage equipment. Industrial gas suppliers in Germany and France are accelerating development of fluoronitrile and clean air alternatives for plasma pulse insulation. Oilfield service providers operating in the North Sea face accelerated retrofit schedules as the 2027 prohibition deadline approaches.
Equipment leasing models are displacing capital purchase arrangements among North American independent producers. Denver and Houston-based service companies now bundle plasma pulse stimulation with real-time formation diagnostics, unbundling the technology from integrated completion packages. This restructuring concentrates most visibly in the Permian and DJ Basins where operator balance sheet constraints favor operational expenditure treatment.
Global Plasma Pulse Technology Market Segmentation
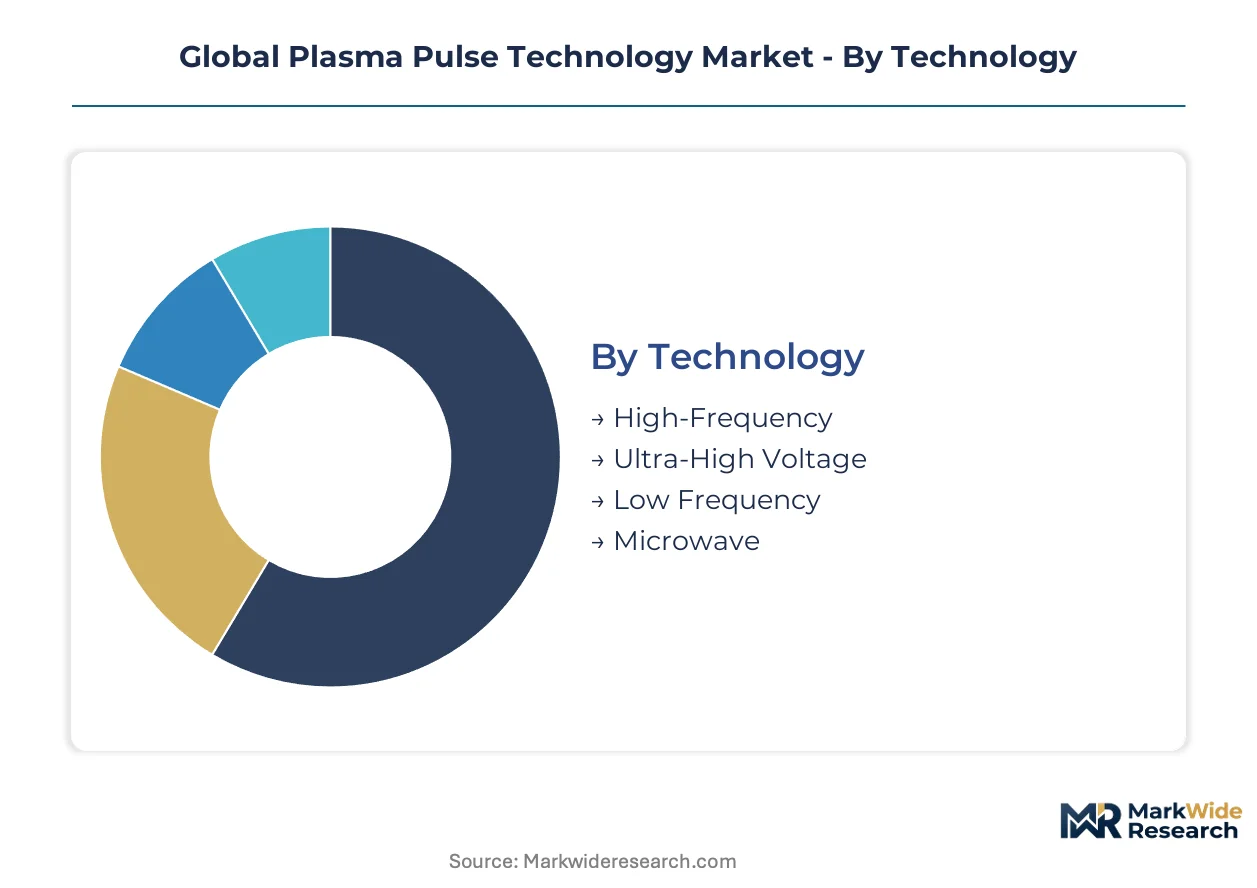
Plasma pulse technology spans divergent voltage regimes, end-use requirements, and deployment constraints that fragment commercialization strategies. Understanding how these segments interact reveals why oilfield service providers, semiconductor manufacturers, and medical device companies rarely compete directly despite sharing core pulsed power competencies.
Technology:
Ultra-high voltage systems command premium pricing and dominate energy-intensive applications, while high-frequency platforms scale through volume manufacturing for precision surface work.
- Ultra-High Voltage:Peak discharge voltages exceeding 100 kV deliver the energy density required for deep formation stimulation in oilfield intervention. Operators in the Permian Basin deploy these systems where reservoir depths exceed 3,000 meters and conventional perforation faces EPA flaring constraints.
- High-Frequency:Pulse repetition rates between 50-100 Hz enable inline processing for semiconductor packaging and electronics cleaning. Taiwanese foundries integrate these compact Marx generator architectures into automated production lines where thermal damage must be eliminated.
- Low Frequency:Sub-10 Hz operation suits large-volume material modification where processing time matters less than energy per pulse.
- Microwave:Electromagnetic excitation at gigahertz frequencies supports specialized plasma chemistry for research-grade surface functionalization.
Today's leader: Ultra-High Voltage. Tomorrow's challenger: High-Frequency.
End User:
Healthcare and electronics buyers prioritize precision and regulatory compliance, while automotive and research customers trade absolute performance for flexibility and capital efficiency.
- Electronics:Semiconductor manufacturers in South Korea and Taiwan drive demand for contamination-free surface treatment as advanced packaging shrinks feature sizes below 10 nanometers. Miniaturization mandates from chip designers force fabs toward non-thermal cleaning methods.
- Healthcare:Surgical instrument sterilization and wound treatment applications require biocompatible plasma chemistry without residual toxicity. FDA clearance pathways for plasma medical devices differ substantially from industrial equipment approvals.
- Automotive:Coating adhesion and surface activation for lightweight materials support manufacturing efficiency goals.
- Research Institutions:Academic and government laboratories pilot novel plasma chemistries with configurable pulse parameters.
Electronics currently anchors revenue concentration. Healthcare offers the steepest expansion trajectory as plasma medicine exits experimental protocols.
Application:
Surface treatment applications generate recurring revenue through consumable dielectric fluids and electrode replacement, while material modification and plasma medicine concentrate project-based capital sales.
- Surface Treatment:Precision cleaning, adhesion promotion, and functionalization for electronics manufacturing represent the most mature commercial segment. Japanese equipment suppliers dominate with integrated inline systems.
- Plasma Medicine:Therapeutic applications span cancer treatment, dermatology, and dental sterilization with distinct regulatory pathways per jurisdiction. EMA and FDA frameworks diverge on plasma-device classification.
- Material Modification:Hardening, coating deposition, and tribological property enhancement serve automotive and aerospace component manufacturers.
- Sterilization:Low-temperature plasma alternatives to autoclaving and ethylene oxide gain traction for heat-sensitive medical devices.
Surface treatment commands installed base dominance. Plasma medicine is gaining share fastest through clinical trial expansion.
Deployment:
On-site deployment for oilfield work demands ruggedized mobile power systems, while in-lab and portable configurations prioritize operator safety and measurement precision over environmental hardening.
- On-Site:Trailer-mounted or skid-based systems service well intervention in remote producing regions. Halliburton and Schlumberger deploy these units across North American shale basins where logistics costs favor localized equipment.
- In-Lab:Fixed installations with comprehensive diagnostics support process development and quality control for manufacturing scale-up. Electronics manufacturers in Germany and Japan anchor demand for repeatable process validation.
- Portable:Compact systems enable field repair and maintenance applications where mobility outweighs throughput.
- Remote:Teleoperated or automated platforms access hazardous environments with minimal human exposure.
On-site deployment leads capital expenditure. In-lab systems are climbing fastest as process validation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pulsed power engineers concentrate in Houston, Tokyo, and Munich, anchoring regional capability clusters that shape deployment patterns across oilfield services and precision manufacturing applications.
United States
Permian Basin operators drive demand for ultra-high voltage well intervention systems as EPA flaring constraints tighten. The Clean Air Act enforcement creates regulatory headroom for non-combustion stimulation methods. Denver and Houston service companies bundle plasma pulse tools with real-time diagnostics, restructuring capital expenditure treatment for independent producers.
Germany
Industrial gas suppliers accelerate fluoronitrile dielectric fluid development as the EU F-Gas Regulation phases down hydrofluorocarbons. REACH compliance costs add procedural friction to system deployment across European manufacturing. Munich and Stuttgart anchor precision surface treatment equipment production for automotive and electronics supply chains.
China
Sichuan Basin shale operators face groundwater protection standards from MEE that complicate traditional fracturing permits. The country's dual carbon goals redirect capital toward lower-carbon extraction technologies. Chengdu and Chongqing clusters pilot non-chemical well stimulation alternatives in tight gas reservoirs.
Japan
Semiconductor manufacturers adopt solid-state Marx generator architectures for inline surface treatment at 50-100 Hz pulse frequencies. METI industrial policy supports precision manufacturing equipment development. Tokyo and Osaka foundries integrate compact plasma systems into automated packaging lines for sub-10 nanometer feature sizes.
South Korea
Electronics miniaturization mandates from chip designers force fabs toward non-thermal cleaning methods. MFDS regulatory frameworks diverge from FDA on plasma medical device classification. Seoul and Suwon manufacturing corridors anchor demand for contamination-free surface treatment in advanced packaging applications.
Global Plasma Pulse Technology Market Competitive Environment
Capital-heavy oilfield service providers compete with asset-light precision equipment designers across divergent voltage regimes and deployment models. The vendor base separates into three strategic archetypes: integrated energy majors with captive technology development, specialized oilfield service companies with proprietary downhole tools, and industrial equipment manufacturers serving electronics and healthcare verticals. Dominant competitive moves include technology licensing partnerships bridging oilfield and industrial applications, and geographic expansion through equipment leasing models that shift capital burden to operators.
Within the integrated energy tier, ExxonMobil and Shell occupy positions that exemplify captive technology development for mature acreage rejuvenation. Among specialized oilfield service providers, Halliburton Energy Services and Schlumberger Limited represent archetypes of proprietary tool integration with real-time formation evaluation. Plasmatreat GmbH anchors the precision manufacturing equipment segment, serving automotive and electronics surface treatment applications from its German base.
| Leading Market Players |
|---|
| ExxonMobil |
| TotalEnergies |
| Halliburton Energy Services |
| CNPC |
| Schlumberger Limited |
| Baker Hughes |
| Chevron Phillips Chemical |
| Plasmatreat GmbH |
| Shell |
| Others |
Value Chain & Pricing Dynamics
Specialized capacitor and switching system indices from German and Japanese suppliers cascade through plasma pulse equipment manufacturing, compressing margins for ultra-high voltage system builders while amplifying pricing power for vertically integrated oilfield service providers that bundle diagnostics with stimulation tools.
Pricing Analysis
The bundled-vs-unbundled service split separates capital expenditure treatment from operational expenditure models across North American shale basins. Denver and Houston service companies now package plasma pulse stimulation with real-time formation diagnostics, commanding premium positioning against standalone equipment vendors. Price differentiation hinges on certification tier—UL-listed versus CE-marked systems—and geographic delivery cost to remote well sites. Pricing pressure stems from REACH compliance costs for dielectric fluid registration in Europe, eroding margins for non-integrated suppliers. Independent Permian Basin operators exhibit highest price sensitivity, while integrated majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
ISO 9001 and API Q1 certification gating restricts component sourcing to qualified suppliers in Germany, Japan, and the United States. Ultra-high voltage capacitors, solid-state Marx generator switches, and fluoronitrile dielectric fluids concentrate among specialty manufacturers in Munich, Tokyo, and Houston. Raw material dependencies include rare-earth magnetic materials for pulse transformers, high-purity aluminum for capacitor electrodes, and synthetic fluorinated compounds for insulation media. Single-source vulnerability around gas-based spark gap switches—now being displaced by solid-state architectures—creates transition risk for legacy system maintainers. Distribution runs through oilfield service company leasing networks in North America and direct equipment sales to semiconductor fabs in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma pulse technology functions as a regulatory compounder, with the EU F-Gas Regulation's 2027 hydrofluorocarbon prohibition accelerating equipment refresh cycles and repricing competitive alternatives for European operators.
For Market Incumbents: To counter solid-state Marx generator displacement of gas-based spark gap systems, Halliburton and Schlumberger should deepen captive supply of switching components through backward integration into Japanese semiconductor foundries. Certification investment in fluoronitrile dielectric fluid compatibility ahead of the EU prohibition deadline secures installed base retention in North Sea operations. For New Entrants and Emerging Players: Enter via biomedical sterilization applications where FDA clearance pathways remain less crowded than oilfield service consolidation. Plasma medicine for surgical instruments and wound treatment offers the most penetrable vertical, with distinct reimbursement codes enabling premium pricing. A go-to-market angle anchored on hospital GPO contracts bypasses the capital intensity of well intervention equipment leasing. For Investors and Strategic Acquirers: Asymmetric upside sits with precision manufacturing equipment designers serving semiconductor packaging lines, where miniaturization mandates from Taiwanese and South Korean chip designers force fabs toward non-thermal cleaning methods. Long-term viability across the analysis window favors asset-light platforms with recurring consumable revenue from dielectric fluid replacement. The signal to watch is MEE enforcement intensity in China's Sichuan Basin, where groundwater protection standards redirect capital toward non-chemical well stimulation alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Bridges oilfield and industrial applications through voltage-scalable Marx generator architectures. |
| Fluoronitrile Dielectric Fluid Transition | Secures EU market access ahead of F-Gas Regulation prohibition deadlines. |
| Equipment Leasing Model Expansion | Shifts capital burden to Permian Basin operators facing balance sheet constraints. |
| Biomedical Regulatory Pathway Investment | Opens FDA-cleared revenue vertical distinct from industrial equipment approvals. |
| Solid-State Switching Architecture Migration | Reduces dependency on Japanese gas-based spark gap suppliers. |
Study Parameters
Multiple input streams—primary interviews with oilfield service executives, semiconductor fab engineers, and high-voltage equipment procurement leads; secondary validation through SEC 10-K filings, EIA drilling productivity reports, and METI industrial equipment statistics; and customs data on capacitor and switching system trade flows—were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across voltage regime segmentation, end-user verticals spanning electronics and healthcare, and deployment models from on-site well intervention to in-lab process validation generated volume and value outputs. CAGRs were derived from installation base growth in mature shale basins and semiconductor packaging line expansion. Industry-specific forecast inputs included EPA flaring enforcement intensity and EU F-Gas Regulation phase-down schedules.
Inputs from oilfield operator capital expenditure disclosures and semiconductor equipment capex guidance were available through the study window; gaps in real-time plasma pulse treatment efficacy data from deep shale reservoirs exceeding 4,500 meters introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented assumptions about regulatory timeline adherence and technology substitution elasticity. A model refresh is warranted upon material change in MEE groundwater protection enforcement or solid-state Marx generator cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
AI Edge Computing Market