
 Asia Pacific Computer Monitor Market | 2026-2036
Asia Pacific Computer Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Computer Monitor Market Outlook
Chinese panel manufacturing clusters is repositioning supply chains toward higher-refresh-rate IPS and OLED substrates. Samsung Electronics leverages vertical integration across semiconductor and display divisions to control premium panel allocation. LG Electronics anchors large-format OLED production for professional color-grading workflows across South Korea and Japan. TPV Technology specializes in cost-optimized LED assembly, occupying the volume tier for corporate procurement contracts across ASEAN markets.
Asia Pacific computer monitors are electro-optical display devices that convert video signals into visible images through liquid-crystal, organic light-emitting diode, or cathode-ray tube technologies, with specifications spanning refresh rates from 60 Hz to 240 Hz and color gamut coverage up to DCI-P3 for professional applications. LED panels dominate unit shipments across corporate and education end users due to backlight efficiency and manufacturing scale, while OLED commands margin concentration in gaming and content creation segments where response time and contrast ratio differentiate purchasing decisions. WQHD resolution captures the fastest upgrade momentum among home office buyers in Australia and South Korea who prioritize screen real estate without 4K GPU demands.
Japan's METI enforces Top Runner standards that mandate progressive efficiency gains in standby and active power consumption, compelling manufacturers to redesign driver circuits for monitors sold across East Asian markets. India's BIS certification requirements for electronic goods restrict market access to tested products, while China's MIIT coordinates GB standard updates that synchronize with domestic panel foundry capabilities. Stakeholders must monitor how Australia's alignment with IEC energy performance frameworks interacts with evolving ASEAN harmonization talks to anticipate compliance cost shifts.
Market Dynamics
China's MIIT-coordinated GB energy efficiency standards are compressing LED backlight procurement cycles while forcing foundries to retool driver architectures for the entire Asia Pacific supply base.
Growth Catalysts
- Hybrid work permanence:India's tier-one cities sustain corporate refresh demand as Bengaluru, Mumbai, and Delhi NCR employers mandate dual-monitor setups for knowledge workers.
- MIIT GB standard updates:China's domestic panel foundries capture preferential sourcing from regional OEMs complying with synchronized efficiency mandates.
- Esports venue buildouts:Gaming cafes across Vietnam, Thailand, and Indonesia drive 165 Hz and 240 Hz panel volume through hardware-as-a-service leasing models.
Market Restraints
- Substrate concentration:Taiwanese and South Korean OLED vapor deposition equipment suppliers control critical capacity for premium panel tiers.
- BIS certification lag:India's testing backlog extends time-to-market for new entrants by four to six months versus ASEAN alternatives.
- GPU mismatch:4K resolution adoption stalls among Australian home office buyers unwilling to upgrade graphics hardware for native rendering.
Strategic Opportunities
- Philippines provincial expansion:Secondary cities like Cebu and Davao show monitor penetration gaps of forty percent below Metro Manila levels.
- Professional color workflows:Post-production houses in South Korea and Japan seek factory-calibrated DCI-P3 coverage for streaming content mastering.
- Japan METI Top Runner alignment:Efficiency-compliant panels gain preferential placement in Australian federal procurement tenders through IEC harmonization.
Industry Challenges
- Firmware certification complexity:Multi-country energy efficiency registrations require parallel testing streams for China's GB, India's BIS, and Australia's GEMS frameworks.
- Display driver IC allocation:Foundry prioritization for automotive and smartphone panels constrains monitor-specific chip supply during capacity tightness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Computer Monitor Market |
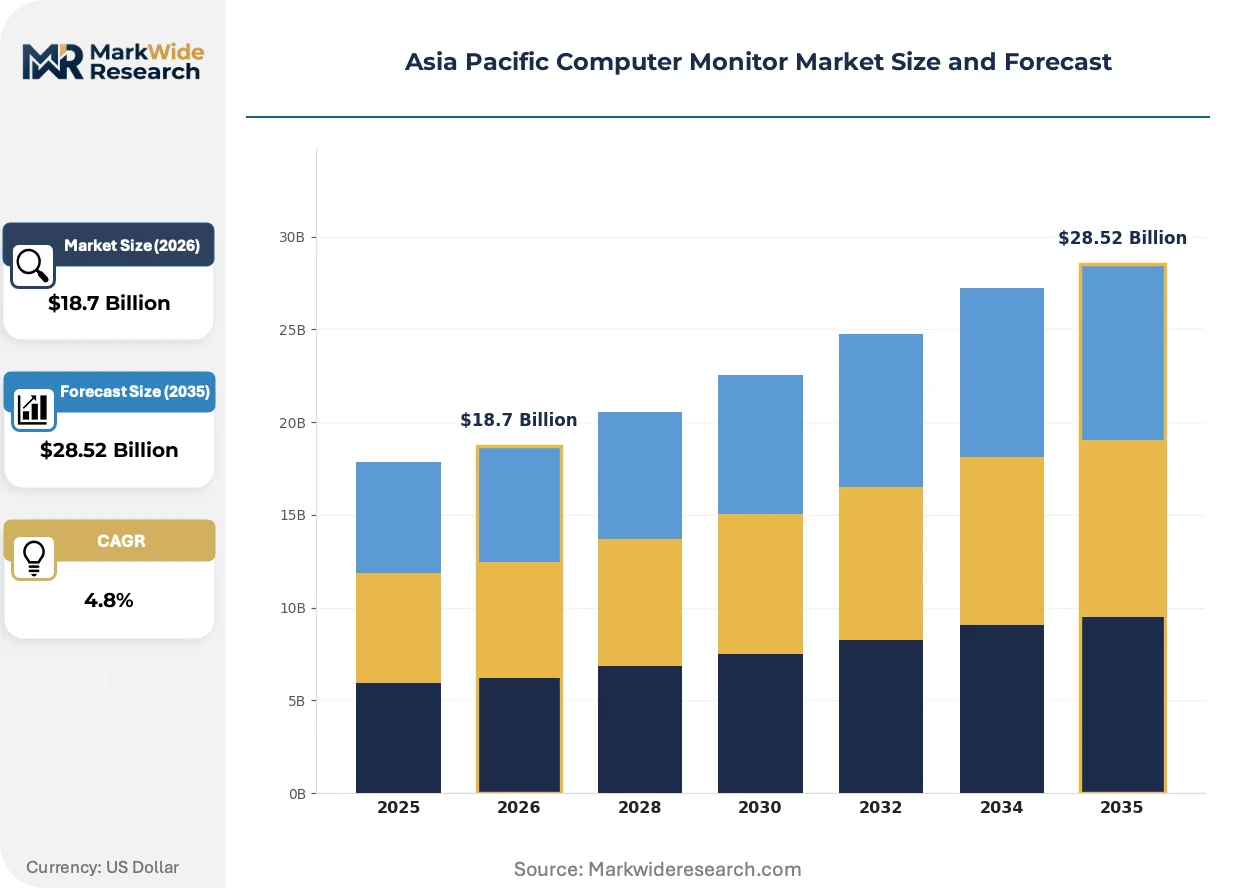
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, CRT End User: Gaming, Corporate, Education, Home Office Screen Size: 27 inch, 32 inch, 24 inch, 19 inch Resolution: Full HD, 4K, WQHD, 8K |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, Dell Technologies Inc., HP Inc., Lenovo, BenQ Corporation, AsusTek Computer Inc., Acer Inc., TPV Technology Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Computer Monitor Market Strategic Shifts
Panel technology trajectories and procurement governance are fragmenting the Asia Pacific monitor landscape into performance-tiered ecosystems with diverging supply chain requirements.
QD-OLED is decentralizing premium gaming panel sourcing away from South Korean exclusive supply. Chinese foundries are scaling inkjet-printed OLED deposition for 27-inch and 32-inch formats. Esports venue operators in Vietnam and Thailand now specify these panels for sub-two-millisecond response time requirements.
Japan's METI Top Runner program mandates annual standby power reductions that cascade through East Asian supply chains. Monitor OEMs redesign power management ICs to meet progressive efficiency tiers. Australian distributors align import specifications with these standards to preempt dual-stock complexity.
Corporate buyers in Australia's financial services sector now unbundle monitor procurement from desktop system contracts. Direct sourcing through B2B marketplaces displaces traditional VAR channels for standard LED specifications. This pattern is replicating among Indian IT services firms negotiating volume pricing outside OEM-locked agreements.
Asia Pacific Computer Monitor Market Segmentation
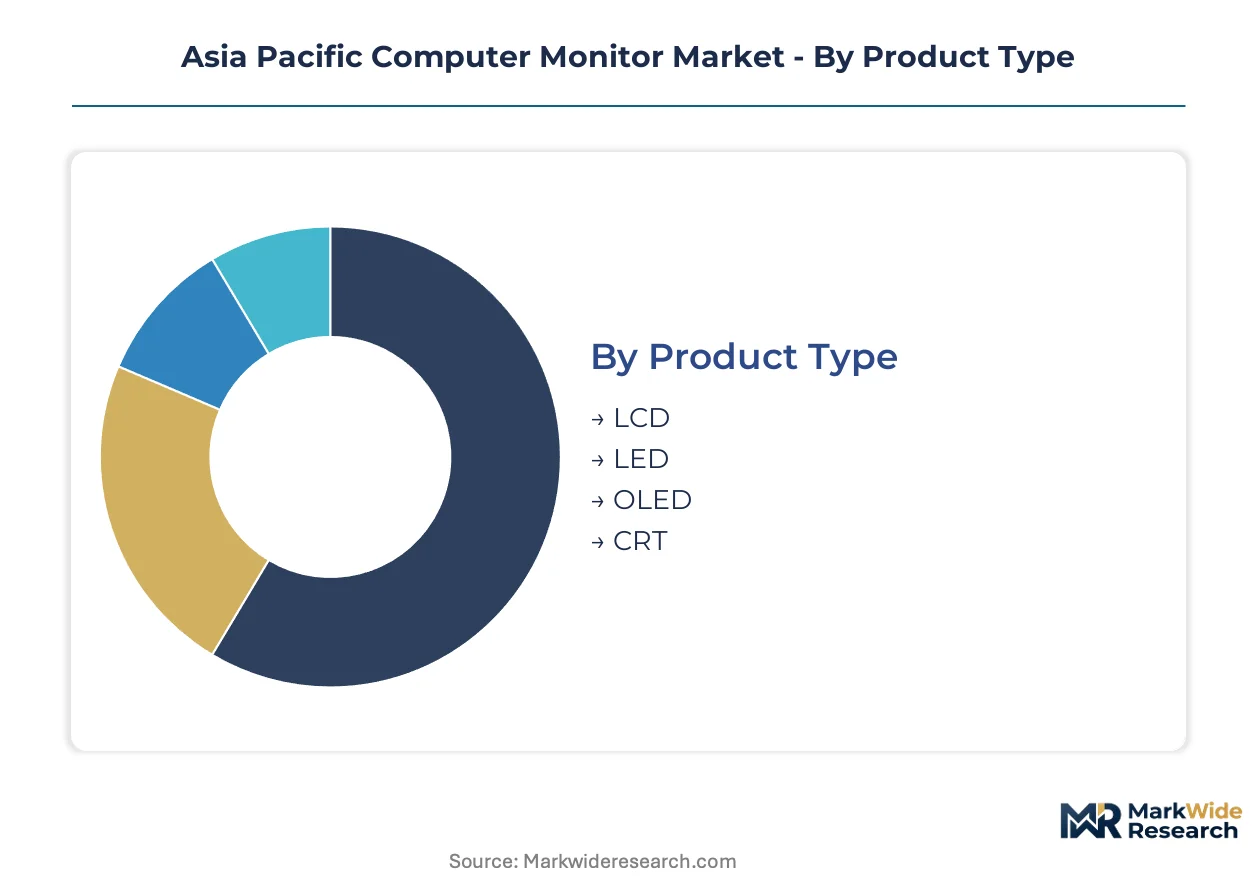
Panel technology and end-use application create distinct certification pathways across Asia Pacific monitor procurement. Energy efficiency mandates from China's MIIT and India's BIS fragment compliance requirements by segment, reshaping sourcing strategies for regional OEMs.
Product Type:
Certification burdens vary sharply across display technologies, with OLED requiring additional electromagnetic compatibility testing under Japan's METI Top Runner program while LED panels face streamlined GB standard compliance in China.
- LCD:Liquid-crystal displays with fluorescent backlighting dominate legacy corporate installations across India's tier-one cities. Bengaluru IT parks sustain refresh demand for 22-inch and 24-inch specifications where TCO certification satisfies European MNC procurement standards.
- LED:Light-emitting diode backlit panels capture volume share across ASEAN education contracts due to lower active power draw. Vietnamese provincial school districts specify these units under Ministry of Education and Training energy efficiency guidelines.
- OLED:Organic light-emitting diode substrates command premium positioning in South Korean and Japanese content creation workflows.
- CRT:Cathode-ray tube technology persists in niche industrial control applications across legacy manufacturing clusters.
Leading the category by volume: LED. Growing fastest: OLED.
End User:
Customer type determines refresh rate specifications and color accuracy requirements, with gaming and professional segments driving divergence in panel sourcing.
- Gaming:High-refresh-rate panels from 144 Hz to 240 Hz anchor hardware-as-a-service leasing models across Vietnam and Thailand esports venues. Bangkok gaming cafe operators specify sub-2ms response times for competitive titles, compressing procurement cycles to 18-month replacement intervals.
- Corporate:Dual-monitor configurations dominate knowledge worker setups in Mumbai and Delhi NCR financial services firms. Hybrid work permanence sustains demand for 24-inch Full HD specifications with VESA mount compatibility.
- Education:Cost-optimized LED panels serve K-12 deployments across Indonesia's outer islands where logistics constraints favor durable, low-power specifications.
- Home Office:Australian remote workers in Sydney and Melbourne prioritize WQHD resolution for spreadsheet-intensive workflows without 4K GPU requirements.
Driving margin concentration: Gaming. Expanding most quickly: Home Office.
Screen Size:
Display diagonal correlates with end-use application and regional workspace constraints, with 27-inch formats gaining share in South Korean and Australian home office environments.
- 27 inch:The dominant format for hybrid work setups across Australia's financial services sector, balancing screen real estate with desk footprint constraints. Sydney and Melbourne home office buyers specify these units through direct B2B marketplace procurement outside traditional VAR channels.
- 32 inch:Large-format panels serve professional color-grading workflows in Tokyo and Seoul post-production houses. Factory-calibrated DCI-P3 coverage differentiates purchasing decisions for streaming content mastering applications.
- 24 inch:Standard corporate specification across Indian IT services firms negotiating volume pricing.
- 19 inch:Legacy format persisting in point-of-sale and industrial control applications.
Highest shipment volume: 27 inch. Steepest expansion trajectory: 32 inch.
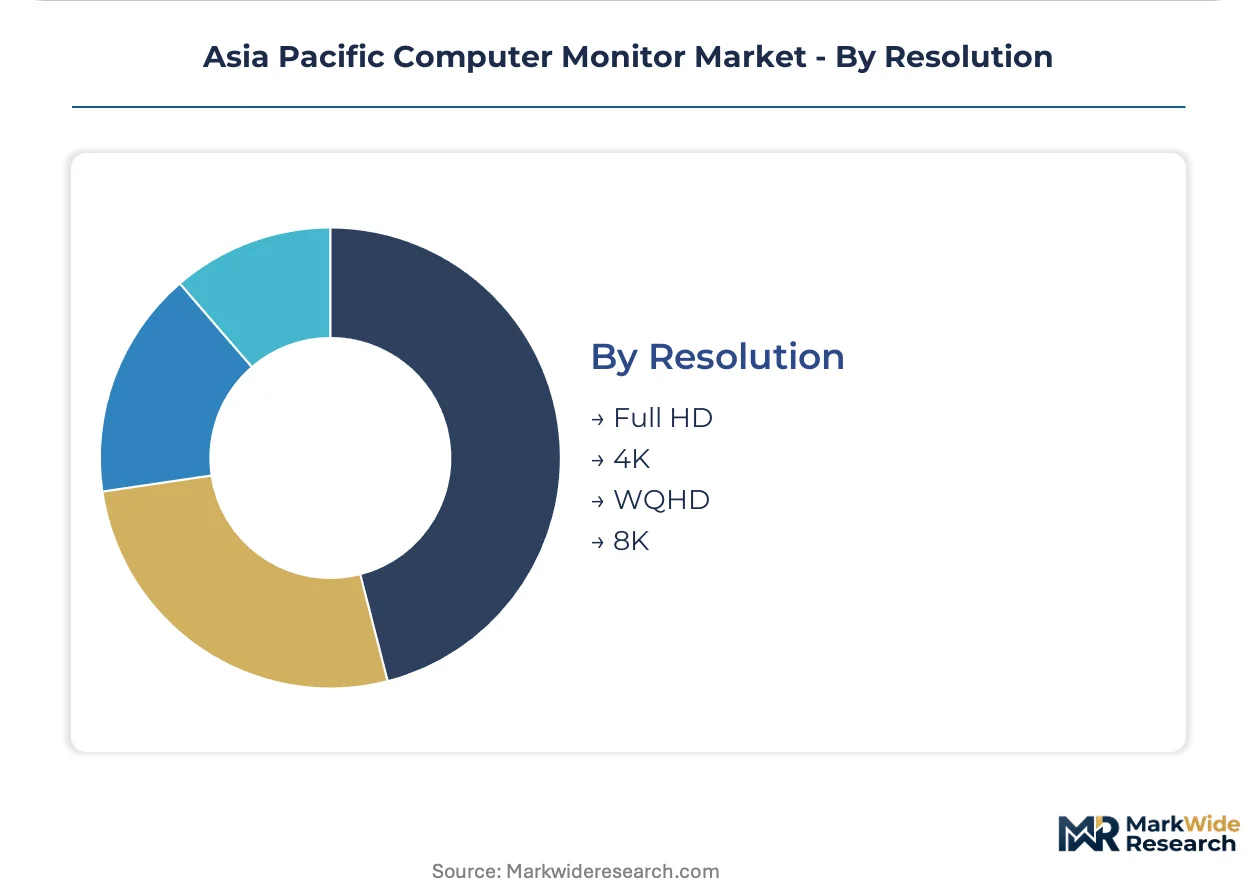
Resolution:
Pixel density requirements fragment by graphics hardware capability and content type, with WQHD capturing upgrade momentum among GPU-constrained buyers.
- Full HD:1920x1080 resolution dominates volume shipments across ASEAN education and entry-level corporate procurement. Indonesian school districts specify these units for cost-constrained deployments where content consumption rather than creation drives requirements.
- 4K:Ultra-high-definition panels stall among Australian home office buyers unwilling to upgrade graphics hardware for native rendering. Adoption concentrates in Tokyo and Seoul professional workflows where color accuracy and pixel density justify GPU investment.
- WQHD:2560x1440 resolution gains fastest share among South Korean remote workers prioritizing productivity applications.
- 8K:Experimental format for medical imaging and specialized visualization in Japan.
Capturing largest unit volume: Full HD. Gaining share fastest: WQHD.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass substrate foundries in South Korea and Taiwan anchor Asia Pacific panel supply chains. Foundry capacity allocation shapes procurement timelines for OEMs across the region.
China
MIIT-coordinated GB energy efficiency standards compress LED backlight procurement cycles while domestic panel foundries capture preferential sourcing from regional OEMs. Yangtze River Delta manufacturing clusters retool driver architectures to synchronize with efficiency mandates. Suzhou and Hangzhou assembly plants serve ASEAN education and corporate contracts.
India
BIS certification requirements restrict market access to tested products while hybrid work policies in Bengaluru, Mumbai, and Delhi NCR sustain corporate refresh demand. Knowledge worker employers mandate dual-monitor setups for IT services firms. Tier-one cities concentrate procurement volume as provincial penetration lags.
Japan
METI Top Runner standards mandate progressive efficiency gains in standby and active power consumption, compelling manufacturers to redesign driver circuits. Tokyo and Osaka post-production houses drive large-format OLED demand for streaming content mastering. Kanto manufacturing clusters supply factory-calibrated panels to professional color workflows.
South Korea
OLED vapor deposition equipment suppliers control critical capacity for premium panel tiers while Seoul remote workers prioritize WQHD resolution for productivity applications. Busan-Ulsan industrial corridors anchor large-format production for content creation segments. Domestic foundries scale inkjet-printed OLED deposition for gaming formats.
Australia
Alignment with IEC energy performance frameworks interacts with evolving ASEAN harmonization talks to shape compliance cost structures. Sydney and Melbourne financial services firms unbundle monitor procurement from desktop contracts through direct B2B marketplace sourcing. Federal procurement tenders gain efficiency-compliant panels through METI standard harmonization.
Asia Pacific Computer Monitor Market Competitive Environment
Global majors compete with regional champions across certification complexity and foundry access. The vendor base stratifies into three tiers: integrated semiconductor-display conglomerates, specialized panel assemblers, and contract manufacturers serving volume education contracts. Korean and Taiwanese equipment suppliers anchor premium OLED capacity. Chinese foundries capture mid-tier LED volume through cost-optimized backlights.
Among Korea-based electronics conglomerates, Samsung Electronics Co., Ltd. and LG Electronics occupy positions spanning semiconductor and display divisions. TPV Technology Limited represents the volume-tier assembler archetype for ASEAN corporate procurement. These three exemplify the competitive spectrum from captive panel supply through outsourced assembly.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Dell Technologies Inc. |
| HP Inc. |
| Lenovo |
| BenQ Corporation |
| AsusTek Computer Inc. |
| Acer Inc. |
| TPV Technology Limited |
| Others |
Value Chain & Pricing Dynamics
Corporate procurement teams at Indian IT services firms and Australian financial services institutions dominate volume negotiations, anchoring contract-based long-term offtake agreements that compress spot-market premiums for standard LED specifications while leaving OLED tiers exposed to foundry allocation volatility.
Pricing Analysis
Warranty and factory-calibration bundling separate premium OLED tiers from unbundled LED volume contracts across ASEAN education tenders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and India's BIS requirements. Cost compression in mid-tier LED panels intensifies as Yangtze River Delta foundries scale driver IC integration. Education buyers in Indonesia and Vietnam exhibit highest price sensitivity; professional color-grading workflows in Tokyo and Seoul show lowest.
Supply Chain Analysis
India's BIS domestic-content mandates and China's MIIT efficiency requirements are reshaping sourcing toward certified regional assembly plants. Glass substrate supply concentrates in South Korea, Taiwan, and Japan, with vapor deposition equipment anchoring premium OLED capacity. Display driver ICs and LED backlight components draw from Chinese and Taiwanese foundries. Single-source vulnerability runs through South Korean OLED equipment suppliers. Distribution runs through direct B2B marketplace procurement displacing traditional VAR channels in Australia and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific monitor market sits in a technology-transition phase where inkjet-printed OLED deposition displaces legacy vapor deposition for mid-format gaming panels, compressing equipment payback periods and redrawing foundry competitiveness maps.
For Market Incumbents: Hedge against Chinese foundry ascension in inkjet-printed OLED by locking exclusive vapor deposition equipment allocation from South Korean and Taiwanese suppliers. Deepen backward integration into driver IC design to bypass foundry prioritization constraints for automotive and smartphone panels. Anchor certification investment under Japan's METI Top Runner to preempt Australian federal procurement alignment.
For New Entrants and Emerging Players: Enter via the Philippines provincial gap where Cebu and Davao penetration trails Metro Manila by forty percent, bypassing congested tier-one city competition. Target secondary Indian cities outside Bengaluru-Mumbai-Delhi NCR where BIS certification backlogs deter multinational entrants. Pursue hardware-as-a-service leasing models for Vietnamese and Thai esports venues as the go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors mid-tier LED assemblers with BIS-certified Indian facilities and ASEAN logistics footprints before Chinese foundries complete vertical integration. Long-term viability hinges on panel technology transition timing rather than volume scale alone. Watch inkjet-printed OLED yield rates at Chinese foundries as the inflection signal for premium tier margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| QD-OLED Panel Scale-Up | Chinese foundries capture gaming panel share from South Korean exclusive supply. |
| BIS Certification Investment | Domestic testing capacity reduces India's four-to-six-month market access lag. |
| Direct B2B Marketplace Launch | Australian financial services firms bypass VAR channels for standard LED procurement. |
| Driver IC Design Integration | In-house power management ICs satisfy Japan METI Top Runner efficiency tiers. |
| Provincial Distribution Expansion | Cebu and Davao penetration gaps offer forty percent headroom versus Metro Manila. |
Study Parameters
Trade databases, customs records, and regulatory filings from China's MIIT and India's BIS formed the secondary backbone. Primary interviews with display panel procurement managers at ASEAN education ministries, OEM supply chain directors, esports venue operators in Vietnam and Thailand, and foundry equipment specialists validated shipment and pricing assumptions. Bottom-up and top-down triangulation reconciled foundry capacity announcements with end-user procurement patterns.
Bottom-up modeling anchored volume projections to named foundry capacity expansions and certification pipeline data across the analysis window. Segmentation dimensions included panel technology, refresh rate tier, end-use application, and regional regulatory cluster. CAGRs derived from shipment trajectory alignment with efficiency mandate compliance deadlines and GPU upgrade cycle timing in Australian and South Korean home office segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BIS certification backlog extensions, OLED equipment supply disruptions, or ASEAN harmonization delays. Forecasts reflect assumptions about foundry yield improvement curves and regulatory synchronization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Volumetric Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Portable Projector Market
Display Technologies
Display Mask Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Backlit Displays Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
Laptop Panels Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
4K Technology Market
Display Technologies
Global Display Panel Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market