
 Global LED Digital Signage Market | 2026-2036
Global LED Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Global LED Digital Signage Market Outlook
Content management subscriptions and software-defined brightness calibration is shifting how LED digital signage vendors monetize hardware deployments. Samsung Electronics leverages its semiconductor supply chain to sustain cost advantages in fine-pitch indoor modules. LG Electronics anchors its position through integrated display-to-cloud service bundles for corporate clients. Leyard Optoelectronic dominates high-resolution outdoor installations across transportation hubs in Asia.
LED digital signage comprises emissive display systems built from packaged gallium nitride diodes mounted on printed circuit boards, typically operating at pixel pitches between 0.9 mm and 16 mm depending on viewing distance requirements. These systems serve commercial messaging, wayfinding, and real-time information dissemination in high-ambient-light environments where projection or transmissive technologies fail. Outdoor displays command the largest revenue share due to durability premiums and weatherproofing requirements, while transparent displays attract the fastest investment from retail architects seeking unobstructed storefront visibility. Video walls retain concentrated margin pools in command-and-control centers where bezel-free continuity justifies elevated pricing.
The EU Green Deal and REACH frameworks enforce material disclosure and energy labeling across imported LED modules, while FCC Part 15 emissions rules govern wireless content distribution hardware in the United States. China's GB standards and MIIT certification protocols create parallel compliance tracks for domestic and export-bound production. Stakeholders must monitor divergence between regional efficiency benchmarks and content security mandates as procurement specifications harden.
Market Dynamics
Software-defined brightness calibration and content management subscriptions are compressing hardware margins while locking buyers into recurring revenue streams, fundamentally altering how vendors capture value from LED deployments.
Growth Catalysts
- EU Green Deal efficiency mandates:Tightening energy labeling requirements under the EU Green Deal and REACH frameworks are forcing facility upgrades across retail and transportation infrastructure, accelerating replacement cycles for legacy display systems.
- Airport retail digitization:Duty-free operators and concession holders at major international hubs are deploying fine-pitch LED walls to enable dynamic pricing and real-time inventory visualization, creating concentrated demand clusters.
- Gallium nitride diode efficiency gains:Advances in GaN packaging density and thermal management are extending outdoor display lifespans while reducing power draw, improving total cost of ownership calculations for municipal procurement.
Market Restraints
- Driver IC supply concentration:Taiwan and South Korea foundries control critical semiconductor supply for LED driver integrated circuits, exposing module assemblers to allocation volatility and extended lead times.
- Indoor fine-pitch technical ceiling:Below 0.7 mm pixel pitch, solder joint reliability and repairability degrade sharply, limiting serviceable market penetration for ultra-high-resolution corporate installations.
- FCC Part 15 emissions compliance:Wireless content distribution hardware faces escalating testing burdens under evolving FCC guidelines, extending certification timelines and freezing product launches.
Strategic Opportunities
- Transparent display retail architecture:Unobstructed storefront visibility requirements in luxury retail districts are driving investment in transparent LED mesh systems, particularly in Dubai and Singapore shopping corridors.
- India smart city infrastructure:Municipal digital wayfinding and public information systems under India's urban renewal programs represent underpenetrated deployment channels for outdoor-rated modules.
- AI-driven content automation:Convergence of computer vision analytics and generative content pipelines enables real-time audience-responsive messaging, opening premium service tiers for venue operators.
Industry Challenges
- Embedded software engineering scarcity:Firmware development for color calibration and thermal compensation algorithms outpaces available talent pools, delaying product roadmaps.
- Legacy AV integration complexity:Enterprise buyers demand seamless interoperability with existing control room and building management systems, requiring costly custom protocol bridges.
- Multi-jurisdiction certification lag:Parallel GB standards, CE marking, and FCC approval tracks stretch time-to-revenue for new product families by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LED Digital Signage Market |
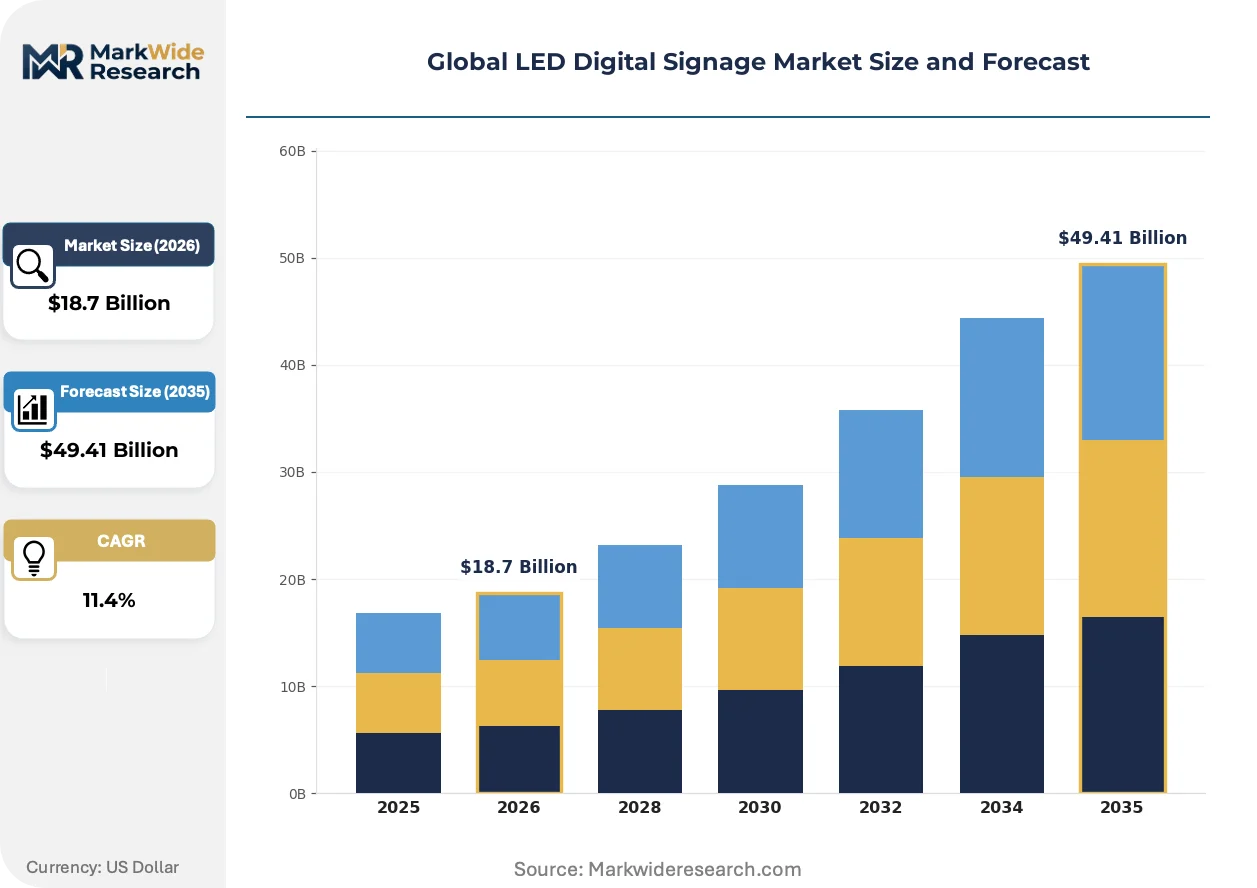
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Displays, Indoor Displays, Transparent Displays, Video Walls Application: Transportation, Retail, Corporate, Entertainment Technology: LCD, OLED, MicroLED, Projection Mapping End User: Advertisers, Event Organizers, Retailers, Public Venues |
| Companies Covered | Samsung Electronics, LG Electronics, Leyard Optoelectronic, Daktronics, Panasonic Corporation, NEC Display Solutions, Sony Corporation, Unilumin, Absen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LED Digital Signage Market Strategic Shifts
Active matrix driving schemes and chip-on-board packaging are compressing module thickness and power budgets, enabling architectural integration previously blocked by structural and thermal constraints.
Chip-on-board LED packaging is consolidating discrete component counts by embedding driver logic directly onto the substrate, eliminating wire bonds and reducing failure points. Corporate lobby and broadcast studio buyers are specifying these modules for 24/7 operation cycles. The technology is consolidating supplier tiers by favoring vertically integrated manufacturers with captive semiconductor capabilities.
REACH substance disclosure requirements are mandating full material transparency across imported LED modules entering European Union markets. Manufacturers must document rare earth content and flame retardant chemistry through extended supply chain audits. Outdoor rental and staging fleets face the steepest compliance costs due to high inventory velocity and cross-border deployment patterns.
Subscription-based content management platforms are displacing perpetual-license software sales across large-format deployments. Venue operators in sports and entertainment verticals now prioritize vendors offering bundled hardware-software-service packages with guaranteed uptime SLAs. This preference shift is most visible in United States collegiate athletic facilities and professional arena renovations.
Global LED Digital Signage Market Segmentation
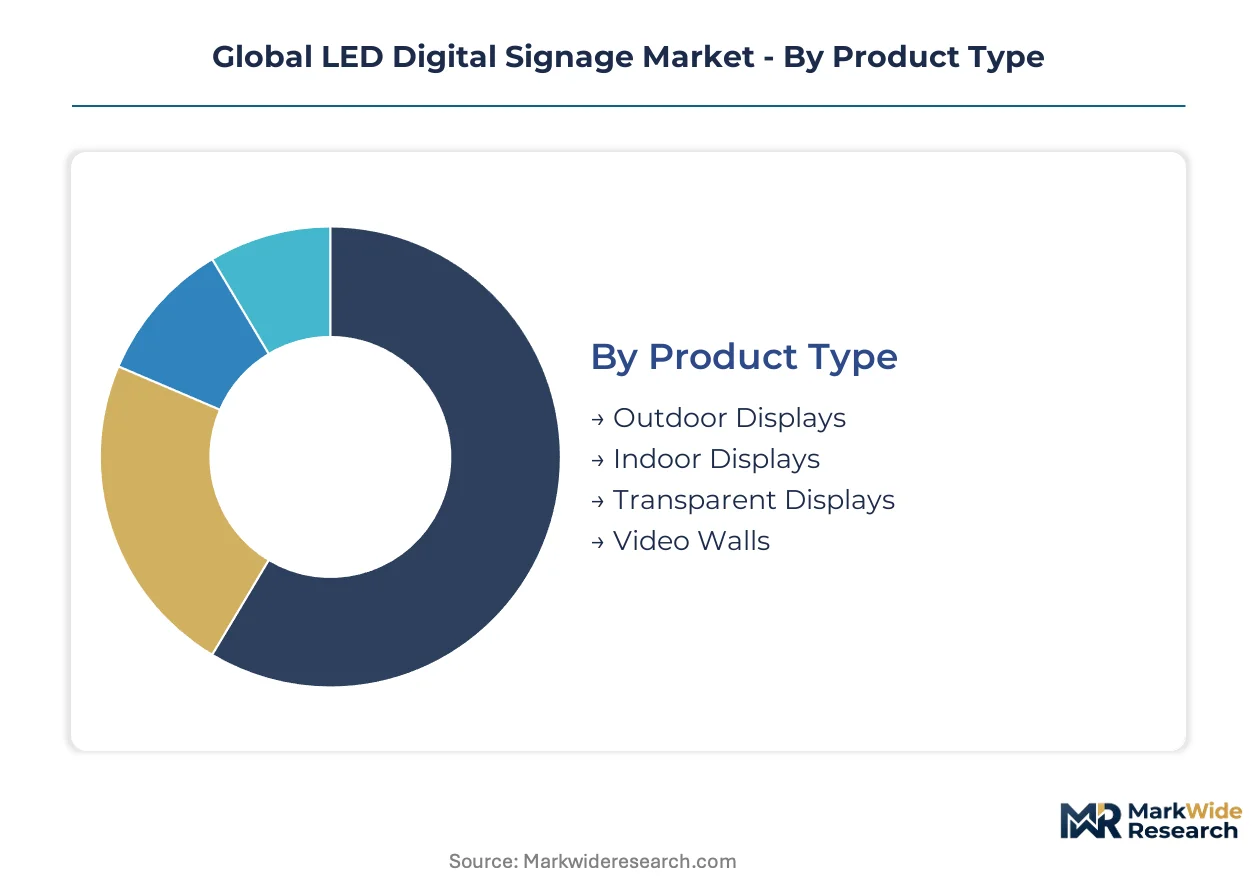
LED digital signage segmentation reveals divergent margin structures across display environments and buyer procurement patterns. Product type and application splits expose where hardware premiums concentrate versus where software subscriptions capture recurring value.
Product Type:
Volume concentrates in weatherproofed outdoor units while premium margins concentrate in architectural transparent systems and seamless video walls.
- Outdoor Displays:Packaged gallium nitride diodes mounted on thermally managed substrates deliver luminance exceeding 5,000 nits for direct sunlight readability. Municipal procurement in China and airport authorities in Dubai drive replacement cycles as EU Green Deal efficiency mandates accelerate legacy system retirement.
- Transparent Displays:Mesh LED arrays with 60-80% transparency enable storefront visibility without sacrificing digital messaging capability. Luxury retail architects in Singapore shopping corridors specify these systems for flagship facade renovations, attracted by unobstructed sightlines combined with dynamic content delivery.
- Indoor Displays:Fine-pitch modules below 2.5 mm pixel pitch serve corporate lobbies and broadcast studios requiring 24/7 operation reliability.
- Video Walls:Bezel-free tiled configurations dominate command-and-control centers where visual continuity justifies elevated pricing tiers.
Today's leader: Outdoor Displays. Tomorrow's challenger: Transparent Displays.
Application:
Transportation infrastructure commands the largest project scale while retail delivers the densest deployment velocity per square kilometer.
- Transportation:Airport terminals, railway stations, and metro platforms require synchronized wayfinding with real-time schedule integration. Duty-free operators at Frankfurt and Changi airports deploy fine-pitch LED walls for dynamic pricing displays, creating concentrated demand clusters with stringent uptime requirements.
- Retail:Shopping malls and flagship stores prioritize content agility over hardware longevity, favoring vendors with bundled software-service packages. Digital signage here compresses campaign deployment from weeks to hours, rewarding subscription-based monetization models.
- Corporate:Headquarters and conference facilities demand seamless interoperability with existing AV infrastructure and building management protocols.
- Entertainment:Arenas, stadiums, and concert venues specify high-refresh-rate modules for broadcast camera compatibility and audience immersion.
Transportation anchors current procurement volume. Retail is gaining share fastest through smaller-ticket, higher-velocity deployments.
Technology:
Emissive versus transmissive architectures separate premium positioning from commodity substitution risk.
- LCD:Backlit liquid crystal panels dominate cost-sensitive indoor applications where ambient light control permits lower luminance output. Corporate meeting rooms and quick-service restaurant menu boards in India represent sustained volume despite narrowing technology gaps with emissive alternatives.
- MicroLED:Chip-scale packaging eliminates wire bonds and enables sub-0.9 mm pixel pitches with superior thermal efficiency. Broadcast studios and luxury automotive showrooms in Japan specify these modules for color accuracy critical to brand presentation.
- OLED:Organic emissive layers enable perfect black levels and wide viewing angles in controlled indoor environments.
- Projection Mapping:Laser-phosphor and solid-state projection serve temporary installations and architectural surfaces unsuited to fixed LED mounting.
LCD holds installed base dominance. MicroLED represents the steepest expansion trajectory as manufacturing yields improve.
End User:
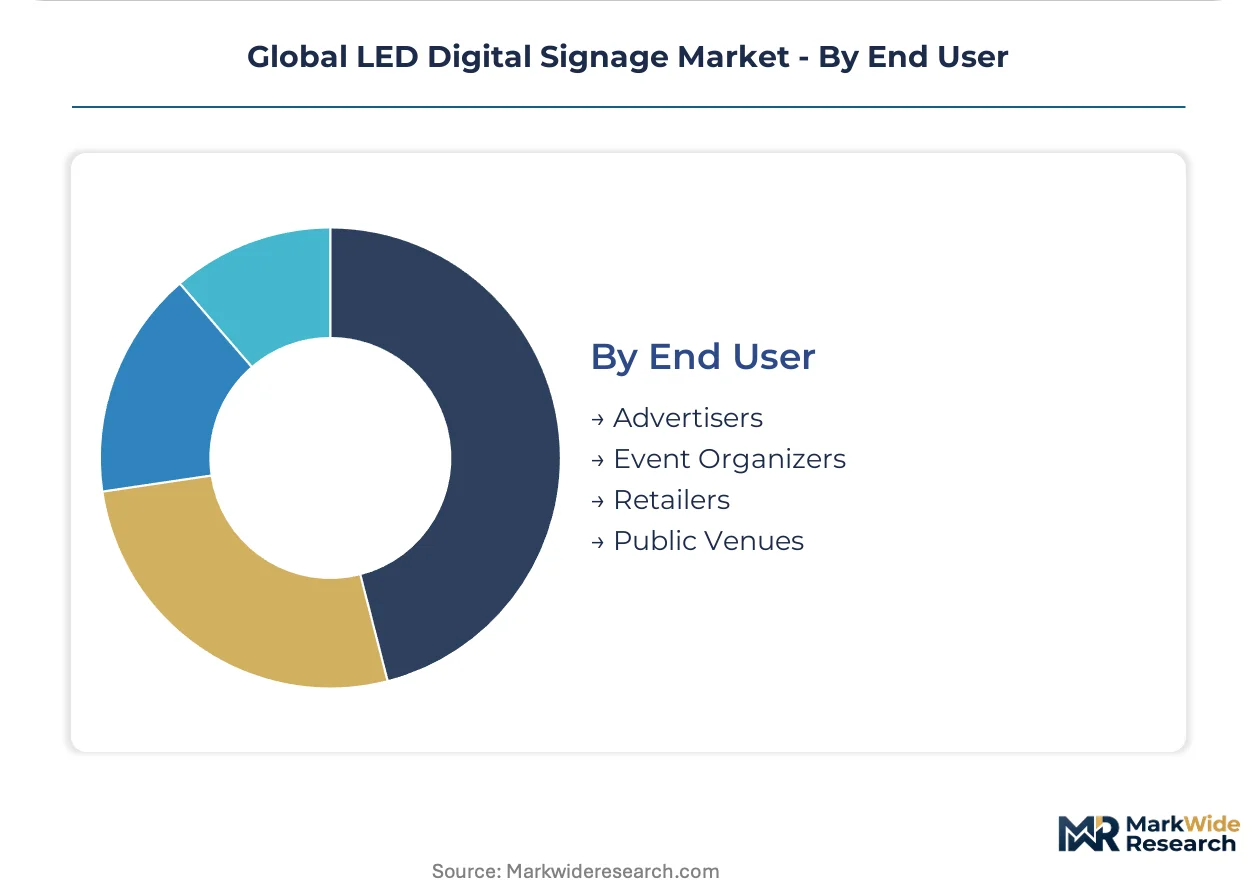
Advertisers and retailers diverge in procurement priorities between creative flexibility and operational predictability.
- Advertisers:Media owners and programmatic networks prioritize content management platform compatibility and audience analytics integration. Out-of-home operators in Times Square and Shibuya Crossing demand real-time campaign swapping capabilities with guaranteed SLA uptime.
- Retailers:Store operators and brand flagships emphasize total cost of ownership and thermal reliability over specification extremes. Grocery chains and fast-fashion outlets in Brazil negotiate hardware-software bundles with predictable five-year operational expenditure profiles.
- Event Organizers:Rental and staging companies require rapid deployment modularity and cross-border logistics compatibility.
- Public Venues:Museums, libraries, and municipal buildings prioritize accessibility compliance and multi-language content support.
Advertisers drive premium specification adoption. Retailers are concentrating procurement power through consolidated vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting LED module assembly toward jurisdictions with streamlined certification pathways, as manufacturers seek to bypass the 8-14 month multi-jurisdiction approval timelines that strain working capital.
China
Shenzhen and Beijing drive manufacturing scale for both domestic procurement and export-bound production. MIIT certification protocols and GB standards create parallel compliance tracks that advantage vertically integrated domestic champions. The Pearl River Delta cluster concentrates chip-on-board packaging innovation, with Shenzhen-based foundries capturing semiconductor supply chain efficiencies.
United States
Collegiate athletic facilities and professional arena renovations concentrate demand for bundled hardware-software-service packages. FCC Part 15 emissions rules govern wireless content distribution hardware, extending certification timelines for new product families. Times Square out-of-home operators demand real-time campaign swapping capabilities with guaranteed SLA uptime.
Germany
Frankfurt airport duty-free operators deploy fine-pitch LED walls for dynamic pricing displays, creating concentrated demand clusters with stringent uptime requirements. EU Green Deal efficiency mandates and REACH frameworks enforce material disclosure and energy labeling across imported modules. Bavaria-based system integrators specialize in command-and-control center installations.
India
Municipal digital wayfinding and public information systems under urban renewal programs represent underpenetrated deployment channels for outdoor-rated modules. BIS certification requirements and PLI scheme incentives for electronics manufacturing are attracting module assembly investment. Maharashtra and Gujarat industrial corridors are emerging as domestic production hubs.
Singapore
Luxury retail architects specify transparent LED mesh systems for flagship facade renovations in shopping corridors, attracted by unobstructed sightlines combined with dynamic content delivery. The country's national standards body enforces strict energy performance benchmarks for imported display systems. Marina Bay and Orchard Road districts anchor high-value deployment density.
Global LED Digital Signage Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated electronics conglomerates commanding premium positioning in fine-pitch indoor modules while pure-play LED fabricators dominate outdoor transportation infrastructure. The vendor base separates into three tiers: semiconductor-captive diversified technology groups, vertically specialized display manufacturers, and regional system integrators with project execution capabilities. Consolidation pressure concentrates among mid-scale module assemblers facing driver IC supply volatility. Geographic expansion and technology licensing represent the dominant competitive moves as firms seek to bypass certification bottlenecks.
Within the diversified technology tier, Samsung Electronics and LG Electronics exemplify semiconductor-captive positioning that sustains cost advantages in component-intensive segments. Leyard Optoelectronic occupies a position among specialized display manufacturers with concentrated strength in high-resolution outdoor installations. These three anchors illustrate how supply chain control and application-specific expertise stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Leyard Optoelectronic |
| Daktronics |
| Panasonic Corporation |
| NEC Display Solutions |
| Sony Corporation |
| Unilumin |
| Absen |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal efficiency mandates gate qualified supply and premium-tier pricing access by restricting module eligibility to certified manufacturers with documented material transparency and energy labeling compliance. Buyers seeking CE-marked outdoor installations face contracted vendor pools and elevated procurement costs, while uncertified alternatives trade at discounts that exclude them from municipal and airport tenders across Germany and France.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade indoor modules even as premium outdoor segments hold firm. Three-tier pricing structure across premium, standard, and economy levels separates CE/FCC dual-certified systems from single-market units and uncertified gray-market imports. Cost compression in standard indoor tiers intensifies because Shenzhen-based foundries expanded chip-on-board packaging lines. Grocery chains and fast-fashion outlets exhibit highest price sensitivity, while airport authorities and command-and-control centers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
India's PLI scheme incentives and BIS certification requirements are reshaping sourcing patterns by rewarding domestic module assembly with tariff advantages and government procurement preference. Taiwan and South Korea foundries control LED driver IC supply, while China dominates gallium nitride diode packaging and printed circuit board fabrication. Single-source vulnerability in driver semiconductor allocation exposes assemblers to foundry allocation volatility. Distribution runs through system integrators with project execution capabilities and direct OEM relationships for large-format transportation and retail deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global LED Digital Signage Market represents a late-cycle quality story as transportation and corporate buyers shift procurement criteria toward sub-0.9 mm pixel pitch specifications and bundled hardware-software-service uptime guarantees.
For Market Incumbents: Hedge against margin erosion in commoditized outdoor modules by deepening backward integration into gallium nitride packaging and captive semiconductor capabilities. Samsung Electronics and LG Electronics demonstrate how semiconductor-captive positioning sustains cost advantages in fine-pitch indoor segments. Prioritize certification investment in EU Green Deal compliance and FCC Part 15 emissions pathways to maintain eligibility for premium municipal and airport tenders. For New Entrants and Emerging Players: Chip-on-board thermal management innovations offer entry into corporate lobby and broadcast studio segments where 24/7 reliability specifications favor new technical approaches. India's smart city infrastructure and municipal digital wayfinding programs present the most penetrable geography, with BIS certification requirements creating defensible positioning against unqualified imports. Pursue hardware-software bundle partnerships with domestic system integrators in Maharashtra and Gujarat industrial corridors. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale module assemblers facing driver IC supply volatility because consolidation creates procurement leverage and shared certification cost pools. Target vertically specialized display manufacturers with concentrated strength in high-resolution outdoor transportation infrastructure and established MIIT or BIS certification tracks. Monitor divergence between regional efficiency benchmarks as the inflection indicator for which certification pathways will dominate procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Chip-on-Board Packaging Scale-Up | Eliminates wire bonds and reduces failure points for 24/7 corporate installations. |
| Dual Certification Investment (CE/FCC) | Unlocks airport and municipal tenders across Germany and United States. |
| Content Management Platform Integration | Captures recurring revenue from sports and entertainment venue operators. |
| Domestic Assembly Partnership (India) | Secures PLI scheme benefits and government procurement preference. |
| Transparent Display Architecture Development | Addresses luxury retail demand in Singapore and Dubai shopping corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with LED module procurement managers at airport authorities and retail chain headquarters, semiconductor sourcing leads at display manufacturers, and software platform engineers at content management vendors. Secondary validation drew from MIIT certification registries, FCC Part 15 equipment authorization databases, EU Ecodesign and energy labeling directives, and customs trade data for gallium nitride diode and driver IC shipments. Bottom-up module shipment estimates and top-down display systems revenue analysis were triangulated against foundry capacity disclosures.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeled by product type (outdoor, transparent, indoor, video wall), application (transportation, retail, corporate, entertainment), and technology (LCD, MicroLED, OLED, projection). CAGRs were derived from fitted growth curves applied to certified module deployment data and software subscription attach rates. Forecast inputs incorporated EU Green Deal implementation timelines, India PLI scheme capacity buildout schedules, and gallium nitride packaging yield improvement curves.
The model holds under stable regulatory enforcement and continuous semiconductor supply; deviation in foundry allocation crises or abrupt tariff regime shifts would shift replacement cycle timing and regional procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Automotive LCD Display Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Collaboration Display Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
4K VR Displays Market
Display Technologies
AMOLED Display Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Wireless Display Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
QLED Display Market
Display Technologies
Visual Computing Market