
 TFT LCD Panel Market | 2026-2036
TFT LCD Panel Market Size, Share, and Industry Trends Forecast 2026-2036
TFT LCD Panel Market Intelligence
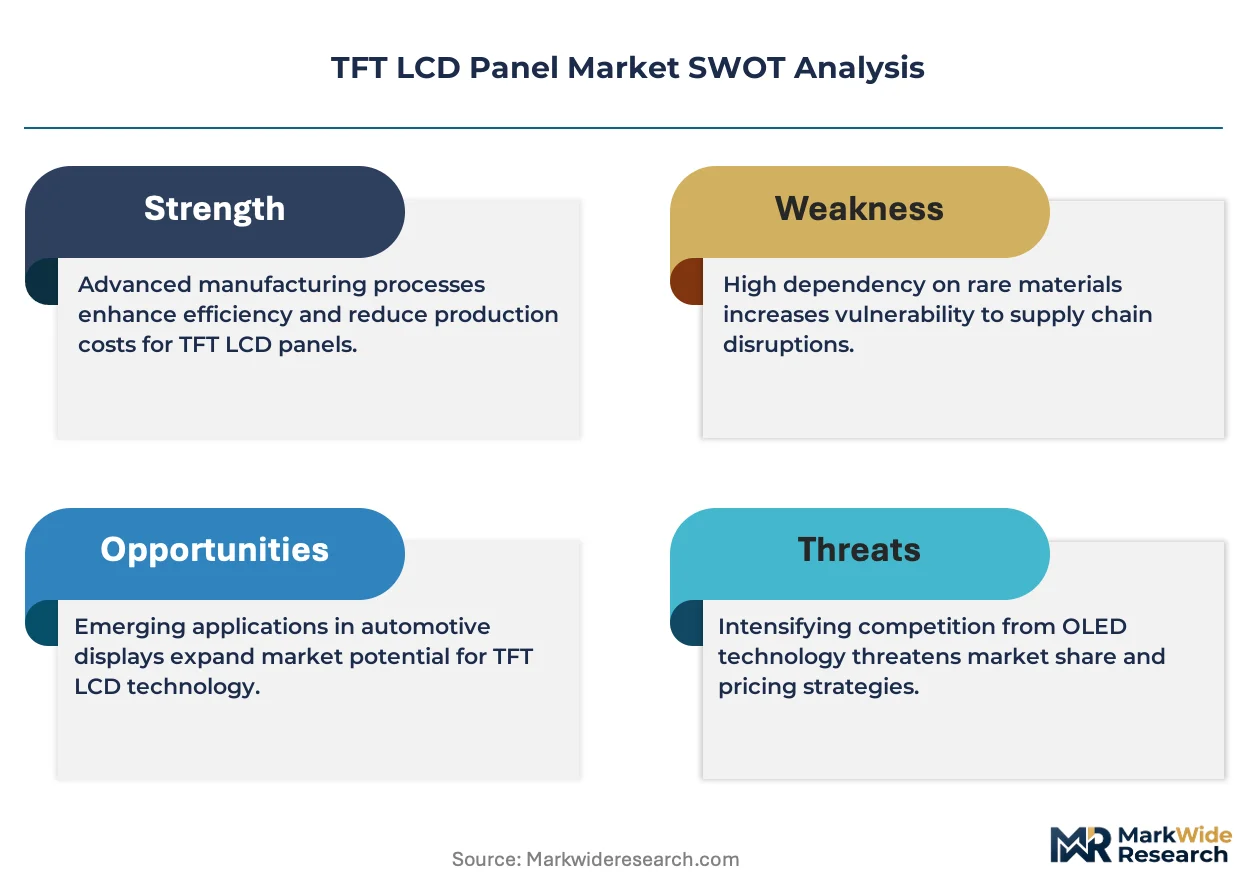
ISO 13406-2 certification for pixel defect tolerance is reorganizing supplier eligibility across automotive and medical display contracts. BOE Technology leverages its Gen 10.5 fab scale to dominate large-format television panel output. LG Display anchors premium IPS supply through captive OLED-TFT hybrid R&D lines in South Korea. Tianma Microelectronics specializes in high-brightness automotive-grade panels for tier-one cockpit integrators.
A thin-film transistor liquid crystal display sandwiches nematic liquid crystals between glass substrates with indium tin oxide electrodes, modulating light transmission via active-matrix addressing at refresh rates exceeding 120 Hz for motion-critical applications. Full HD panels still occupy the highest shipment volumes across emerging-market television replacement cycles, while 4K UHD panels generate disproportionate margin pools in professional monitor and high-end smartphone segments. Automotive display applications represent the fastest-growing demand vector as dashboard digitization and head-up display penetration deepen across vehicle tiers.
China's MIIT enforces GB 21520 standards for display energy efficiency, compressing margins for non-compliant legacy fabs while advantaging Gen 8.6 and larger production lines. South Korea's MFDS and Japan's METI coordinate chemical substance controls on indium gallium zinc oxide precursors, tightening feedstock access for second-tier panel makers. Stakeholders must monitor how regional carbon-border adjustments and rare-earth processing concentration reshape total cost of ownership across alternative backplane technologies.
Market Dynamics
Automotive cockpit digitization is compressing display refresh cycles from seven-year vehicle platforms to three-year electronics refresh timelines, forcing panel makers to synchronize roadmaps with tier-one integrators rather than consumer electronics brands.
Growth Catalysts
- GB 21520 energy efficiency mandates:China's MIIT standards are retiring legacy Gen 6 fabs and accelerating migration to Gen 8.6+ lines that consume 40% less power per substrate area.
- Head-up display penetration:Automotive HUD integration requires high-brightness, wide-temperature panels that command premium positioning in tier-one cockpit supply chains.
- Indium gallium zinc oxide feedstock:IGZO backplane chemistry enables lower power consumption and higher electron mobility for 4K UHD medical imaging displays.
Market Restraints
- Rare-earth processing concentration:Indium refining capacity clusters in Chinese smelters, exposing non-Chinese panel makers to supply interruption risks and price volatility.
- Gen 10.5 capex barriers:Single-fab investments exceed $4 billion, freezing second-tier manufacturers out of large-format television panel economics.
- OLED substitution in smartphones:Flexible organic emitters are capturing flagship handset sockets that previously anchored high-margin TFT LCD volumes.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production are creating localized demand for dashboard and infotainment displays without established domestic panel supply.
- ISO 13406-2 medical certification:Pixel defect tolerance standards for diagnostic imaging are raising barriers and margin pools for qualified suppliers in radiology and surgical navigation.
- Dual carbon compliance services:Chinese manufacturers can monetize carbon accounting and renewable energy documentation as value-added offerings to European automotive OEMs facing CSRD disclosure requirements.
Industry Challenges
- AMOLED-TFT hybrid process integration:Combining oxide backplanes with organic emitters requires cleanroom reconfiguration and cross-trained engineering talent scarce in legacy LCD hubs.
- Automotive qualification timelines:AEC-Q100 stress testing and OEM-specific validation protocols extend new product introduction cycles to 24-36 months, misaligning with consumer electronics speed expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TFT LCD Panel Market |
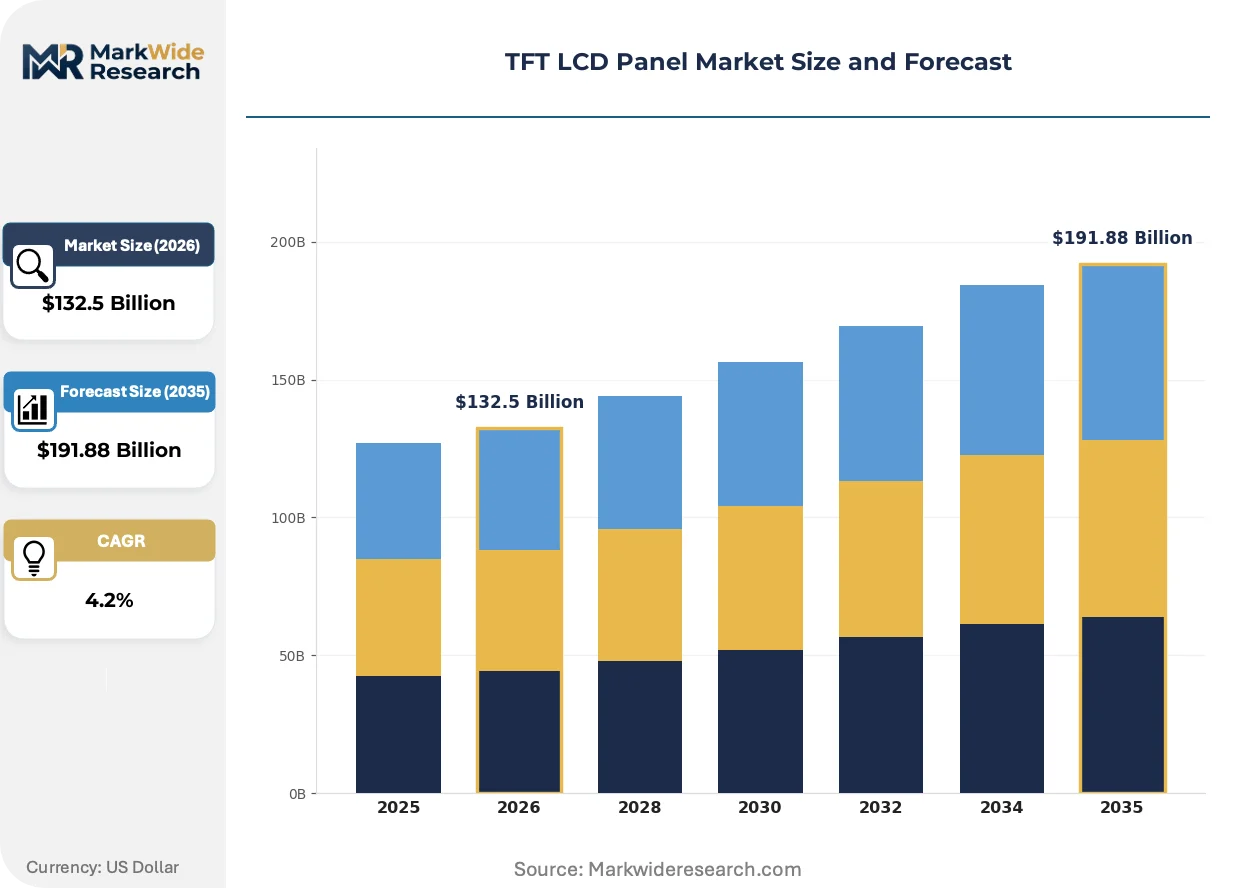
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $191.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full HD, 4K UHD, WQXGA, Retina Application: Smartphone Displays, Television Screens, Computer Monitors, Automotive Displays Technology: IPS, TN, VA, OLED End User: Consumers, Enterprises, Automotive Manufacturers, Electronics Manufacturers |
| Companies Covered | TCL China Star Optoelectronics Technology, Sharp Corporation, BOE Technology, Tianma Microelectronics Co., Ltd., Japan Display Inc., LG Display, AU Optronics Corp., Caihong Display Devices Co., Ltd., Innolux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TFT LCD Panel Market Strategic Shifts & Innovations
Panel architecture is bifurcating between cost-optimized a-Si lines for commodity television and precision IGZO investments for automotive and medical applications where defect tolerance and thermal stability command structural premiums.
Low-temperature polysilicon backplanes are supplanting amorphous silicon in automotive cluster displays where electron mobility determines pixel density for curved instrument panels. Tier-one cockpit integrators in Germany and Japan are specifying LTPS for 2026 vehicle platforms. This migration is compressing a-Si margin pools to emerging-market television replacement cycles exclusively.
China's MIIT enforcement of GB standards for display energy efficiency is disqualifying legacy fabs from government procurement and state-owned enterprise supply chains. Non-compliant manufacturers face exclusion from tenders for digital signage and educational equipment. South Korean and Japanese exporters are accelerating Gen 8.6+ line investments to maintain access to Chinese state-affiliated demand.
Fleet operators and commercial vehicle manufacturers are consolidating display procurement through long-term supply agreements rather than spot-market purchasing. This concentration favors panel makers with captive automotive certification and AEC-Q100 track records. The shift is most visible in North American heavy-truck manufacturing where vertical integration between OEMs and tier-one integrators is tightening supplier rosters.
TFT LCD Panel Market Segmentation
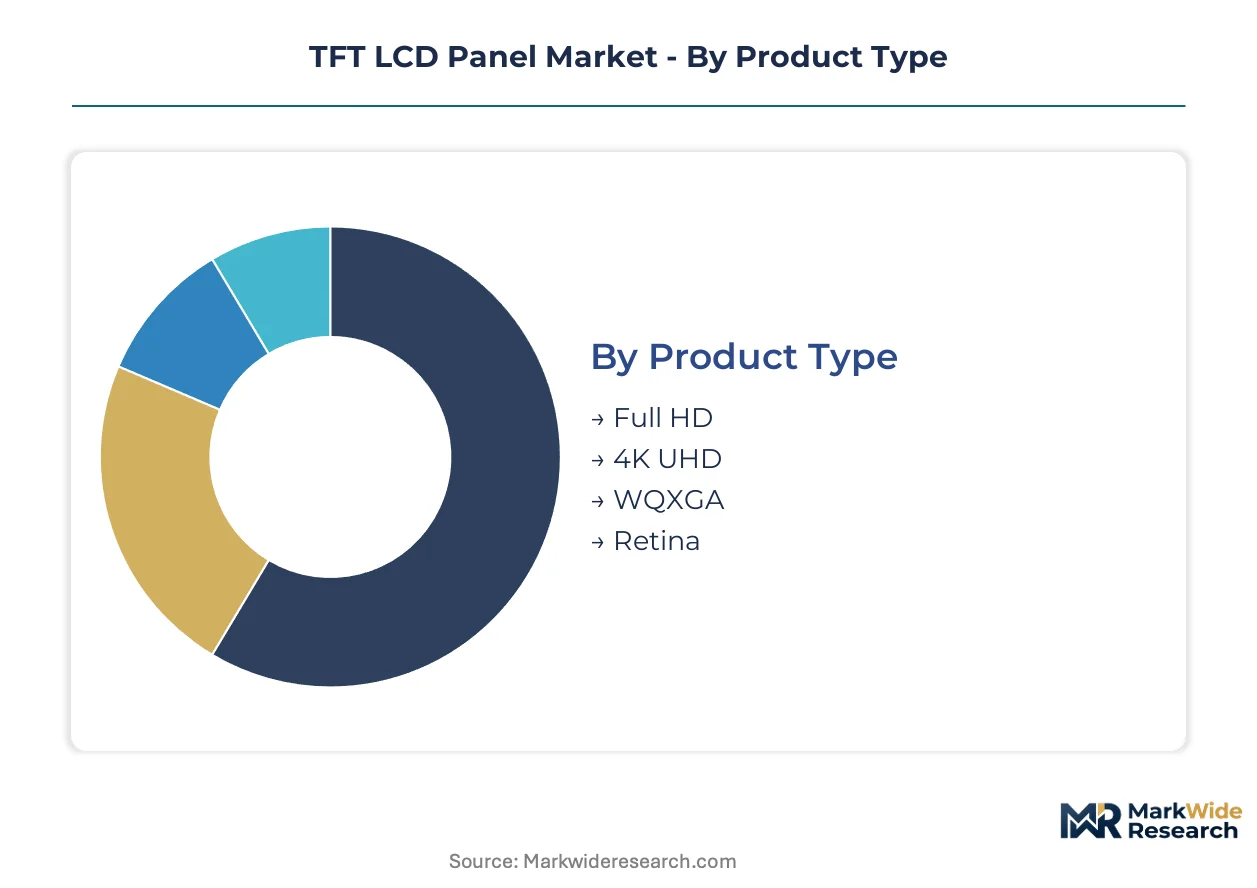
TFT LCD panel procurement diverges sharply across certification tiers and thermal specifications. Automotive and medical contracts enforce ISO 13406-2 pixel defect tolerance, while consumer electronics prioritize cost-optimized a-Si backplanes at scale.
Product Type:
MIIT's GB 21520 energy efficiency standards disqualify legacy resolution formats from Chinese state procurement channels, advantaging compliant high-density panels.
- Full HD:1920×1080 resolution panels utilize mature a-Si backplanes with 60-120 Hz refresh rates. Emerging-market television replacement cycles in India and Brazil concentrate demand here, constrained by Gen 6 fab obsolescence under tightening efficiency mandates.
- 4K UHD:3840×2160 resolution demands IGZO or LTPS backplanes for pixel density. Professional monitor deployments and high-end smartphone segments drive procurement, with premium positioning sustained by medical imaging and broadcast color calibration requirements.
- WQXGA:2560×1600 resolution serves laptop and tablet form factors requiring 16:10 aspect ratios. Enterprise workstation refresh cycles sustain volume.
- Retina:Pixel density exceeding 300 PPI at typical viewing distances. Mobile device integration dominates, with supply concentrated in South Korean and Chinese captive lines.
Full HD handles the majority of throughput; 4K UHD is the fastest mover on share.
Application:
End-use specifications fragment procurement requirements across thermal cycling, brightness thresholds, and qualification timelines.
- Smartphone Displays:Flexible OLED emitters are displacing TFT LCD in flagship sockets, compressing high-margin volume to mid-tier handsets where LTPS backplanes compete on cost.
- Television Screens:Gen 10.5 fab scale dominates 65-inch and larger formats, with BOE Technology and CSOT capturing volume through Chinese domestic demand and export substitution.
- Computer Monitors:Gaming-oriented 144-240 Hz refresh specifications drive IGZO adoption for motion clarity. Professional color-critical workflows sustain premium IPS volumes.
- Automotive Displays:Dashboard digitization and head-up display integration require wide-temperature operation (-40°C to 85°C) and 1000+ nit brightness. AEC-Q100 qualification extends supplier development cycles to 24-36 months, concentrating share among certified tier-one integrators.
Television Screens anchor volume scale; Automotive Displays are expanding most quickly on qualification-driven contract value.
Technology:
Backplane chemistry determines electron mobility, power consumption, and manufacturing capital intensity across application tiers.
- IPS:In-plane switching aligns liquid crystals horizontally for 178-degree viewing angles. LG Display anchors premium supply through South Korean R&D lines, with automotive cluster adoption accelerating for curved instrument panels.
- TN:Twisted nematic cells offer fastest response times at lowest cost. Competitive gaming monitors and budget television segments sustain demand despite narrow viewing angles.
- VA:Vertical alignment delivers 3000:1 native contrast for home theater positioning. Samsung Display and AU Optronics concentrate supply.
- OLED:Organic emitters eliminate backlight assembly for sub-3mm thickness. Flexible form factors capture flagship smartphone and emerging foldable tablet applications, though TFT LCD retains cost advantage at scale.
IPS commands the highest unit margins; Automotive qualification is pushing LTPS-IPS hybrids fastest on share gain.
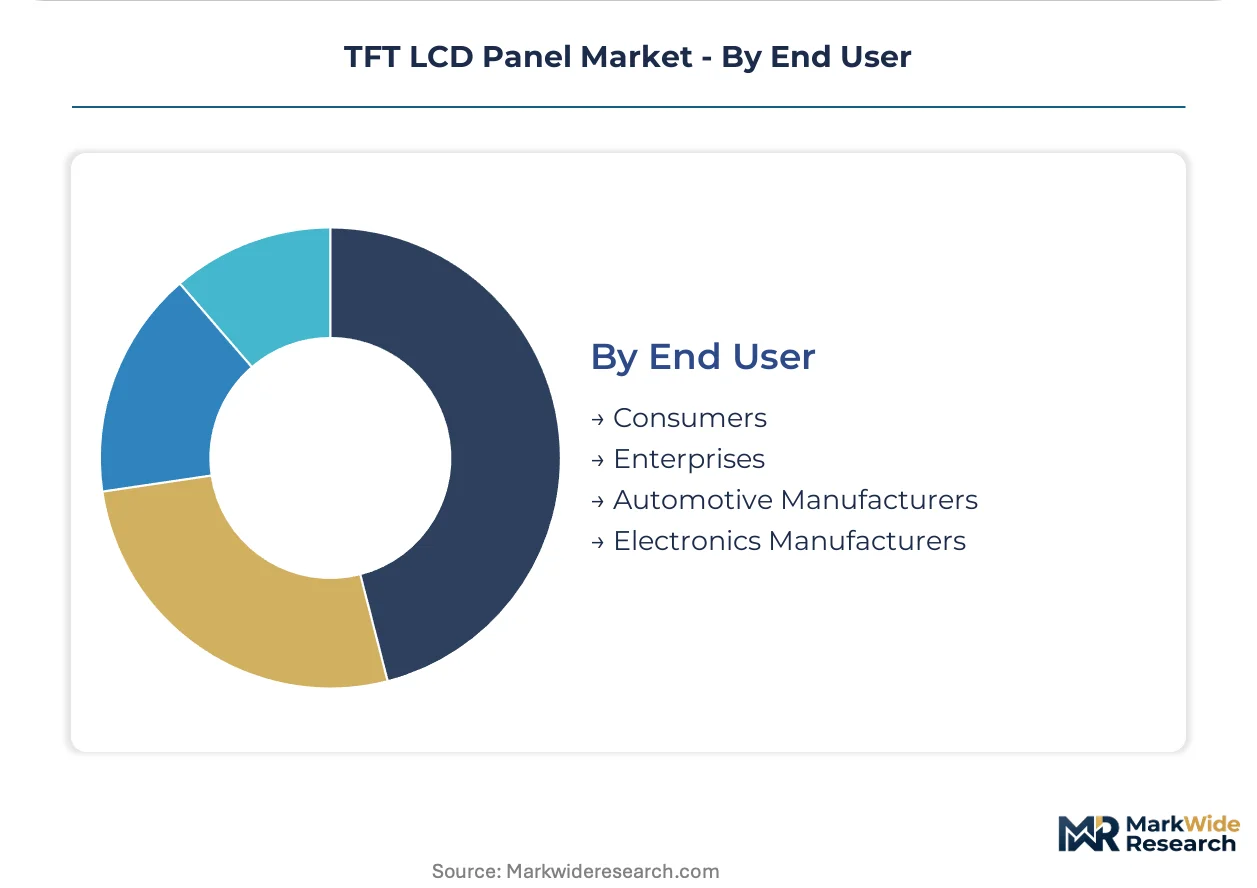
End User:
Procurement concentration and contract structure vary dramatically across buyer sophistication and vertical integration depth.
- Consumers:Retail channel purchasing drives price elasticity and seasonal demand spikes. Replacement cycle extension in mature markets compresses volume growth.
- Enterprises:Fleet refresh programs and digital signage deployments favor long-term supply agreements. EPEAT and TCO certification requirements filter supplier pools.
- Automotive Manufacturers:Vertical integration between OEMs and tier-one cockpit integrators tightens supplier rosters. North American heavy-truck and German premium passenger vehicle segments concentrate procurement through Denso, Continental, and Bosch.
- Electronics Manufacturers:ODM assembly for consumer brands demands flexible volume commitments and rapid specification pivots. Foxconn and Pegatron procurement teams negotiate quarterly price adjustments.
Electronics Manufacturers drive the highest absolute volume; Automotive Manufacturers are climbing the fastest on contract duration and qualification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams and tier-one cockpit integrators concentrate demand in manufacturing clusters where panel certification and backplane chemistry capabilities overlap. China's MIIT standards and South Korea's MFDS chemical controls reshape supplier eligibility across East Asian production hubs.
China
Domestic electric vehicle manufacturers and state-owned digital signage deployers drive panel procurement at scale. MIIT enforces GB 21520 energy efficiency standards that disqualify legacy Gen 6 fabs from government tenders. BOE Technology anchors large-format television output from Beijing and Hefei manufacturing complexes.
South Korea
Premium passenger vehicle OEMs and medical imaging equipment manufacturers source high-brightness, wide-temperature panels. MFDS coordinates with Japan's METI on indium gallium zinc oxide precursor controls that tighten feedstock access. LG Display operates captive R&D lines in Paju and Gumi for IPS and OLED-TFT hybrid development.
Japan
Automotive tier-one integrators and broadcast color-critical monitor manufacturers sustain demand for precision backplane technologies. METI chemical substance regulations on rare-earth processing concentrate indium refining oversight. Japan Display Inc. maintains engineering capabilities in Mobara and Ishikawa for automotive qualification protocols.
United States
North American heavy-truck fleet operators and defense cockpit integrators consolidate procurement through long-term supply agreements. NHTSA safety standards and Buy American provisions filter supplier eligibility for federal vehicle contracts. Texas and Michigan host tier-one integration facilities for dashboard digitization programs.
India
Electric vehicle PLI scheme beneficiaries and commercial vehicle manufacturers generate localized demand without established domestic panel supply. BIS certification requirements and DGFT import duties shape landed cost structures for display modules. Tamil Nadu and Gujarat automotive corridors attract tier-one cockpit integrator investments.
TFT LCD Panel Market Key Industry Players
Player mix skews toward diversified Asian electronics conglomerates with captive display divisions and specialized automotive-grade panel fabricators. Market structure consolidates around Gen 10.5 scale leaders and certified automotive suppliers, with second-tier manufacturers frozen out by capital barriers. Strategic archetypes include scale-driven television panel producers, premium IPS specialists, and high-brightness automotive-grade fabricators. Dominant competitive moves encompass backward integration into oxide backplane chemistry and geographic expansion into Indian automotive manufacturing corridors.
Within the diversified conglomerate tier, TCL China Star Optoelectronics Technology and BOE Technology represent scale-driven positions anchored in Chinese domestic demand and export substitution. Tianma Microelectronics Co., Ltd. exemplifies the automotive-specialist archetype with qualification track records for tier-one cockpit integrators. These three entities occupy positions that reflect the market's bifurcation between commodity television economics and premium automotive certification premiums.
| Leading Market Players |
|---|
| TCL China Star Optoelectronics Technology |
| Sharp Corporation |
| BOE Technology |
| Tianma Microelectronics Co., Ltd. |
| Japan Display Inc. |
| LG Display |
| AU Optronics Corp. |
| Caihong Display Devices Co., Ltd. |
| Innolux Corporation |
| Others |
Cost & Logistics Intelligence
Gen 10.5 fab scale economies concentrate pricing power among three Chinese and South Korean producers, compressing margin floors for second-tier manufacturers while elevating cost-plus contract premiums for automotive-certified supply. This concentration forces procurement teams at tier-one cockpit integrators to accept multi-year offtake agreements indexed to indium and glass substrate costs.
Pricing Analysis
Long-term supply agreements with quarterly price indexation to rare-earth oxide benchmarks dominate automotive and medical procurement, while spot-market spot purchasing persists in consumer television segments. Price differentiation hinges on AEC-Q100 automotive qualification status and ISO 13406-2 medical certification tiers, with certified panels commanding structural premiums over commodity a-Si output. Cost compression in Full HD television panels is intensifying as BOE Technology and CSOT ramp Gen 10.5 utilization, eroding margins for legacy Gen 6 operators. Electronics manufacturers exhibit highest price sensitivity through quarterly volume negotiations, whereas German premium automotive OEMs prioritize qualification track records over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among South Korean and Japanese panel makers serving tier-one automotive integrators, while Chinese producers maintain strategic stockpiles of indium ingots and polarizer films against feedstock volatility. Supply concentrates in China, South Korea, and Japan, with indium refining capacity clustering in Chinese smelters and glass substrate production anchored in Japanese and South Korean chemical complexes. Raw material dependencies center on indium tin oxide targets, liquid crystal blends, and polarizer films sourced from specialized chemical suppliers. Single-source vulnerability in indium gallium zinc oxide precursor supply exposes non-Chinese panel makers to export control risks. Distribution runs through captive tier-one integrator channels for automotive applications and spot-market brokers for commodity television panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among North American heavy-truck fleet operators and German premium passenger vehicle OEMs is shifting procurement leverage toward buyers, forcing panel makers to accept longer qualification timelines and price indexation clauses.
For Market Incumbents: Fortify automotive certification moats by deepening AEC-Q100 track records with Denso, Continental, and Bosch while accelerating backward integration into IGZO backplane chemistry. OLED substitution in flagship smartphones threatens high-margin LTPS volumes, demanding defensive capacity reallocation toward medical imaging and head-up display applications. Captive oxide precursor synthesis in South Korean or Japanese facilities reduces indium supply interruption exposure. For New Entrants and Emerging Players: Lead with localized automotive panel supply to Indian electric vehicle manufacturers under PLI scheme incentives, where domestic production gaps create procurement urgency without established incumbent relationships. Tamil Nadu and Gujarat automotive corridors offer penetrable entry points through BIS certification pathways shorter than AEC-Q100 timelines. Partner with tier-two cockpit integrators serving commercial vehicle segments to build qualification history before targeting premium passenger platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-certified panel fabricators with captive IGZO or LTPS capabilities over commodity a-Si television producers facing Gen 10.5 scale barriers. Long-term viability rests on qualification-driven contract structures extending through multiple vehicle platform cycles rather than spot-market television exposure. Watch indium gallium zinc oxide precursor export licensing patterns from Chinese regulators as inflection indicator for feedstock cost trajectories and competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Certification Investment | AEC-Q100 qualification with tier-one integrators unlocks multi-year supply agreements with German and North American OEMs. |
| Backward Integration into Oxide Chemistry | Captive IGZO precursor synthesis reduces dependency on Chinese indium refining concentration and price volatility. |
| Gen 8.6+ Line Migration | MIIT GB 21520 compliance secures access to Chinese state procurement and state-owned enterprise display tenders. |
| Indian Manufacturing Footprint | Localized production near Tamil Nadu automotive corridors captures PLI scheme demand without import duty exposure. |
| Medical Imaging Certification | ISO 13406-2 qualification for pixel defect tolerance opens radiology and surgical navigation margin pools. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade databases, MIIT energy efficiency disclosures, and vehicle production registries. Interviews with tier-one cockpit integrator procurement directors, panel maker R&D heads, automotive OEM platform engineers, and rare-earth chemical suppliers informed demand and supply assumptions. Secondary validation drew from AEC-Q100 qualification databases, GB standards compliance registries, and indium trade flow statistics. Bottom-up capacity utilization models and top-down end-use demand projections were cross-referenced for triangulation.
Segmentation dimensions modeled span resolution format, backplane chemistry, application vertical, and thermal specification tier across the projection horizon. Analytical frameworks incorporated automotive platform refresh cycles, television replacement patterns, and medical equipment procurement timelines. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trajectories by certification tier. Forecast inputs included MIIT enforcement schedules for GB 21520 standards and MFDS-METI coordination patterns on chemical substance controls.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification, stable rare-earth processing access, and continued GB standards enforcement would require recalibration. Forecasts reflect assumptions on indium supply continuity, tier-one integrator consolidation patterns, and OLED substitution rates in smartphone segments. Revision becomes warranted when Chinese export licensing for indium gallium zinc oxide precursors crosses restrictive thresholds or when Indian PLI scheme disbursement delays alter localized demand timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electroluminescent Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Multi-Function Display Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Computer Monitor Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Industrial Display Market
Display Technologies
QLED Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Global Projector Market